
 China Topical Oxygen Therapy Market | 2026-2036
China Topical Oxygen Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
China Topical Oxygen Therapy Market Insights
The China topical oxygen therapy landscape is shifting between premium electrolytic systems and commodity mechanical alternatives. Yantai Hongyuan Oxygen Industry Group leverages its domestic manufacturing base to anchor the mechanical systems tier. AOTI Inc. differentiates through specialized portable devices for outpatient wound clinics. Sechrist Industries competes on technology leadership in precision oxygen delivery controls.
Topical oxygen therapy delivers concentrated oxygen directly to wound surfaces via sealed chambers or semi-permeable dressings, typically operating at pressures between 1.0 and 1.5 ATA to accelerate angiogenesis and collagen synthesis in hypoxic tissue. Portable devices command the fastest expansion as home care protocols extend beyond hospital settings, while stationary systems retain the dominant installed base in rehabilitation centers where longer treatment cycles justify capital investment. Wound healing applications generate the deepest margin pools due to reimbursement alignment with chronic care pathways, whereas cosmetic procedures represent an emerging segment with premium pricing flexibility.
NMPA medical device regulations and GB standards for oxygen equipment shape product certification requirements and clinical trial obligations for market entry. China's dual carbon goals are forcing manufacturers to redesign concentrator energy profiles and reduce power consumption in electrolytic device architectures. Stakeholders must monitor how provincial procurement consortia consolidate purchasing power across tier-one hospital networks.
Market Dynamics
NMPA medical device classification reforms are compressing approval timelines for Class II oxygen therapy equipment while Shanghai and Beijing tertiary hospital networks accelerate wound care center upgrades. This regulatory streamlining collides with provincial procurement consolidation to reshape competitive access.
Growth Catalysts
- Chronic wound protocol expansion:Hospital networks in Shanghai and Beijing are embedding topical oxygen systems into standardized diabetic foot and pressure ulcer treatment pathways, creating institutional pull for both portable and stationary equipment.
- Dual carbon goals:China's national decarbonization mandates are forcing electrolytic device manufacturers to redesign energy profiles, opening competitive differentiation through power-efficient architectures.
- Home care protocol extension:Outpatient wound clinics in tier-two cities are adopting portable devices for post-discharge patient management, extending treatment continuity beyond hospital walls.
Market Restraints
- GB standards compliance burden:Oxygen equipment certification requires extensive clinical trial documentation under GB 9706 medical electrical safety standards, stretching smaller manufacturers across 18-24 month approval cycles.
- Electrolytic cell supply concentration:Domestic sourcing of high-purity proton exchange membranes remains concentrated among three specialized chemical suppliers, exposing device makers to input bottlenecks.
- Mechanical system substitution:Commodity oxygen concentrators using pressure swing adsorption offer lower capital outlay for budget-constrained county hospitals, pressuring premium electrolytic positioning.
Strategic Opportunities
- Central China penetration gap:Henan and Hubei provinces show wound care infrastructure deficits relative to coastal benchmarks, presenting first-mover advantage for equipment vendors establishing provincial distribution partnerships.
- Cosmetic procedure adjacency:Aesthetic clinics in Chengdu and Hangzhou are piloting topical oxygen for post-laser recovery protocols, opening premium pricing segments outside reimbursement-constrained wound care.
- MIIT smart medical device incentives:The Ministry of Industry and Information Technology's connected health equipment subsidies favor IoT-enabled oxygen delivery systems with remote monitoring capabilities.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining oxygen system design with wound care clinical protocols remains concentrated in Beijing and Shanghai, constraining R&D scaling for regional manufacturers.
- Legacy hospital IT integration:Stationary systems must interface with heterogeneous electronic health record platforms across provincial hospital networks, complicating deployment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Topical Oxygen Therapy Market |
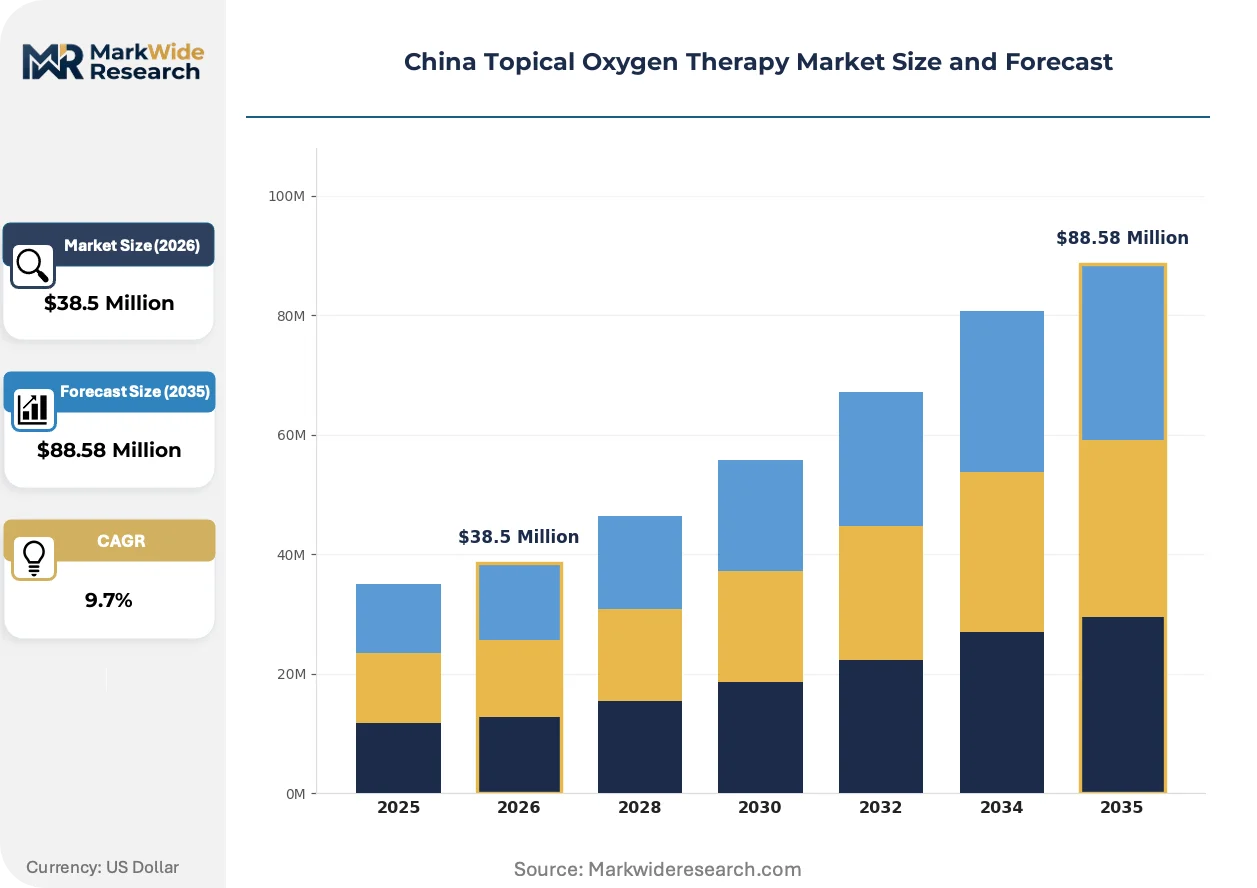
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $88.58 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Stationary Systems, Consumables, Accessories End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Wound Healing, Cosmetic Procedures, Pain Management, Scar Treatment Technology: Electrolytic Devices, Mechanical Systems, Oxygen Concentrators, Others |
| Companies Covered | Yantai Hongyuan Oxygen Industry Group, IHC Hytech, Nanning Xinzizhu Trading, AOTI Inc., Pommec Hytech, Sechrist Industries, Environmental Tectonics, Haux-Life-Support, Perry Baromedical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Topical Oxygen Therapy Market Trends and Innovations
Electrolytic oxygen generation architectures are displacing mechanical alternatives as the dominant technical platform, while regulatory data requirements and procurement centralization reshape how equipment reaches end-users. Three forces are compressing the competitive landscape.
Membrane-based electrolytic oxygen generation is consolidating market preference over pressure swing adsorption systems in premium installations. Tertiary hospital wound care centers in Beijing and Shanghai are adopting these platforms for precision flow control. The technology is consolidating supplier margins by embedding proprietary membrane chemistries into long-term consumable revenue streams.
NMPA's 2023 medical device classification adjustment for Class II oxygen therapy equipment is compressing clinical trial obligations for sealed-chamber topical systems. Domestic manufacturers now face reduced documentation burdens for 510(k)-equivalent pathways. Stationary rehabilitation center equipment is responding fastest, with provincial procurement consortia accelerating vendor qualification timelines.
Hospital group purchasing organizations are unbundling after-sales service contracts from capital equipment sales. Tier-one hospital networks in Guangdong and Jiangsu provinces are negotiating standalone technical service agreements with third-party maintenance providers. This behavior is most visible in Shanghai, where municipal health bureaus are mandating transparent lifecycle cost disclosure for oxygen therapy capital allocations.
China Topical Oxygen Therapy Market Segmentation
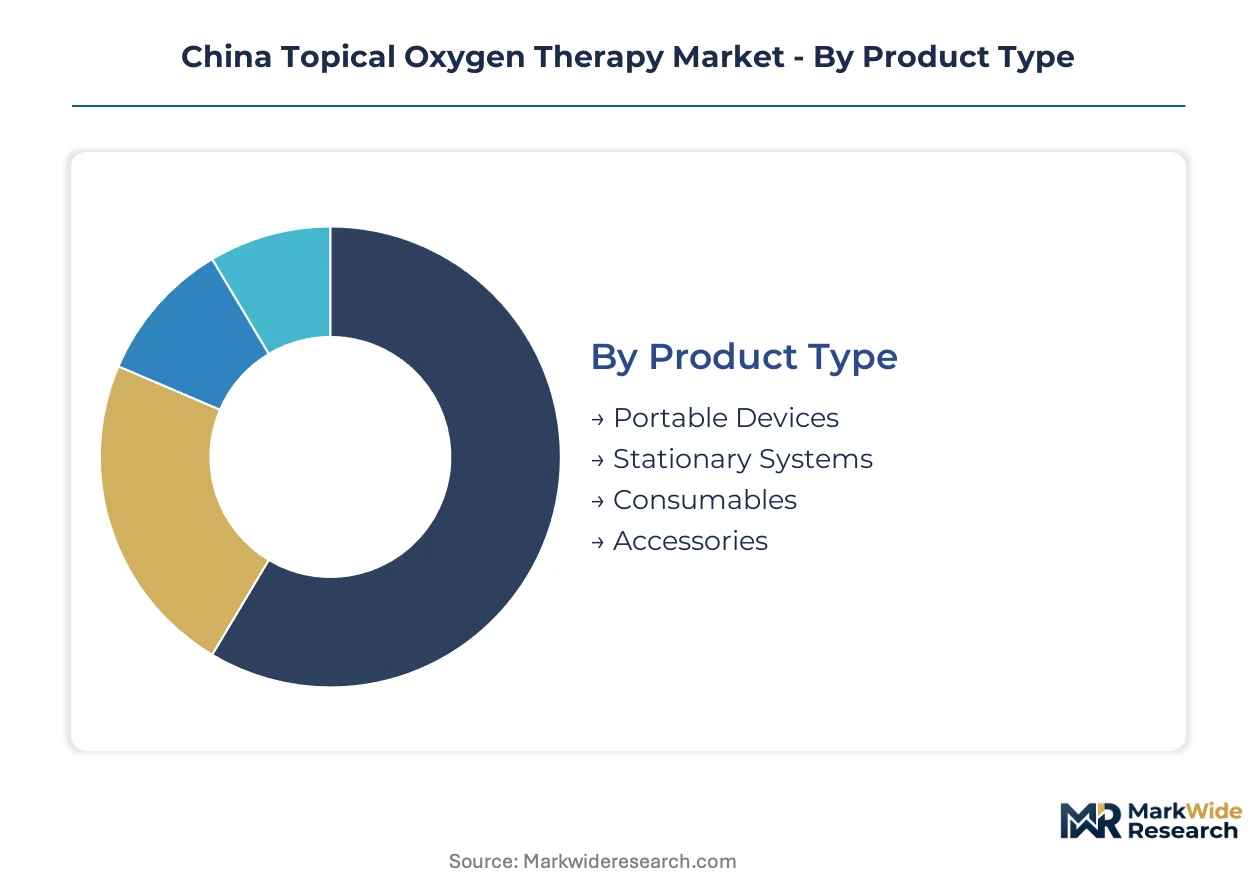
Segmentation reveals how procurement consolidation and clinical protocol standardization are reshaping equipment deployment across China's wound care infrastructure. Hospital network purchasing decisions increasingly favor technology platforms that align with tiered reimbursement pathways and energy efficiency mandates.
Product Type:
Replacement cycles diverge sharply between capital equipment and recurring consumables, with tertiary hospitals driving faster refresh rates for precision delivery platforms.
- Portable Devices:Battery-powered units with sealed-chamber designs enable outpatient wound clinic deployment. Shanghai and Beijing municipal health bureaus are mandating these for post-discharge diabetic foot protocols to reduce readmission rates.
- Stationary Systems:Fixed-installation platforms operating at 1.0-1.5 ATA pressure ranges dominate rehabilitation center footprints. Capital allocation constraints in county hospitals are compressing replacement timelines for legacy mechanical units.
- Consumables:Semi-permeable dressings and membrane cartridges generate recurring revenue streams through proprietary chemistries.
- Accessories:Tubing assemblies and pressure monitoring sensors complete system configurations.
Stationary systems sit at the top of the volume ranking, with portable devices climbing the fastest.
End User:
Procurement authority concentrates differently across facility types, with hospital group purchasing organizations wielding disproportionate pricing leverage.
- Hospitals:Tertiary wound care centers in Guangdong and Jiangsu provinces anchor electrolytic system adoption. NMPA Class II streamlined approvals are accelerating equipment qualification for standardized diabetic foot pathways.
- Clinics:Outpatient facilities in tier-two cities favor portable configurations for session-based revenue models.
- Home Care:Patient-managed protocols are extending treatment continuity beyond institutional walls. MIIT smart medical device subsidies favor connected oxygen delivery platforms with remote monitoring capabilities.
- Rehabilitation Centers:Long-stay facilities justify capital-intensive stationary installations through extended treatment cycles.
Hospitals command the dominant procurement volume, while home care segments are gaining share fastest on protocol extension.
Application:
Margin structures diverge between reimbursement-aligned clinical uses and premium-priced aesthetic procedures.
- Wound Healing:Chronic diabetic foot and pressure ulcer protocols generate the deepest margin pools through national reimbursement alignment. Henan and Hubei provinces show infrastructure deficits relative to coastal benchmarks, presenting first-mover opportunities.
- Cosmetic Procedures:Post-laser recovery applications in Chengdu and Hangzhou aesthetic clinics command premium pricing outside constrained wound care reimbursement.
- Pain Management:Adjunctive oxygen therapy for neuropathic conditions represents an emerging clinical use case.
- Scar Treatment:Keloid management protocols are piloting topical oxygen as adjunct to surgical intervention.
Wound healing dominates current deployment, with cosmetic procedures expanding most quickly on pricing flexibility.
Technology:
Platform selection reflects trade-offs between precision control and capital efficiency, with energy mandates reshaping competitive positioning.
- Electrolytic Devices:Proton exchange membrane architectures enable precise flow control and embed proprietary consumable revenue. Dual carbon goals are forcing manufacturers to redesign energy profiles for power-efficient operation.
- Mechanical Systems:Pressure swing adsorption concentrators offer lower capital outlay for budget-constrained county hospitals. Domestic manufacturing bases anchor commodity positioning.
- Oxygen Concentrators:Standalone PSA units serve as entry-level alternatives for basic wound care protocols.
- Others:Emerging hybrid architectures combine electrolytic generation with mechanical backup systems.
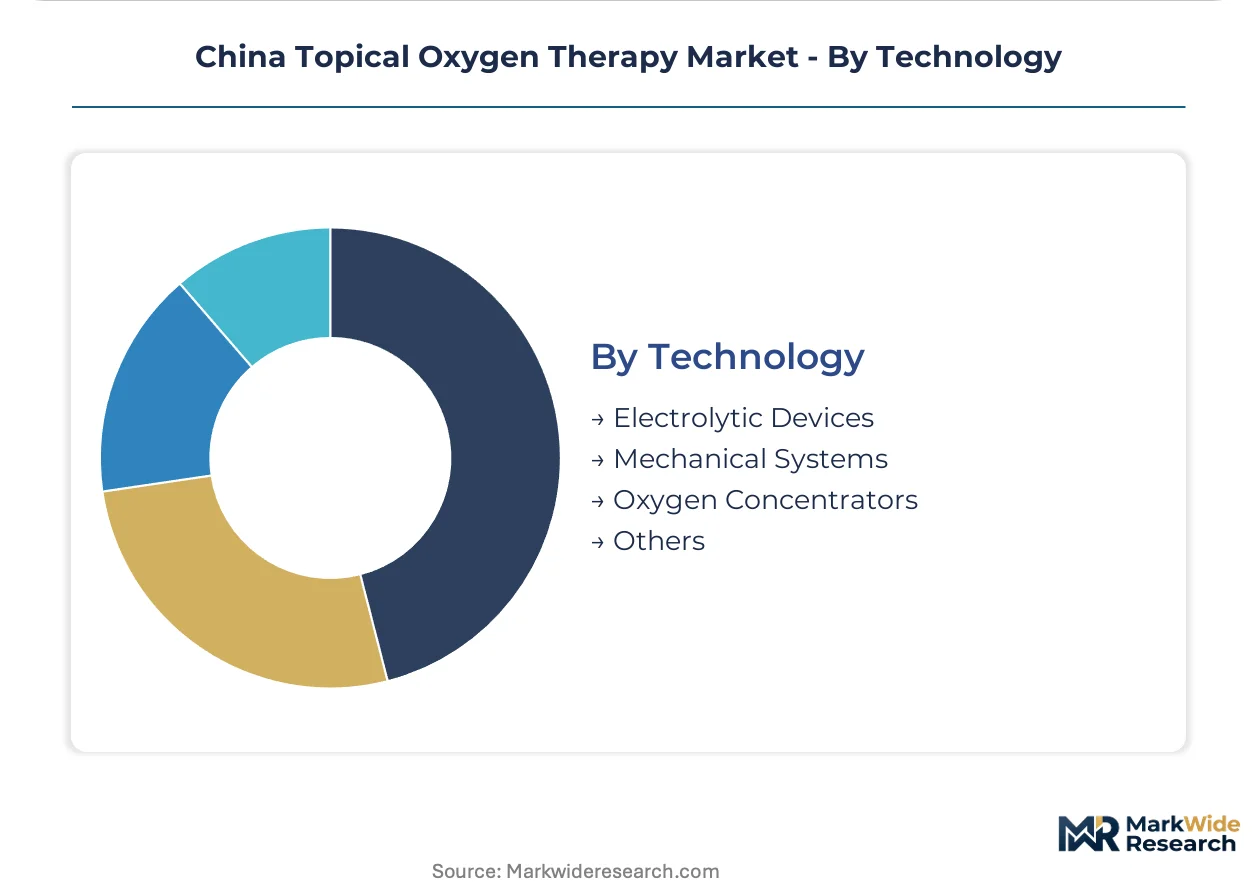
Mechanical systems retain installed base leadership, though electrolytic platforms are gaining share fastest on precision and efficiency differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's topical oxygen therapy infrastructure outpaces India's emerging wound care networks in absolute deployment scale, though both markets face similar regulatory compression timelines for medical device approvals.
Yangtze River Delta
Shanghai municipal health bureaus mandate portable topical oxygen devices for post-discharge diabetic foot protocols, reducing tertiary hospital readmission rates. NMPA Class II streamlined approvals accelerate equipment qualification for standardized treatment pathways. Jiangsu provincial procurement consortia negotiate transparent lifecycle cost disclosures for oxygen therapy capital allocations.
Pearl River Delta
Guangdong hospital group purchasing organizations unbundle after-sales service contracts from capital equipment sales, favoring third-party maintenance providers. MIIT smart medical device subsidies attract IoT-enabled oxygen delivery platforms with remote monitoring capabilities. Shenzhen and Guangzhou aesthetic clinics pilot post-laser recovery applications for premium pricing segments.
Beijing-Tianjin-Hebei
Beijing tertiary wound care centers anchor electrolytic system adoption for precision flow control in chronic wound protocols. Dual carbon goals force manufacturers to redesign energy profiles for power-efficient concentrator architectures. The capital's biomedical engineering talent concentration constrains R&D scaling for regional competitors lacking cross-functional expertise.
Sichuan-Chongqing
Chengdu aesthetic clinics expand topical oxygen deployment for cosmetic procedure adjacencies outside reimbursement-constrained wound care. GB 9706 medical electrical safety standards impose 18-24 month approval cycles on smaller manufacturers seeking oxygen equipment certification. Chongqing rehabilitation centers justify capital-intensive stationary installations through extended treatment cycles.
Central China
Henan and Hubei provinces exhibit wound care infrastructure deficits relative to coastal benchmarks, presenting first-mover distribution partnership opportunities. County hospitals in these regions favor commodity mechanical systems using pressure swing adsorption for lower capital outlay. Provincial health commissions are consolidating purchasing power across tier-two hospital networks.
China Topical Oxygen Therapy Market Competitive Landscape
Top-tier vendors anchor the electrolytic precision tier, while mechanical system specialists occupy commodity positioning for budget-constrained installations. The competitive structure fragments across three strategic archetypes: domestic manufacturing bases leveraging cost advantages, specialized portable device developers targeting outpatient protocols, and precision control technology leaders embedding proprietary consumable revenue streams. Dominant competitive moves include backward integration into membrane supply chains and geographic expansion through provincial distribution partnerships.
Within the domestic manufacturing tier, Yantai Hongyuan Oxygen Industry Group occupies a position exemplifying mechanical systems commoditization. Among specialized portable developers, AOTI Inc. represents the outpatient clinic vector. Sechrist Industries anchors the precision technology archetype for electrolytic platform differentiation. These three companies collectively illustrate how competitive positioning stratifies across capital efficiency, clinical mobility, and technical performance dimensions.
| Leading Market Players |
|---|
| Yantai Hongyuan Oxygen Industry Group |
| IHC Hytech |
| Nanning Xinzizhu Trading |
| AOTI Inc. |
| Pommec Hytech |
| Sechrist Industries |
| Environmental Tectonics |
| Haux-Life-Support |
| Perry Baromedical |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply access and premium-tier pricing power, forcing electrolytic device manufacturers to redesign energy profiles while provincial procurement consortia consolidate purchasing leverage across tier-one hospital networks. NMPA Class II streamlined approvals compress qualification timelines for power-efficient architectures, embedding proprietary membrane chemistries into long-term consumable revenue streams that sustain margin premiums.
Pricing Analysis
Capacity additions in Shandong and Jiangsu provinces are reshaping price floors for mechanical pressure swing adsorption systems, intensifying cost compression in the commodity tier. Three-tier pricing structure across premium electrolytic, standard hybrid, and economy mechanical levels stratifies by energy efficiency certification and remote monitoring capability. Price differentiation stems from GB 9706 compliance burden and MIIT smart device subsidy eligibility. County hospitals exhibit highest price sensitivity due to capital allocation constraints, while Beijing and Shanghai tertiary centers prioritize precision control over unit economics.
Supply Chain Analysis
Refurbishment flows for stationary rehabilitation systems concentrate in domestic facilities near Beijing and Shanghai, extending equipment lifecycle and compressing replacement demand. Proton exchange membrane supply draws from three specialized chemical suppliers concentrated in coastal provinces, creating single-source vulnerability for electrolytic device manufacturers. Distribution runs through provincial procurement consortia unbundling after-sales service contracts, with third-party maintenance providers capturing standalone technical service agreements. High-purity membrane cartridges and semi-permeable dressings represent critical consumable dependencies tethered to proprietary chemistries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in China's topical oxygen therapy market rests on power-efficient electrolytic architectures capturing premium positioning, while mechanical system commoditization concentrates volume in consolidated procurement channels. The cost-down driver is energy profile redesign aligning with dual carbon mandates, and the premium-tier shift is IoT-enabled remote monitoring qualifying for MIIT smart medical device subsidies.
For Market Incumbents: Deploy backward integration into proton exchange membrane supply chains to defend against input bottlenecks from the three concentrated coastal suppliers. Capture long-term consumable revenue by embedding proprietary chemistries into membrane cartridges, while consolidating provincial distribution partnerships in Henan and Hubei to preempt emerging mechanical system substitution threats from Yantai Hongyuan Oxygen Industry Group's domestic manufacturing base. For New Entrants and Emerging Players: Portable device connectivity with remote monitoring capabilities offers the clearest technology-first wedge, qualifying for MIIT subsidies while addressing Shanghai and Beijing municipal mandates for post-discharge diabetic foot protocols. Target Central China penetration gaps in Henan and Hubei provinces where wound care infrastructure deficits relative to coastal benchmarks present first-mover distribution partnership opportunities. Pursue session-based revenue models in tier-two outpatient clinics favoring battery-powered sealed-chamber configurations. For Investors and Strategic Acquirers: Roll-up economics work for specialized portable device developers because outpatient protocol extension is fragmenting procurement authority across municipal health bureaus and tier-two clinic networks. Platform consolidation captures MIIT subsidy flows and NMPA streamlined approval synergies. Long-term viability hinges on electrolytic precision tier dominance as dual carbon goals displace mechanical alternatives. Watch provincial procurement consortia consolidation velocity as the inflection signal for margin compression timing in commodity tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Supply | Captive proton exchange membrane production insulates electrolytic device makers from three-supplier concentration risk. |
| MIIT Smart Device Certification | IoT-enabled remote monitoring capabilities unlock subsidy flows and differentiate premium electrolytic positioning. |
| Provincial Distribution Partnerships | Henan and Hubei first-mover agreements capture infrastructure build-out ahead of procurement consolidation. |
| Consumable Revenue Stream Development | Proprietary membrane cartridge chemistries embed recurring revenue and sustain margin premiums. |
| Energy Profile Redesign | Power-efficient architectures align with dual carbon mandates and qualify for premium-tier hospital procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and provincial health commission procurement leads with secondary validation against NMPA device registration databases, hospital procurement records, and MIIT smart medical equipment subsidy disclosures. Bottom-up equipment deployment estimates triangulated against top-down addressable market sizing across portable, stationary, and consumable product categories.
Historical reference periods anchored volume and value trajectories across the projection horizon, with CAGRs derived from segmented growth rate reconciliation across product type, end user, application, and technology dimensions. Modeled inputs included NMPA approval timeline compression effects, provincial procurement consortium formation velocity, and electrolytic versus mechanical system substitution elasticity under dual carbon compliance pressure.
The model holds under continued NMPA Class II streamlining and MIIT subsidy continuity; deviation in GB standards enforcement intensity or proton exchange membrane supply disruption would shift equipment availability and pricing trajectories. Practitioners should monitor provincial procurement consortium mandate expansion and membrane supplier capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Respiratory Trainer Market