
 Global Bronchitis Treatment Market | 2026-2036
Global Bronchitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bronchitis Treatment Market Foresight
Combination therapy bundling of bronchodilators with corticosteroids in single-inhaler devices is realigning prescribing patterns across pulmonary clinics. AstraZeneca leverages its respiratory portfolio depth to sustain leadership in fixed-dose combination formats. GlaxoSmithKline anchors its position through backward integration into active pharmaceutical ingredient production for inhaled corticosteroids. Boehringer Ingelheim differentiates via specialized nebulization technology platforms that target severe chronic bronchitis segments.
Bronchitis treatment encompasses pharmaceutical and device-based interventions targeting acute and chronic airway inflammation, with bronchodilators functioning as beta-agonist or anticholinergic agents that relax smooth muscle to improve forced expiratory volume. Corticosteroids reduce eosinophilic and neutrophilic airway inflammation through glucocorticoid receptor agonism, forming the pharmacological backbone of maintenance therapy for chronic bronchitis patients with recurring exacerbations. Among therapy areas, chronic bronchitis commands the largest patient pool and corresponding revenue base, while acute bronchitis drives seasonal volume spikes in oral antibiotic and expectorant segments. The inhalation delivery mode captures premium positioning due to direct lung targeting and faster onset kinetics, though nebulization retains critical share in hospital and home care settings for patients with compromised inspiratory flow.
The FDA oversees inhaler bioequivalence standards and combination product approvals, while the EMA's MDR framework imposes stricter clinical evidence requirements for nebulizer devices marketed across European Union member states. China's NMPA has accelerated review timelines for locally manufactured generic bronchodilators under its priority审评 program, reshaping competitive access in Asia's largest respiratory therapy market. Stakeholders must monitor evolving pharmacovigilance mandates from WHO prequalification initiatives that could redefine export eligibility for emerging-market manufacturers.
Market Dynamics
Fixed-dose combination inhalers are compressing the chronic bronchitis maintenance segment by collapsing multi-device regimens into single-administration platforms, forcing incumbents to reconfigure R&D pipelines around bronchodilator-corticosteroid synergies rather than standalone molecules.
Growth Catalysts
- MDR Device Classification:The European Union's Medical Device Regulation imposes stricter clinical evidence requirements for nebulizer systems, accelerating consolidation toward manufacturers with robust notified body relationships and premium pricing power.
- Pulmonary Clinic Networks:Germany's statutory health insurance reimbursement framework for nebulized therapies creates predictable demand corridors, anchoring volume commitments for severe chronic bronchitis segments.
- Dual Carbon Goals:China's NMPA priority review program for locally manufactured generic bronchodilators is compressing approval timelines, reshaping competitive access in Asia's largest respiratory therapy market.
Market Restraints
- API Supply Concentration:Inhaled corticosteroid active pharmaceutical ingredient production clusters among a handful of European and Indian contract manufacturers, exposing formulation specialists to input volatility and qualification delays.
- Bioequivalence Burden:The FDA's inhaler bioequivalence standards require complex pharmacokinetic studies for generic entrants, extending development timelines and preserving originator pricing power in the United States.
- Oral Antibiotic Substitution:Acute bronchitis episodes increasingly resolve without pharmaceutical intervention, compressing seasonal demand for antibiotic and expectorant segments traditionally captured by retail pharmacy channels.
Strategic Opportunities
- Home Nebulization Infrastructure:Post-acute care discharge protocols in the United States are expanding reimbursement for durable medical equipment, opening channel access for specialized nebulization platforms targeting COPD-bronchitis comorbid patients.
- Digital Inhaler Convergence:Bluetooth-enabled dose counters paired with telemonitoring platforms are creating adherence data monetization opportunities for payers managing high-utilization chronic bronchitis populations.
- PLI Manufacturing Incentives:India's production-linked incentive scheme for pharmaceutical ingredients is attracting contract manufacturing investment, positioning domestic suppliers to serve emerging market bronchodilator demand.
Industry Challenges
- Inhaler Technique Training:Correct use of dry powder and metered-dose devices requires sustained patient education investment, with suboptimal technique driving real-world efficacy gaps and exacerbation-related hospitalizations.
- Combination Product Complexity:Bronchodilator-corticosteroid single-inhaler development demands synchronized formulation stability, device engineering, and regulatory submission coordination across FDA Center for Drug Evaluation and Research and Center for Devices and Radiological Health review tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bronchitis Treatment Market |
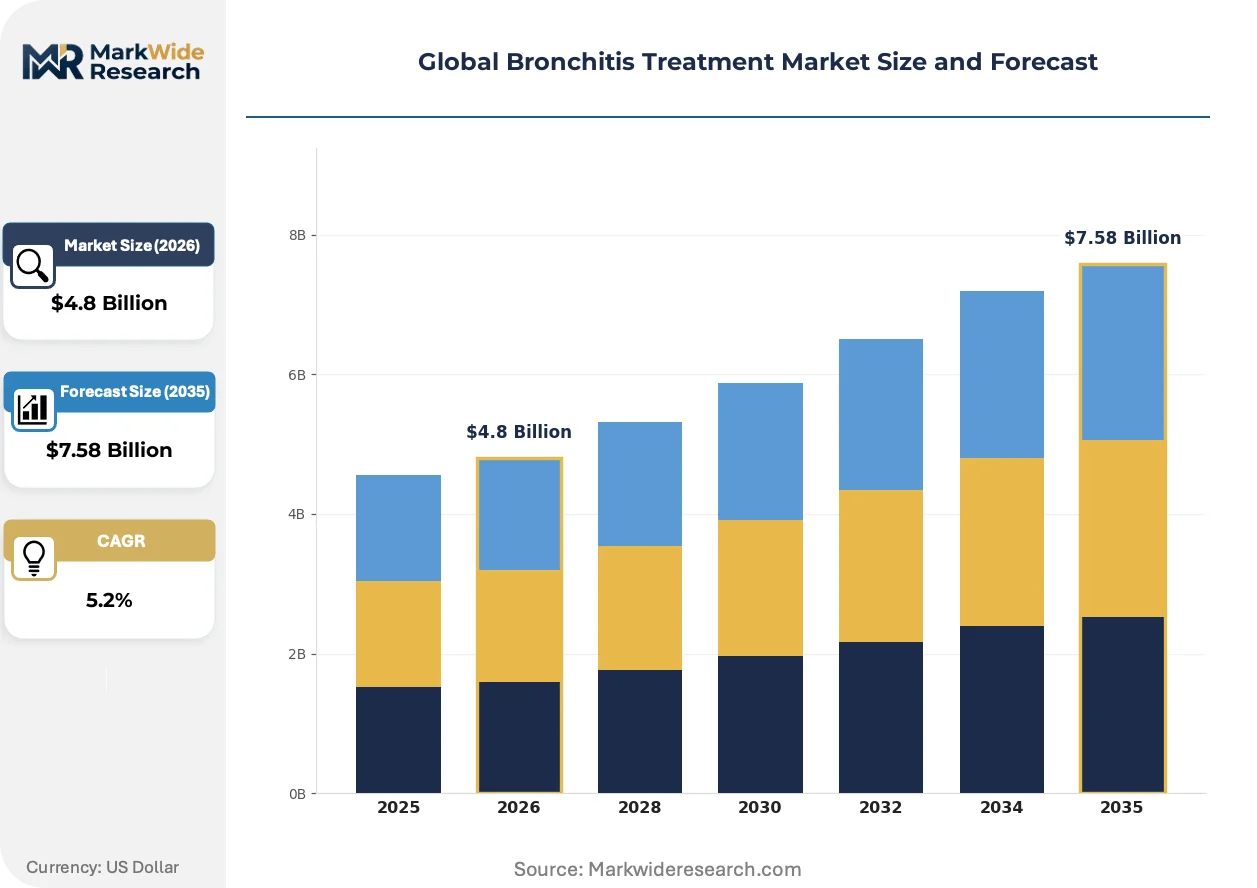
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Expectorants, Antibiotics, Antiviral Agents Therapy Area: Acute Bronchitis, Chronic Bronchitis, Viral Bronchitis, Bacterial Bronchitis, Allergic Bronchitis End User: Hospitals, Pulmonary Clinics, Respiratory Therapy Centers, Home Care Settings, Specialized Clinics Delivery Mode: Oral, Inhalation, Nebulization, Injection, Topical |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Novartis AG, Boehringer Ingelheim, Pfizer, Sanofi, Dr. Reddy's Laboratories, Teva Pharmaceutical Industries, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bronchitis Treatment Market Shifts & Advancements
Respiratory therapy delivery platforms are converging with digital health infrastructure, creating new value capture mechanisms beyond molecule exclusivity while regulatory frameworks on both sides of the Atlantic recalibrate evidence standards for device-drug combinations.
Smart nebulization systems with integrated flow sensors and dose verification algorithms are automating compliance monitoring for severe chronic bronchitis patients with compromised inspiratory capacity. Home care agencies across Germany and the United States are piloting these platforms for high-risk discharge populations. The technology is automating the transition from episodic pulmonary rehabilitation to continuous remote therapeutic monitoring, compressing emergency department utilization patterns.
The FDA's accelerated approval pathways for inhaled combination therapies are shortening development timelines for bronchodilator-corticosteroid products, compressing the traditional new molecular entity-to-market interval. Sponsors are responding by front-loading real-world evidence collection commitments to satisfy post-marketing study obligations. Fixed-dose combination formats targeting moderate-to-severe chronic bronchitis segments are capturing disproportionate review resource allocation.
Hospital procurement committees are consolidating respiratory therapy vendor relationships around full-service contracts encompassing devices, disposables, and clinical training. Pulmonary departments are shifting from transactional equipment purchasing to multi-year performance agreements with outcome-linked pricing adjustments. This consolidation is most visible in United States health system networks where COPD readmission penalties create aligned incentives for device standardization.
Global Bronchitis Treatment Market Segmentation
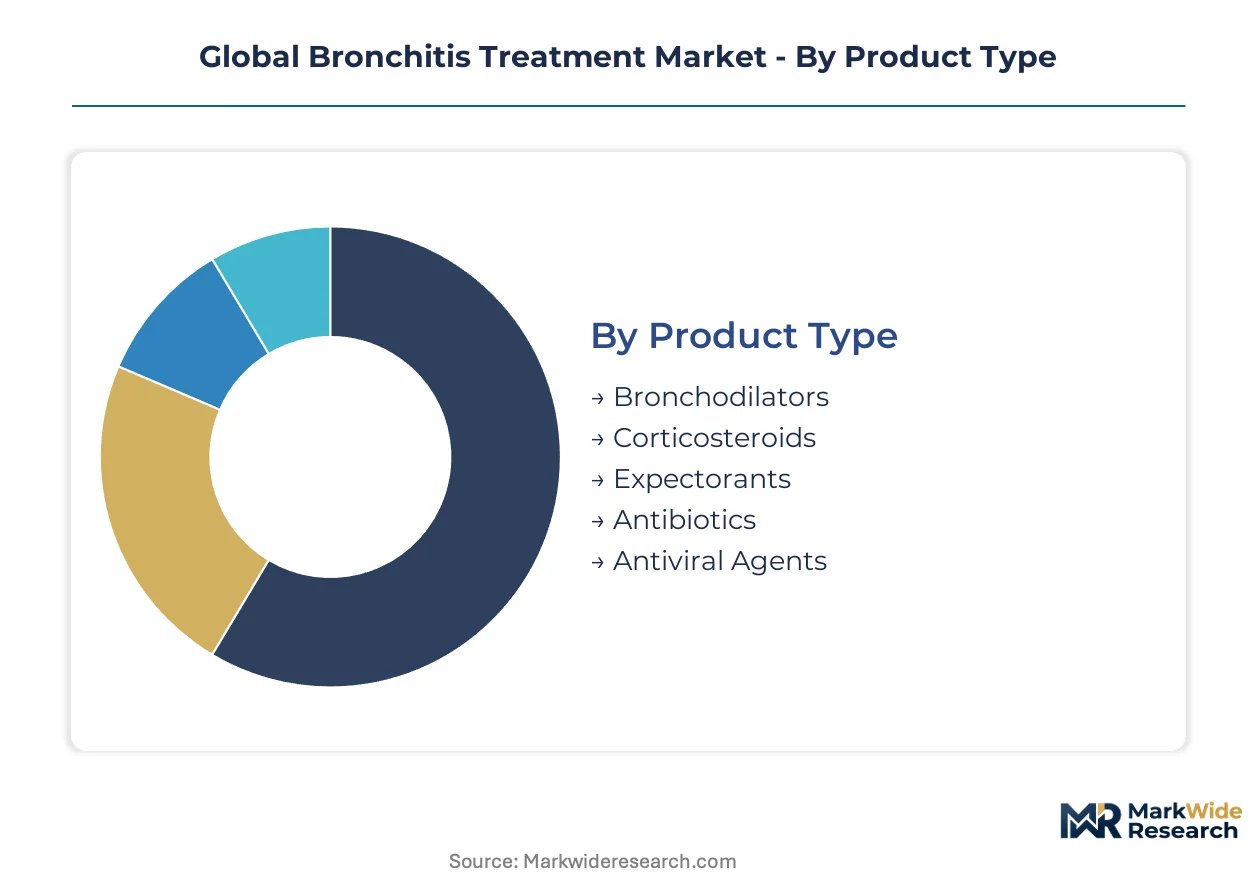
Bronchitis treatment markets fragment across pharmacological mechanisms, disease duration, care settings, and delivery technologies. Each dimension carries distinct regulatory burdens, reimbursement pathways, and competitive dynamics that shape portfolio prioritization for manufacturers.
Product Type:
FDA Center for Drug Evaluation and Research oversees bronchodilators and corticosteroids as new drug applications, while nebulizer-device combinations trigger parallel Center for Devices and Radiological Health review. EMA's MDR framework imposes additional clinical evidence requirements for drug-device combinations marketed across European Union member states.
- Bronchodilators:Beta-agonist and anticholinergic agents relax airway smooth muscle to improve forced expiratory volume. Demand concentrates in United States pulmonary clinics where COPD-bronchitis comorbidities drive maintenance prescribing, though generic substitution pressures compress pricing power.
- Corticosteroids:Inhaled glucocorticoid receptor agonists reduce eosinophilic and neutrophilic airway inflammation. Germany's statutory health insurance reimbursement for nebulized formulations anchors volume commitments for severe chronic bronchitis segments.
- Expectorants:Mucolytic agents thin bronchial secretions to facilitate clearance. Retail pharmacy channels capture seasonal acute bronchitis demand.
- Antibiotics:Bacterial infection targeting therapies face narrowing indications as diagnostic stewardship reduces inappropriate prescribing.
- Antiviral Agents:Neuraminidase inhibitors and polymerase inhibitors address influenza-triggered bronchitis episodes. Hospital formularies restrict access to confirmed viral etiology cases.
Leading the category by volume: Bronchodilators. Growing fastest: Corticosteroids in fixed-dose combination formats.
Therapy Area:
Duration and etiology determine treatment intensity, with chronic maintenance regimens commanding tenfold higher lifetime value per patient than acute episodic interventions.
- Acute Bronchitis:Self-limiting airway inflammation typically resolving without pharmaceutical intervention. United States retail pharmacy channels capture seasonal volume spikes in over-the-counter expectorants.
- Chronic Bronchitis:Persistent productive cough with recurring exacerbations requiring maintenance bronchodilator-corticosteroid therapy. Germany's pulmonary clinic networks and United States hospital systems anchor the largest revenue pools.
- Viral Bronchitis:Influenza, RSV, and rhinovirus-triggered inflammation. Antiviral prescribing concentrates in hospital emergency departments during winter respiratory seasons.
- Bacterial Bronchitis:Secondary bacterial colonization requiring targeted antibiotic therapy. Diagnostic stewardship initiatives in United States and European Union markets narrow appropriate use criteria.
- Allergic Bronthitis:IgE-mediated airway hyperresponsiveness overlapping with asthma phenotypes. Specialized allergy-immunology clinics in Germany and United States coordinate multidisciplinary care.
Revenue concentration peaks in chronic maintenance segments. Steepest expansion trajectory: Viral-directed therapies amid respiratory virus surveillance investments.
End User:
Site-of-care migration from inpatient to outpatient and home settings is reshaping device form factor requirements and reimbursement coding complexity.
- Hospitals:Acute exacerbation management with intravenous bronchodilators and oxygen therapy. United States COPD readmission penalties align procurement committees around outcome-linked device contracts.
- Pulmonary Clinics:Chronic disease monitoring and maintenance therapy optimization. Germany's statutory health insurance framework creates predictable demand corridors for nebulized therapies.
- Respiratory Therapy Centers:Specialized rehabilitation and technique training facilities. Post-acute care discharge protocols in United States expand referral volumes.
- Home Care Settings:Durable medical equipment provision for stable chronic patients. Bluetooth-enabled adherence monitoring creates data monetization opportunities for payers.
- Specialized Clinics:Allergy-immunology and occupational medicine referral centers. Urban clusters in Germany and United States concentrate highest-complexity cases.
Volume leadership: Hospital systems. Fastest channel expansion: Home care settings riding durable medical equipment reimbursement expansion.
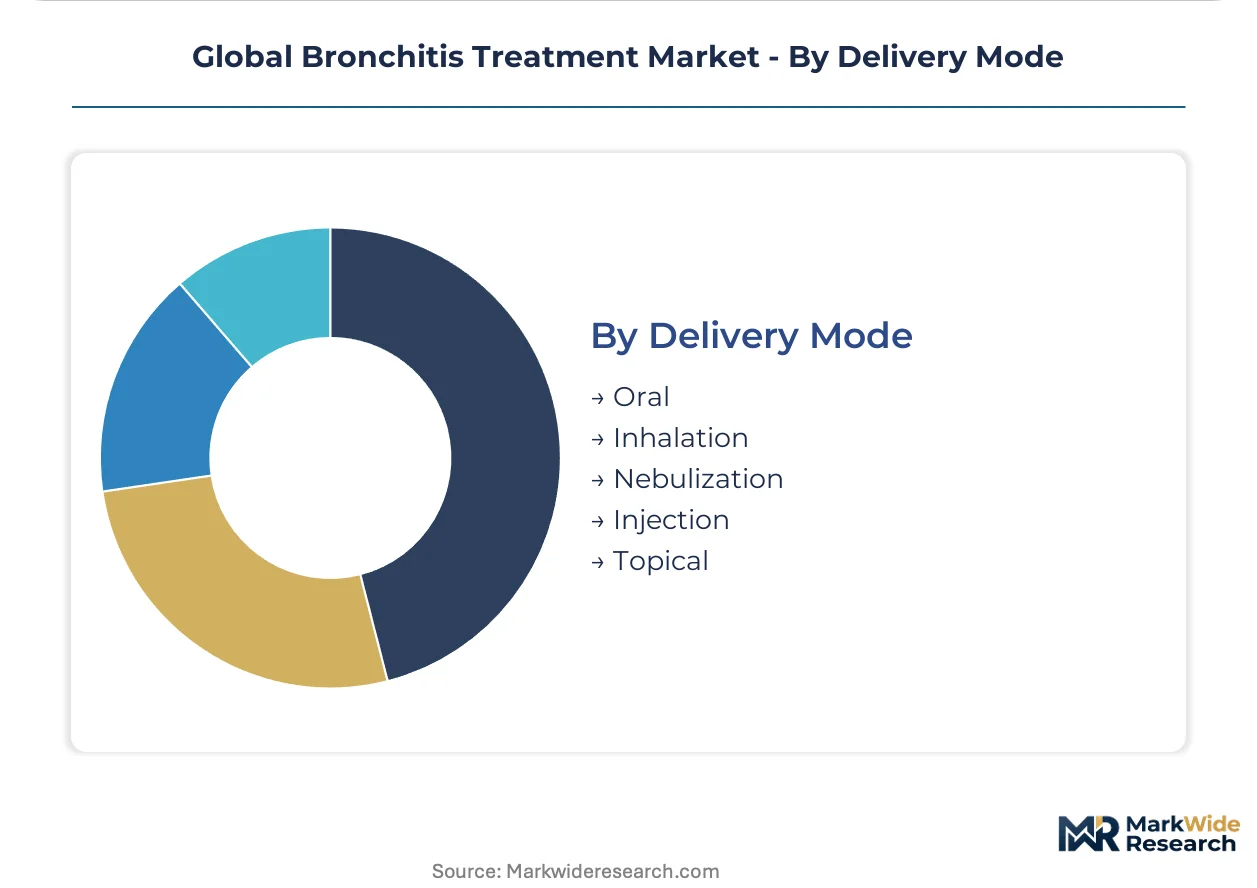
Delivery Mode:
Pharmacokinetic targeting precision and patient inspiratory capacity determine modality selection, with direct lung delivery commanding premium positioning over systemic routes.
- Oral:Systemic absorption via gastrointestinal tract for antibiotics and expectorants. Retail pharmacy distribution captures acute bronchitis episodic demand.
- Inhalation:Dry powder and metered-dose devices delivering bronchodilators and corticosteroids to distal airways. FDA bioequivalence standards for generic entrants preserve originator pricing power in United States markets.
- Nebulization:Aerosol generation for patients with compromised inspiratory flow. EMA MDR device classification imposes stricter clinical evidence requirements, accelerating manufacturer consolidation.
- Injection:Intravenous and subcutaneous routes for acute exacerbation rescue therapy. Hospital pharmacy controls formulary access.
- Topical:Limited application for chest rub formulations and steam inhalation adjuncts. Consumer health segments in emerging markets sustain residual demand.
Revenue per patient peaks in inhalation modalities. Gaining share fastest: Nebulization systems integrated with remote monitoring platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical ingredients clusters in India and European contract facilities, while consumption concentrates in United States hospital systems and German pulmonary clinic networks. Regulatory divergence between FDA bioequivalence standards and EMA MDR device classifications fragments competitive access across Atlantic markets.
United States
COPD-bronchitis comorbidities drive maintenance prescribing of bronchodilator-corticosteroid combinations across hospital respiratory therapy departments. FDA accelerated approval pathways compress development timelines for fixed-dose inhaler products. The Cleveland Clinic and Mayo Clinic pulmonary networks anchor outcome-linked device procurement contracts that standardize nebulization platforms across multi-hospital systems.
Germany
Statutory health insurance reimbursement for nebulized therapies creates predictable demand corridors for severe chronic bronchitis segments. EMA MDR framework imposes stricter clinical evidence requirements for drug-device combinations, favoring manufacturers with established notified body relationships. Pulmonary clinic networks in Bavaria and North Rhine-Westphalia concentrate the highest-volume maintenance therapy prescriptions.
China
NMPA priority review program for locally manufactured generic bronchodilators accelerates competitive entry timelines. Dual carbon goals reshape pharmaceutical manufacturing investment toward energy-efficient API production. Yangtze River Delta contract manufacturers expand capacity to serve domestic respiratory therapy demand and emerging market export requirements.
India
Production-linked incentive schemes attract contract manufacturing investment for inhaled corticosteroid active pharmaceutical ingredients. CDSCO streamlined review pathways compress generic bronchodilator approval timelines. Gujarat and Maharashtra pharmaceutical clusters deepen backward integration into API synthesis, reducing import dependence for formulation specialists.
United Kingdom
NHS respiratory pathway redesigns shift chronic bronchitis monitoring from hospital to community settings, expanding home nebulization eligibility. MHRA post-Brexit regulatory autonomy enables accelerated approval timelines for innovative inhaler devices. London and Manchester pulmonary research centers pilot Bluetooth-enabled adherence monitoring for high-utilization patient populations.
Global Bronchitis Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with respiratory portfolio depth. Originators with established bronchodilator-corticosteroid franchises command pricing power through FDA bioequivalence barriers, while generic specialists compete on cost in oral antibiotic and expectorant segments. Two strategic archetypes dominate: integrated respiratory platform owners with device-engineering capabilities, and API-backward-integrated formulation specialists. Capacity expansion in Indian contract manufacturing and strategic partnerships for digital inhaler convergence represent the dominant competitive moves.
Within the integrated respiratory platform tier, AstraZeneca and GlaxoSmithKline occupy positions anchored by fixed-dose combination inhaler portfolios. Boehringer Ingelheim exemplifies the device-differentiation archetype through specialized nebulization technology platforms. Among emerging-market formulation specialists, Dr. Reddy's Laboratories and Cipla represent cost-competitive positions in generic bronchodilator supply.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Novartis AG |
| Boehringer Ingelheim |
| Pfizer |
| Sanofi |
| Dr. Reddy's Laboratories |
| Teva Pharmaceutical Industries |
| Cipla |
| Others |
Supply & Pricing Matrix
Backward integration into active pharmaceutical ingredient production anchors pricing power for inhaled corticosteroid formulators, while outsourced bronchodilator supply exposes generic specialists to input volatility and margin compression. This structural divergence separates originators with captive supply chains from formulation-dependent competitors navigating qualification delays and spot-market API costs.
Pricing Analysis
Margin tightening in generic bronchodilator tiers reflects CDSCO accelerated review pathways compressing competitive windows in India. Three-tier pricing structure across premium fixed-dose combinations, standard single-agent inhalers, and economy oral generics separates originator device-engineering investments from commodity substitution. Price differentiation traces to FDA bioequivalence study burdens and EMA MDR device certification tiers. Hospital procurement committees exhibit lowest price sensitivity due to outcome-linked contracting, while retail pharmacy channels face acute substitution pressure.
Supply Chain Analysis
Inhaled corticosteroid API supply rests on European contract manufacturers and Indian pharmaceutical clusters in Gujarat and Maharashtra. Beclomethasone and fluticasone propionate feedstock draws from specialty chemical producers, while lactose carrier excipients source from New Zealand and European dairy processors. Single-source vulnerability concentrates in qualified inhaler device component suppliers. Distribution runs through hospital pharmacy direct purchasing and pulmonary clinic durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EMA MDR device classification and FDA combination product review complexity force subscale manufacturers toward exit or acquisition. Regulatory qualification burdens favor incumbents with established notified body relationships and parallel CDER-CDRH submission experience.
For Market Incumbents: Extend fixed-dose combination portfolios through synchronized bronchodilator-corticosteroid formulation stability programs. Deepen backward integration into API synthesis to defend against Indian contract manufacturing cost advantages. Anchor hospital system procurement relationships through multi-year performance agreements with COPD readmission penalty alignment. For New Entrants and Emerging Players: Capture home nebulization infrastructure gaps in United States post-acute discharge protocols where durable medical equipment reimbursement creates channel access. Target Bluetooth-enabled adherence monitoring platforms for payer data monetization partnerships. Pursue CDSCO streamlined review pathways for generic bronchodilator entry with localized manufacturing partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in device-differentiated respiratory platforms with nebulization technology moats and established notified body relationships. Five-to-ten year viability hinges on digital inhaler convergence capabilities and real-world evidence collection infrastructure. Watch FDA accelerated approval commitment letters to originators as signal of review resource allocation and competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Accelerated Approval Pathway | Compresses bronchodilator-corticosteroid development timelines through priority review resource allocation. |
| EMA MDR Device Certification | Raises clinical evidence barriers for nebulizer systems, consolidating manufacturer base toward premium players. |
| Hospital System Partnership | Locks multi-year respiratory therapy contracts with outcome-linked pricing and device standardization. |
| Backward API Integration | Captures inhaled corticosteroid active pharmaceutical ingredient supply through Indian PLI manufacturing incentives. |
| Digital Inhaler Convergence | Enables Bluetooth-enabled dose counter telemonitoring for payer adherence data monetization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this respiratory therapy market assessment. Primary interviews with formulary directors, hospital procurement managers, pulmonary clinic administrators, and payer access specialists cross-validated volume assumptions. FDA CDER and CDRH submission databases, EMA MDR notified body certificates, and CDSCO approval records provided regulatory trajectory inputs. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation reconciled market sizing.
Data-stream reconciliation across therapy area, delivery mode, and end-user segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs derived from patient epidemiology trends, pricing trajectory assumptions, and regulatory approval velocity modeling. Inhaler bioequivalence study completion rates and nebulizer device MDR certification timelines served as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA review resource reallocation, EMA MDR enforcement intensity shifts, and NMPA domestic manufacturing preference policy evolution. Forecasts reflect documented assumptions on patient diagnosis rates, generic substitution elasticities, and durable medical equipment reimbursement stability. A small set of named triggers—WHO prequalification initiative expansion, major health system vertical integration, and respiratory virus surveillance investment surges—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market