
 Croup Treatment Market | 2026-2036
Croup Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Croup Treatment Market Outlook
Capital-intensity divergence between large-scale inhalation device manufacturers and generic oral formulation producers is redrawing competitive boundaries in croup therapeutics. GlaxoSmithKline plc leverages decades of respiratory delivery expertise to sustain premium positioning across pediatric inhalation portfolios. AstraZeneca plc anchors its presence through specialized corticosteroid development programs targeting acute laryngeal obstruction. Teva Pharmaceutical Industries competes aggressively on cost-optimized oral and inhaled generic alternatives, extending reach into price-sensitive hospital procurement channels.
Croup treatment encompasses pharmacological and supportive interventions targeting acute viral laryngotracheobronchitis in children, typically involving nebulized epinephrine and systemic corticosteroids administered via metered-dose inhalers or oral solutions with precise weight-based dosing protocols. The primary purpose centers on rapid airway decongestion and inflammation reduction to prevent respiratory failure and intubation. Corticosteroids dominate value generation within product type segmentation due to their established efficacy in reducing hospitalization duration, while inhaled medications capture expanding share as emergency departments prioritize faster onset of action. Pediatric clinics and emergency departments together constitute the critical end-user nexus where formulary decisions and treatment protocols concentrate purchasing power.
FDA pediatric guidance documents and EMA Pediatric Investigation Plans shape clinical trial requirements and labeling standards for croup-specific indications, directly influencing development timelines and market access conditions. The WHO Essential Medicines List inclusion of dexamethasone and epinephrine reinforces procurement prioritization across national health systems. Stakeholders must monitor evolving pharmacovigilance requirements for inhaled corticosteroid use in children under two years, as regulatory scrutiny intensifies around long-term neurodevelopmental outcomes.
Market Dynamics
Pediatric emergency departments are consolidating treatment protocols around single-dose dexamethasone protocols, compressing formulary diversity and concentrating purchasing power among hospital networks that can enforce standardized care pathways across multiple facilities.
Growth Catalysts
- WHO Essential Medicines List inclusion:Dexamethasone and epinephrine procurement prioritization by national health systems in low-resource settings is expanding addressable patient populations.
- FDA pediatric labeling expansion:Tightening formulation standards for inhaled therapies in children under two years is accelerating device innovation investments by manufacturers seeking differentiated positioning.
- Epinephrine nebulization protocols:Emergency medicine societies in the United States are endorsing faster onset-of-action treatments, driving hospital formulary upgrades from oral to inhaled delivery systems.
Market Restraints
- API supply concentration:Corticosteroid active pharmaceutical ingredient production clusters in India and China, exposing formulators to export restriction risks and quality inspection backlogs.
- Inhalation device technical limitations:Current nebulizer designs struggle with consistent particle size distribution below five microns, reducing lung deposition efficiency in infants with narrow airways.
- EMA Pediatric Investigation Plan timelines:Extended clinical trial requirements for children under two years delay product launches by three to five years versus adult respiratory indications.
Strategic Opportunities
- Underpenetrated Brazil market:ANVISA streamlined pediatric emergency medicine approvals create first-mover advantages for corticosteroid-device combination filings.
- Home-based nebulization:Parent-administered croup treatment protocols are expanding beyond hospital settings, opening retail pharmacy and direct-to-patient distribution channels.
- Smart inhaler convergence:Bluetooth-enabled dose counters paired with mobile applications enable adherence monitoring that satisfies payer evidence requirements for reimbursement.
Industry Challenges
- Pediatric formulation expertise scarcity:Qualified toxicologists and pharmacokineticists specializing in neonatal respiratory dosing remain concentrated at fewer than twelve contract research organizations globally.
- ISO 18562 biocompatibility certification:Inhalation device manufacturers face eighteen-month testing timelines for polymer leachables and condensate analysis before EU market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Croup Treatment Market |
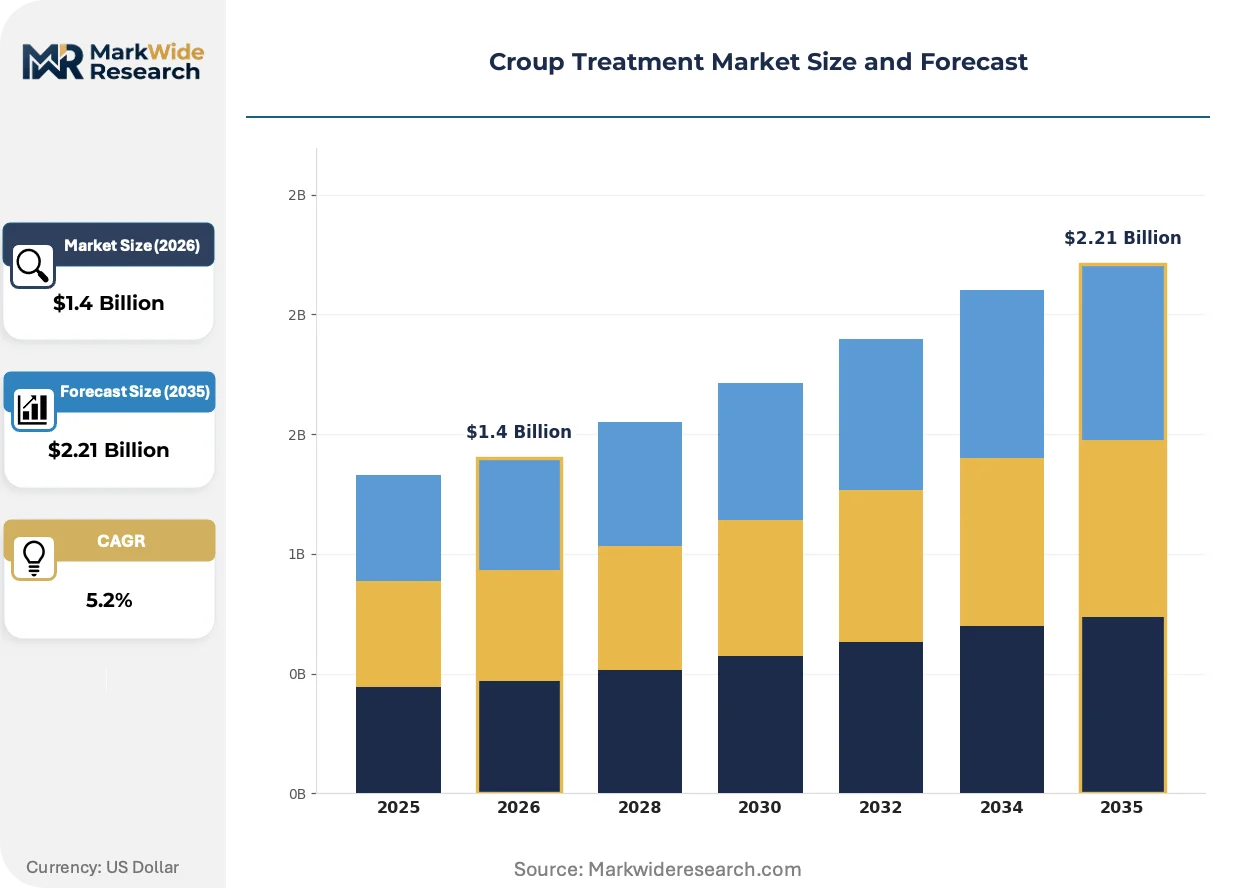
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Inhaled Medications, Corticosteroids, Antipyretics Therapy Area: Respiratory Conditions, Pediatric Care, Acute Care, Emergency Medicine Delivery Mode: Inhalation, Oral, Intravenous, Subcutaneous End User: Pediatric Clinics, Emergency Departments, Home Care, Hospitals |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Novartis AG, Sanofi, Merck & Co., Inc., Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Croup Treatment Market Strategic Shifts
Evidence-based protocol standardization is compressing variation in croup treatment while digital therapeutics and connected devices create new data layers around medication adherence and outcomes tracking.
Mesh nebulization technology is supplanting traditional jet nebulizers in pediatric emergency departments by delivering epinephrine aerosols with tighter particle size distribution and reduced treatment times. Children's Hospital of Philadelphia and Boston Children's Hospital have adopted these devices for croup protocols since 2022. The technology is supplanting compressor-based systems in high-throughput emergency settings where throughput metrics determine capital allocation.
EMA's tightened Pediatric Investigation Plan requirements for inhaled corticosteroids are extending development timelines and forcing sponsors to commit to neurodevelopmental follow-up studies through age five. Small and mid-sized pharmaceutical developers are abandoning pediatric-specific indications in favor of adult asthma extensions with off-label use. European hospital formularies are responding by consolidating around established dexamethasone oral solutions rather than awaiting novel inhaled approvals.
Hospital procurement departments are unbundling device and drug purchasing decisions, creating separate vendor relationships for nebulization hardware and pharmaceutical supply. Group purchasing organizations representing mid-Atlantic and Southwest US health systems have split these categories in recent tenders. This shift is most visible in integrated delivery networks with centralized pharmacy and materials management functions.
Croup Treatment Market Segmentation
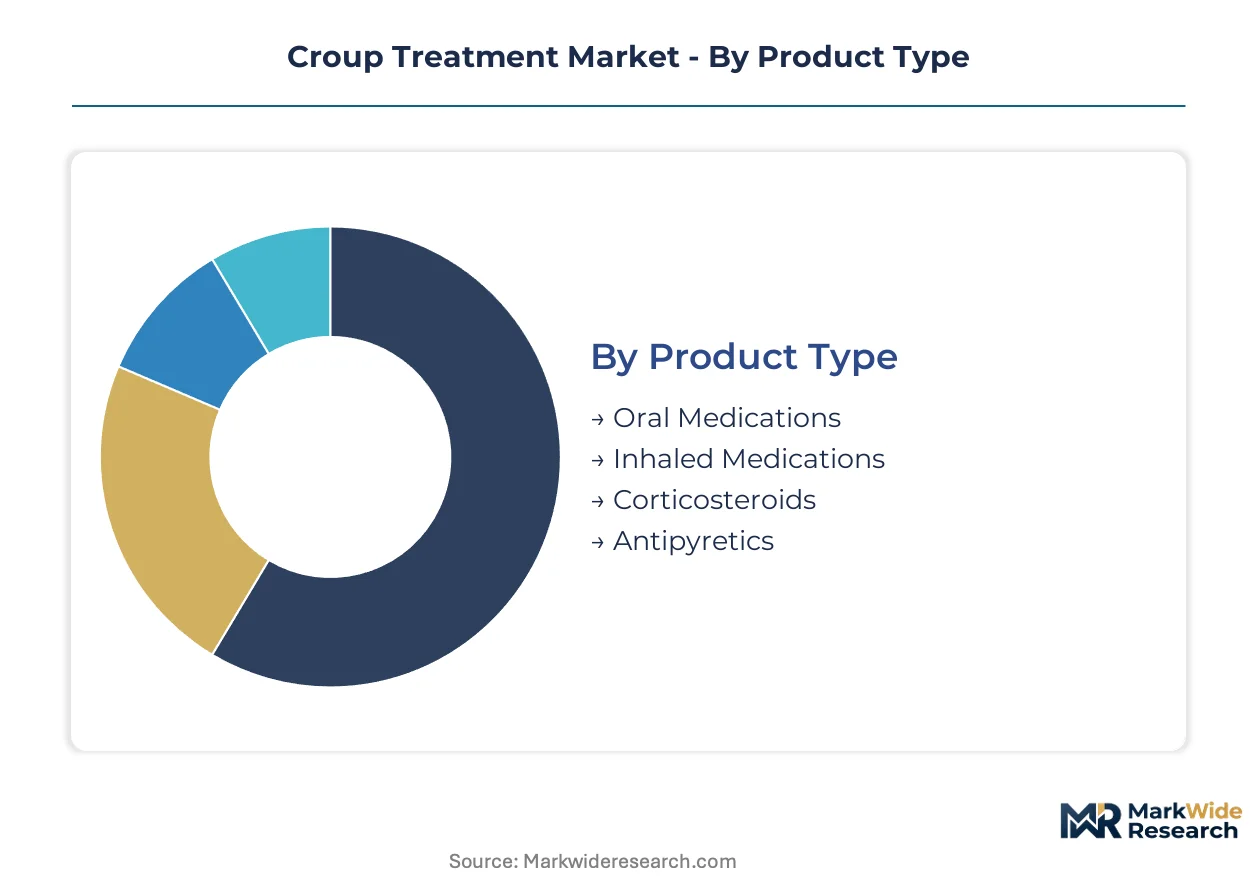
Croup treatment segmentation reveals how regulatory pathways and clinical settings reshape commercial priorities. Formulation standards diverge sharply across pediatric age brackets, while delivery technology investments concentrate where emergency protocols demand fastest onset of action.
Product Type:
FDA pediatric labeling requirements and EMA formulation standards create distinct compliance burdens across chemical classes, with inhaled therapies facing heightened biocompatibility scrutiny.
- Corticosteroids:Systemic dexamethasone and nebulized budesonide formulations dominate hospital formularies through established evidence bases in reducing airway inflammation. United States pediatric emergency departments have consolidated around single-dose protocols, compressing purchasing decisions toward high-volume oral solutions and standardized nebulization cartridges.
- Inhaled Medications:Nebulized epinephrine delivers rapid alpha-adrenergic vasoconstriction for acute laryngeal obstruction, with mesh nebulizer technology tightening particle size distribution below five microns. Children's Hospital of Philadelphia and Boston Children's Hospital adopted these systems for throughput optimization, though ISO 18562 certification timelines extend EU commercialization by eighteen months.
- Oral Medications:Liquid corticosteroid solutions with weight-based dosing syringes remain the cost-optimized standard for mild-to-moderate cases in outpatient settings.
- Antipyretics:Adjunctive fever management plays limited role in airway-focused protocols, with acetaminophen and ibuprofen suspensions supporting comfort care rather than disease modification.
Established volume favors corticosteroids; emerging adoption favors inhaled medications.
Therapy Area:
Clinical setting determines reimbursement pathways and device capital allocation, with emergency medicine commanding premium pricing for rapid-onset interventions.
- Emergency Medicine:Acute laryngotracheobronchitis protocols in high-throughput departments drive nebulization hardware procurement and single-use medication cartridges. United States hospital networks enforce standardized care pathways across multiple facilities, concentrating purchasing power among integrated delivery systems.
- Pediatric Care:Outpatient clinics manage mild croup presentations through oral corticosteroid dispensing, with parent education on home monitoring reducing unnecessary emergency transfers.
- Respiratory Conditions:Broader pediatric respiratory portfolios include croup as one indication among viral bronchiolitis and asthma exacerbation management.
- Acute Care:General pediatric wards handle observation admissions following emergency department stabilization, with nursing protocols emphasizing respiratory monitoring rather than active intervention.
Revenue concentration sits with emergency medicine; volume expansion is climbing the fastest in pediatric care.
Delivery Mode:
Particle engineering capabilities and patient age stratification determine technical feasibility, with infant airway anatomy constraining deposition efficiency.
- Inhalation:Jet and mesh nebulization systems target lower respiratory deposition, though current designs struggle with consistent particle size distribution in infants under twelve months. WHO Essential Medicines List inclusion of epinephrine reinforces procurement prioritization across national health systems.
- Oral:Palatability-masked solutions with calibrated dosing devices dominate home and outpatient administration, with generic competition compressing margins.
- Intravenous:Reserved for respiratory failure and peri-intubation management in intensive care settings with limited addressable volume.
- Subcutaneous:Minimal role in croup protocols, with epinephrine auto-injector formats more relevant to anaphylaxis indications.
Technical leadership concentrates in inhalation; cost optimization favors oral delivery.
End User:
Procurement centralization and protocol standardization reshape vendor relationships across care settings.
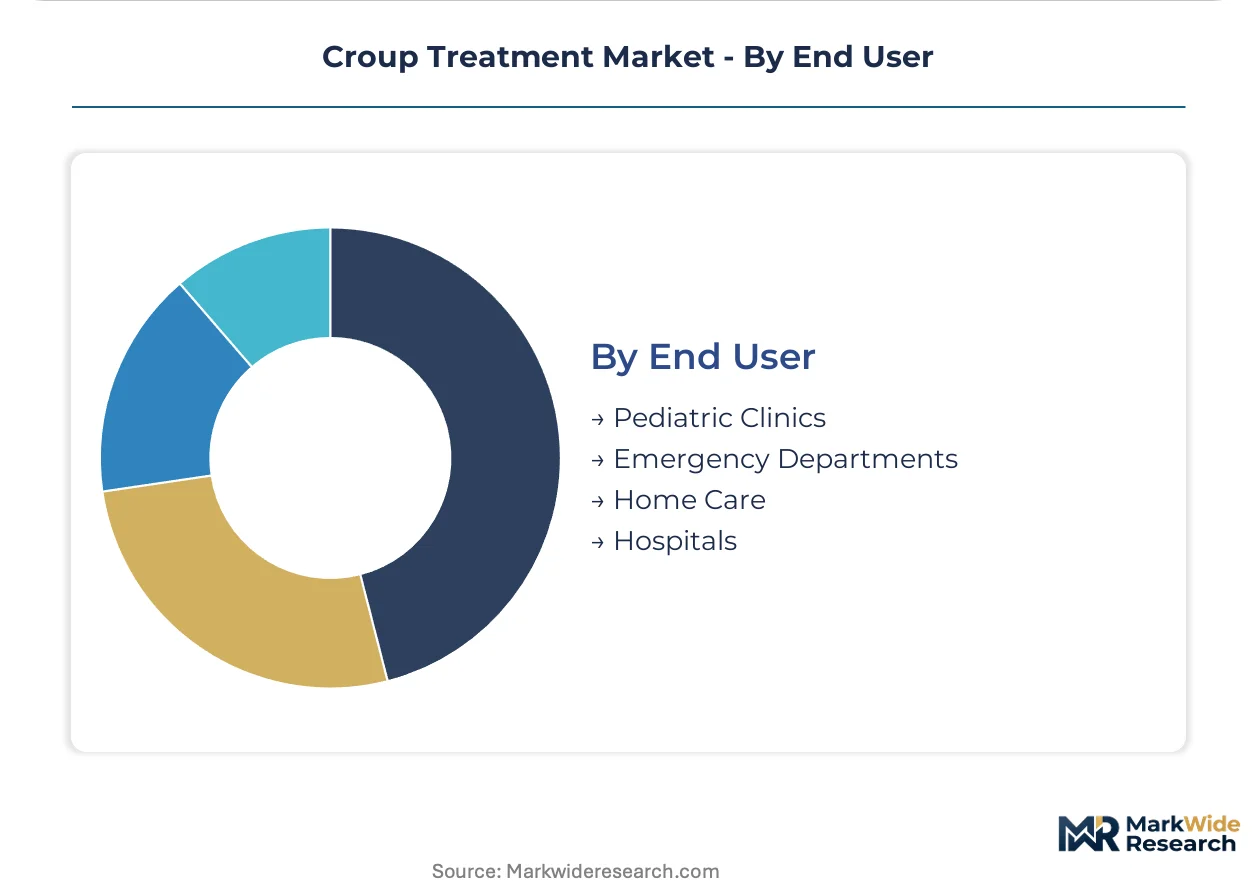
- Emergency Departments:Pediatric emergency medicine societies in the United States endorse faster onset-of-action treatments, driving formulary upgrades and mesh nebulizer capital investments. Group purchasing organizations have unbundled device and drug purchasing decisions, creating separate vendor relationships.
- Pediatric Clinics:Outpatient settings prioritize parent-administered oral solutions with clear rescue criteria for emergency escalation.
- Hospitals:General inpatient units handle observation and step-down care, with pharmacy and therapeutics committees standardizing across emergency and ward formularies.
- Home Care:Parent-administered nebulization protocols are expanding beyond hospital settings, opening retail pharmacy distribution and mobile application adherence monitoring.
Institutional purchasing power favors emergency departments; steepest expansion trajectory favors home care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States hospital networks while procurement in India and Brazil operates on cost-optimized tenders. This asymmetry shapes where device manufacturers prioritize premium mesh nebulizers versus generic oral formulations.
United States
Pediatric emergency departments at Children's Hospital of Philadelphia and Boston Children's Hospital drive mesh nebulizer adoption for throughput optimization. FDA pediatric labeling requirements for inhaled therapies in children under two years accelerate device innovation investments. Hospital procurement consolidation across integrated delivery networks in the mid-Atlantic and Southwest regions unbundles device and drug purchasing decisions.
Germany
EMA Pediatric Investigation Plan timelines extend development for novel inhaled corticosteroids by three to five years versus adult indications. ISO 18562 biocompatibility certification for polymer leachables creates eighteen-month testing barriers before EU market entry. Berlin-Brandenburg and Bavaria host specialized contract research organizations handling neonatal respiratory pharmacokinetics.
India
API production concentration for corticosteroids in Hyderabad and Ahmedabad exposes formulators to export restriction risks and quality inspection backlogs. CDSCO streamlined pediatric emergency medicine approvals attract filings for cost-optimized oral dexamethasone solutions. Maharashtra and Gujarat manufacturing clusters supply generic formulations to WHO Essential Medicines List procurement programs.
Brazil
ANVISA regulatory streamlining creates first-mover advantages for corticosteroid-device combination filings in underpenetrated pediatric emergency markets. São Paulo and Rio de Janeiro hospital networks consolidate formulary decisions around evidence-based single-dose protocols. National health system procurement prioritization of WHO-listed medicines expands addressable patient populations beyond insured segments.
United Kingdom
NHS England pediatric pathway standardization compresses formulary diversity toward oral dexamethasone solutions with weight-based dosing syringes. MHRA alignment with EMA pediatric investigation requirements delays novel inhaled product launches. London and Southeast England academic medical centers anchor clinical trial networks for neurodevelopmental follow-up studies through age five.
Croup Treatment Market Competitive Environment
Concentration sits with diversified respiratory pharmaceutical manufacturers possessing decades of pediatric delivery expertise. The vendor base spans three tiers: multinational innovators with integrated device-drug portfolios, generic specialists competing on oral formulation cost, and emerging nebulizer technology developers. Strategic moves center on unbundling procurement relationships and backward integration into corticosteroid API supply.
Within the multinational innovator tier, GlaxoSmithKline plc and AstraZeneca plc occupy positions shaped by respiratory delivery heritage and specialized corticosteroid development programs. Teva Pharmaceutical Industries exemplifies the generic specialist archetype, anchoring cost-optimized competition across oral and inhaled alternatives. These three companies represent the competitive poles around which hospital formulary decisions and procurement channel strategies organize.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Novartis AG |
| Sanofi |
| Merck & Co., Inc. |
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries |
| Cipla |
| Others |
Value Chain & Pricing Dynamics
Batch-scale efficiency in corticosteroid API synthesis anchors cost structures across oral and inhaled formulation tiers, concentrating manufacturing advantage among producers operating multi-tonne reactors in Gujarat and Maharashtra while compressing price floors for generic alternatives. This scale dynamic funnels procurement power toward hospital networks and group purchasing organizations capable of consolidating volume across integrated delivery systems.
Pricing Analysis
The customization-premium spread separates ISO 18562-certified mesh nebulizer systems from commodity jet nebulizers and standard oral solutions, with FDA pediatric labeling tiers and EMA biocompatibility grades serving as the primary price differentiation drivers. Contract-based long-term offtake agreements dominate hospital procurement, though cost compression in generic oral dexamethasone intensifies as Indian API producers expand capacity. Pediatric emergency departments show lowest price sensitivity due to protocol standardization imperatives, while outpatient clinics and home care segments prioritize cost-optimized alternatives.
Supply Chain Analysis
Hyderabad-Ahmedabad API corridors and Shanghai-Zhejiang chemical parks constitute the dominant chokepoints for corticosteroid active pharmaceutical ingredients, with single-source vulnerability concentrated among European and North American formulators lacking backward integration into fermentation and synthesis stages. Distribution runs through national health system tenders and group purchasing organization contracts, with WHO Essential Medicines List procurement creating parallel channels for low-resource settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Purchasing power is concentrating among mid-Atlantic and Southwest US integrated delivery networks that unbundle device and drug procurement, fragmenting vendor relationships and compressing margin capture across the supplier base.
For Market Incumbents: Fortify mesh nebulizer market position through captive corticosteroid API supply and accelerated ISO 18562 certification pipelines that preempt EU market entry barriers. Prioritize backward integration into Indian API manufacturing clusters to offset export restriction risks from concentrated Hyderabad-Ahmedabad production zones. For New Entrants and Emerging Players: Lead with ANVISA-streamlined pediatric emergency filings in São Paulo and Rio de Janeiro hospital networks, where single-dose protocol standardization creates first-mover advantages for cost-optimized oral dexamethasone solutions. Target home care distribution channels through parent-administered nebulization protocols paired with mobile adherence applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-drug combination developers with locked hospital system contracts and neurodevelopmental follow-up study commitments through EMA Pediatric Investigation Plans. Monitor FDA pediatric labeling expansion timelines for inhaled therapies in children under two years as the critical inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Pediatric Investigation Plan commitments through age five anchor neurodevelopmental liability and extend exclusivity windows. |
| Backward Integration | Captive corticosteroid API production in Indian manufacturing clusters insulates formulators from export restriction shocks. |
| Hospital System Partnership | Integrated delivery network formulary consolidation across mid-Atlantic and Southwest US regions locks in multi-facility procurement. |
| Software Companion Development | Bluetooth-enabled dose counters paired with mobile applications satisfy payer evidence requirements for home care reimbursement. |
| CE Marking Pathway | ISO 18562 biocompatibility certification for polymer leachables creates eighteen-month barriers that filter competitor entry. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric emergency medicine specialists, hospital pharmacy and therapeutics committee chairs, nebulizer device engineering leads, and corticosteroid API procurement managers at Indian manufacturing clusters. Secondary validation drew from FDA pediatric guidance documents, EMA Pediatric Investigation Plan submissions, WHO Essential Medicines List procurement databases, and hospital GPO contract disclosures. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Across the analysis window, the analytical framework modeled treatment setting stratification, delivery technology tier, pediatric age bracket, and regional regulatory cluster. CAGRs were derived from epidemiological incidence projections, protocol penetration curves for mesh nebulization, and formulary consolidation rates across integrated delivery networks. Forecast inputs included pediatric emergency department admission rates, corticosteroid API capacity expansion schedules, and EMA neurodevelopmental follow-up study completion timelines.
Underlying assumptions cover stable viral croup incidence patterns and sustained WHO procurement prioritization, with deviation risk concentrated in export restriction shocks from Indian API corridors and accelerated FDA labeling requirements for inhaled therapies. Practitioners should keep alternative scenarios live as EMA Pediatric Investigation Plan enforcement intensity and hospital procurement unbundling momentum evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Respiratory Trainer Market