
 Respiratory Disorders Treatment Market | 2026-2036
Respiratory Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Disorders Treatment Market Outlook
Aftermarket service revenue for inhaler device maintenance and nebulizer calibration is narrowing as manufacturers bundle multi-year service contracts with initial equipment sales. AstraZeneca plc leverages its biologics pipeline to dominate severe asthma and COPD segments with inhaled corticosteroid combinations. Boehringer Ingelheim International GmbH sustains manufacturing scale across dry powder and soft mist platforms, anchoring supply security for European and Asian hospitals. GlaxoSmithKline plc competes through channel control in retail pharmacy networks, particularly for rescue inhaler volumes.
Respiratory disorders treatment encompasses pharmaceutical interventions, mechanical delivery devices, and oxygen supplementation systems designed to restore pulmonary function, maintain airway patency, and correct hypoxemia in patients with obstructive, restrictive, or infectious lung conditions. Inhalers incorporating hydrofluoroalkane propellants or dry powder formulations deliver metered doses of bronchodilators and anti-inflammatory agents directly to the lower respiratory tract, achieving therapeutic concentrations with minimal systemic exposure. Among application segments, chronic obstructive pulmonary disease occupies the largest patient pool and generates the steadiest reimbursement flows, while cystic fibrosis commands premium pricing for targeted biologic therapies despite smaller eligible populations. Home care settings represent the fastest-growing end user channel as portable oxygen concentrators and mesh nebulizers enable ambulatory management of chronic conditions outside institutional walls.
The FDA's Center for Drug Evaluation and Research enforces strict bioequivalence standards for generic inhaled products, limiting substitutability and preserving branded pricing power for complex formulations. The European Medicines Agency's Medical Device Regulation imposes clinical evidence requirements on nebulizer and oxygen delivery systems, elevating compliance costs for manufacturers seeking CE marking access. Stakeholders must monitor how payer consolidation in the United States and reference pricing expansion in Germany reshape margin structures across the inhaler-to-biologic value chain.
Market Dynamics
Reimbursement pathways for home-based respiratory care are redirecting patient volumes from acute hospital settings toward ambulatory channels, compressing traditional device economics while expanding service contract bundling.
Growth Catalysts
- Medicare reimbursement reforms:United States policy shifts for home oxygen therapy and nebulizer coverage accelerate patient migration from inpatient to home care settings.
- EMA adaptive licensing frameworks:Accelerated pathways for breakthrough respiratory biologics compress time-to-market for severe asthma and COPD therapies across European markets.
- Portable oxygen concentrator miniaturization:Battery chemistry advances enable lighter ambulatory devices that sustain therapeutic oxygen delivery during patient mobility.
Market Restraints
- Active pharmaceutical ingredient concentration:Inhaler propellant and corticosteroid supply chains cluster among limited specialty chemical manufacturers in India and China.
- FDA bioequivalence standards:Complex pharmacokinetic requirements for generic inhaled products limit substitutability and preserve branded pricing power.
- Dry powder inhaler technical barriers:Powder engineering limitations around dose uniformity and moisture sensitivity constrain formulation flexibility for biologic macromolecules.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil and Mexico exhibit rising COPD prevalence with limited biologic therapy access, creating whitespace for tiered pricing entry.
- Mesh nebulizer connectivity convergence:Integration of Bluetooth dose tracking with electronic health record systems enables remote monitoring reimbursement codes.
- Japanese super-aging demographics:METI incentives for home medical device innovation align with pulmonary rehabilitation demand among elderly populations.
Industry Challenges
- Inhaler device engineering talent scarcity:Specialized aerosol physics and human factors design capabilities concentrate among limited contract development organizations.
- CE marking clinical evidence burdens:European Medical Device Regulation requirements for nebulizer and oxygen delivery systems extend regulatory timelines and documentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Disorders Treatment Market |
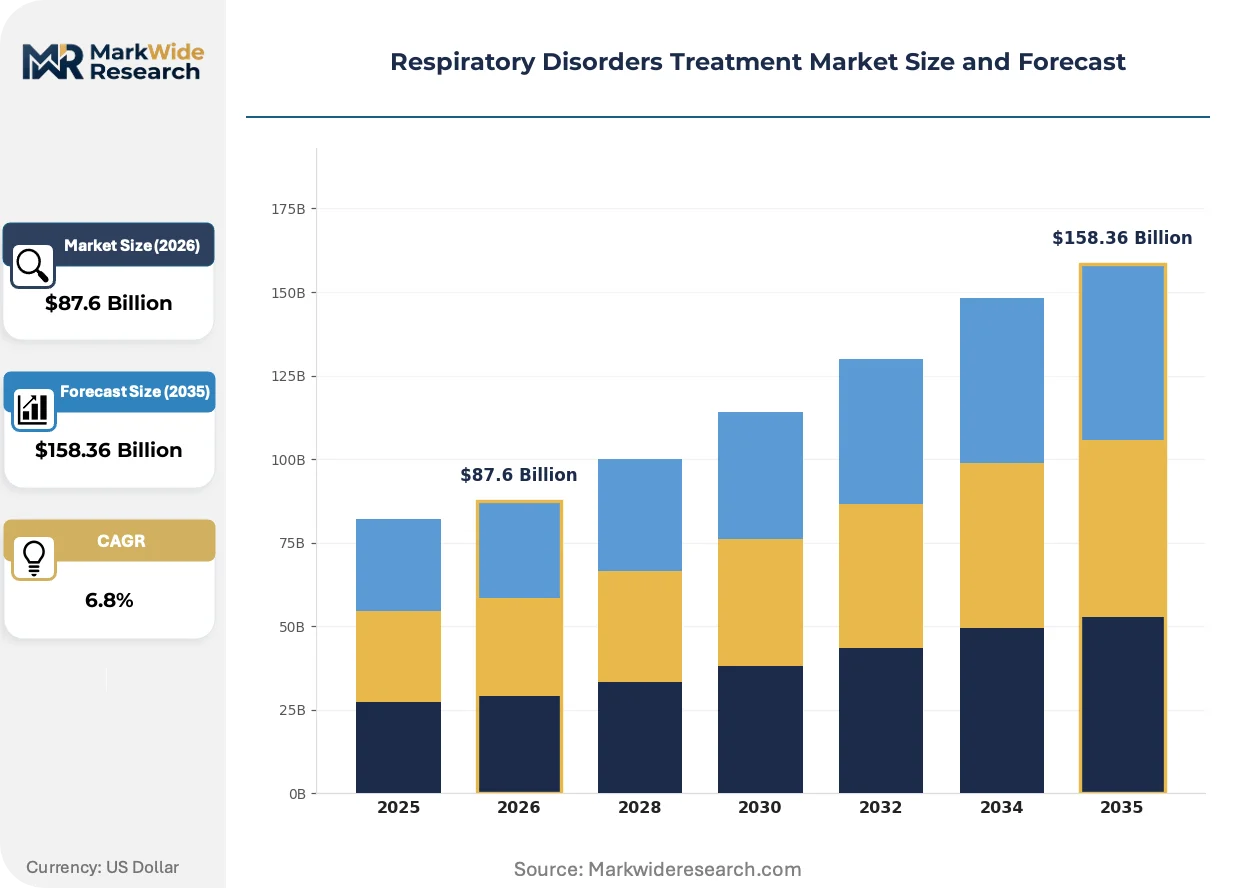
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Therapy Equipment, Vaporizers End User: Hospitals, Home Care Settings, Research Institutions, Clinics Technology: Dry Powder Inhalation, Metered Dose Inhalation, Soft Mist Inhalation, Ultrasonic Nebulization Application: Chronic Obstructive Pulmonary Disease, Asthma, Pneumonia, Cystic Fibrosis |
| Companies Covered | Novartis AG, Merck & Co., Inc., AstraZeneca plc, Teva Pharmaceutical Industries, F. Hoffmann-La Roche Ltd., Boehringer Ingelheim International GmbH, Sanofi, CHIESI Farmaceutici S.p.A., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Disorders Treatment Market Strategic Shifts
Connected inhaler ecosystems and soft mist delivery platforms are reshaping how pharmaceutical formulations reach lower respiratory tract targets, with regulatory frameworks racing to catch up to hardware capabilities.
Soft mist inhaler technology is migrating from niche pediatric and geriatric applications toward mainstream COPD maintenance therapy. Pulmonology practices in Germany and the United Kingdom are adopting these devices for patients with suboptimal hand-breath coordination. The technology is migrating from rescue medication delivery toward chronic corticosteroid administration, compressing the dominance of traditional pressurized metered-dose inhalers.
The European Union F-Gas Regulation is phasing down hydrofluoroalkane propellant quotas through 2030, forcing reformulation investments across inhaled corticosteroid portfolios. Pharmaceutical manufacturers are accelerating dry powder and alternative propellant development programs to maintain product registrations. Dry powder inhaler platforms face the steepest compliance cost increases as HFA transition timelines compress.
Hospital procurement consortia are consolidating respiratory device purchasing across integrated delivery networks, unbundling traditional manufacturer service contracts. Third-party clinical engineering firms are capturing inhaler device calibration and nebulizer maintenance volumes previously held by original equipment suppliers. This consolidation is most visible in United States metropolitan markets where health system mergers have concentrated buying power among three to five regional entities.
Respiratory Disorders Treatment Market Segmentation
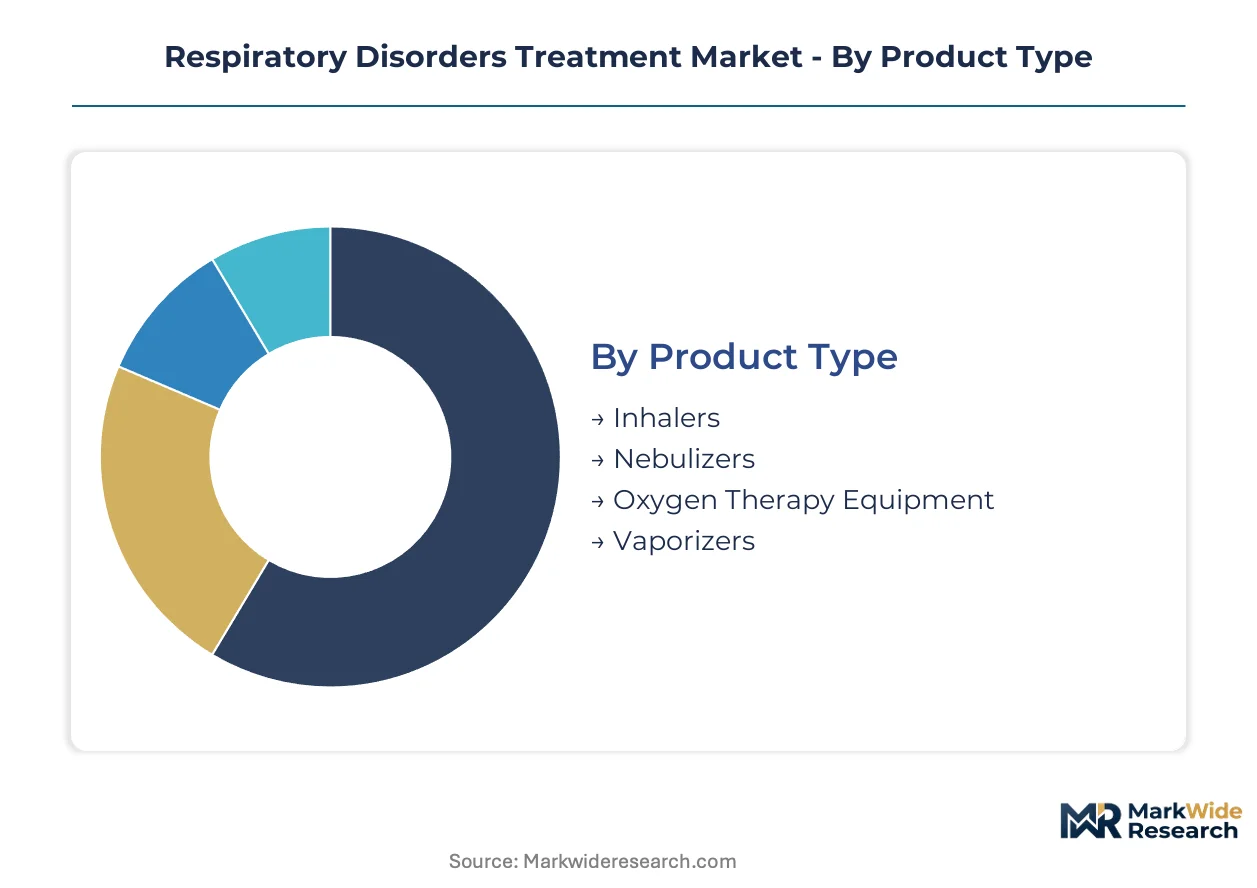
Respiratory treatment markets fragment across delivery mechanism, care setting, and disease severity. Each segmentation dimension carries distinct reimbursement codes, regulatory pathways, and service intensity requirements that reshape manufacturer margin structures.
Product Type:
After-sales service intensity varies sharply across device categories, with nebulizers requiring calibration protocols and inhalers demanding patient training support.
- Inhalers:Pressurized metered-dose and dry powder systems dominate prescription volumes through retail pharmacy channels. Hand-breath coordination requirements drive replacement cycles in the United States and Germany, where Medicare and statutory health insurance reimburse device switches.
- Nebulizers:Compressor and mesh technologies deliver bronchodilators to patients with severe airflow limitation. Home care adoption in Japan and Brazil accelerates as portable units gain reimbursement eligibility under pulmonary rehabilitation programs.
- Oxygen Therapy Equipment:Stationary concentrators and liquid oxygen systems serve hypoxemic patients. CMS competitive bidding reforms in the United States compressed rental economics while extending patient monitoring obligations.
- Vaporizers:Heated humidification devices support airway clearance in cystic fibrosis populations. Pediatric specialty clinics in France and Canada drive concentrated demand for high-output units.
By volume, Inhalers leads. By growth pace, Oxygen Therapy Equipment is ahead.
End User:
Procurement authority concentrates differently across settings, with hospital consortia wielding purchasing power while home care channels fragment across durable medical equipment suppliers.
- Hospitals:Acute care facilities manage acute exacerbations through emergency department nebulization and inpatient oxygen titration. Integrated delivery networks in Texas and California consolidate device contracts across pulmonary and critical care service lines.
- Home Care Settings:Ambulatory patients manage chronic conditions through portable concentrators and connected inhaler systems. Remote patient monitoring reimbursement codes in the United States and Germany expand service contract bundling.
- Research Institutions:Academic medical centers conduct Phase II/III trials for novel biologic formulations. CRO partnerships in Massachusetts and Basel anchor device validation studies.
- Clinics:Pulmonology and allergy practices dispense rescue inhalers and perform spirometry. Retail clinic expansion in the United Kingdom and Australia extends point-of-care prescription authority.
Hospitals capture the highest per-patient revenue. Home Care Settings expand most quickly.
Technology:
Formulation-device compatibility constraints limit technology substitution, with biologic macromolecules demanding specific aerosol engineering approaches.
- Dry Powder Inhalation:Breath-actuated systems eliminate propellant dependence. Powder engineering challenges around moisture sensitivity and dose uniformity concentrate manufacturing expertise among Swiss and German suppliers.
- Metered Dose Inhalation:Hydrofluoroalkane propellant systems retain dominance in rescue medication delivery. EU F-Gas Regulation phase-down timelines force reformulation investments across corticosteroid portfolios.
- Soft Mist Inhalation:Mechanical energy generates slow-moving aerosol clouds suitable for geriatric and pediatric populations. Adoption in German and United Kingdom pulmonology practices migrates from niche toward mainstream COPD maintenance.
- Ultrasonic Nebulization:High-frequency vibration produces fine droplets for deep lung deposition. Heat sensitivity limits application with protein-based therapies.
Metered Dose Inhalation retains volume leadership. Soft Mist Inhalation shows the steepest expansion trajectory.
Application:
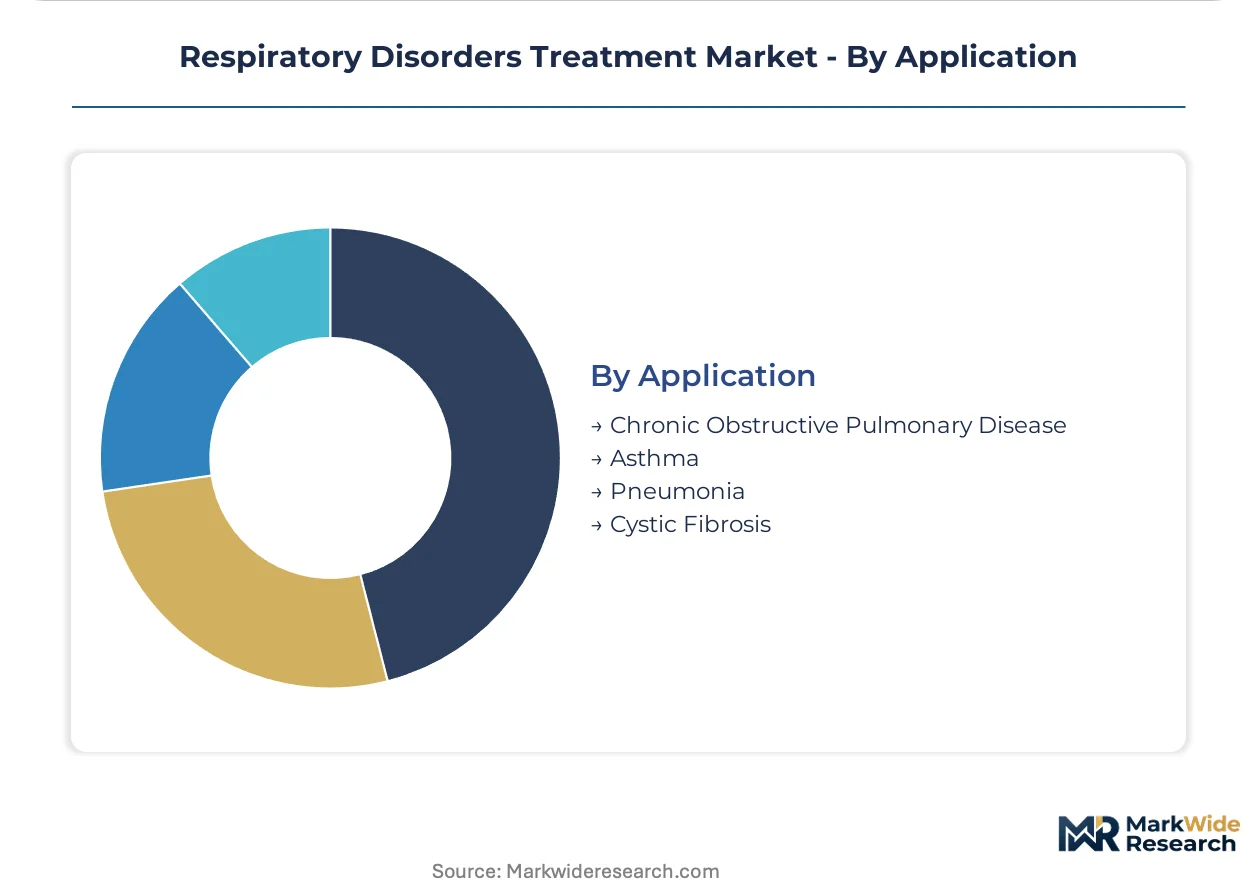
Disease prevalence and therapy pricing power diverge across indications, with rare conditions commanding premium biologic access despite smaller addressable populations.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation generates the largest patient pool and steadiest reimbursement flows. Triple therapy inhaler adoption in the United States and Japan compresses monotherapy market share.
- Asthma:Inflammatory airway disease spans intermittent to severe persistent phenotypes. Biologic eligibility criteria in European markets restrict anti-IgE and anti-IL5 access to specialist-confirmed eosinophilic subtypes.
- Pneumonia:Infectious lung inflammation drives acute nebulizer and oxygen utilization. Antimicrobial stewardship protocols in French and Italian hospitals constrain empiric bronchodilator co-prescription.
- Cystic Fibrosis:Genetic mucociliary dysfunction demands specialized nebulizer and airway clearance regimens. Vertex Pharmaceuticals' modulator therapies in the United States and United Kingdom extend survival while shifting treatment focus toward maintenance device optimization.
Chronic Obstructive Pulmonary Disease leads by patient volume. Cystic Fibrosis gains share fastest through biologic premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany demonstrate the lowest price elasticity for advanced biologic therapies, while patients in Brazil and India face steep out-of-pocket barriers that compress demand for premium inhaler formulations.
United States
Medicare competitive bidding reforms for home oxygen equipment and nebulizer rentals are accelerating patient migration toward ambulatory channels. The FDA's Center for Drug Evaluation and Research maintains stringent bioequivalence standards for generic inhaled products, preserving branded pricing power for complex corticosteroid combinations. Hospital procurement consortia in Texas and California are consolidating respiratory device contracts across integrated delivery networks, compressing manufacturer margins through volume aggregation.
Germany
Statutory health insurance reimbursement for soft mist inhalers and triple-therapy combinations sustains steady prescription volumes among COPD populations. The EU F-Gas Regulation phase-down timeline through 2030 is forcing pharmaceutical manufacturers to accelerate dry powder and alternative propellant development programs. Pulmonology practices in Bavaria and North Rhine-Westphalia are adopting connected inhaler ecosystems with Bluetooth dose tracking, enabling remote monitoring reimbursement under digital health legislation.
Japan
METI incentives for home medical device innovation align with pulmonary rehabilitation demand among super-aging demographics in Tokyo and Osaka prefectures. The PMDA's Sakigake designation system accelerates approval timelines for novel respiratory biologics targeting severe eosinophilic asthma. Portable oxygen concentrator adoption is concentrating in the Kansai region, where municipal governments subsidize equipment purchases for ambulatory COPD patients.
Brazil
Rising COPD prevalence combined with limited biologic therapy access creates whitespace for tiered pricing entry across metered-dose and dry powder platforms. ANVISA's regulatory harmonization with FDA standards is streamlining import pathways for advanced nebulizer technologies. Hospital systems in São Paulo and Rio de Janeiro are expanding pulmonary care departments to manage growing asthma and chronic bronchitis caseloads from urban air quality deterioration.
India
Domestic manufacturing of hydrofluoroalkane propellants and corticosteroid active pharmaceutical ingredients concentrates supply security for regional inhaler production. CDSCO's accelerated approval pathways for orphan respiratory indications are attracting biologic therapy trials for cystic fibrosis and primary ciliary dyskinesia. Contract development organizations in Hyderabad and Ahmedabad are accumulating specialized aerosol physics capabilities to serve multinational pharmaceutical clients.
Respiratory Disorders Treatment Market Competitive Environment
Integrated pharmaceutical conglomerates and specialized respiratory device manufacturers split the market along therapy-delivery boundaries. The vendor base exhibits moderate consolidation, with the top tier controlling branded biologic portfolios and the mid-tier competing on generic formulation scale. Three archetypes dominate: vertically integrated pharma-device hybrids, standalone inhaler engineering specialists, and regional generic manufacturers. Competitive intensity centers on M&A activity targeting connected device platforms and strategic partnerships between biologic developers and aerosol delivery engineering firms.
Among the integrated pharmaceutical conglomerates, AstraZeneca plc, Boehringer Ingelheim International GmbH, and GlaxoSmithKline plc occupy positions exemplifying the pharma-device hybrid archetype. AstraZeneca leverages biologics pipeline depth across severe asthma and COPD segments. Boehringer Ingelheim sustains manufacturing scale across multiple inhaler platforms, anchoring supply security for European and Asian hospital systems. GlaxoSmithKline competes through channel control in retail pharmacy networks, particularly for rescue inhaler volumes in mature markets.
| Leading Market Players |
|---|
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Teva Pharmaceutical Industries |
| F. Hoffmann-La Roche Ltd. |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| CHIESI Farmaceutici S.p.A. |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from propellant chemical hubs into European inhaler pricing tiers, compressing margins for manufacturers without backward integration into active pharmaceutical ingredient production while amplifying price differentiation between service-bundled and bare-equipment contracts.
Pricing Analysis
After-sales service contracts spanning calibration, preventive maintenance, and patient training support now capture the majority of lifetime value in nebulizer and oxygen concentrator deployments. A three-tier pricing structure across premium, standard, and economy levels separates manufacturers with integrated digital health platforms from commodity equipment suppliers, with FDA 510(k) clearance tier and CE marking MDR compliance grade serving as the primary price differentiation drivers. Pricing pressure stems from Medicare competitive bidding reforms that compressed rental reimbursement rates for home oxygen therapy by eliminating multi-year contract premiums. Hospital procurement consortia exhibit the lowest price sensitivity due to bundled service obligations, while independent durable medical equipment suppliers face acute margin compression.
Supply Chain Analysis
Contract manufacturing concentration for dry powder inhaler devices rests with Swiss and German precision engineering specialists, while compressor nebulizer assembly clusters in China and Mexico. Hydrofluoroalkane propellant production draws from Indian and Chinese specialty chemical manufacturers, with corticosteroid active pharmaceutical ingredients similarly concentrated in Hyderabad and Ahmedabad production zones. Single-source vulnerability pervades the HFA propellant supply base as EU F-Gas Regulation quotas phase down through 2030. Distribution runs through hospital procurement consortia in Texas and California, retail pharmacy networks for rescue inhalers, and durable medical equipment suppliers for home oxygen systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device connectivity standards and reimbursement code fragmentation for remote patient monitoring create specialization niches across the respiratory treatment landscape, rewarding focused players over generalist portfolios.
For Market Incumbents: Build switching-cost moats through proprietary connected inhaler ecosystems that lock hospital systems into longitudinal patient data contracts. Consolidate manufacturing scale across dry powder and soft mist platforms to anchor supply security against emerging mesh nebulizer entrants. Acquire specialized contract development organizations in Swiss and German aerosol physics clusters to defend formulation-device integration capabilities. For New Entrants and Emerging Players: Establish a beachhead in Brazilian and Mexican COPD maintenance markets where biologic therapy penetration remains limited and ANVISA regulatory harmonization streamlines import pathways. Target portable oxygen concentrator segments in Japan's Kansai region where METI subsidies offset patient equipment costs. Deploy direct-to-pulmonologist education programs emphasizing hand-breath coordination advantages of soft mist technology over traditional pressurized metered-dose systems. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting legacy inhaler device portfolios to focus on biologic drug development. Position acquisition screening around contract development organizations accumulating specialized aerosol physics capabilities, with valuation premia justified by talent scarcity in human factors design. Watch FDA bioequivalence standard relaxation for generic inhaled products as the inflection signal that would erode branded pricing power and reshape competitive returns.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements extend timelines for nebulizer manufacturers seeking European market access. |
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate purchasing power across pulmonary service lines. |
| Software Companion Development | Bluetooth dose tracking integration with Epic and Cerner EHR systems enables remote monitoring reimbursement codes. |
| Reimbursement Strategy | Medicare competitive bidding reforms redirect patient volumes from acute settings toward home care channels. |
| Manufacturing Scale-Up | Dry powder inhaler production expansion in Swiss and German facilities addresses moisture sensitivity engineering constraints. |
Study Parameters
A standing panel of pulmonology practice administrators, hospital biomedical engineering directors, durable medical equipment procurement managers, and payer formulary specialists provided ongoing calibration against market developments across the analysis window. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA marketing authorization applications, CMS Medicare reimbursement databases, and hospital GPO contract repositories. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Scenario bracketing around EU F-Gas Regulation phase-down timelines, Medicare competitive bidding expansion scope, and FDA bioequivalence standard evolution framed projection uncertainty across the modeling period. Segmentation dimensions spanned delivery mechanism, care setting, disease severity, and regional regulatory cluster. CAGRs derived from patient population epidemiology, therapy pricing trajectories, and reimbursement code adoption curves, with portable oxygen concentrator battery chemistry advances and soft mist inhaler mechanical engineering improvements serving as specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in freight corridor costs, propellant chemical commodity prices, or statutory health insurance reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and patient migration velocity from institutional to home care settings. Cross-checking against CMS Medicare claims data and EMA marketing authorization databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market