
 Human Respiratory Syncytial Virus (RSV) Treatment Market | 2026-2036
Human Respiratory Syncytial Virus (RSV) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Human Respiratory Syncytial Virus (RSV) Treatment Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is realigning manufacturing standards for biologic RSV therapies across European supply chains. Sanofi leverages its integrated monoclonal antibody production network to secure raw material access for nirsevimab manufacturing. Pfizer anchors its competitive position through sustained R&D investment in maternal vaccine platforms. Moderna differentiates via mRNA technology leadership in pediatric infectious disease applications.
Human Respiratory Syncytial Virus treatment encompasses prophylactic and therapeutic interventions targeting a negative-sense RNA paramyxovirus that infects respiratory epithelial cells, primarily administered as intramuscular monoclonal antibodies or intramuscular/subcutaneous vaccines to prevent severe lower respiratory tract disease in infants and high-risk elderly populations. The monoclonal antibodies segment dominates current revenue pools due to extended half-life engineering enabling single-dose seasonal protection, while vaccines represent the fastest-expanding category as maternal immunization and pediatric direct-to-infant formulations advance through regulatory pathways. Delivery mode segmentation shows subcutaneous administration gaining share through prefilled syringe convenience formats that reduce hospital pharmacy preparation burden.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks shape demand by enabling earlier commercial access for breakthrough RSV biologics based on surrogate endpoint data. WHO prequalification standards influence procurement decisions across low- and middle-income country immunization programs, expanding addressable volume beyond traditional premium markets. Stakeholders must monitor evolving CMS reimbursement determinations for maternal versus infant-directed prophylaxis strategies as cost-effectiveness thresholds redefine competitive positioning.
Market Dynamics
FDA accelerated approval pathways are compressing development timelines for RSV biologics, while EMA conditional marketing authorization frameworks enable earlier commercial access across European markets. This regulatory velocity is restructuring competitive entry sequencing and investment allocation across prophylactic and therapeutic segments.
Growth Catalysts
- Neonatal intensive care demand:United States NICU admission protocols now prioritize preventive monoclonal antibody administration for high-risk infants, creating institutional pull-through for extended half-life formulations.
- WHO prequalification expansion:Low- and middle-income country immunization programs are integrating RSV prophylaxis into national schedules, unlocking volume procurement beyond traditional premium markets.
- Subcutaneous prefilled syringe engineering:Hospital pharmacy preparation burden reduction is driving format preference shifts that favor single-dose seasonal protection delivery systems.
Market Restraints
- Cold chain biologics distribution:mRNA and monoclonal antibody stability requirements impose temperature-controlled logistics costs that limit reach into resource-constrained settings.
- Single-source raw material concentration:Cell culture media and specialized bioreactor components concentrate among limited contract manufacturing organizations, creating supply vulnerability.
- CMS reimbursement determination lag:United States maternal versus infant-directed prophylaxis cost-effectiveness thresholds remain unresolved, compressing prescriber confidence in preventive investment.
Strategic Opportunities
- Elderly immunization underpenetration:Adult respiratory disease programs in Germany and Japan present expansion vectors beyond pediatric-focused development pipelines.
- EU Green Deal pharmaceutical sustainability criteria:Manufacturing standard realignment creates first-mover advantage for biologic producers with integrated renewable energy and waste reduction systems.
- Maternal vaccine platform convergence:Combination antigen approaches targeting RSV alongside tetanus and influenza are reshaping prenatal care bundling opportunities.
Industry Challenges
- Bioprocess engineering talent scarcity:Extended half-life antibody manufacturing requires specialized cell line development expertise that outpaces current training pipeline output.
- Multi-jurisdiction regulatory synchronization:Divergent surrogate endpoint acceptance between FDA and national European regulators creates submission strategy complexity and timeline misalignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Respiratory Syncytial Virus (RSV) Treatment Market |
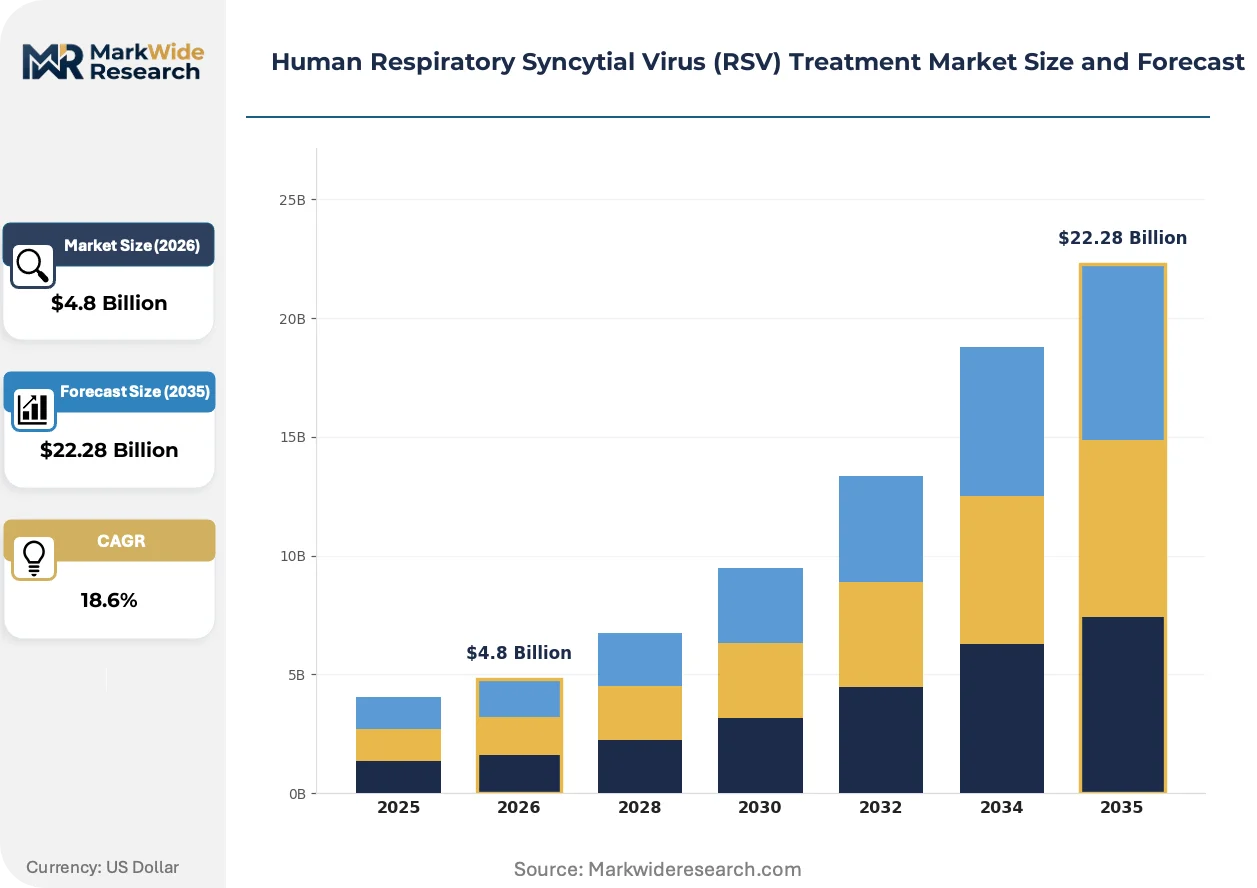
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Antiviral Medications, Vaccines, Supportive Care Delivery Mode: Intravenous, Inhalation, Oral, Subcutaneous End User: Pediatrics, Geriatrics, Hospitals, Clinics Therapy Area: Respiratory Disease, Infectious Disease, Critical Care, Immunology |
| Companies Covered | Sanofi, Pfizer, AbbVie Inc., Merck & Co., Inc., Johnson & Johnson, Swedish Orphan Biovitrum AB, GlaxoSmithKline, Moderna, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Respiratory Syncytial Virus (RSV) Treatment Market Shifts & Advancements
Extended half-life monoclonal antibody engineering is consolidating technical leadership among biologics developers, while regulatory pathway innovation and delivery format convenience are reshaping competitive differentiation vectors across preventive RSV interventions.
Extended half-life Fc-engineered antibodies are consolidating prophylactic market architecture by enabling single-dose seasonal protection that eliminates the compliance burden of monthly palivizumab injections. Pediatric hospitals in the United States are adopting these formulations at accelerating pace for NICU discharge protocols. The technology is consolidating manufacturing scale advantages around integrated production networks with captive cell culture capacity.
EMA conditional marketing authorization frameworks are enabling earlier commercial access for breakthrough RSV biologics based on surrogate endpoint data before confirmatory efficacy trials complete. This regulatory innovation compresses time-to-revenue for developers with robust immunogenicity packages. European neonatal intensive care units are responding by establishing formulary pre-approval pathways for priority biologics.
Hospital pharmacy procurement patterns are pivoting toward prefilled syringe convenience formats that reduce preparation burden and medication error risk. Subcutaneous administration training requirements are displacing intramuscular injection protocols across pediatric wards. This behavioral shift is most visible in United States academic medical centers where nursing staff efficiency metrics drive product selection criteria.
Human Respiratory Syncytial Virus (RSV) Treatment Market Segmentation
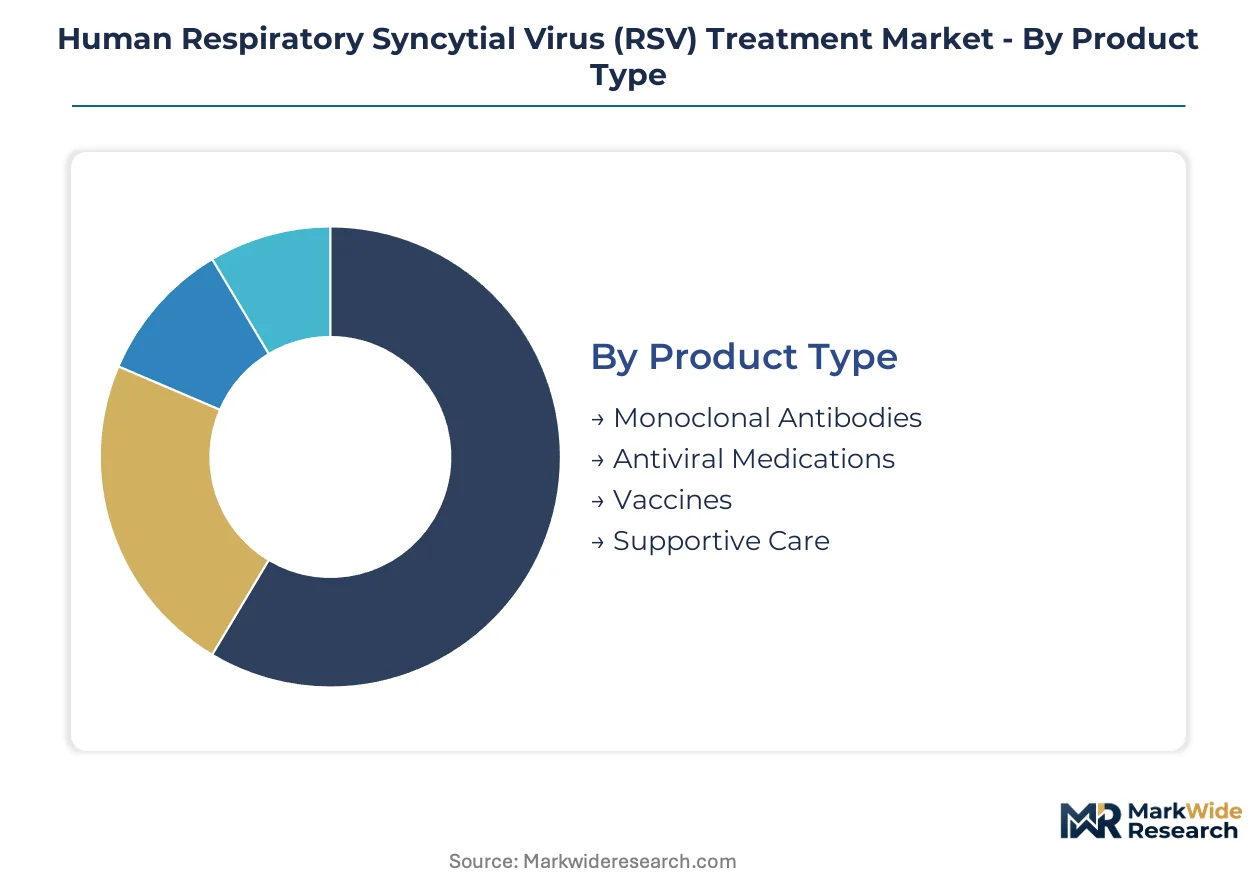
RSV treatment segmentation reveals distinct procurement patterns across prophylactic and therapeutic modalities. Hospital formulary committees evaluate products through divergent lenses: clinical efficacy for NICU protocols versus cost-effectiveness for outpatient elderly populations. Understanding these decision frameworks illuminates where manufacturers must align technical specifications with institutional purchasing criteria.
Product Type:
Hospital procurement committees weight prophylactic efficacy against total cost of care when selecting across biologic and pharmaceutical modalities.
- Monoclonal Antibodies:Fc-engineered proteins with extended half-life modifications enable single-dose seasonal protection. United States neonatal intensive care units prioritize these for high-risk infant discharge protocols, driven by compliance advantages over monthly injection regimens.
- Vaccines:Maternal immunization platforms and direct-to-infant formulations advance through FDA accelerated approval pathways. Demand concentrates in prenatal care networks seeking bundled antigen approaches, constrained by cold chain distribution requirements in resource-limited settings.
- Antiviral Medications:Small-molecule therapeutics targeting viral replication enzymes for acute infection management.
- Supportive Care:Supplemental oxygen, bronchodilators, and hydration protocols for symptom management in severe cases.
Volume sits with Monoclonal Antibodies; growth tilts toward Vaccines.
Delivery Mode:
Route selection reflects institutional workflow optimization and patient population compliance constraints.
- Subcutaneous:Prefilled syringe formats reduce hospital pharmacy preparation burden and medication error risk. United States academic medical centers favor this administration for pediatric ward efficiency metrics.
- Intravenous:Hospital-based infusion for severe hospitalized cases requiring rapid therapeutic intervention.
- Inhalation:Nebulized delivery for localized respiratory tract drug deposition in acute bronchiolitis.
- Oral:Outpatient convenience for antiviral courses in adult populations with treatment-seeking behavior.
Procurement velocity favors Subcutaneous; Intravenous retains critical care anchoring.
End User:
Patient population risk stratification determines reimbursement pathways and product positioning.
- Pediatrics:Infants under 24 months, especially premature births and congenital heart disease patients, drive prophylactic demand through NICU admission protocols.
- Geriatrics:Adults over 65 with chronic cardiopulmonary conditions represent underpenetrated expansion territory.
- Hospitals:Institutional purchasers negotiating formulary placement based on clinical outcomes data and total cost of care models.
- Clinics:Outpatient settings managing seasonal vaccination campaigns and acute case triage.
Revenue concentrates in Pediatrics; expansion opportunity centers on Geriatrics.
Therapy Area:
Clinical specialty alignment shapes prescriber education investment and key opinion leader engagement.
- Respiratory Disease:Pulmonologists and neonatologists direct lower respiratory tract disease prevention protocols.
- Infectious Disease:Specialists coordinate seasonal prophylaxis timing and outbreak response.
- Critical Care:Intensivists manage severe bronchiolitis requiring mechanical ventilation support.
- Immunology:Specialists address immune-compromised patient populations requiring modified prophylaxis strategies.
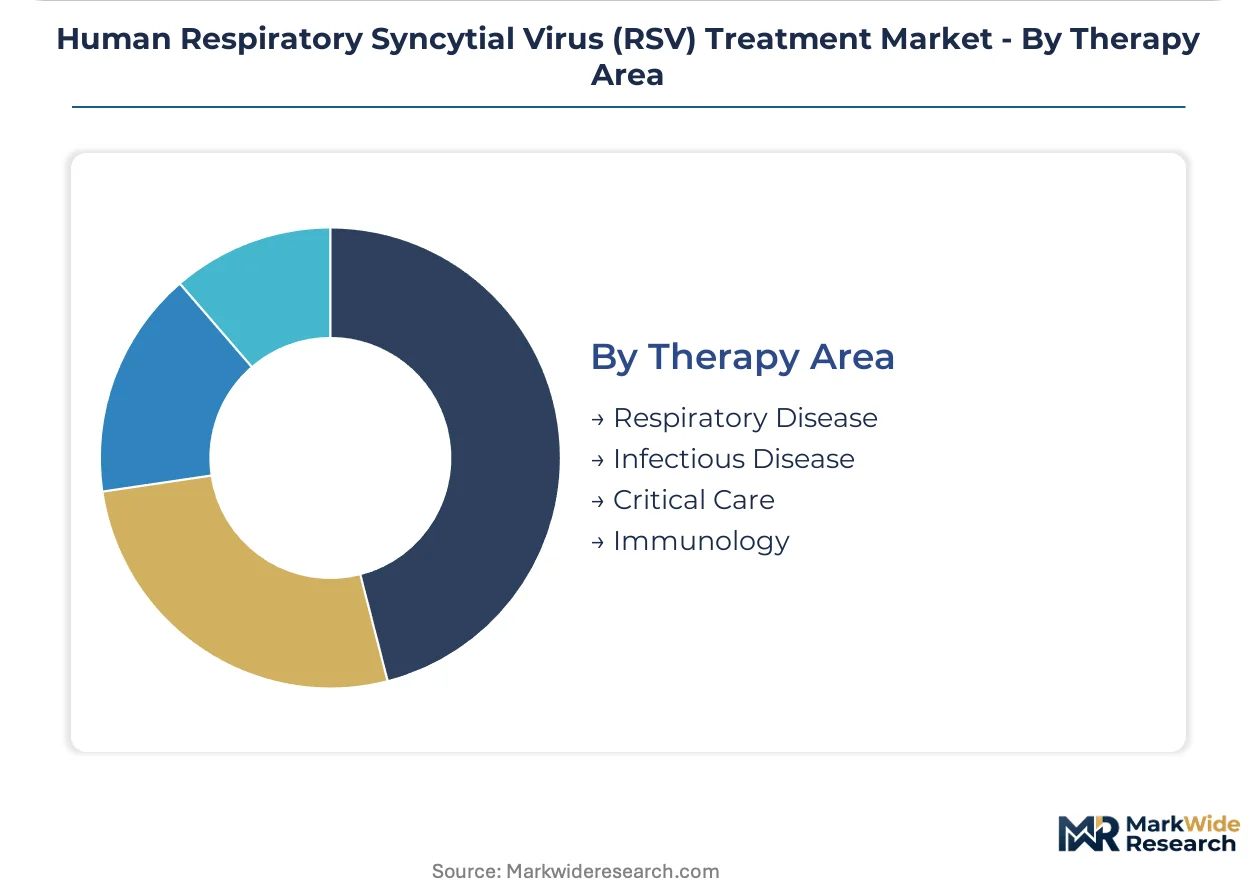
Clinical development pipelines concentrate in Respiratory Disease; cross-specialty adoption expands through Infectious Disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors RSV therapeutic development through concentrated monoclonal antibody research facilities and proximity to FDA regulatory expertise. Pediatric hospital networks across the metropolitan area pilot extended half-life formulations for neonatal discharge protocols. Manufacturing partnerships with Cambridge cell culture facilities supply clinical trial materials for Phase III programs.
United States
Neonatal intensive care units in academic medical centers drive monoclonal antibody procurement through institutional formulary committees prioritizing single-dose seasonal protection. FDA accelerated approval pathways compress commercialization timelines for breakthrough biologics targeting infant populations. Research Triangle Park biomanufacturing clusters expand cell culture capacity to support extended half-life antibody production.
Germany
Pediatric pulmonology departments in university hospitals coordinate seasonal prophylaxis timing with infectious disease specialists across Bavaria and North Rhine-Westphalia. EMA conditional marketing authorization frameworks enable earlier patient access based on surrogate immunogenicity endpoints. Frankfurt Rhine-Main logistics hubs specialize in cold chain distribution for temperature-sensitive biologics.
Japan
Geriatric respiratory programs in Tokyo metropolitan hospitals present expansion vectors for adult immunization platforms beyond pediatric-focused pipelines. PMDA review standards align with international harmonization initiatives for monoclonal antibody safety databases. Osaka-Kobe biopharma manufacturing zones integrate Fc-engineering capabilities into existing antibody production infrastructure.
United Kingdom
NHS England specialized commissioning frameworks negotiate value-based contracts for high-cost preventive biologics in neonatal care pathways. MHRA post-Brexit regulatory autonomy enables streamlined assessment of innovative delivery formats including prefilled syringe presentations. London-Oxford-Cambridge life sciences clusters concentrate early-phase clinical development for maternal vaccine platforms.
India
CDSCO accelerated approval pathways for essential medicines facilitate access to imported monoclonal antibodies through government procurement programs. Mumbai-Pune pharmaceutical corridors develop biosimilar manufacturing capabilities for regional supply of extended half-life formulations. National immunization technical advisory groups evaluate cost-effectiveness models for RSV prophylaxis integration into existing pediatric schedules.
Human Respiratory Syncytial Virus (RSV) Treatment Market Competitive Landscape
The competitive structure tilts toward integrated biopharmaceutical conglomerates with captive monoclonal antibody manufacturing networks. Market concentration reflects high barriers in cell line development expertise and extended half-life Fc-engineering capabilities. Two strategic archetypes dominate: diversified pharmaceutical majors leveraging vaccine platform synergies, and specialized biologics developers with concentrated infectious disease portfolios. Dominant competitive moves include strategic partnerships for raw material security and geographic expansion through WHO prequalification pathways.
Within the diversified pharmaceutical tier, Sanofi and Pfizer exemplify archetypes built on integrated production networks and sustained R&D investment in preventive platforms. Moderna occupies a position representing mRNA technology specialization in pediatric applications. These three anchors demonstrate how competitive positioning depends on manufacturing scale, regulatory navigation expertise, and platform technology differentiation rather than therapeutic modality alone.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Swedish Orphan Biovitrum AB |
| GlaxoSmithKline |
| Moderna |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up contract manufacturing organizations now control critical bioreactor capacity across the United States and Western Europe, enabling disciplined pricing power through captive supply of extended half-life antibody production while extracting margin premiums from developers lacking in-house Fc-engineering expertise.
Pricing Analysis
Value-based pricing anchored to RSV hospitalization prevention outcomes dominates United States neonatal intensive care procurement, with formulary committees weighting total cost of care against clinical efficacy endpoints. Three-tier pricing structure across premium extended half-life monoclonal antibodies, standard maternal vaccine platforms, and economy-tier supportive care protocols reflects differentiation by clinical outcome certainty and administration convenience. Pricing pressure stems from CMS reimbursement determination lag between maternal versus infant-directed prophylaxis strategies, compressing prescriber confidence and procurement velocity. Pediatric hospital networks exhibit lowest price sensitivity due to institutional protocols prioritizing single-dose compliance, while outpatient clinics face acute budget constraints for seasonal vaccination campaigns.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States pediatric hospital procurement committees are reshaping supplier qualification protocols for cell culture media and specialized bioreactor components. Manufacturing gravity centers on the United States, Germany, and Japan, with Boston-Cambridge and Research Triangle Park clusters anchoring North American extended half-life antibody production. Raw material dependencies concentrate on Chinese-sourced recombinant proteins, German-engineered chromatography resins, and Japanese bioreactor equipment. Single-source vulnerability in Fc-engineering cell line development expertise creates supply interruption risk during capacity expansion cycles. Distribution runs through temperature-controlled logistics networks with Frankfurt Rhine-Main and Memphis hubs specializing in cold chain biologics handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioprocess engineering talent scarcity and regulatory pathway complexity are forcing consolidation among developers lacking integrated manufacturing networks, positioning well-capitalized incumbents to acquire distressed pipeline assets.
For Market Incumbents: Lock in raw material security through backward integration into cell culture media production or long-term offtake agreements with qualified contract manufacturing organizations. Prioritize EMA conditional marketing authorization submissions to compress European commercialization timelines ahead of competitors dependent on full confirmatory trial completion. Defend against mRNA platform substitution threats by accelerating Fc-engineering iterations that extend protection duration beyond seasonal windows. For New Entrants and Emerging Players: Hospital pharmacy outsourcing specialists represent the most accessible channel partnership for prefilled syringe format introduction without direct formulary committee engagement. White-space opportunities concentrate on geriatric respiratory programs in Japan and Germany where adult immunization platforms remain underpenetrated relative to pediatric-focused pipelines. Target maternal vaccine platform convergence through combination antigen approaches bundling RSV with tetanus and influenza to capture prenatal care network procurement. For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization rate is the leading indicator that manufacturing scale advantages are crystallizing around integrated biopharmaceutical conglomerates rather than specialized infectious disease developers. Five-to-ten year viability favors acquirers of distressed pipeline assets with robust immunogenicity packages but lacking captive production capacity. Monitor WHO prequalification submission timing as the critical inflection signal for volume expansion into low- and middle-income country procurement programs.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA conditional marketing authorization compresses European commercialization timelines for breakthrough biologics. |
| Manufacturing Scale-Up | Research Triangle Park biomanufacturing clusters expand cell culture capacity for extended half-life antibody production. |
| Backward Integration | Captive supply of cell culture media reduces single-source vulnerability in Fc-engineering manufacturing. |
| Hospital System Partnership | United States academic medical center formulary pre-approval pathways secure institutional procurement commitment. |
| Reimbursement Strategy | CMS maternal versus infant-directed prophylaxis determination shapes prescriber confidence in preventive investment. |
Research Methodology
Independent corroboration across formulary directors at United States academic medical centers, regulatory affairs leads at EMA-submission-stage developers, and payer access specialists at national immunization programs underwrites the qualitative findings. Primary interviews with hospital procurement managers, neonatologists, and infectious disease specialists were validated against FDA filings, EMA assessment reports, ClinicalTrials.gov entries, and WHO prequalification documentation. Bottom-up patient population modeling and top-down revenue triangulation across product type and delivery mode segments anchored the quantitative framework.
Rate-of-change decomposition across the projection horizon isolates volume expansion from price evolution within each modeled segment. Segmentation dimensions include prophylactic versus therapeutic modality, monoclonal antibody versus vaccine platform, subcutaneous versus intramuscular administration route, and pediatric versus geriatric patient population. CAGRs were derived from regression analysis against historical biologics launch curves adjusted for regulatory pathway velocity and reimbursement determination timing. Forecast inputs incorporate cold chain distribution cost trajectories and cell culture capacity expansion announcements.
Caveats apply where CMS reimbursement determination resolution or EMA conditional marketing authorization withdrawal could materially shift the outlook. Forecasts reflect assumptions regarding sustained FDA accelerated approval pathway utilization and WHO prequalification expansion pace. Deviation in bioprocess engineering talent pipeline output or single-source raw material supply interruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Respiratory Inhaler Market