
 Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market | 2026-2036
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market Foresight
Modular ventilator configurations is decoupling hardware from software service tiers, letting buyers customize support packages without full-system replacement. Medtronic plc leverages its integrated critical care portfolio to anchor hospital contracts across North American and European accounts. Pfizer Inc. competes through inflammation-reduction drug pipelines targeting ARDS-specific pathways. Faron Pharmaceuticals Oy differentiates via specialized immunomodulation therapies in late-stage development.
Acute Respiratory Distress Syndrome treatment encompasses mechanical, pharmacological, and extracorporeal interventions designed to restore oxygenation in patients with diffuse alveolar damage and refractory hypoxemia, typically requiring positive end-expiratory pressure above 5 cm H2O and fraction of inspired oxygen exceeding 0.40. Mechanical ventilators dominate current revenue as established infrastructure, while extracorporeal membrane oxygenation represents the fastest-expanding segment as centers build ECMO capability for salvage therapy. Inhaled nitric oxide commands premium positioning in pulmonary clinics for selective vasodilation, and surfactants occupy a niche in neonatal and pediatric intensive care where endogenous deficiency drives pathophysiology.
The FDA maintains stringent premarket review for novel respiratory devices, while the EMA's Medical Device Regulation tightens clinical evidence requirements for ECMO and ventilator systems entering European markets. Japan's PMDA accelerates priority review for ARDS therapies addressing unmet critical care needs, creating differentiated access timelines across major jurisdictions. Stakeholders must monitor how reimbursement frameworks for invasive versus non-invasive delivery modes evolve as health systems weigh cost against mortality outcomes.
Market Dynamics
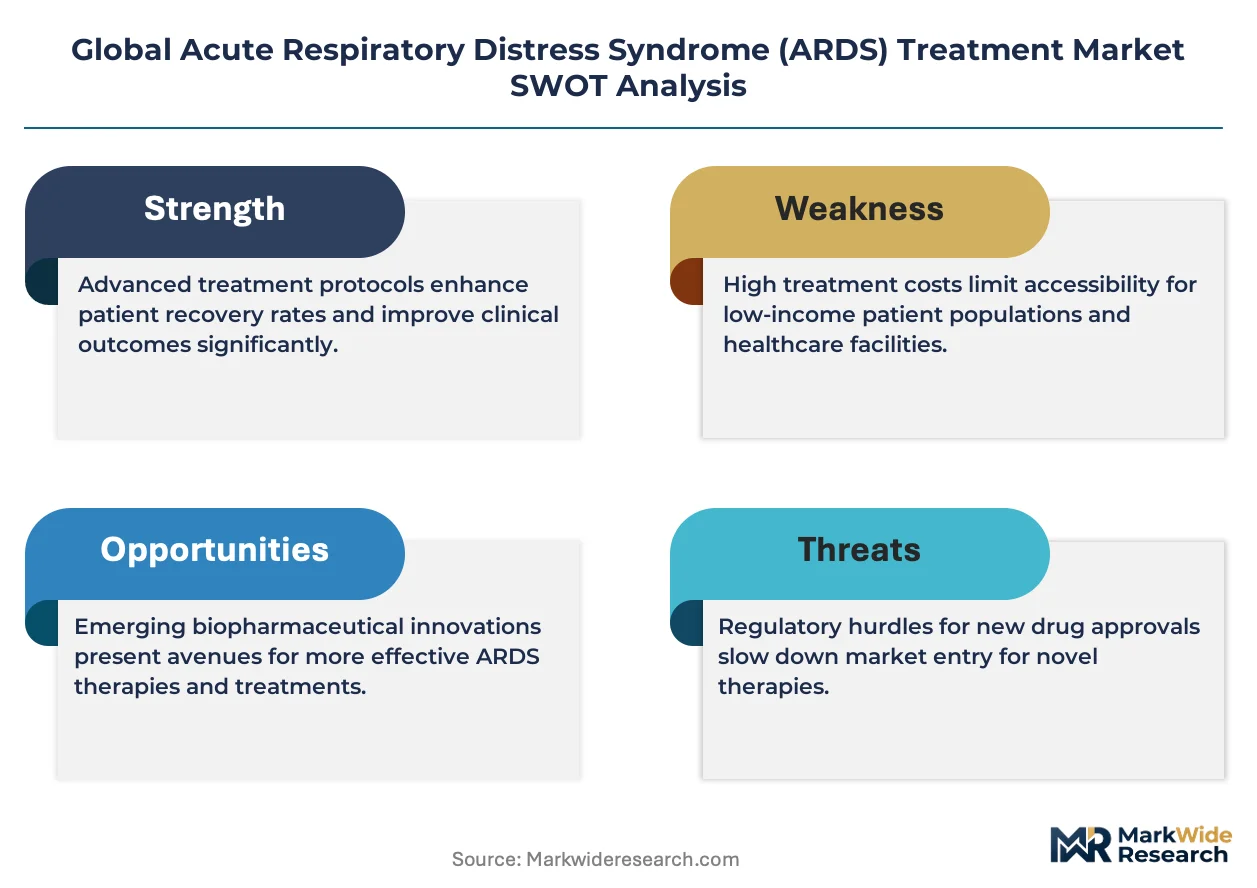
Mechanical ventilation hardware is decoupling from software service tiers, forcing manufacturers to defend recurring revenue streams against modular competitors while ICU procurement teams demand flexible upgrade paths without full-system replacement.
Growth Catalysts
- EMA Medical Device Regulation:Tightened clinical evidence requirements for ECMO and ventilator systems are accelerating consolidation among manufacturers with robust trial portfolios, favoring established critical care portfolios.
- Pediatric intensive care units:Surfactant therapy protocols for neonatal respiratory distress are expanding into broader premature infant populations, creating protocol-driven demand for specialized formulations.
- Japan's PMDA priority review:Accelerated pathways for ARDS therapies addressing unmet critical care needs are compressing development timelines for immunomodulation candidates targeting salvage therapy populations.
Market Restraints
- Silicon membrane supply concentration:ECMO oxygenator manufacturing depends on specialized biocompatible membrane suppliers concentrated in Germany and Japan, exposing procurement to single-source vulnerabilities.
- FDA premarket review timelines:Novel respiratory devices face 12-18 month clearance cycles for 510(k) pathways and 24-36 months for PMA, delaying revenue realization for breakthrough ventilation modes.
- Non-invasive ventilation substitution:High-flow nasal cannula systems are capturing mild-to-moderate hypoxemia cases previously routed to mechanical ventilation, compressing addressable volume for invasive device manufacturers.
Strategic Opportunities
- India's critical care infrastructure expansion:Government hospital networks are scaling ICU bed capacity in tier-2 cities, creating first-mover advantage for ventilator manufacturers offering localized service networks and rupee-denominated pricing.
- Hybrid ECMO-CRRT convergence:Integrated platforms combining extracorporeal membrane oxygenation with continuous renal replacement therapy are reducing circuit complexity and nursing burden in multi-organ failure protocols.
- Japan's aging demographics:Pneumonia-associated ARDS incidence in patients over 75 is driving demand for lung-protective ventilation strategies and specialized weaning protocols in geriatric-focused hospitals.
Industry Challenges
- ECMO specialist workforce scarcity:Perfusionist and critical care physician training programs produce insufficient operators for expanding center capability, creating bottlenecks at tertiary referral hospitals.
- Legacy ventilator fleet interoperability:Hospital networks face integration friction when connecting 1990s-era hardware to modern electronic health record systems and remote monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market |
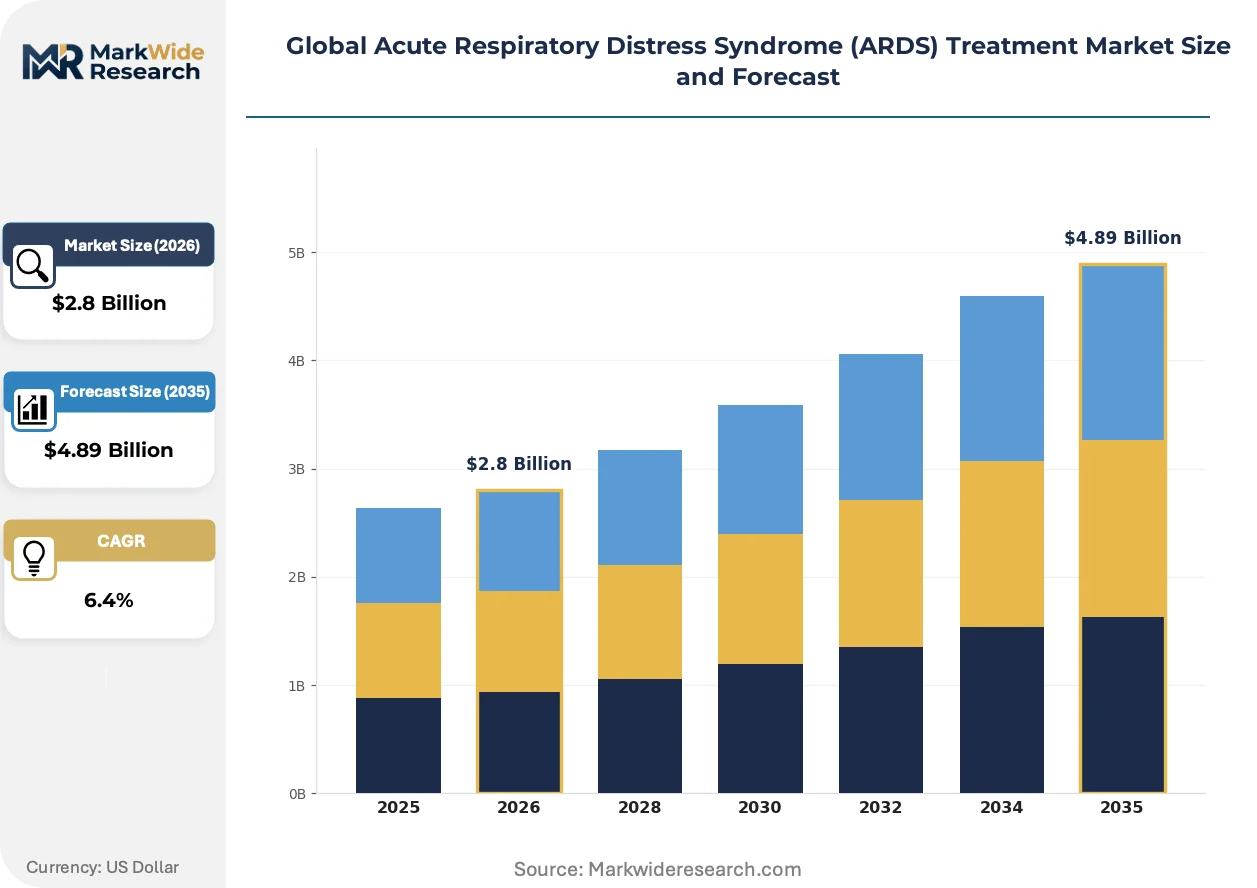
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Ventilators, Extracorporeal Membrane Oxygenation, Inhaled Nitric Oxide, Corticosteroids, Surfactants Therapy Area: Pulmonary Support, Immunomodulation, Inflammation Reduction, Fluid Management, Oxygenation Enhancement End User: Intensive Care Units, Pulmonary Clinics, Emergency Departments, Specialized Respiratory Centers, Rehabilitation Facilities Delivery Mode: Inhalation Therapy, Intravenous Injection, Oral Medication, Non-invasive Ventilation, Invasive Ventilation |
| Companies Covered | Novartis AG, Medtronic plc, Pfizer Inc., Faron Pharmaceuticals Oy, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Boehringer Ingelheim International GmbH, Athersys Inc., Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market Shifts & Advancements
Adaptive ventilation algorithms are displacing fixed-parameter protocols across intensive care units, with machine learning models analyzing real-time respiratory mechanics to automate titration decisions previously requiring manual intervention.
Neurally adjusted ventilatory assist is electrifying patient-ventilator synchrony by capturing diaphragmatic electrical signals through specialized esophageal catheters. Academic medical centers in Germany and the United States are adopting this technology for difficult-to-wean populations. The approach is compressing mechanical ventilation duration and reducing sedation requirements in prolonged ARDS recovery.
REACH authorization requirements for persistent organic pollutants are tightening material specifications for circuit components and disposable sets used in extracorporeal systems. Manufacturers are reformulating polymers and adhesive chemistries to maintain biocompatibility while eliminating restricted substances. European ECMO device suppliers are absorbing compliance costs into premium positioning rather than economy-tier offerings.
Hospital procurement teams are unbundling ventilator hardware from preventive maintenance contracts, negotiating separate service agreements with third-party clinical engineering firms or in-house biomed departments. Original equipment manufacturers are responding with subscription-based software licensing for advanced ventilation modes. This pattern is most visible in United States health systems where capital budget constraints favor operating expenditure models.
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market Segmentation
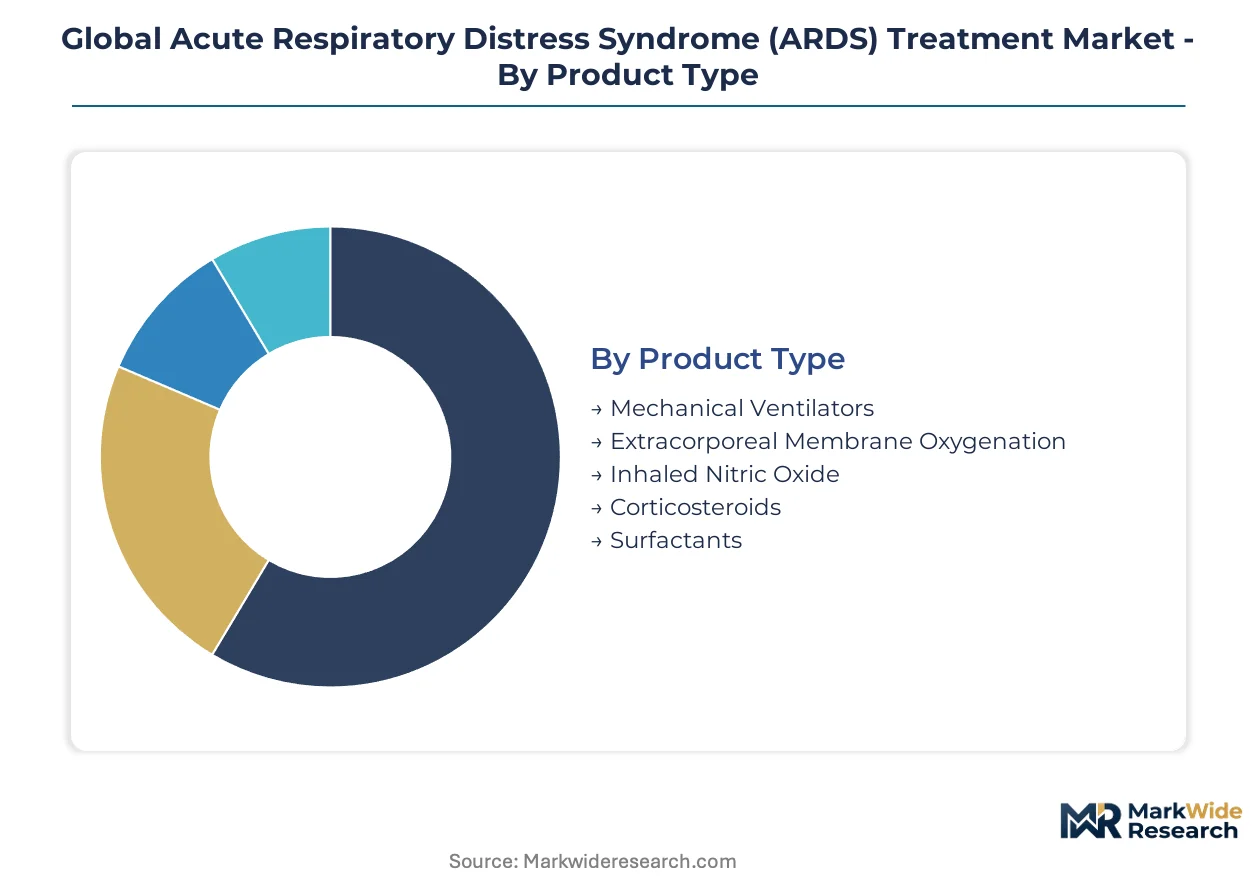
ARDS treatment modalities span device, pharmaceutical, and procedural categories with divergent margin profiles and regulatory pathways. Procurement patterns fragment across capital-intensive hardware, consumable-driven drug protocols, and hybrid service models. Understanding segment boundaries clarifies where manufacturers compete on technology versus price versus clinical evidence depth.
Product Type:
Mechanical specification and oxygenation performance define competitive positioning across hardware and pharmaceutical segments.
- Mechanical Ventilators:Positive-pressure systems delivering controlled tidal volumes with PEEP modulation above 5 cm H₂O. Intensive care units in the United States and Germany anchor procurement volume as these countries expand tertiary critical care infrastructure. Hospital procurement teams now unbundle hardware from software service tiers, pressuring original equipment manufacturers to defend recurring revenue through subscription licensing for advanced ventilation modes.
- Extracorporeal Membrane Oxygenation:Extracorporeal circuits providing gas exchange through specialized biocompatible membranes when refractory hypoxemia exceeds ventilator salvage capacity. Academic medical centers in Japan and Germany are building ECMO capability for multi-organ failure protocols, though perfusionist workforce scarcity constrains center expansion. Silicon membrane supply concentration in Germany and Japan exposes procurement to single-source vulnerabilities.
- Inhaled Nitric Oxide:Selective pulmonary vasodilator delivered via specialized delivery systems for acute hypoxic respiratory failure.
- Corticosteroids:Systemic anti-inflammatory agents modulating alveolar-capillary membrane permeability in early-phase ARDS.
- Surfactants:Phospholipid-protein formulations replacing endogenous deficiency in neonatal and pediatric respiratory distress.
Mechanical ventilators lead on scale; extracorporeal membrane oxygenation leads on momentum.
Therapy Area:
Clinical objective determines reimbursement coding and evidence requirements across intervention categories.
- Pulmonary Support:Mechanical and pharmacological interventions targeting alveolar recruitment and ventilation-perfusion matching. Emergency departments and intensive care units drive demand concentration as first-line intervention sites for acute decompensation.
- Immunomodulation:Targeted biologics and small molecules interrupting dysregulated inflammatory cascades in diffuse alveolar damage. Japan's PMDA priority review pathways compress development timelines for late-stage candidates addressing salvage therapy populations.
- Inflammation Reduction:Broad-spectrum anti-inflammatory protocols including corticosteroid timing optimization.
- Fluid Management:Conservative versus liberal fluid strategies in septic and non-septic ARDS phenotypes.
- Oxygenation Enhancement:Adjunctive therapies including prone positioning and inhaled vasodilator protocols.
Pulmonary support commands installed base; immunomodulation attracts development investment.
End User:
Care setting acuity shapes device specification, staffing requirements, and reimbursement intensity.
- Intensive Care Units:Tertiary facilities with 24-hour intensivist coverage managing invasive ventilation and vasoactive support. India's government hospital networks are scaling ICU bed capacity in tier-2 cities, creating first-mover advantage for manufacturers offering localized service networks.
- Pulmonary Clinics:Subspecialty centers managing weaning protocols and long-term respiratory rehabilitation. Germany's dense network of pneumology-focused hospitals drives adoption of neurally adjusted ventilatory assist for difficult-to-wean populations.
- Emergency Departments:Frontline stabilization sites initiating non-invasive ventilation and triage decisions.
- Specialized Respiratory Centers:Dedicated ECMO referral hubs concentrating salvage therapy expertise.
- Rehabilitation Facilities:Post-acute settings managing ventilator liberation and functional recovery.
Intensive care units absorb capital expenditure; pulmonary clinics extend procedure volume.
Delivery Mode:
Invasiveness gradient determines patient selection, complication profile, and reimbursement tier.
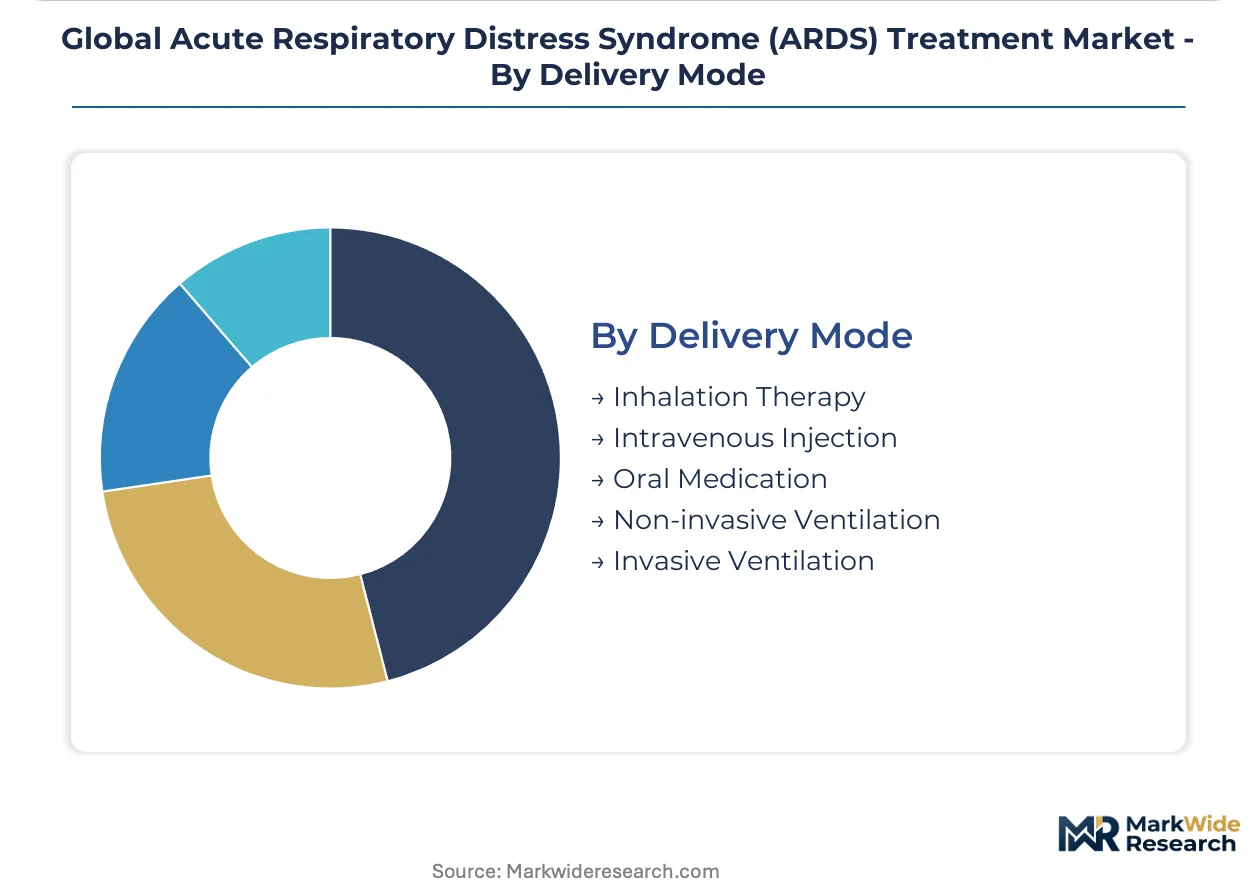
- Invasive Ventilation:Endotracheal intubation with positive-pressure delivery for refractory hypoxemia requiring FiO₂ exceeding 0.40. High-flow nasal cannula systems are capturing mild-to-moderate cases previously routed to mechanical ventilation, compressing addressable volume for device manufacturers.
- Non-invasive Ventilation:Mask-delivered positive pressure avoiding intubation in selected hypoxemic respiratory failure. Japan's aging demographics drive demand for lung-protective strategies and specialized weaning protocols in geriatric-focused hospitals.
- Inhalation Therapy:Aerosolized drug delivery targeting pulmonary vasculature and alveolar surfaces.
- Intravenous Injection:Systemic pharmacokinetics for immunomodulation and sedation protocols.
- Oral Medication:Maintenance and prophylactic dosing in subacute and recovery phases.
Invasive ventilation retains revenue concentration; non-invasive ventilation expands access breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechanical ventilation technology first achieved clinical scale in the United States during the polio epidemics of the 1950s, establishing the country as the foundational market for critical care respiratory devices. Subsequent development of ECMO systems in Germany and Japan during the 1970s-1980s created the current tripolar distribution of advanced pulmonary support manufacturing and clinical expertise.
United States
Academic medical centers in Boston and Baltimore drive ECMO protocol innovation for salvage therapy populations. The FDA maintains 12-18 month 510(k) clearance cycles for novel ventilation modes, compressing revenue timelines for device innovators. Hospital procurement teams in the Southeast and Midwest are unbundling hardware from service contracts, favoring subscription-based software licensing.
Germany
Silicon membrane suppliers in Baden-Württemberg and Bavaria anchor ECMO oxygenator manufacturing for global markets. The EMA's Medical Device Regulation tightens clinical evidence requirements for ventilator systems entering European markets, favoring manufacturers with robust trial portfolios. Pneumology-focused hospitals in North Rhine-Westphalia adopt neurally adjusted ventilatory assist for difficult-to-wean populations.
Japan
Pneumonia-associated ARDS incidence in patients over 75 drives demand for lung-protective ventilation strategies in geriatric-focused hospitals. The PMDA accelerates priority review for ARDS therapies addressing unmet critical care needs, compressing development timelines for immunomodulation candidates. Tokyo and Osaka medical centers concentrate perfusionist training programs for expanding ECMO capability.
India
Government hospital networks scale ICU bed capacity in tier-2 cities across Maharashtra and Karnataka, creating first-mover advantage for ventilator manufacturers offering localized service networks. The CDSCO regulates medical device imports while domestic production incentives under PLI schemes attract assembly operations. Delhi-NCR and Chennai clusters absorb capital expenditure for pulmonary support infrastructure expansion.
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology licensing and clinical evidence depth, with integrated critical care portfolios commanding contract anchoring power against modular competitors. The vendor base fragments between diversified pharmaceutical conglomerates and specialized device manufacturers, with ECMO oxygenator supply concentrating around membrane chemistry specialists. Three archetypes dominate: diversified medtech conglomerates with installed base leverage, inflammation-targeting pharmaceutical developers with late-stage pipelines, and immunomodulation specialists pursuing salvage therapy indications. Consolidation accelerates through strategic partnerships for hybrid ECMO-CRRT platforms and geographic licensing agreements for emerging market access.
Within the diversified medtech tier, Medtronic plc and Johnson & Johnson Services Inc. occupy positions anchored by integrated critical care portfolios spanning ventilation hardware and disposables. Pfizer Inc. and Novartis AG exemplify pharmaceutical archetypes competing through inflammation-reduction drug pipelines targeting ARDS-specific pathways. Faron Pharmaceuticals Oy represents the specialized immunomodulation developer archetype, pursuing differentiated positioning via late-stage candidates for refractory patient populations.
| Leading Market Players |
|---|
| Novartis AG |
| Medtronic plc |
| Pfizer Inc. |
| Faron Pharmaceuticals Oy |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Boehringer Ingelheim International GmbH |
| Athersys Inc. |
| Johnson & Johnson Services Inc. |
| Others |
Supply & Pricing Matrix
Silicon membrane chemistry costs cascade from Baden-Württemberg and Bavaria manufacturing clusters through ECMO oxygenator assembly tiers, compressing margins at standard-grade suppliers while premium membrane specialists capture pricing power through FDA and CE dual-certification positioning.
Pricing Analysis
Subscription-based software licensing for advanced ventilation modes now anchors revenue models across North American health systems. Price differentiation separates FDA-cleared premium systems from CE-marked standard configurations and economy-tier Asian imports without regulatory dual-approval. Cost compression in invasive ventilation hardware intensifies as high-flow nasal cannula systems substitute mild-to-moderate cases. Hospital procurement committees in India's tier-2 cities exhibit highest price sensitivity; academic medical centers in Boston and Tokyo demonstrate lowest sensitivity due to bundled service requirements.
Supply Chain Analysis
Regional distribution centers in Chicago, Frankfurt, and Osaka operate hub-and-spoke patterns for ventilator consumables and ECMO circuit components. Manufacturing concentrates in Germany for silicon membrane oxygenators, the United States for adaptive ventilation firmware, and Japan for neurally adjusted ventilatory assist catheters. Supply chain risk centers on single-source silicon membrane suppliers concentrated in Baden-Württemberg. Distribution runs through hospital GPO contracts and government procurement frameworks with localized service network requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as salvage therapy demand shifts toward lung-protective ventilation specifications and immunomodulation protocols requiring specialized clinical evidence depth.
For Market Incumbents: Deepen backward integration into silicon membrane supply through captive partnerships with Baden-Württemberg chemistry specialists, insulating against single-source vulnerability while defending service revenue against modular competitors unbundling hardware from software tiers. Expand perfusionist training program sponsorship in Tokyo and Osaka to relieve ECMO specialist workforce scarcity constraining center expansion. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer lowest-friction entry into India's tier-2 ICU infrastructure expansion, bypassing established GPO relationships. Target hybrid ECMO-CRRT convergence platforms for multi-organ failure protocols in academic medical centers, where nursing burden reduction commands premium positioning absent from pure-play ventilation hardware. For Investors and Strategic Acquirers: Consolidation pressure builds where immunomodulation pipelines require critical care commercial infrastructure absent from specialized biotech developers. Five-to-ten year viability favors diversified medtech conglomerates with installed base leverage over pure-play pharmaceutical developers facing pulmonary support device commoditization. Watch FDA breakthrough device designation velocity as inflection indicator for revenue timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Long-term GPO contracts in the United States lock out modular competitors through bundled service tiers. |
| FDA Submission | Premarket approval pathways for adaptive ventilation algorithms compress development timelines against 510(k) clearance cycles. |
| Software Companion Development | Machine learning titration modules differentiate premium ventilator configurations from fixed-parameter economy systems. |
| Reimbursement Strategy | CMS coding for neurally adjusted ventilatory assist in difficult-to-wean populations expands addressable procedure volume. |
| CE Marking Pathway | EMA Medical Device Regulation compliance for ECMO systems favors manufacturers with robust European trial portfolios. |
Research Methodology
Direct dialogue with intensivists, perfusionists, hospital procurement managers, and biomedical engineers grounded qualitative findings, cross-referenced against FDA 510(k) and PMA filings, EMA Medical Device Regulation guidance documents, Japan PMDA priority review designations, and hospital GPO contract databases. Bottom-up demand modeling triangulated with top-down market sizing across mechanical ventilation, ECMO, and pharmacological intervention categories.
Segment-level value outputs combined installed base analysis with replacement cycle assumptions across the projection horizon. Treatment modality, delivery mode invasiveness, end-user acuity, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from procedure volume trajectories, device shipment data, and drug protocol adoption curves in tertiary critical care settings.
Regulatory approval delays, silicon membrane supply disruption, and non-invasive ventilation substitution are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market