
 Global Dyspnea Treatment Market | 2026-2036
Global Dyspnea Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dyspnea Treatment Market Foresight
Pulmonologist workforce shortages in rural health systems is unwinding access to specialized dyspnea care across multiple continents. GlaxoSmithKline plc leverages its inhaled corticosteroid portfolio to anchor chronic obstructive pulmonary disease therapy lines. Teva Pharmaceutical Industries Ltd sustains competitive pressure through its generic bronchodilator manufacturing scale.
Dyspnea treatment encompasses pharmacological and mechanical interventions that restore adequate gas exchange by dilating airways, reducing pulmonary edema, or supplementing oxygen delivery. Inhalation delivery systems for bronchodilators require particle size distributions between one and five microns to achieve optimal alveolar deposition. Bronchodilators occupy the largest revenue share due to their first-line status across asthma and COPD protocols. Oxygen therapy devices represent the fastest-expanding segment as portable concentrator technology enables homecare migration from institutional settings.
The FDA maintains stringent bioequivalence standards for generic inhaled products through its draft guidance on orally inhaled and nasal drug products. EMA's MDR framework imposes clinical performance verification on oxygen delivery systems marketed across European Union member states. The EU F-Gas Regulation restricts hydrofluorocarbon propellants in metered-dose inhalers, compelling formulation transitions. Stakeholders must monitor propellant chemistry substitutions and their compatibility with existing device architectures.
Market Dynamics
Portable oxygen concentrator miniaturization is collapsing the boundary between acute hospital respiratory care and ambulatory home management, forcing device manufacturers to reengineer power efficiency and noise suppression specifications simultaneously.
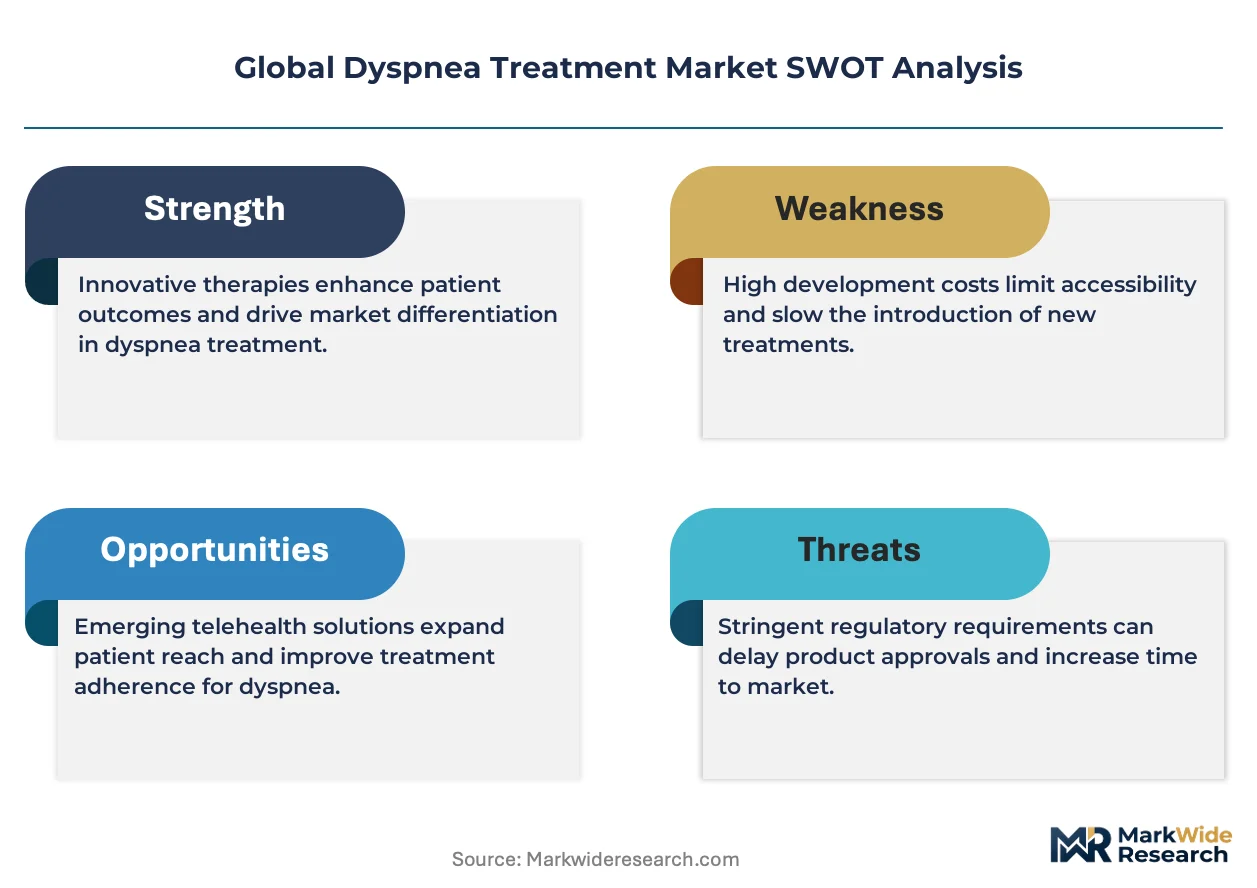
Growth Catalysts
- China's tier-one home oxygen penetration:Municipal healthcare reimbursement in Shanghai and Beijing now covers portable concentrator rentals, accelerating patient migration from inpatient wards to residential settings.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon propellant restrictions in metered-dose inhalers are compelling formulation chemistry investments that yield patent-protected next-generation delivery systems.
- Mesh nebulizer piezoelectric advances:Vibrating membrane technology achieves sub-three-micron particle distributions without compressed gas, enabling battery-powered operation in resource-limited clinic environments.
Market Restraints
- Specialized pulmonologist scarcity:Rural health systems across the United States, India, and Brazil cannot staff respiratory specialty clinics, creating diagnostic bottlenecks that delay therapy initiation.
- Helium-3 supply concentration:Magnetic resonance imaging for pulmonary embolism diagnosis depends on this isotope, with production concentrated in aging nuclear facilities in Russia and the United States.
- FDA bioequivalence complexity:Generic inhaled corticosteroids face prolonged clinical endpoint studies under draft OINDP guidance, extending development timelines versus oral solid dosage forms.
Strategic Opportunities
- India's underserved tier-two cities:Respiratory disease prevalence in Lucknow and Jaipur exceeds specialist capacity by factors of eight to twelve, creating whitespace for tele-pulmonology platforms.
- Japan's METI carbon neutrality roadmap:Subsidies for medical device energy efficiency are accelerating demand for low-power oxygen concentrators in Tokyo's homecare networks.
- Digital biomarker integration:Convergence of pulse oximetry wearables with machine learning algorithms enables predictive exacerbation alerts before emergency department presentation.
Industry Challenges
- ISO 18562 biocompatibility testing capacity:Third-party laboratories face eighteen-month queues for respiratory device gas pathway validation, delaying product registrations.
- Legacy ventilator interoperability:Home oxygen systems must integrate with hospital discharge records through HL7 FHIR standards, requiring middleware investments that strain mid-tier device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dyspnea Treatment Market |
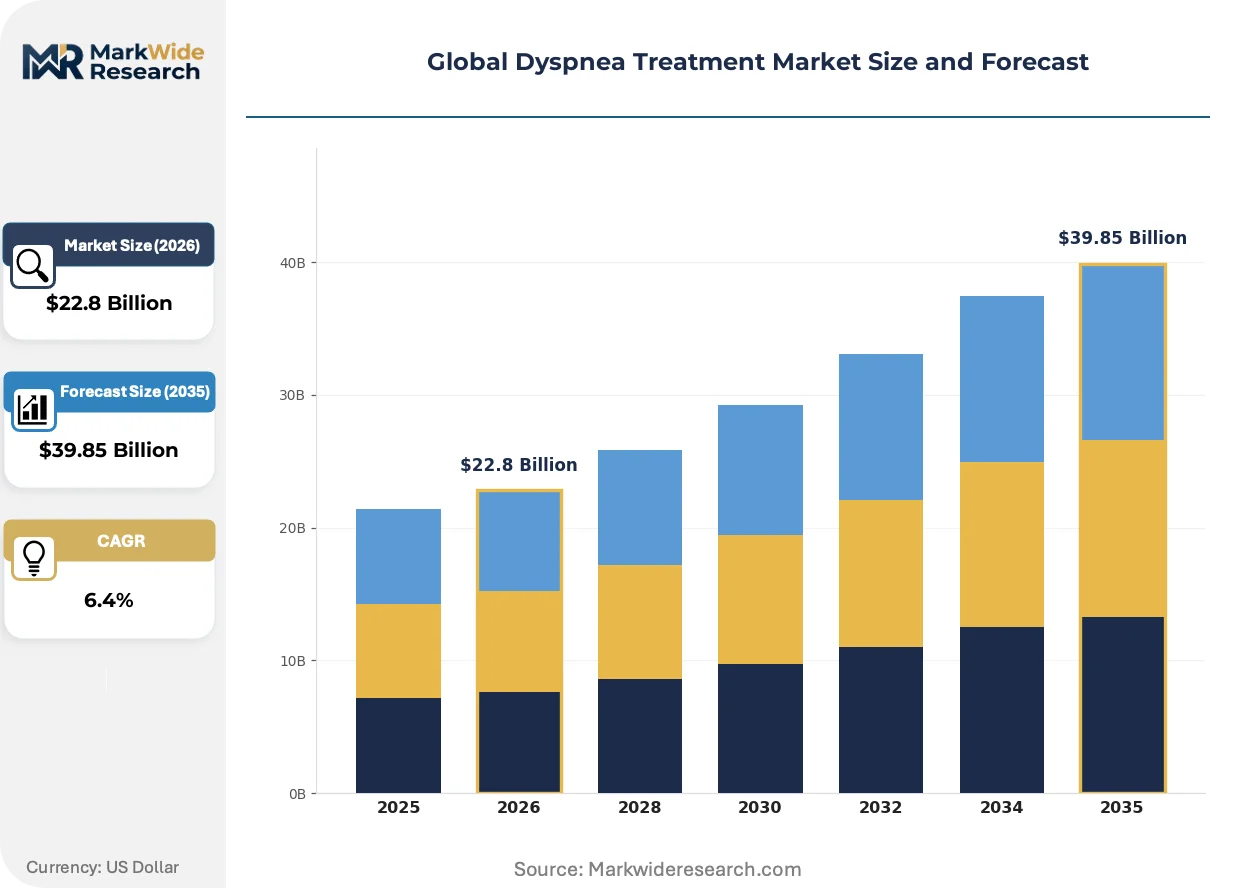
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Oxygen Therapy Devices, Diuretics, Anticholinergics Therapy Area: Chronic Obstructive Pulmonary Disease, Asthma, Heart Failure, Pulmonary Fibrosis, Interstitial Lung Disease End User: Hospitals, Homecare Settings, Outpatient Clinics, Respiratory Care Centers, Long-Term Care Facilities Delivery Mode: Inhalation, Oral, Intravenous, Subcutaneous, Nebulization |
| Companies Covered | Mayne Pharma Group Limited, Teva Pharmaceutical Industries Ltd, GlaxoSmithKline plc, Hikma Pharmaceuticals plc, Lannett Company, Inc., Bausch Health Companies Inc., Amneal Pharmaceuticals LLC, Viatris Inc., Lupin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dyspnea Treatment Market Shifts & Advancements
Dry powder inhaler engineering is abandoning lactose carrier dependence, with formulation scientists pursuing engineered particle technologies that improve lung deposition consistency across humidity extremes.
Silicon micro-pump technology is decomposing the traditional compressor-nebulizer market by enabling palm-sized devices that generate consistent aerosol output from lithium-ion power. Pediatric asthma clinics in Germany and Australia are piloting these systems for school-based medication administration. The structural consequence is compressing reimbursement codes that previously distinguished hospital-grade from home-use nebulization equipment.
EMA's Medical Device Regulation clinical performance requirements are forcing oxygen concentrator manufacturers to submit real-world evidence from European homecare deployments. Post-market surveillance obligations now extend to software updates and battery degradation tracking. German notified bodies are prioritizing review capacity for devices with remote monitoring capabilities, creating regulatory preference for connected-system architectures.
Hospital procurement consortia in São Paulo and Mexico City are unbundling respiratory device purchases from maintenance service contracts, shifting toward per-patient utilization fees. Distributors must now carry inventory risk while manufacturers retain technical support obligations. This model is most visible in Latin American public hospital systems where capital expenditure budgets face chronic compression.
Global Dyspnea Treatment Market Segmentation
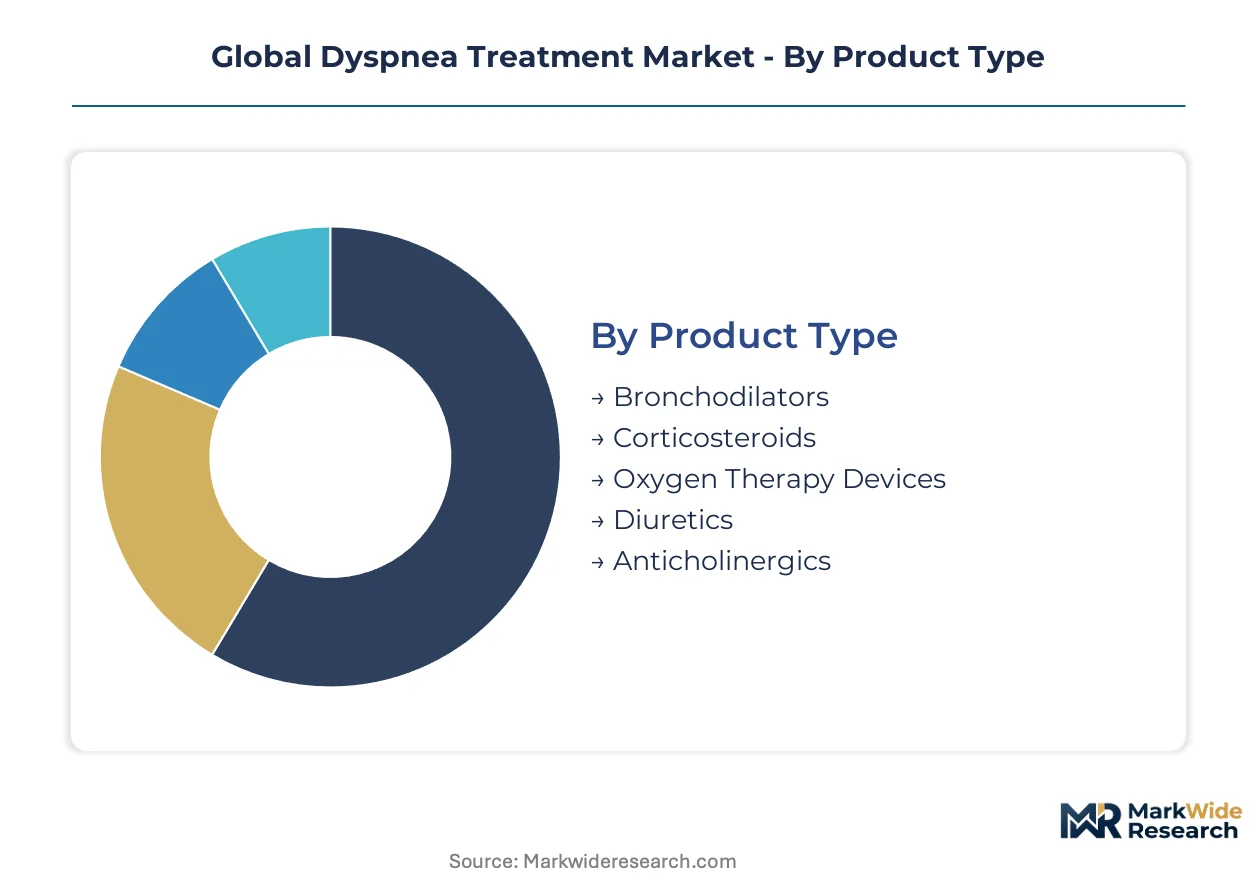
Dyspnea treatment markets fragment across therapeutic modality, care setting, and delivery technology. Each segmentation axis reveals distinct margin structures, reimbursement pathways, and competitive dynamics that shape portfolio allocation decisions for device and pharmaceutical manufacturers.
Product Type:
Margin pools concentrate in device categories where miniaturization commands premium pricing and in maintenance therapies with chronic dosing profiles.
- Bronchodilators:Beta-agonist and anticholinergic formulations relax airway smooth muscle through cyclic AMP modulation or muscarinic receptor blockade. Demand clusters in China's tier-one cities where outpatient COPD protocols standardize on long-acting combination inhalers. The FDA's OINDP bioequivalence requirements protect originator margins against generic erosion.
- Oxygen Therapy Devices:Portable concentrators employing pressure swing adsorption separate nitrogen from ambient air to deliver continuous flow or pulse-dose oxygen. Homecare migration in Germany and Japan drives replacement cycles, with METI subsidies accelerating low-power device adoption in Tokyo's residential networks. Battery chemistry improvements are collapsing the weight-performance tradeoff that previously segmented hospital and ambulatory markets.
- Corticosteroids:Inhaled formulations suppress airway inflammation through glucocorticoid receptor agonism. Fluticasone and budesonide dominate maintenance protocols across asthma and COPD.
- Diuretics:Loop and thiazide agents reduce pulmonary edema through sodium excretion in heart failure-related dyspnea. Furosemide remains the acute standard.
- Anticholinergics:Ipratropium and tiotropium block acetylcholine at M3 receptors to achieve bronchodilation without systemic beta-agonist effects.
Bronchodilators hold installed capacity. Oxygen Therapy Devices is rotating up the share rankings.
Therapy Area:
Volume concentration follows disease prevalence patterns, with reimbursement intensity varying by acute versus chronic management protocols.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation from small airway fibrosis and emphysematous destruction creates sustained demand for bronchodilator maintenance. Brazil's SUS system and India's tier-two cities face diagnostic bottlenecks where pulmonologist scarcity delays therapy initiation. Long-acting muscarinic antagonist plus long-acting beta-agonist combinations anchor GOLD guideline step-up protocols.
- Asthma:Reversible airway hyperresponsiveness driven by type 2 inflammation responds to inhaled corticosteroid-controller therapy. Pediatric clinics in Germany and Australia pilot silicon micro-pump nebulizers for school-based administration, compressing reimbursement distinctions between hospital and home equipment.
- Heart Failure:Pulmonary congestion from left ventricular dysfunction drives diuretic and vasodilator utilization. Acute decompensation episodes generate hospital admission volume.
- Pulmonary Fibrosis:Interstitial remodeling with restrictive physiology creates oxygen-dependent hypoxemia. Antifibrotic therapy slows progression without reversing established damage.
- Interstitial Lung Disease:Heterogeneous parenchymal disorders including sarcoidosis and hypersensitivity pneumonitis require individualized immunosuppression and supplemental oxygen.
COPD commands the largest addressable population. Asthma is gaining share fastest among pediatric-specialized portfolios.
End User:
Customer type determines capital intensity, with institutional purchasers negotiating consortia contracts while homecare channels fragment across rental and direct-sale models.
- Hospitals:Acute care facilities manage exacerbations through nebulized bronchodilators, intravenous diuretics, and high-flow nasal cannula oxygen. São Paulo procurement consortia unbundle device purchases from maintenance contracts, shifting toward per-patient utilization fees that transfer inventory risk to distributors.
- Homecare Settings:Residential oxygen therapy and self-administered inhaler regimens reduce readmission penalties under value-based reimbursement. Shanghai and Beijing municipal coverage for portable concentrator rentals accelerates patient migration from inpatient wards.
- Outpatient Clinics:Community-based respiratory assessment and prescription renewal sites bridge hospital discharge and home management.
- Respiratory Care Centers:Specialized facilities provide pulmonary rehabilitation and non-invasive ventilation titration.
- Long-Term Care Facilities:Nursing homes manage chronic dyspnea in multimorbid elderly populations with limited specialist access.
Hospitals hold installed capacity. Homecare Settings is rotating up the share rankings.
Delivery Mode:
Technology selection hinges on particle size engineering, patient coordination capacity, and the urgency of therapeutic onset.
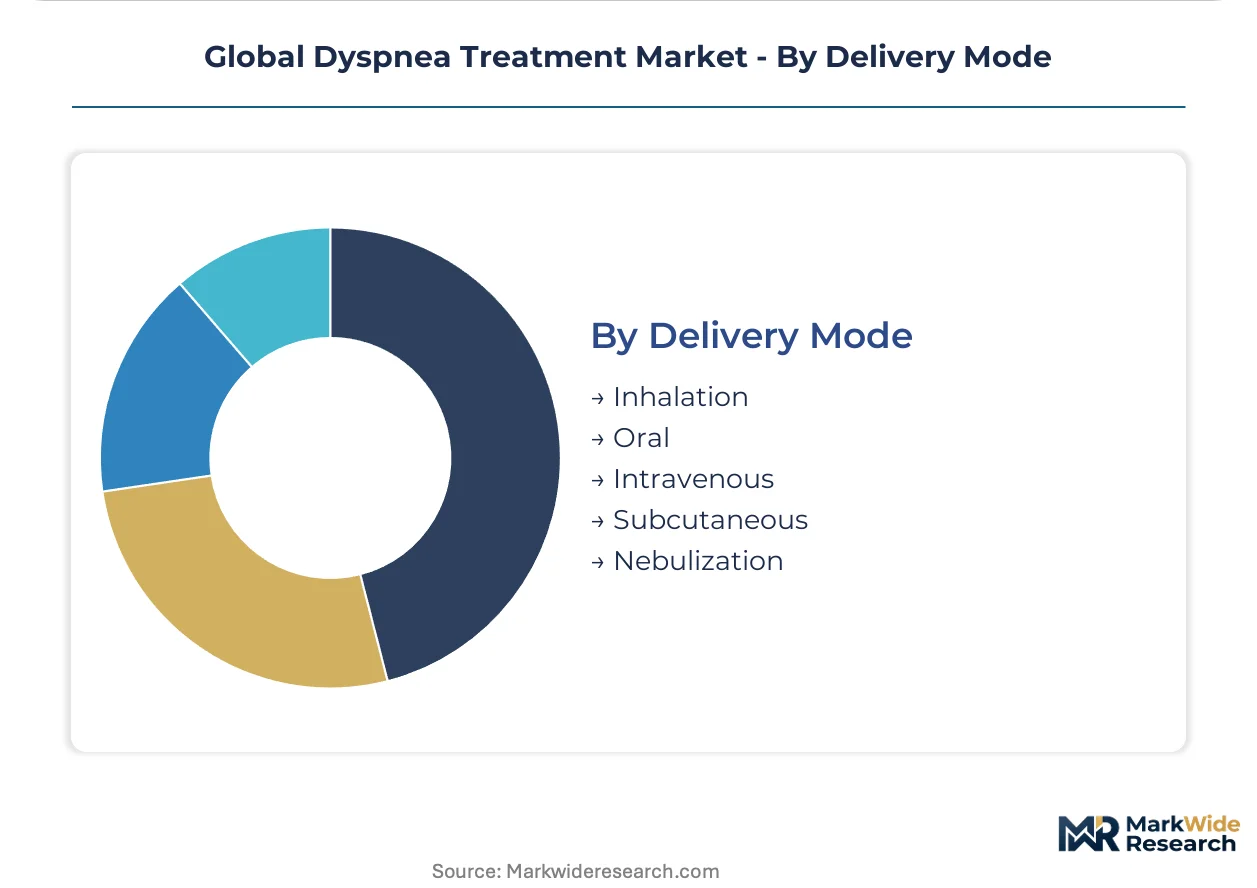
- Inhalation:Pressurized metered-dose and dry powder devices achieve one-to-five-micron particle distributions for alveolar deposition. EU F-Gas Regulation hydrofluorocarbon propellant restrictions compel formulation chemistry investments yielding patent-protected next-generation systems.
- Nebulization:Mesh and jet nebulizers generate aerosol for patients with poor hand-breath coordination. Piezoelectric vibrating membrane technology achieves sub-three-micron distributions without compressed gas, enabling battery-powered operation in resource-limited clinic environments.
- Oral:Systemic corticosteroids and diuretics address inflammation and fluid overload without requiring respiratory coordination.
- Intravenous:Emergency and perioperative settings employ IV bronchodilators and loop diuretics for rapid onset.
- Subcutaneous:Biologic therapies targeting type 2 inflammation in severe asthma bypass gastrointestinal metabolism.
Inhalation holds installed capacity. Nebulization is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital systems favor high-flow nasal cannula oxygen for acute dyspnea management, while China's tier-one cities prioritize portable concentrator rentals for residential migration. Brazil's public procurement consortia unbundle device purchases from service contracts, creating divergent capital deployment patterns across institutional purchasers.
United States
Rural health systems face pulmonologist scarcity that delays specialized dyspnea diagnosis across the Midwest and Southeast. The FDA's OINDP bioequivalence draft guidance extends development timelines for generic inhaled corticosteroids. Hospital networks in Texas and Florida consolidate respiratory device purchasing through regional procurement alliances.
Germany
Notified bodies under EMA's MDR framework prioritize oxygen concentrators with remote monitoring capabilities for expedited review. The EU F-Gas Regulation compels hydrofluorocarbon propellant phase-downs in metered-dose inhalers manufactured in Baden-Württemberg. Berlin's homecare networks accelerate low-power device adoption through municipal reimbursement expansion.
China
Shanghai and Beijing municipal healthcare reimbursement now covers portable concentrator rentals, accelerating patient discharge from inpatient wards. NMPA maintains stringent clinical evidence requirements for combination bronchodilator therapies seeking market authorization. Yangtze River Delta manufacturing clusters scale mesh nebulizer production for domestic and export markets.
Japan
Tokyo's residential networks drive replacement cycles for energy-efficient oxygen concentrators under METI carbon neutrality subsidies. PMDA evaluates real-world evidence submissions for software-updated respiratory devices under revised pharmaceutical and medical device regulations. Osaka-based distributors manage inventory risk under per-patient utilization fee models.
Brazil
São Paulo hospital procurement consortia shift respiratory device purchasing toward per-patient utilization fees that transfer inventory risk to distributors. ANVISA enforces clinical performance verification for imported oxygen delivery systems entering the SUS public health network. Minas Gerais faces diagnostic bottlenecks where respiratory disease prevalence exceeds specialist capacity.
Global Dyspnea Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the dyspnea treatment market, with pharmaceutical originators commanding maintenance therapy margins and device manufacturers competing on miniaturization specifications. The competitive terrain separates into three strategic archetypes: originator pharmaceutical firms with inhaled corticosteroid portfolios, generic manufacturers scaling bronchodilator production, and medical device specialists engineering portable oxygen systems. Dominant competitive moves include geographic expansion into underserved tier-two cities and technology licensing for mesh nebulizer piezoelectric platforms.
Within the originator pharmaceutical tier, GlaxoSmithKline plc and Teva Pharmaceutical Industries Ltd occupy positions that exemplify divergent strategic postures. GlaxoSmithKline plc anchors chronic obstructive pulmonary disease therapy lines through its inhaled corticosteroid portfolio concentration. Teva Pharmaceutical Industries Ltd represents the generic manufacturing scale archetype, sustaining competitive pressure through bronchodilator production volume. Mayne Pharma Group Limited sits within the specialist tier, occupying a position that reflects mid-cap pharmaceutical development focus.
| Leading Market Players |
|---|
| Mayne Pharma Group Limited |
| Teva Pharmaceutical Industries Ltd |
| GlaxoSmithKline plc |
| Hikma Pharmaceuticals plc |
| Lannett Company, Inc. |
| Bausch Health Companies Inc. |
| Amneal Pharmaceuticals LLC |
| Viatris Inc. |
| Lupin Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for hydrofluorocarbon propellants lock in both supply access and price visibility for metered-dose inhaler manufacturers navigating the EU F-Gas Regulation phase-down, while per-patient utilization fees in São Paulo and Mexico City transfer inventory risk to distributors.
Pricing Analysis
Contract-based long-term offtake dominates active pharmaceutical ingredient procurement, with price differentiation resting on ISO 18562 certification tier and after-sales service bundling. Cost compression in generic bronchodilators intensifies as FDA bioequivalence studies extend development timelines. Hospital procurement consortia exhibit lowest price sensitivity; retail pharmacy channels face greatest margin pressure.
Supply Chain Analysis
Strategic stockpiling of piezoelectric mesh components prevails over just-in-time preferences among nebulizer manufacturers, given eighteen-month ISO 18562 validation queues. Supply concentrates in China's Yangtze River Delta for mesh nebulizer production, Germany's Baden-Württemberg for propellant formulation, and India's API synthesis clusters. Single-source vulnerability runs through Russian and United States helium-3 for pulmonary imaging. Distribution runs through hospital procurement consortia in Latin America and homecare rental networks in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from digital biomarker-enabled remote monitoring platforms that bypass traditional device-centric care models.
For Market Incumbents: Shield installed base by securing backward integration into piezoelectric mesh manufacturing and accelerating MDR-compliant remote monitoring capabilities ahead of German notified body prioritization shifts. Lock in long-term propellant chemistry partnerships before EU F-Gas restrictions tighten further.
For New Entrants and Emerging Players: Differentiate on tele-pulmonology platform integration targeting India's tier-two cities where specialist scarcity exceeds supply by eight to twelve factors. Pursue per-patient utilization fee contracts with São Paulo hospital consortia to bypass capital expenditure barriers.
For Investors and Strategic Acquirers: Medical device specialists with captive ISO 18562 testing capacity command scarcity premia as third-party laboratory queues extend. Watch for FDA OINDP guidance finalization as inflection indicator for generic inhaler pipeline valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Municipal coverage expansion in Shanghai and Beijing accelerates home oxygen migration. |
| Regulatory Approval Pathway | EMA MDR clinical performance verification creates preference for connected-system architectures. |
| Backward Integration | In-house piezoelectric mesh production collapses ISO 18562 validation dependency risks. |
| Hospital System Partnership | Per-patient utilization contracts with São Paulo consortia transfer inventory risk downstream. |
| Software Companion Development | Pulse oximetry wearable integration enables predictive exacerbation alerts before emergency presentation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pulmonologists, hospital procurement managers, GPO contracts managers, and biomedical engineers; and secondary validation through FDA OINDP guidance documents, EMA MDR submissions, CMS Medicare reimbursement databases, and ClinicalTrials.gov entries. Bottom-up and top-down triangulation reconciled device shipment data with pharmaceutical prescription volumes.
Across the projection horizon, the analytical framework modeled therapeutic modality, care setting, delivery technology, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth trajectories weighted by reimbursement intensity and patient population prevalence curves. Forecast inputs incorporated METI subsidy elasticity for energy-efficient concentrators and EU F-Gas Regulation compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in FDA OINDP, EMA MDR, and NMPA combination therapy frameworks; material policy shifts would require re-modeling. Revision becomes warranted when pulmonologist workforce shortage ratios in target geographies cross critical access thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market