
 Idiopathic Pulmonary Fibrosis (IPF) Treatment Market | 2026-2036
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market Foresight
Modular unbundling of antifibrotic therapy from bundled hospital contracts is decoupling procurement decisions from institutional formularies. Boehringer Ingelheim International GmbH leverages its vertical integration into pyridone chemistry manufacturing to sustain supply security across European and North American channels. F. Hoffmann-La Roche Ltd anchors its position through biologics R&D intensity in fibrotic disease pathways. United Therapeutics Corporation differentiates via pulmonary arterial hypertension cross-therapeutic expertise that extends into IPF supportive care.
Idiopathic Pulmonary Fibrosis treatment encompasses pharmacological interventions targeting progressive lung scarring of unknown etiology, with nintedanib and pirfenidone representing tyrosine kinase and pyridone-based antifibrotic mechanisms that slow forced vital capacity decline. These therapies serve the primary purpose of delaying disease progression and reducing acute exacerbation frequency in patients with histologically or radiologically confirmed usual interstitial pneumonia pattern. Antifibrotic agents command the dominant margin pool due to premium pricing and chronic administration requirements, while combination therapy represents the fastest-growing therapeutic approach as clinicians explore nintedanib-pirfenidone sequencing. Hospital end users retain volume leadership in initial diagnosis and acute management, though homecare channels are capturing growing prescription refill volumes as oral therapies mature.
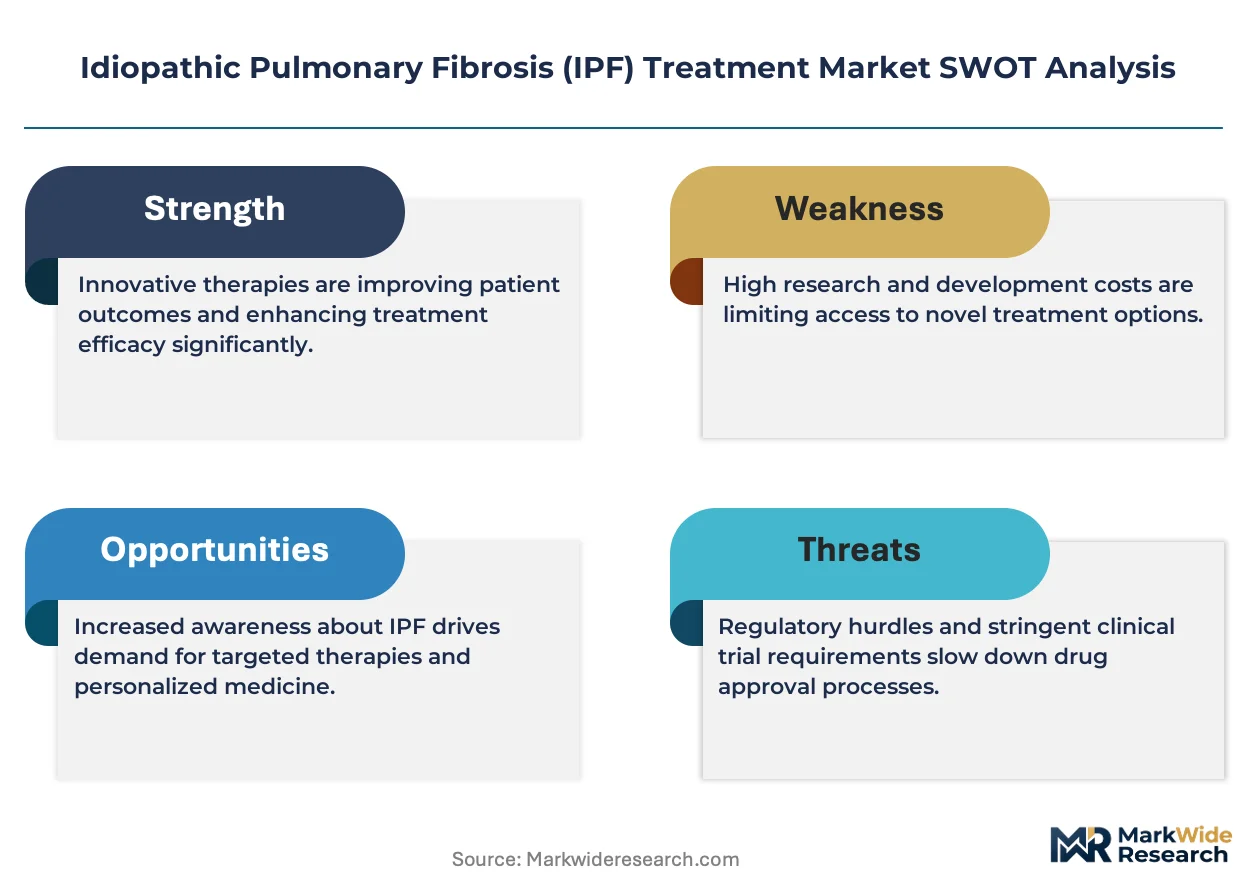
The FDA Orphan Drug program and EMA orphan designation framework shape IPF development economics through tax credits, protocol assistance, and market exclusivity provisions that reduce clinical trial risk for sponsors. NMPA accelerated review pathways in China and Japan's PMDA Sakigake designation further expand geographic access for novel antifibrotic entrants. Stakeholders must monitor biomarker-validated patient stratification trials that could fragment the historically homogeneous IPF indication into addressable subpopulations with differentiated therapy responses.
Market Dynamics
The FDA Orphan Drug designation framework is restructuring IPF development economics by compressing clinical trial timelines and amplifying sponsor incentives through tax credits and market exclusivity provisions that de-risk novel antifibrotic programs.
Growth Catalysts
- Orphan Drug Incentives:The FDA's seven-year market exclusivity and protocol assistance provisions reduce regulatory friction for sponsors pursuing novel pyridone and kinase inhibitor mechanisms in fibrotic pathways.
- Specialty Clinic Expansion:Pulmonary specialty clinics in the United States are decoupling antifibrotic procurement from hospital formularies, enabling direct physician-patient decision pathways for nintedanib and pirfenidone selection.
- Biomarker Stratification:Circulating protein signature validation is fragmenting the homogeneous IPF indication into therapy-responsive subpopulations that expand addressable patient pools for targeted mechanisms.
Market Restraints
- Input Concentration Risk:Pyridone active pharmaceutical ingredient synthesis depends on captive Chinese and Indian intermediate suppliers, exposing formulation capacity to single-source disruption.
- Reimbursement Compression:Medicare Part D prior authorization requirements in the United States impose 14-21 day therapy initiation delays that compress real-world adherence rates.
- Diagnostic Latency:Radiological pattern recognition expertise concentrates in academic medical centers, leaving community pulmonology practices with 12-24 month median delays from symptom onset to antifibrotic initiation.
Strategic Opportunities
- Homecare Channel Penetration:Oral antifibrotic maturation enables specialty pharmacy direct-to-patient distribution models that bypass hospital outpatient infusion center dependency.
- Japan's Sakigake Pathway:PMDA priority review designation for breakthrough fibrosis mechanisms offers 50% faster approval timelines than standard review, accelerating geographic expansion for novel entrants.
- Combination Regimen White Space:Nintedanib-pirfenidone sequencing protocols are establishing a new therapeutic category with distinct pharmacoeconomic profiles from monotherapy standards.
Industry Challenges
- Interstitial Pneumonia Pattern Recognition:High-resolution CT interpretation expertise scarcity restricts diagnosis capacity to tertiary referral networks, creating patient access bottlenecks.
- Forced Vital Capacity Endpoint Standardization:Variability in spirometry protocol execution across multicenter trials generates regulatory scrutiny and protocol amendment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Pulmonary Fibrosis (IPF) Treatment Market |
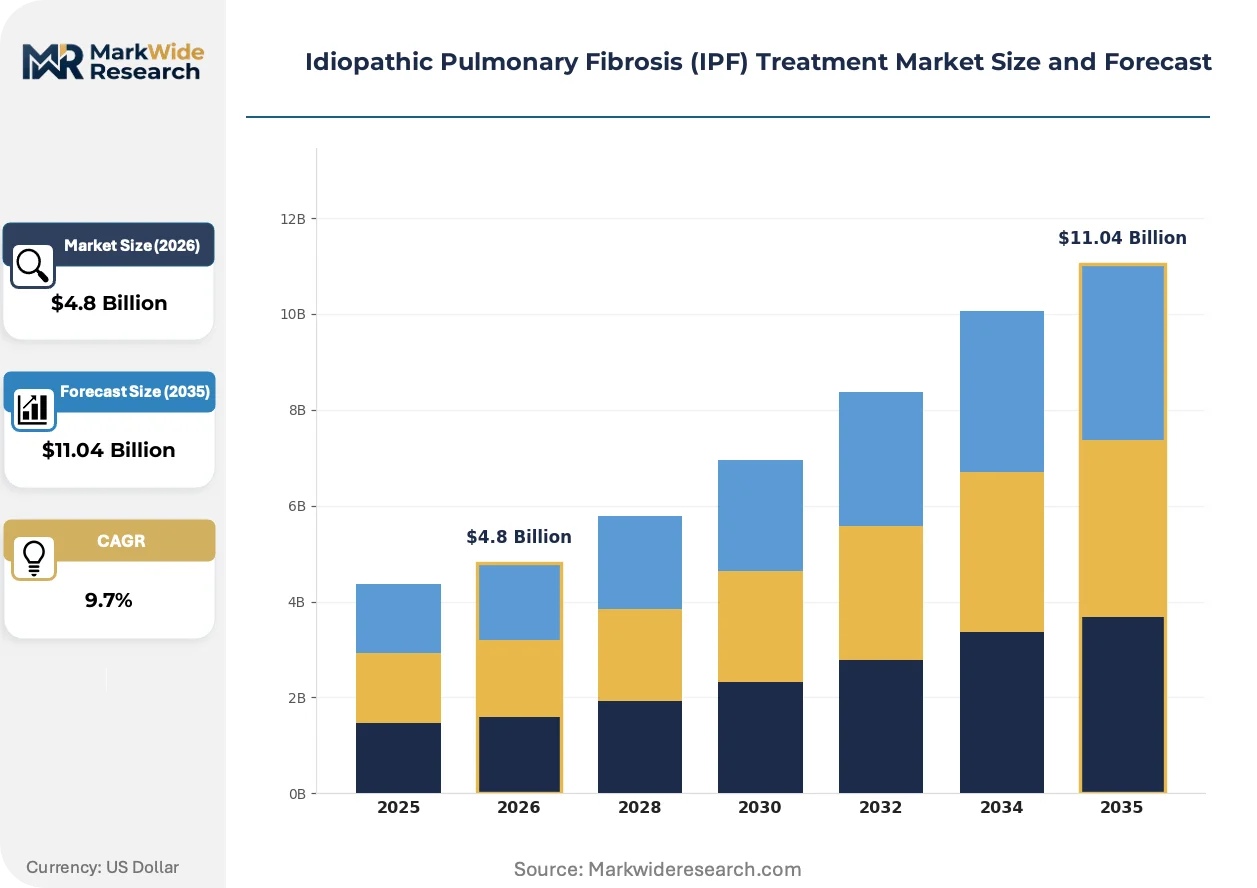
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Immunosuppressants, Corticosteroids, Antibiotics Therapeutic Approach: Monotherapy, Combination Therapy, Supportive Care, Palliative Care End User: Hospitals, Specialty Clinics, Homecare, Research Institutes Distribution Channel: Direct Sales, Pharmacy Chains, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, FibroGen, Inc., United Therapeutics Corporation, Bristol-Myers Squibb Company, Galapagos NV, MediciNova, Inc., Cipla Inc., Pliant Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market Shifts & Advancements
Antifibrotic therapy development is pivoting from homogeneous population trials toward biomarker-validated subpopulation studies that promise differentiated regulatory pathways and reimbursement positioning.
Artificial intelligence-based quantitative interstitial lung disease scoring is automating radiological pattern recognition in high-resolution CT interpretation workflows. Pulmonary imaging centers at Cleveland Clinic and Mayo Clinic are deploying these algorithms to compress diagnostic timelines from weeks to days. This automation is reducing specialist radiologist dependency and enabling community hospital diagnosis capacity expansion.
EMA's orphan designation framework revision is tightening evidentiary standards for IPF therapies by requiring forced vital capacity decline demonstration against placebo rather than historical controls. Sponsors must now enroll larger placebo arms or pursue active comparator designs that inflate trial costs. European pulmonary specialists are responding by consolidating patients into academic trial networks to sustain enrollment velocity.
Specialty pharmacy direct distribution is displacing hospital outpatient dispensing for oral antifibrotic maintenance therapy. Accredo and CVS Specialty are capturing refill volume through hub-and-spoke models that integrate adherence monitoring with home delivery logistics. This channel rotation is most visible in United States Medicare Advantage plans where risk-bearing entities seek to reduce 30-day readmission exposure through medication therapy management bundling.
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market Segmentation
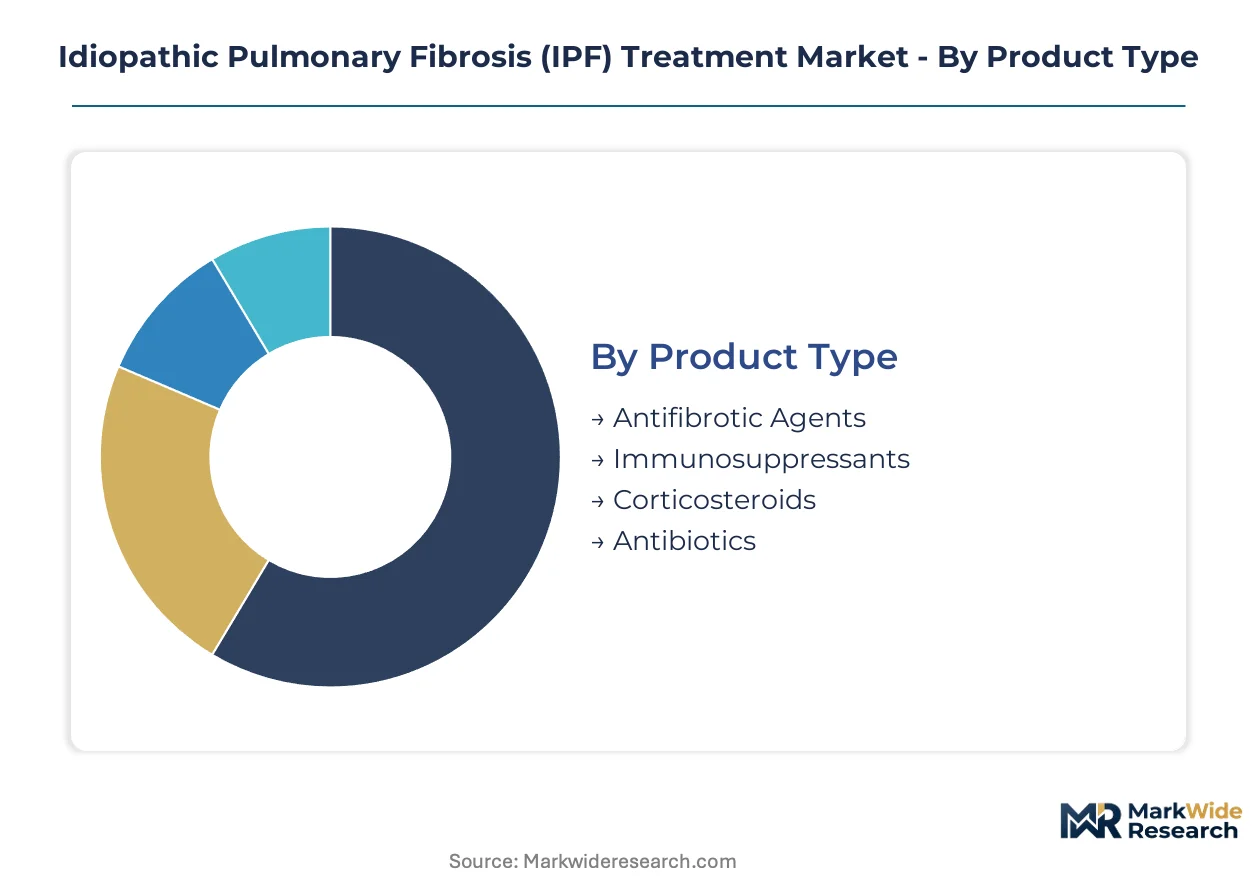
IPF treatment segmentation reveals distinct procurement pathways and reimbursement dynamics across therapeutic modalities. Understanding these divisions exposes where margin pools concentrate and how channel strategies must adapt to divergent patient journeys.
Product Type:
Antifibrotic agents operate as standalone chronic therapies, while immunosuppressants and corticosteroids embed within acute exacerbation protocols requiring hospital oversight.
- Antifibrotic Agents:Tyrosine kinase and pyridone-based mechanisms slow forced vital capacity decline through chronic oral administration. United States Medicare Part D and European statutory health insurance systems concentrate demand through specialty pharmacy networks that manage prior authorization workflows.
- Immunosuppressants:Azathioprine and mycophenolate mofetil modulate immune-mediated fibrotic acceleration in selected phenotypes. German and French academic medical centers drive prescription volumes through interstitial lung disease unit protocols that stratify autoimmune overlap cases.
- Corticosteroids:High-dose pulse methylprednisolone addresses acute exacerbations requiring inpatient monitoring.
- Antibiotics:Macrolide prophylaxis targets chronic microaspiration and infection-triggered exacerbation cascades.
Antifibrotic agents lead volumes today; combination regimens pairing these mechanisms are gaining share fastest.
Therapeutic Approach:
Cost tier stratification separates premium-priced disease-modifying therapy from supportive interventions reimbursed at standard care rates.
- Monotherapy:Single-agent nintedanib or pirfenidone constitutes first-line standard for confirmed usual interstitial pneumonia pattern. Japan's PMDA Sakigake pathway accelerates approval for novel monotherapy entrants seeking premium positioning.
- Combination Therapy:Sequential or concurrent nintedanib-pirfenidone protocols target residual disease activity in rapid progressors. Cleveland Clinic and Mayo Clinic pulmonary centers in the United States are establishing sequencing protocols that define this emerging category.
- Supportive Care:Supplemental oxygen, pulmonary rehabilitation, and nutritional intervention manage functional decline.
- Palliative Care:Symptom-focused approaches address end-stage dyspnea and quality-of-life preservation.
Monotherapy dominates current prescribing; combination approaches show steepest expansion trajectory as biomarker stratification enables patient selection.
End User:
Volume concentration varies by therapy maturity, with oral antifibrotics shifting from hospital initiation toward distributed maintenance channels.
- Hospitals:Academic medical centers anchor diagnosis through high-resolution CT pattern recognition and surgical lung biopsy capacity. United States tertiary referral networks at institutions like Johns Hopkins and University of California San Francisco capture initial antifibrotic prescriptions before patient transition.
- Specialty Clinics:Dedicated interstitial lung disease clinics decouple ongoing management from hospital formularies. United Kingdom and Netherlands specialist networks are expanding community-based prescribing authority for oral maintenance therapy.
- Homecare:Specialty pharmacy direct distribution enables patient-managed oral therapy with remote monitoring.
- Research Institutes:Academic trial units enroll patients into biomarker-stratified studies and novel mechanism evaluations.
Hospitals retain diagnostic volume leadership; specialty clinics are capturing maintenance-phase share fastest.
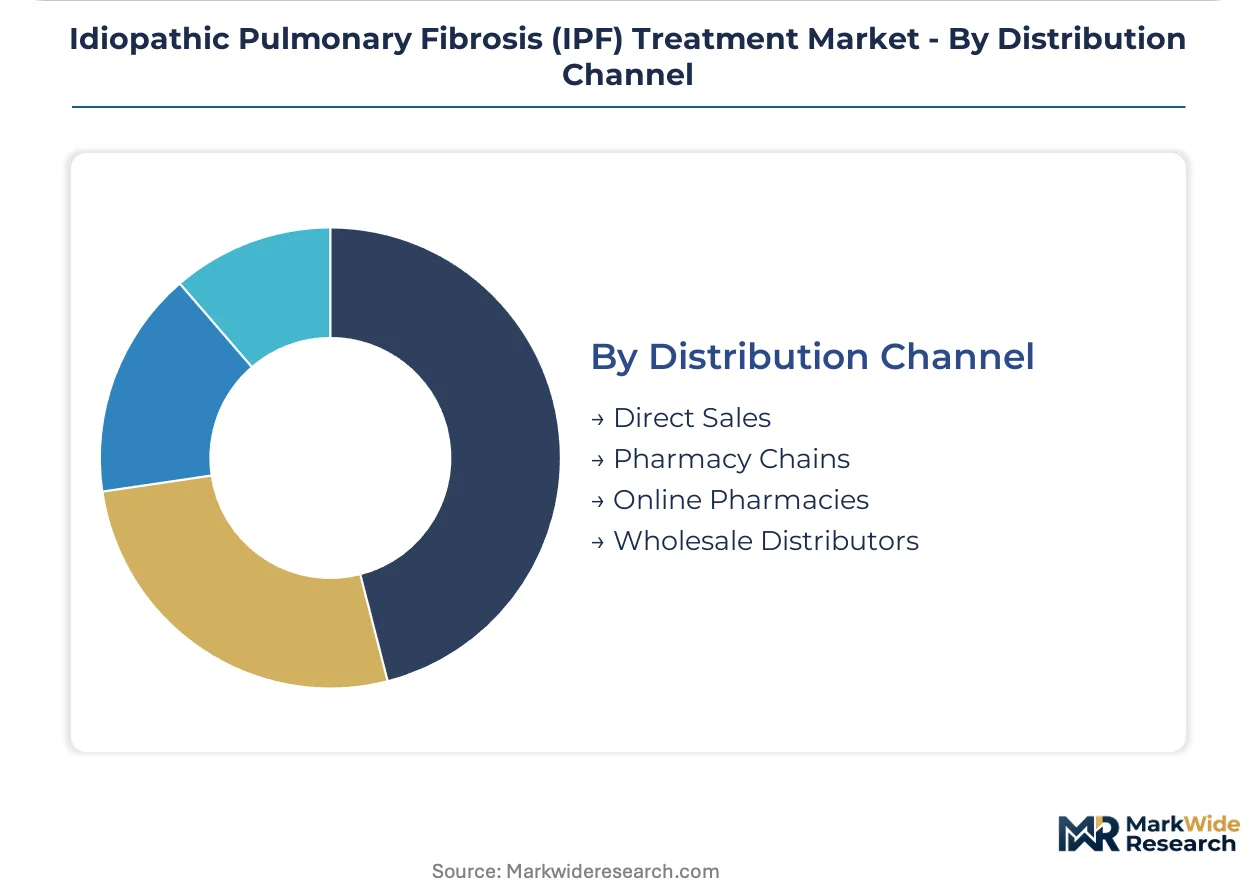
Distribution Channel:
Supply concentration in pyridone API synthesis shapes channel reliability and geographic availability for antifibrotic formulations.
- Direct Sales:Manufacturer-to-institution contracts serve hospital formularies and integrated delivery networks. Boehringer Ingelheim and Roche maintain dedicated account teams for United States academic medical center procurement.
- Pharmacy Chains:CVS Specialty and Walgreens specialty pharmacy divisions capture Medicare Advantage plan volumes through risk-bearing entity contracts.
- Online Pharmacies:Telehealth-integrated platforms facilitate refill adherence for geographically dispersed patients.
- Wholesale Distributors:McKesson and AmerisourceBergen maintain cold-chain and controlled-substance infrastructure for hospital replenishment.
Direct sales lead institutional volumes today; specialty pharmacy chains are displacing wholesale channels fastest in oral maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antifibrotic therapy development traces its commercial origins to Germany and Switzerland, where pyridone chemistry platforms and kinase inhibitor programs first achieved regulatory validation for idiopathic pulmonary fibrosis indications.
United States
Medicare Part D reimbursement structures and specialty clinic networks concentrate antifibrotic demand. FDA Orphan Drug tax credits and seven-year exclusivity provisions sustain sponsor investment in novel mechanisms. Johns Hopkins and University of California San Francisco anchor diagnostic capacity through high-resolution CT pattern recognition and surgical lung biopsy expertise.
Germany
Statutory health insurance coverage for nintedanib and pirfenidone drives prescription volumes through interstitial lung disease unit protocols. EMA orphan designation frameworks shape evidentiary requirements for novel entrants. Heidelberg and Munich academic medical centers consolidate biomarker-stratified trial enrollment through European reference network structures.
Japan
PMDA Sakigake priority review designation compresses approval timelines for breakthrough fibrosis mechanisms by 50 percent versus standard review. Aging demographics and elevated IPF prevalence expand addressable patient pools. Tokyo and Osaka pulmonary centers pioneer combination therapy sequencing protocols that define emerging therapeutic categories.
United Kingdom
NICE technology appraisal processes determine antifibrotic access through cost-effectiveness thresholds. NHS England interstitial lung disease specialist networks decouple maintenance prescribing from hospital formularies. Manchester and London academic clusters deploy artificial intelligence-based quantitative interstitial lung disease scoring to compress diagnostic latency.
China
NMPA accelerated review pathways enable priority status for novel antifibrotic mechanisms addressing unmet medical need. Domestic pyridone active pharmaceutical ingredient synthesis concentrates formulation supply security. Beijing and Shanghai tertiary hospitals anchor high-resolution CT interpretation capacity for usual interstitial pneumonia pattern confirmation.
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive manufacturing infrastructure and biologics R&D depth. Two strategic archetypes dominate: established respiratory therapy platforms leveraging cross-therapeutic expertise, and emerging biotechnology specialists pursuing biomarker-validated subpopulation strategies. Competitive moves concentrate on backward integration into pyridone chemistry supply chains and geographic expansion through priority regulatory pathways.
Among European pharmaceutical conglomerates, Boehringer Ingelheim International GmbH and F. Hoffmann-La Roche Ltd exemplify the integrated platform archetype through in-house production capabilities and biologics pipeline intensity. United Therapeutics Corporation occupies a distinct position bridging pulmonary arterial hypertension expertise into IPF supportive care segments. These three anchors represent divergent strategic vectors: captive supply security, biologics R&D intensity, and cross-therapeutic domain extension.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd |
| FibroGen, Inc. |
| United Therapeutics Corporation |
| Bristol-Myers Squibb Company |
| Galapagos NV |
| MediciNova, Inc. |
| Cipla Inc. |
| Pliant Therapeutics |
| Others |
Supply & Pricing Matrix
Vertically integrated pharmaceutical conglomerates with captive pyridone chemistry manufacturing anchor supply security for antifibrotic therapies, enabling premium pricing discipline through controlled input costs and limited third-party dependency. This ownership structure concentrates pricing power among Boehringer Ingelheim and Roche while exposing smaller entrants to API sourcing volatility that compresses margin flexibility.
Pricing Analysis
Three-tier pricing structure across premium antifibrotic monotherapy, combination regimens, and supportive care interventions stratifies the IPF treatment landscape. Price differentiation rests on forced vital capacity endpoint validation and FDA Orphan Drug exclusivity status rather than manufacturing cost alone. Pricing pressure stems from Medicare Part D prior authorization delays that extend therapy initiation timelines and trigger adherence-driven discounting. Hospital procurement committees exhibit highest price sensitivity due to bundled reimbursement constraints, while specialty clinics with direct patient relationships sustain premium acceptance.
Supply Chain Analysis
Certification gating through FDA active pharmaceutical ingredient facility inspections and EMA GMP compliance standards constrains pyridone intermediate sourcing to qualified Chinese and Indian manufacturers. Formulation supply draws from captive European synthesis at Boehringer Ingelheim Ludwigshafen and Roche Basel alongside third-party Indian API converters. Single-source vulnerability concentrates in pyridone ring closure chemistry steps where qualified alternative suppliers remain limited. Distribution runs through specialty pharmacy hub-and-spoke networks that bypass hospital outpatient dependency for oral maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IPF treatment market represents a late-cycle quality story where biomarker-validated patient stratification is shifting demand toward premium-priced targeted mechanisms with differentiated regulatory pathways.
For Market Incumbents: Deepen backward integration into pyridone intermediate synthesis to insulate formulation capacity from Chinese supplier disruption. Expand Cleveland Clinic and Mayo Clinic academic partnerships to anchor combination therapy protocol development before biosimilar entrants erode nintedanib and pirfenidone pricing power through Medicare Advantage formulary competition. For New Entrants and Emerging Players: Capture Japan's PMDA Sakigake priority review pathway for novel kinase inhibitor mechanisms with 50% faster approval timelines than standard FDA review. Target biomarker-stratified subpopulations with circulating protein signature validation that fragments the homogeneous IPF indication into addressable rapid-progressor segments with distinct pharmacoeconomic profiles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotechnology specialists with Phase II biomarker-stratified trial assets and orphan designation precedent. Long-term viability hinges on successful forced vital capacity endpoint demonstration against placebo rather than historical controls under tightening EMA evidentiary standards. The signal to watch is artificial intelligence-based quantitative interstitial lung disease scoring adoption across United States academic medical centers as diagnostic capacity expansion indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Validated Patient Stratification | Cleveland Clinic and Mayo Clinic protocols fragment homogeneous IPF indication into therapy-responsive subpopulations. |
| Backward Integration into Pyridone Chemistry | Boehringer Ingelheim Ludwigshafen captive synthesis insulates European supply from Chinese intermediate disruption. |
| PMDA Sakigake Priority Review Pathway | Tokyo pulmonary centers accelerate novel antifibrotic approval timelines by 50 percent versus standard FDA review. |
| Specialty Pharmacy Direct Distribution | Accredo and CVS Specialty hub-and-spoke models displace hospital outpatient dispensing for oral maintenance therapy. |
| Artificial Intelligence Diagnostic Automation | Mayo Clinic quantitative interstitial lung disease scoring compresses high-resolution CT interpretation from weeks to days. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare Part D claims data. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated to anchor market estimates.
Comparable-period anchoring linked projection assumptions to historical antifibrotic adoption curves across the analysis window, with segmentation modeling across therapeutic approach, end user channel, and regional regulatory cluster dimensions. CAGRs were derived from patient incidence forecasting, therapy penetration assumptions, and pricing trajectory analysis incorporating Medicare reimbursement rate evolution and prior authorization friction estimates.
Regulatory pathway delays, biomarker validation failures, and pyridone API supply disruption are the dominant revision risks that could materially alter trajectory assumptions. A model refresh is warranted upon material change in FDA Orphan Drug exclusivity precedent or EMA evidentiary standard tightening for placebo-controlled trial designs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Nitric Oxide Management Systems Market