
 Global Online Second-Hand Car Trading Service Market | 2026-2036
Global Online Second-Hand Car Trading Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Second-Hand Car Trading Service Market Foresight
The EU Green Deal is hardening the cost-of-entry calculus for online used-car platforms serving European consumers. Carvana leverages its vertically integrated logistics network to sustain same-day delivery promises across the United States. Guazi dominates China's fragmented peer-to-peer segment through AI-powered vehicle condition scoring.
Online second-hand car trading services are digital marketplaces that match pre-owned vehicle sellers with buyers through algorithmic pricing engines, vehicle history databases, and remote inspection protocols; their primary commercial purpose is to reduce information asymmetry and transaction friction in decentralized automotive resale. Commission-based payment models anchor profitability for platforms processing high-value transactions, while subscription fees attract dealership volume in the United States and Germany. SUVs command premium listing visibility due to elevated average selling prices and faster inventory turnover.
The EPA enforces emissions disclosure requirements that shape vehicle eligibility for platform listings in the United States, while China's SAMR monitors antitrust compliance as platform consolidation accelerates. The EU AI Act will impose algorithmic transparency obligations on automated pricing systems. Stakeholders must monitor how regulator scrutiny of pricing algorithms reshapes platform economics and competitive moats.
Market Dynamics
Algorithmic pricing engines and remote inspection protocols are compressing transaction cycles and eroding traditional dealer intermediation in pre-owned vehicle resale.
Growth Catalysts
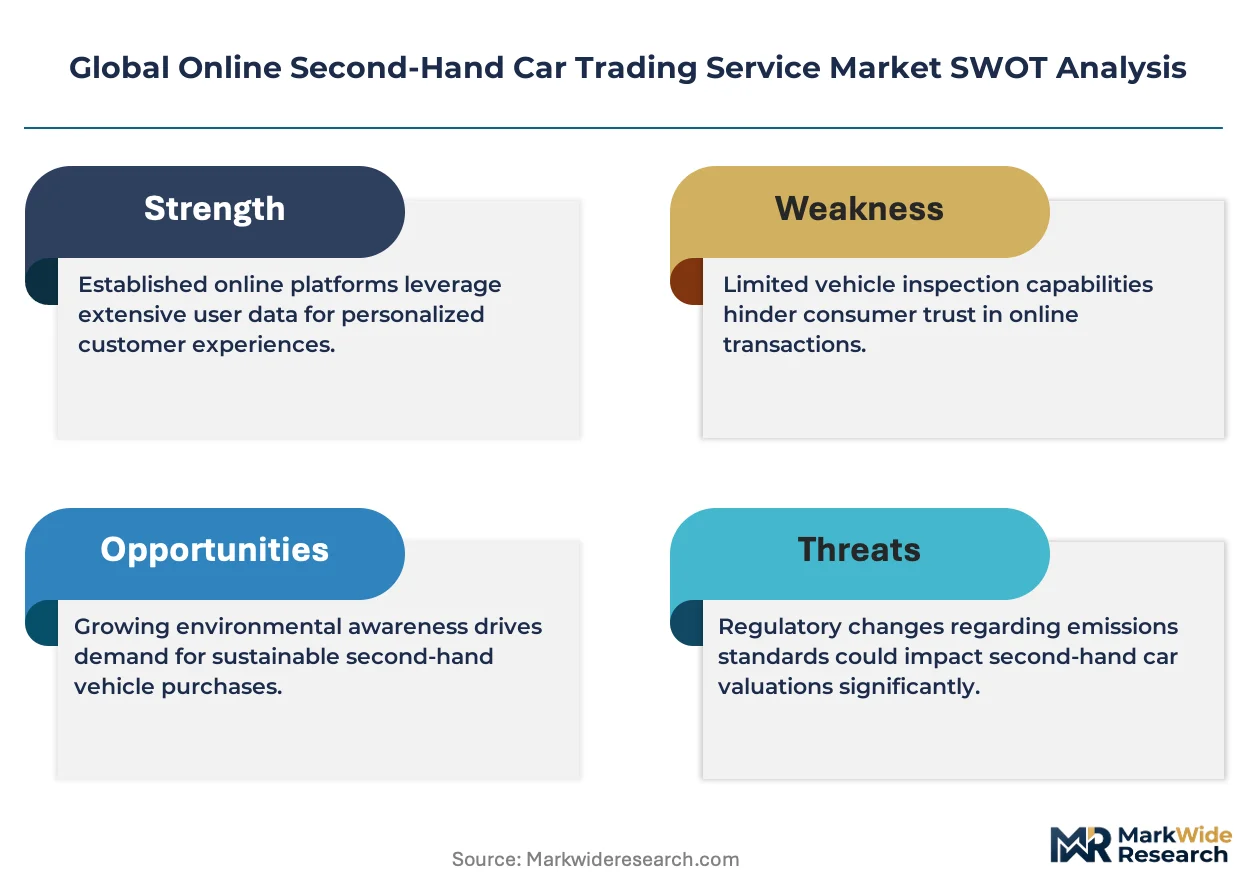
- EU Green Deal circularity mandates:Brussels is compelling platforms to invest in carbon footprint tracking and refurbishment certification, creating compliant listing advantages for early adopters.
- AI-powered vehicle condition scoring:Computer vision systems trained on damage datasets are standardizing remote assessments and reducing buyer return rates.
- First-time buyer digital preference:Younger demographics in the United States and Germany bypass physical lots entirely, concentrating demand on platforms with same-day logistics.
Market Restraints
- Input cost volatility in logistics fuel:Diesel price fluctuations compress margins for platforms promising rapid delivery across dispersed geographies.
- EPA emissions disclosure complexity:California's stricter tailpipe standards create eligibility fragmentation that blocks interstate listing standardization.
- Platform consolidation under SAMR review:China's antitrust regulator is scrutinizing vertical mergers that would concentrate pricing algorithm control.
Strategic Opportunities
- Subscription fee models for German dealerships:Fixed monthly access charges attract volume sellers seeking predictable customer acquisition costs.
- Blockchain title verification:Distributed ledger integration with state DMV databases is reducing fraud exposure in high-value transactions.
- EU AI Act transparency requirements:Automated pricing disclosure obligations will favor platforms with auditable algorithm architectures.
Industry Challenges
- Certified inspector talent scarcity:Remote assessment protocols require technicians trained in both automotive diagnostics and digital documentation standards.
- Legacy dealer system integration:API compatibility with established dealership management software demands sustained engineering investment.
- Algorithmic bias audit timelines:Platforms must document pricing fairness across demographic segments before regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Second-Hand Car Trading Service Market |
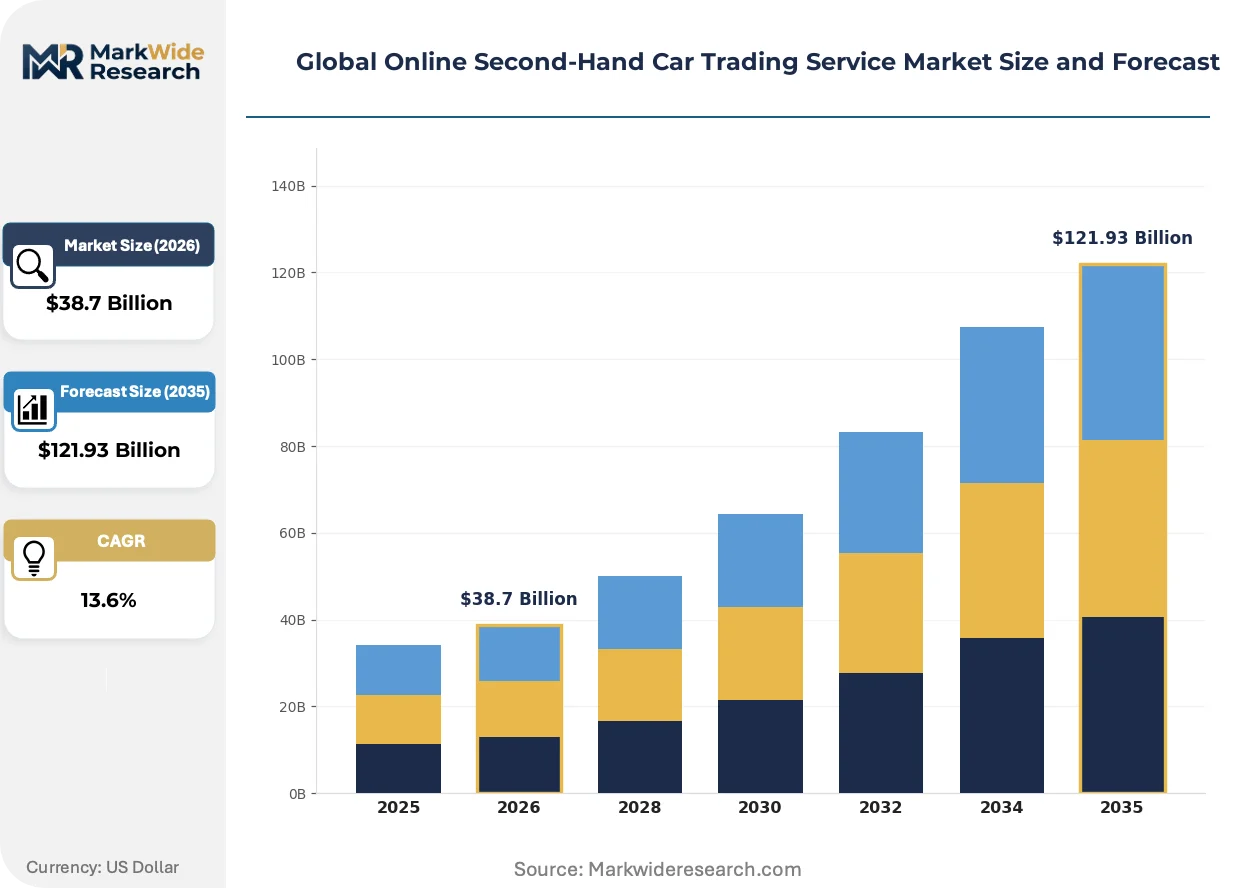
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $121.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Platforms, Auctions, Direct Sales, Classifieds Customer Type: Individuals, Dealerships, Rental Agencies, Corporate Clients Product Type: Sedans, SUVs, Hatchbacks, Trucks Payment Model: Subscription Fees, Commission-based, Listing Fees, Transaction Fees |
| Companies Covered | Carvana, CarMax, TrueCar, Cars.com, Guazi, Uxin, Renrenche, AutoTrader, Carsome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Second-Hand Car Trading Service Market Shifts & Advancements
Digital retail infrastructure is rewiring how trust is manufactured in high-value peer-to-peer transactions, compressing the traditional inspection-test drive-negotiation sequence into single-session completions.
Computer vision damage assessment is overtaking physical inspector dispatch as the default condition verification method. Fleet sellers in the United States now upload 360-degree imagery for instant AI scoring. This compression eliminates 48-hour scheduling delays and expands addressable inventory beyond metropolitan radii.
REACH chemical compliance is extending from manufacturing into refurbishment operations. EU platforms must now document substance restrictions in cleaning agents and interior treatments applied during reconditioning. German listing services are front-loading compliance costs to secure Green Deal-aligned certification badges.
Buyer aggregation through mobile-native interfaces is fragmenting traditional dealership foot traffic. Younger demographics in China complete entire transactions through super-app integrations without visiting physical locations. This channel shift forces legacy operators to rebuild customer acquisition around platform API partnerships rather than lot visibility.
Global Online Second-Hand Car Trading Service Market Segmentation
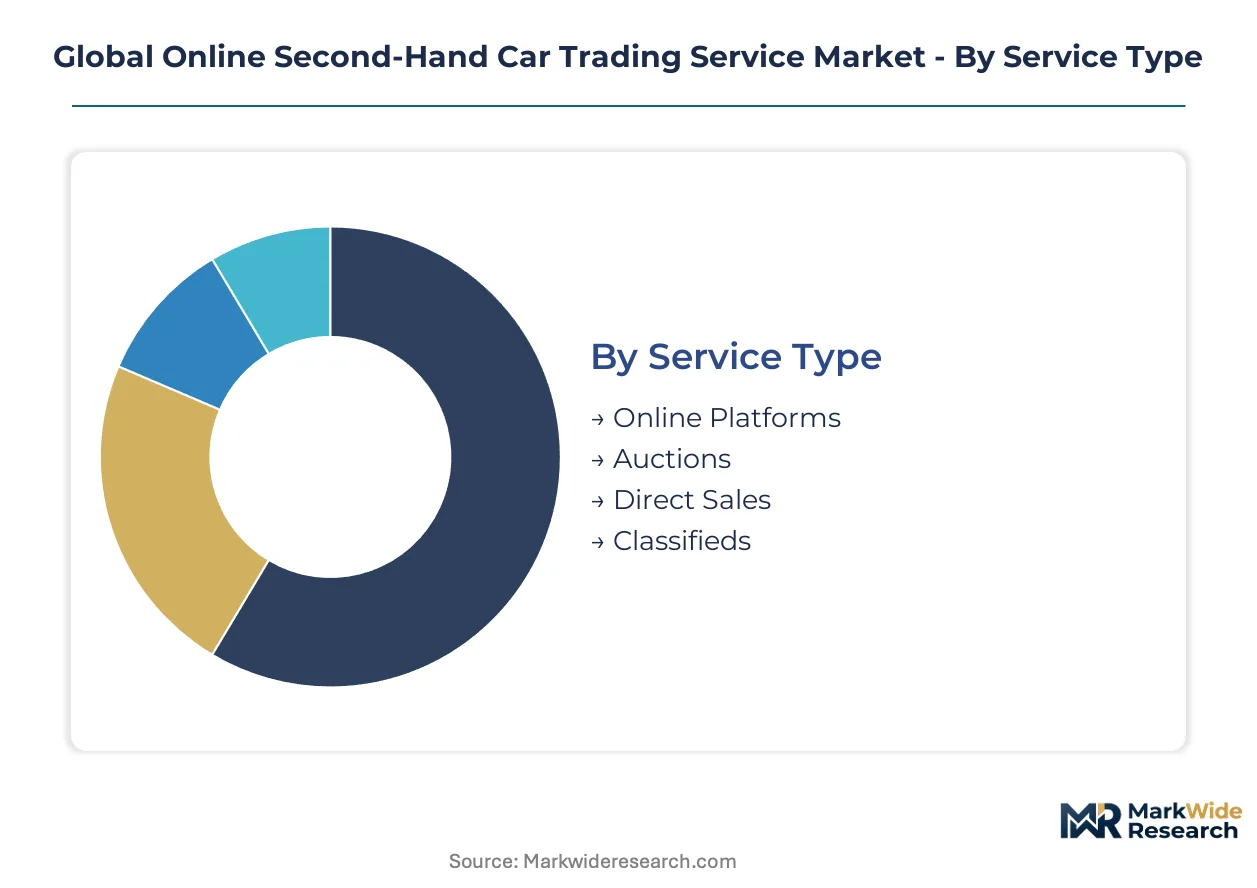
Segmentation in online second-hand car trading reveals how platform economics fragment across transaction mechanisms and buyer profiles. Each dimension exposes distinct margin structures and regulatory exposure that shape competitive positioning.
Service Type:
Buyer trust thresholds determine which transaction format captures volume versus premium economics.
- Online Platforms:Vertically integrated marketplaces combine algorithmic pricing, remote inspection, and logistics fulfillment. Demand concentrates in the United States and Germany among first-time buyers seeking same-day delivery guarantees and standardized return policies.
- Auctions:Time-bound competitive bidding systems aggregate dealer-to-dealer and fleet liquidation volume. Wholesale pricing transparency attracts dealership networks in China facing SAMR scrutiny on algorithmic concentration.
- Direct Sales:Manufacturer-certified pre-owned programs bypass intermediary platforms entirely. OEM control over refurbishment standards appeals to risk-averse corporate procurement officers.
- Classifieds:Listing-only services shift inspection and payment risk to transacting parties. Peer-to-peer cost minimization sustains adoption in price-sensitive emerging markets.
Volume sits with Online Platforms; growth tilts toward Auctions as fleet electrification accelerates wholesale turnover cycles.
Customer Type:
Acquisition cost economics separate high-frequency institutional sellers from episodic individual listers.
- Dealerships:Franchise and independent dealers seek predictable customer acquisition costs through subscription access models. German dealership density makes this segment the primary revenue anchor for platform pricing power.
- Individuals:Single-vehicle sellers prioritize listing simplicity and price discovery over speed. Mobile-native interfaces in China aggregate this fragmented supply through super-app integrations.
- Rental Agencies:Fleet rotation programs generate standardized inventory with complete maintenance histories. Defleet timing synchronization creates volume spikes that strain platform logistics capacity.
- Corporate Clients:Employee benefit and executive vehicle programs demand bulk disposal with audit-compliant documentation. ESG reporting requirements in the EU favor platforms with carbon footprint tracking.
Dealerships deliver baseline volume; Corporate Clients are expanding most quickly as fleet electrification mandates accelerate replacement cycles.
Product Type:
Vehicle form factor determines inspection protocol complexity and logistics configuration.
- SUVs:Elevated average selling prices and faster inventory turnover command premium listing placement fees. Family transportation demand in the United States sustains this segment's margin contribution.
- Sedans:Standardized dimensions simplify remote condition assessment and long-haul transport pricing. Commuter vehicle replacement cycles in Germany concentrate volume in this category.
- Hatchbacks:Compact urban footprint appeals to first-time buyers in dense Chinese metropolitan areas. Parking constraint compatibility drives platform algorithmic promotion.
- Trucks:Commercial utility specifications require specialized inspector training and regional buyer matching. Small business procurement in North American secondary cities sustains niche platform development.
Sedans retain transaction frequency leadership; SUVs gain share fastest as platform algorithms optimize for gross merchandise value per listing.
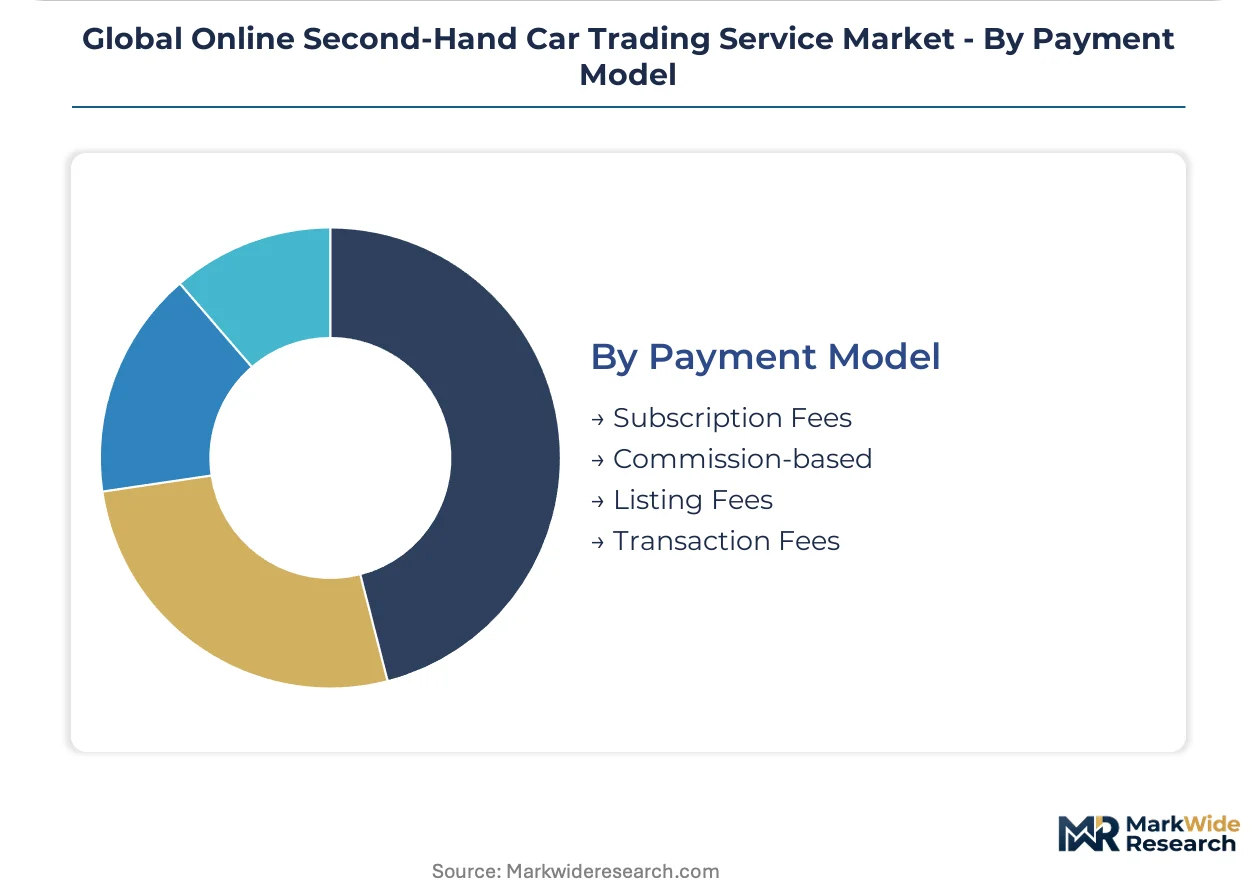
Payment Model:
Revenue predictability trades off against transaction value capture in platform monetization design.
- Commission-based:Percentage-of-transaction pricing aligns platform incentives with seller success. High-value SUV and truck sales in the United States maximize this model's yield per unit.
- Subscription Fees:Fixed monthly charges attract volume sellers seeking customer acquisition cost certainty. German dealership subscription penetration exceeds other geographies due to market maturity.
- Listing Fees:Upfront placement charges shift risk to sellers in volatile demand environments. Price discovery platforms in fragmented markets rely on this structure.
- Transaction Fees:Payment processing and escrow services generate ancillary revenue independent of vehicle value. Cross-border trade complexity in Europe drives adoption of bundled financial services.
Commission-based structures dominate current revenue; Subscription Fees show steepest expansion trajectory as dealership software integration deepens platform stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate cross-border vehicle re-export activity. Special economic zones in Shanghai and Dubai accelerate platform logistics hub development. Tax-advantaged trading corridors in Rotterdam and Singapore anchor European and Asia-Pacific inventory circulation.
United States
First-time buyer preference for same-day delivery drives platform density in metropolitan corridors. The EPA enforces emissions disclosure requirements that shape vehicle eligibility standards. Phoenix and Dallas anchor Carvana's vertically integrated logistics network with same-day fulfillment guarantees.
Germany
Dealership subscription models attract volume sellers seeking predictable customer acquisition costs. The EU Green Deal mandates circularity compliance through carbon footprint tracking and refurbishment certification. Berlin and Hamburg concentrate platform engineering talent for algorithmic pricing development.
China
Super-app integration enables complete transaction completion without physical lot visits. SAMR monitors antitrust compliance as platform consolidation accelerates algorithmic pricing control. Beijing and Shanghai dominate Guazi's AI-powered vehicle condition scoring operations.
United Kingdom
Digital retail adoption among younger demographics compresses traditional inspection-negotiation cycles. GDPR compliance requirements shape customer data handling in platform matching engines. London anchors AutoTrader's marketplace technology development for European expansion.
Japan
Corporate fleet electrification mandates accelerate replacement cycle timing for platform inventory. METI standards govern remote inspection protocol certification for cross-regional transactions. Tokyo and Osaka concentrate auction platform technology for dealer-to-dealer wholesale volume.
Global Online Second-Hand Car Trading Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across transaction format segments. The vendor base stratifies between vertically integrated marketplaces, listing-only classifieds, and auction-based wholesale platforms. Three archetypes dominate: algorithmic pricing engines with captive logistics, super-integrated consumer interfaces, and dealer-facing wholesale aggregators. Capacity expansion in fulfillment networks and strategic API partnerships with legacy dealership management systems represent the dominant competitive moves.
Within the vertically integrated marketplace tier, Carvana and CarMax exemplify divergent approaches to logistics ownership and inventory risk positioning. Guazi occupies a distinctive position in China's peer-to-peer segment through AI-native condition assessment protocols. These three anchors demonstrate how geographic market maturity and regulatory density shape platform architecture choices.
| Leading Market Players |
|---|
| Carvana |
| CarMax |
| TrueCar |
| Cars.com |
| Guazi |
| Uxin |
| Renrenche |
| AutoTrader |
| Carsome |
| Others |
Supply & Pricing Matrix
The EU Green Deal's circularity mandates gate qualified supply and premium-tier pricing access, compelling platforms to front-load carbon footprint tracking and refurbishment certification costs. Compliant inventory commands algorithmic promotion priority and faster turnover velocity, while non-certified listings face demotion or exclusion from European marketplaces entirely.
Pricing Analysis
Short lead-time guarantees extract premium placement fees from sellers seeking same-day delivery commitments, while spot inventory without logistics integration trades at discounted rates. Commission-based structures dominate transaction economics, with price differentiation driven by vehicle condition certification tier and geographic delivery radius. Cost compression in rapid fulfillment networks intensifies margin pressure as diesel volatility erodes fixed-price delivery promises. Individual sellers exhibit highest price sensitivity, prioritizing listing simplicity over speed premiums; corporate fleet clients accept elevated fees for audit-compliant documentation bundles.
Supply Chain Analysis
Certified inspector availability constrains platform expansion in Germany, Japan, and the United States, where remote assessment protocols demand technicians trained in automotive diagnostics and digital documentation standards. Vehicle sourcing draws from fleet defleet programs, dealership trade-ins, and peer-to-peer listings, with logistics capacity resting on diesel-powered long-haul transport and last-mile delivery partnerships. Single-source vulnerability in AI-powered condition scoring algorithms creates concentration risk as platform consolidation accelerates. Distribution runs through vertically integrated fulfillment networks in metropolitan corridors and third-party logistics partnerships in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform logistics capacity serves as the binding constraint propping pricing power, with certified inspector scarcity and fulfillment network density limiting supply elasticity across all major markets.
For Market Incumbents: Lock in exclusive API partnerships with legacy dealership management software providers to entrench switching costs before regulatory deadlines for algorithmic transparency arrive. Deepen backward integration into refurbishment facilities in Germany and the United States to capture Green Deal-compliant certification margins that non-integrated competitors forfeit.
For New Entrants and Emerging Players: Super-app developers in Southeast Asia and Latin America represent the most penetrable channel partnership avenue for bypassing established platform infrastructure. Target price-sensitive individual sellers in fragmented emerging markets through listing-fee minimization and mobile-native interfaces, leveraging algorithmic pricing transparency as differentiation against opaque incumbent models.
For Investors and Strategic Acquirers: SAMR approval of vertical mergers in China is the leading indicator that algorithmic pricing control will concentrate among three to four national platforms, compressing valuation multiples for subscale regional operators. Long-term viability hinges on logistics network ownership rather than marketplace liquidity alone. Watch for EPA emissions disclosure rule expansion beyond California as the signal that interstate listing standardization will favor platforms with compliance infrastructure already deployed.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Condition Scoring Deployment | Computer vision standardization reduces inspector dispatch costs and compresses transaction cycles below 24 hours. |
| Blockchain Title Verification Integration | Distributed ledger connectivity with state DMV databases cuts fraud exposure in high-value cross-state transactions. |
| Subscription Fee Model Expansion | Fixed monthly charges attract German dealership volume seeking predictable customer acquisition cost structures. |
| Carbon Footprint Tracking Implementation | EU Green Deal compliance badges unlock algorithmic promotion priority and premium buyer segments in Europe. |
| Same-Day Logistics Network Buildout | Vertically controlled fulfillment infrastructure sustains delivery guarantees that third-party partnerships cannot match. |
Research Methodology
Multi-period observation of platform transaction volumes, logistics capacity expansion, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with used-car marketplace executives, fleet procurement directors, automotive refurbishment facility operators, and EU regulatory affairs specialists. Secondary validation drew from EPA enforcement databases, SAMR merger review disclosures, EU Green Deal implementation guidelines, and vehicle registration data from national transport authorities. Bottom-up platform economics modeling triangulated against top-down market size estimates derived from commission-rate analysis and subscription penetration rates.
Input-output matrices mapped transaction volume flows across service type, customer archetype, vehicle segment, and payment model dimensions throughout the forecast period. CAGRs were derived from segmented growth rate assumptions calibrated to observed platform expansion trajectories and regulatory compliance investment cycles. Forecast inputs incorporated fleet electrification replacement timelines, diesel price volatility scenarios, and algorithmic pricing transparency implementation schedules.
Caveats apply where SAMR merger blocking actions, EPA emissions rule expansion, or EU AI Act enforcement timing could materially shift the outlook for platform consolidation and pricing power distribution. Material deviation in these triggers warrants pause and re-evaluation of capacity-constrained supply assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Germany Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
India Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Italy Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Australia Used Car Market