
 US Electric Bus Battery Pack Market | 2026-2036
US Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Bus Battery Pack Market Insights
Battery leasing and service-based procurement is reshaping capital deployment across the US electric bus battery pack value chain. Proterra leverages vertical integration into pack assembly and vehicle integration to control cost structures. LG Energy Solution anchors its position through dedicated US manufacturing capacity and OEM supply relationships. CATL competes via scale advantages in lithium iron phosphate cell chemistry tailored to transit duty cycles.
A US electric bus battery pack integrates electrochemical cells, thermal management systems, and battery management electronics into a chassis-mounted energy storage unit, typically delivering 100 kWh to 400 kWh for single-charge route coverage. Lithium-ion chemistry dominates installed base economics due to proven cycle life and established recycling pathways. Solid-state configurations represent the fastest-growing technology segment as manufacturers pursue higher energy density for extended-range routes. Public transport agencies command the largest share of end-user demand, though school districts are emerging as a high-growth buyer category under federal electrification programs.
Federal Transit Administration Buy America requirements, EPA Clean School Bus grant rules, and NHTSA lithium-ion battery safety standards collectively dictate domestic content thresholds and testing protocols for pack suppliers. State-level zero-emission mandates in California and New York further compress procurement timelines for transit operators. Stakeholders must track evolving domestic content percentages and cell qualification timelines to secure program eligibility and avoid supply disqualification.
Market Dynamics
EPA Clean School Bus funding and FTA Buy America content thresholds are compressing procurement timelines while forcing domestic cell-to-pack integration investments across US transit agencies and school districts.
Growth Catalysts
- EPA Clean School Bus Program:Federal grants covering up to 100% of electric bus and battery costs are accelerating zero-emission conversions in California, Texas, and Florida school districts.
- State Zero-Emission Mandates:California Air Resources Board and New York State regulations require full fleet electrification by 2040, locking in long-term battery procurement pipelines.
- Lithium Iron Phosphate Chemistry:Improved thermal stability and extended cycle life under high-frequency transit duty cycles are displacing nickel-manganese-cobalt configurations in route planning decisions.
Market Restraints
- Domestic Cell Manufacturing Concentration:Limited US-based lithium-ion cell production forces pack assemblers to absorb tariff exposure on imported electrodes from South Korean and Chinese suppliers.
- NHTSA Thermal Runaway Testing:Extended certification timelines for cell-to-pack architectures delay program eligibility for transit agencies operating under compressed federal grant windows.
- Raw Material Price Volatility:Lithium carbonate and nickel sulfate spot market fluctuations compress gross margins for fixed-price municipal contracts spanning 10-15 year service agreements.
Strategic Opportunities
- Texas and Florida School Districts:Underpenetrated markets relative to California present first-mover advantages for battery-as-a-service providers targeting EPA funding tranches through 2027.
- Battery Leasing Models:Capital-light procurement structures separate pack ownership from vehicle acquisition, unlocking municipal budgets previously constrained by upfront replacement costs.
- Solid-State Chemistry Convergence:Next-generation electrolyte and ceramic separator integration promises 400+ kWh configurations for extended rural routes currently excluded from electrification.
Industry Challenges
- Battery Management Systems Engineering:Scarce firmware talent capable of integrating thermal runaway detection with vehicle telematics extends development cycles for mid-tier pack assemblers.
- FTA Bus Testing Protocol Compliance:Altoona durability testing and structural integrity validation add 18-24 months to product qualification timelines, misaligning with grant application deadlines.
- End-of-Life Recycling Infrastructure:Limited US-based hydrometallurgical recovery capacity for lithium iron phosphate cells creates stranded asset risk under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Bus Battery Pack Market |
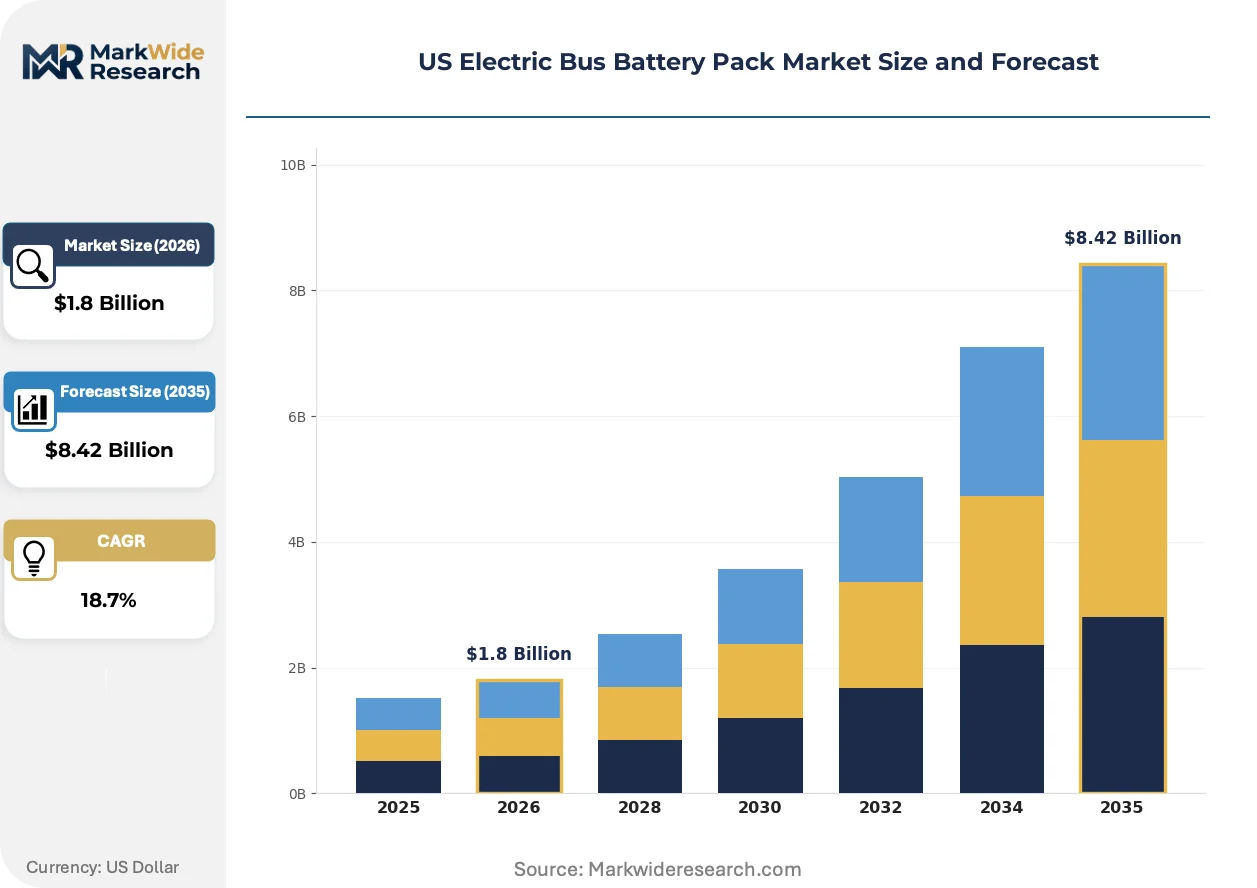
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Solid-state, Nickel-metal Hydride End User: Public Transport, Private Operators, School Districts, Fleet Managers Charging Technology: Fast Charging, Standard Charging, Wireless Charging, Opportunity Charging Capacity: 100 kWh, 200 kWh, 300 kWh, 400 kWh |
| Companies Covered | SK Innovation, CATL, LG Energy Solution, XALT Energy, Proterra, Panasonic Energy, BYD, WattEV, Samsung SDI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Bus Battery Pack Market Trends and Innovations
Cell chemistry diversification and thermal management architecture evolution are compressing pack design cycles while federal procurement rules force supply chain reconfiguration toward domestic electrode sourcing.
Solid-state battery configurations are hybridizing conventional liquid electrolyte systems with ceramic separator layers to achieve energy densities exceeding 300 Wh/kg. Transit agencies in California and New York are piloting these packs for 300-mile daily routes. The technology is hybridizing procurement specifications as agencies rewrite RFPs around range assurance rather than capital cost minimization.
NHTSA battery safety standards and FTA Buy America requirements are tightening in parallel, mandating domestic cell assembly percentages that rise through 2029. Pack suppliers must requalify supply chains or face program disqualification. California transit operators are responding fastest, locking in joint ventures with South Korean cell makers for US-based electrode coating capacity.
Service-based battery procurement is displacing traditional capital purchase models across municipal transit agencies. Third-party ownership structures transfer degradation risk and residual value exposure to specialized fleet operators. This shift concentrates most visibly in school districts navigating EPA Clean School Bus grant administration complexity.
US Electric Bus Battery Pack Market Segmentation
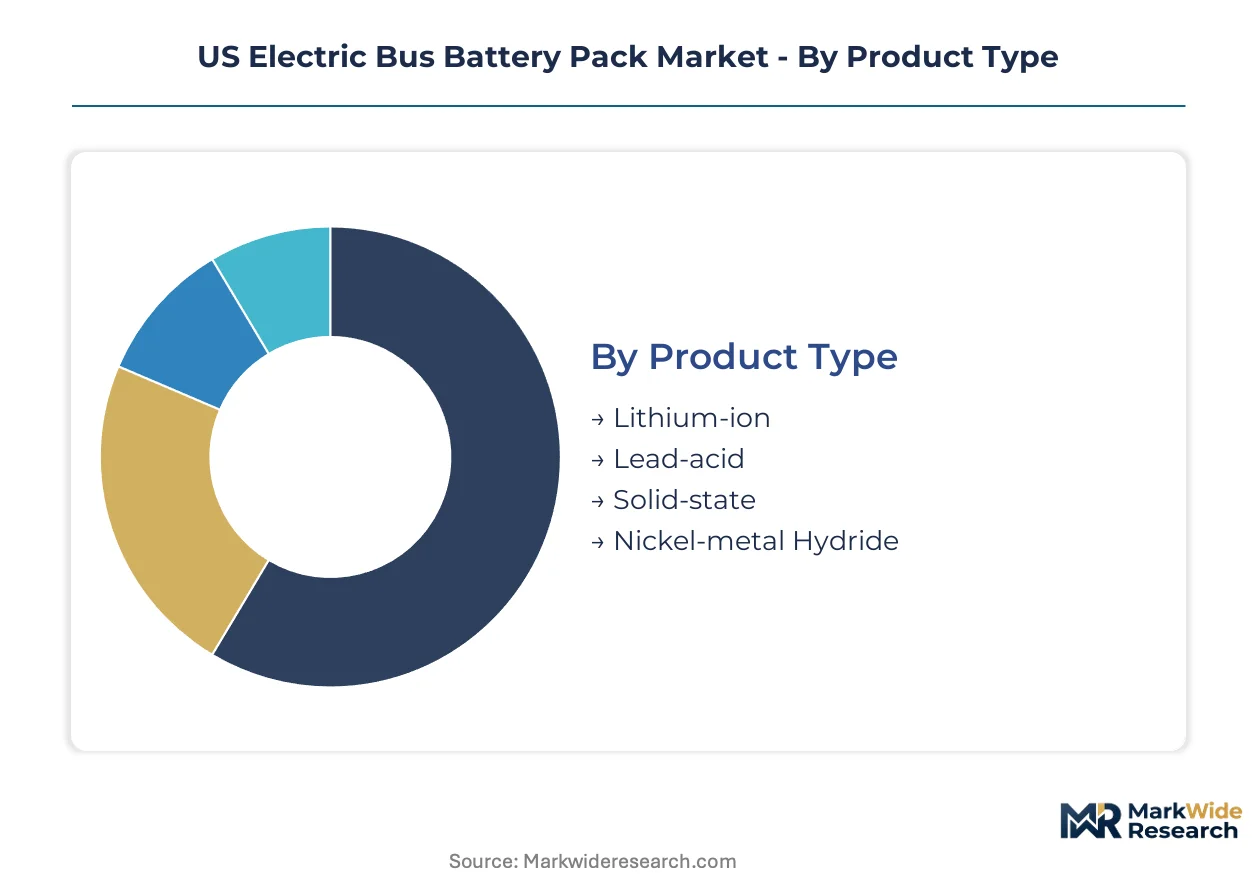
Segmentation in the US electric bus battery pack market reveals how procurement priorities diverge across chemistry types, operational duty cycles, and ownership structures. Transit agencies, school districts, and private fleet operators each impose distinct performance specifications that reshape pack design and supplier qualification pathways.
Product Type:
Mature lithium-ion architectures anchor current deployments while emerging solid-state configurations promise step-change improvements in energy density and thermal stability.
- Lithium-ion:Dominant cell chemistry integrates lithium iron phosphate or nickel-manganese-cobalt cathodes with liquid electrolyte systems, delivering 150-250 Wh/kg energy density. California transit agencies specify these packs for high-frequency urban routes where proven cycle life and established recycling infrastructure reduce total cost of ownership calculations.
- Solid-state:Ceramic electrolyte and lithium metal anode architectures achieve 300+ Wh/kg density, enabling 400 kWh configurations for extended rural routes. New York State pilot programs are qualifying these packs for 300-mile daily operations where liquid electrolyte thermal management adds weight and complexity.
- Lead-acid:Legacy chemistry persists in limited school district retrofits and auxiliary power applications where capital constraints override performance requirements.
- Nickel-metal Hydride:Mature technology retains niche presence in hybrid-electric conversions and cold-climate deployments where proven low-temperature performance outweighs energy density limitations.
Lithium-ion handles the majority of throughput; solid-state is expanding most quickly on share as federal grant programs extend eligibility to next-generation chemistries.
End User:
Customer type segmentation tracks how capital availability, federal funding access, and operational complexity reshape procurement patterns across municipal and commercial ownership structures.
- Public Transport:Municipal transit agencies command the largest installed base, operating 200+ bus fleets under California Air Resources Board and New York State zero-emission mandates. These buyers prioritize 12-15 year service life warranties and domestic content compliance for FTA Buy America eligibility.
- School Districts:EPA Clean School Bus Program grants covering up to 100% of electric bus and battery costs are accelerating zero-emission conversions in Texas and Florida districts previously constrained by capital budgets. Procurement complexity favors battery-as-a-service structures that transfer degradation risk to third-party owners.
- Private Operators:Commercial fleet owners in airport shuttle and corporate campus applications emphasize rapid charge compatibility and modular pack replacement to minimize vehicle downtime.
- Fleet Managers:Third-party vehicle management companies aggregate demand across multiple municipal clients, standardizing on 200-300 kWh configurations to simplify maintenance training and spare parts inventory.
Public transport absorbs the dominant share of pack volume; school districts are climbing the fastest as federal funding tranches extend through 2027.
Charging Technology:
Charging infrastructure segmentation reflects how route planning, depot constraints, and grid interconnection capacity dictate power delivery architecture selection.
- Fast Charging:150-350 kW DC systems enable mid-route energy replenishment for high-frequency corridors, requiring packs with enhanced thermal management and higher C-rate tolerance. California transit agencies deploy these along priority bus rapid transit corridors.
- Opportunity Charging:Pantograph or inductive systems at route terminals allow smaller pack sizes and extended vehicle range without depot infrastructure expansion. Texas school districts are piloting these for rural routes where depot electrical upgrades face utility interconnection delays.
- Standard Charging:Overnight AC or low-power DC charging at depots remains the default for fleets with predictable duty cycles and sufficient dwell time.
- Wireless Charging:Inductive pad systems embedded in roadways or depot parking enable automated charging without connector wear, though capital costs limit deployment to premium corridor demonstrations.
Fast charging carries the heaviest utilization in dense urban corridors; opportunity charging is gaining share fastest where depot infrastructure constraints block standard deployment.
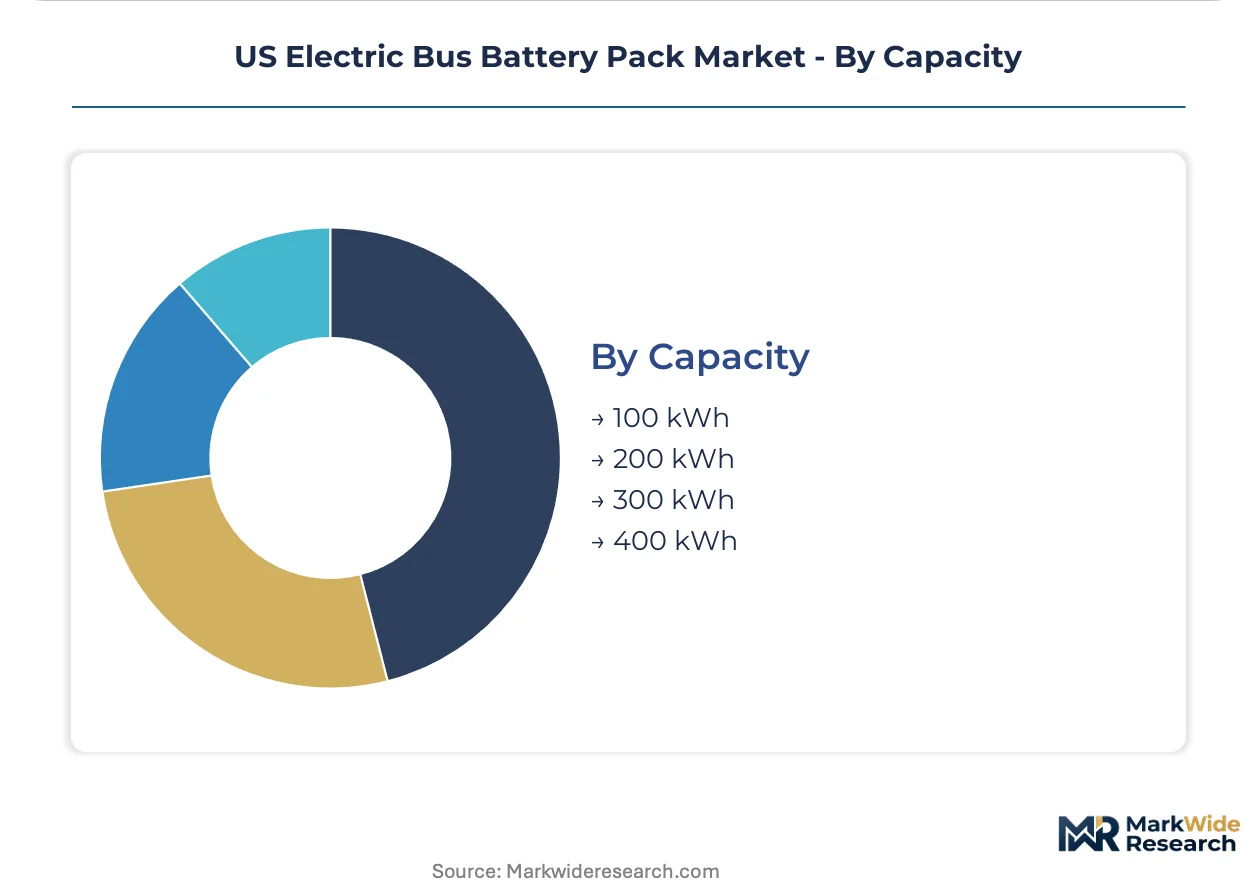
Capacity:
Energy storage segmentation aligns with route length, climate conditions, and heating-cooling loads that determine daily kWh consumption per vehicle.
- 300 kWh:Standard configuration for California transit agencies operating 150-200 mile daily routes with air conditioning loads and grade variations. These packs balance vehicle weight against range assurance requirements in NHTSA safety testing protocols.
- 200 kWh:Mid-size packs serve Florida school districts with moderate route lengths and milder climate loads, enabling lower vehicle purchase prices while maintaining EPA Clean School Bus grant eligibility.
- 100 kWh:Compact configurations support shuttle and circulator applications with predictable short-loop operations and opportunity charging access.
- 400 kWh:Extended-range packs address rural Texas routes exceeding 250 miles daily, where charging infrastructure gaps and extreme temperature swings demand oversized energy reserves.
300 kWh configurations handle the majority of new deployments; 400 kWh packs show the steepest expansion trajectory as electrification extends beyond urban cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transit agencies and school districts cluster procurement decisions around EPA funding availability and state-level electrification mandates, creating distinct demand pockets across sub-regional markets.
California
Los Angeles County Metropolitan Transportation Authority and San Francisco Bay Area transit operators anchor the nation's largest electric bus deployment pipeline. California Air Resources Board zero-emission mandates require full fleet conversion by 2040, compressing procurement timelines for battery pack suppliers. Silicon Valley and Los Angeles industrial corridors host joint ventures between South Korean cell manufacturers and domestic pack assemblers seeking FTA Buy America compliance.
Texas
Houston Independent School District and Dallas Area Rapid Transit represent underpenetrated demand relative to California, with EPA Clean School Bus grants covering up to 100% of conversion costs. State energy regulators have streamlined utility interconnection for depot charging infrastructure, reducing deployment friction for rural school districts. Austin and San Antonio transit agencies are piloting 400 kWh extended-range configurations for suburban commuter routes.
New York
Metropolitan Transportation Authority operates North America's largest municipal bus fleet under state-mandated electrification deadlines. New York State Energy Research and Development Authority funding supplements federal grants for upstate transit operators serving colder climate corridors. Buffalo and Rochester industrial zones are attracting pack assembly investments to serve cross-border Canadian transit demand.
Florida
Miami-Dade County Public Schools and Orange County Public Schools lead southeastern procurement under EPA funding tranches extending through 2027. Florida Power & Light has prioritized electrical infrastructure upgrades at district depots, enabling faster deployment than utility-constrained markets. Tampa and Orlando transit agencies specify 200 kWh mid-size packs optimized for moderate climate loads and shorter route profiles.
Illinois
Chicago Transit Authority's electric bus pilot programs influence procurement specifications across Midwest transit agencies. Illinois Environmental Protection Agency state-level funding bridges gaps in federal grant coverage for smaller municipal operators. Rockford and Peoria school districts are emerging as early adopters for battery-as-a-service structures that transfer degradation risk to third-party fleet managers.
US Electric Bus Battery Pack Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around domestic content compliance and long-term service contracts. The competitive landscape tiers into three strategic archetypes: vertically integrated vehicle OEMs with captive pack production, dedicated battery manufacturers with US-based cell assembly, and third-party pack integrators serving retrofit and aftermarket demand. Capacity expansion and strategic partnerships dominate competitive moves as firms position for FTA Buy America threshold increases through 2029.
Within the dedicated battery manufacturer tier, LG Energy Solution anchors its position through Korean-US joint venture structures for electrode coating capacity, while CATL represents scale-driven LFP chemistry specialization. SK Innovation occupies a position within the premium-tier vector for high-nickel cell configurations. These three exemplify how foreign cell makers are reconfiguring supply chains to meet domestic content requirements without ceding technology control.
| Leading Market Players |
|---|
| SK Innovation |
| CATL |
| LG Energy Solution |
| XALT Energy |
| Proterra |
| Panasonic Energy |
| BYD |
| WattEV |
| Samsung SDI |
| Others |
Pricing and Supply Chain Analysis
Port of Long Beach container freight corridors govern landed cost differentials between South Korean electrode suppliers and domestic pack assemblers, concentrating pricing power among vertically integrated producers while forcing tiered cost pass-through structures across municipal procurement tiers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lithium carbonate and nickel sulfate benchmarks dominate municipal transit agreements spanning 10-15 year service terms. Price differentiation separates FTA Buy America-compliant domestic cell assemblies from imported electrode configurations facing tariff exposure. Pricing pressure stems from fixed-price municipal obligations confronting raw material spot volatility. School districts operating under EPA Clean School Bus grants exhibit highest price sensitivity, while California transit agencies with dedicated electrification budgets show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for pack assemblers sourcing lithium iron phosphate cathodes and graphite anodes. Cell production concentrates in China, South Korea, and Japan, with electrode coating capacity expanding through Korean-US joint ventures near Detroit and Atlanta. The supply chain rests on lithium carbonate from Chilean and Australian mining operations, plus nickel sulfate from Indonesian processing facilities. Distribution runs through OEM direct contracts and third-party pack integrators serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service revenue layers expand faster than hardware sales as degradation risk transfer becomes the dominant procurement mechanism across EPA-funded school district conversions.
For Market Incumbents: Harden domestic electrode coating capacity through Korean joint venture structures near Detroit industrial corridors to preempt FTA Buy America threshold escalations. Secure NHTSA thermal runaway certification pipelines ahead of compressed grant windows to maintain program eligibility. Lock in 12-15 year service warranties that transfer residual value risk away from municipal balance sheets. For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida school districts where EPA Clean School Bus penetration lags California benchmarks. Target battery leasing structures that absorb degradation risk and simplify grant administration for capital-constrained rural operators. Lead with firmware-integrated thermal management systems that compress qualification timelines relative to incumbent offerings. For Investors and Strategic Acquirers: Pack integrators with captive battery management system firmware capabilities represent the most defensible acquisition archetype as software-defined thermal control displaces commodity assembly margins. Long-term viability hinges on service contract renewal rates rather than hardware shipment volumes. Monitor NHTSA rulemaking timelines for cell-to-pack certification requirements as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Electrode Coating Joint Venture | Korean cell makers partner with US pack assemblers near Detroit to satisfy FTA Buy America thresholds. |
| Battery-as-a-Service Platform Launch | Third-party ownership structures transfer degradation risk from Texas school districts to specialized fleet operators. |
| Solid-State Chemistry Pilot Program | New York State transit agencies qualify 300+ Wh/kg configurations for extended rural route coverage. |
| Thermal Management Firmware Acquisition | Pack integrators acquire scarce battery management system engineering talent to compress development cycles. |
| End-of-Life Recycling Infrastructure Investment | Hydrometallurgical recovery capacity for lithium iron phosphate cells addresses stranded asset risk under producer responsibility frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA grant disbursement records, FTA Buy America compliance filings, NHTSA safety certification databases, and lithium carbonate spot market data from London Metal Exchange. Primary interviews engaged transit agency procurement directors, school district fleet managers, pack assembler operations heads, and South Korean cell manufacturer US subsidiary executives. Bottom-up unit deployment estimates triangulate against top-down federal funding allocation analysis.
Forecast inputs incorporate cell chemistry adoption curves, route electrification feasibility by climate zone, and utility interconnection capacity constraints across depot infrastructure. Segmentation dimensions span product type, end user category, charging technology, and energy capacity tier. CAGRs derive from logistic diffusion modeling of municipal procurement cycles aligned with regulatory mandate deadlines. Federal grant program renewal probability and domestic content threshold escalation schedules inform trajectory sensitivity.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, nickel sulfate supply disruptions, or utility interconnection queue delays would shift the trajectory. Forecasts reflect documented assumptions regarding FTA Buy America compliance timelines and NHTSA certification pathway stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
South America E-Bike Market