
 Marine Chronometers Market | 2026-2036
Marine Chronometers Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Chronometers Market Foresight
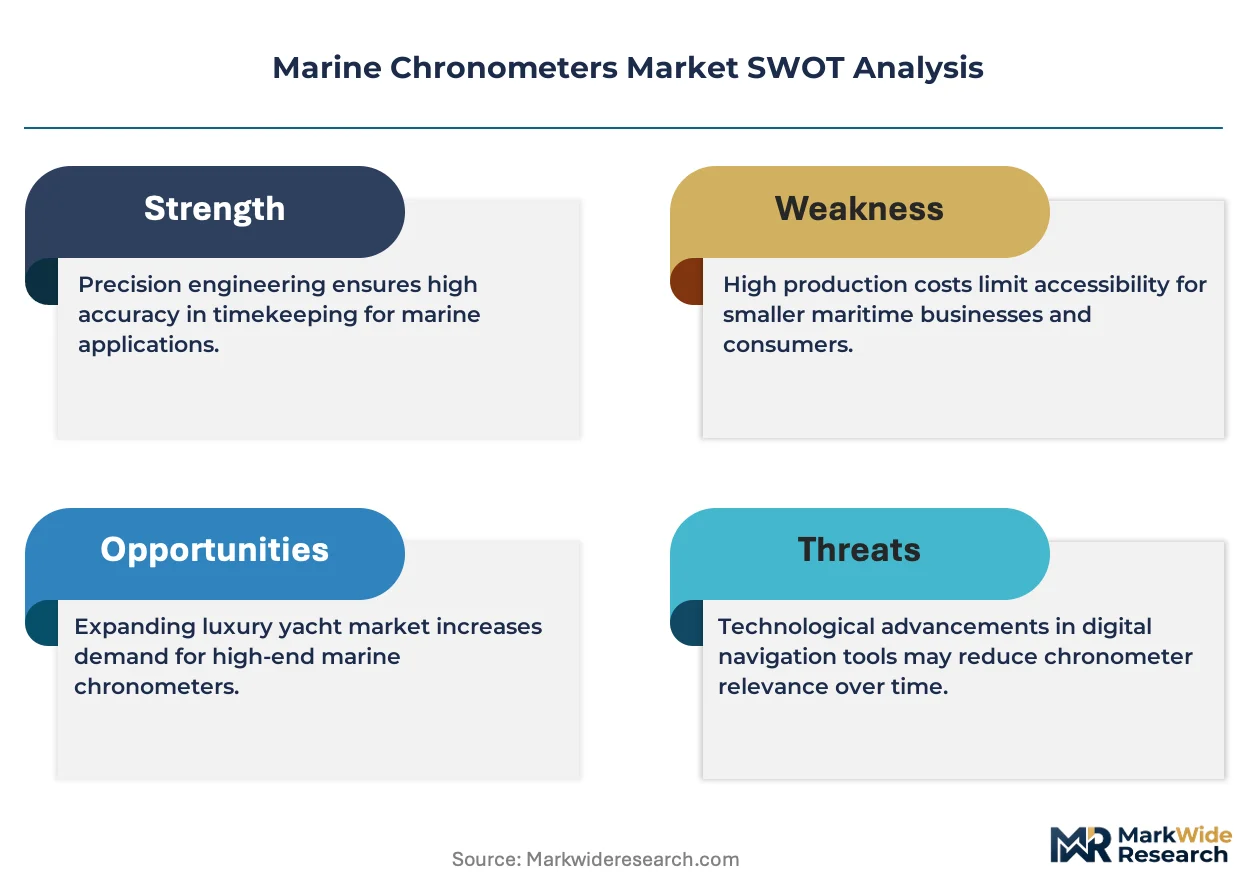
ISO 3159 certification is bifurcating the competitive landscape between heritage manufactures and newer entrants. Rolex SA leverages its in-house chronometer testing protocols to sustain premium positioning. Omega SA anchors its maritime credibility through extended service networks for naval clients. Ulysse Nardin competes on marine heritage, occupying a distinct niche in expedition-grade timepieces.
Marine chronometers are precision timekeeping instruments engineered to maintain accuracy within fractions of a second per day despite vessel motion, temperature variation, and magnetic interference, traditionally employing spring-driven escapements or modern quartz oscillators stabilized against gimbal-mounted platforms. Mechanical product types retain dominance in heritage and ceremonial applications where collectors and naval institutions prize traditional craftsmanship, while electronic segments capture operational deployments prioritizing maintenance simplicity and GPS synchronization. Research applications exhibit the fastest structural expansion as oceanographic institutions demand synchronized sensor arrays for deep-sea mapping.
The EU Marine Equipment Directive and ISO 3159 standards govern market access for chronometers deployed on European-flagged vessels, while the US Coast Guard enforces carriage requirements for certified timepieces aboard commercial shipping. Switzerland's METI-equivalent horological oversight and Germany's KBA maritime equipment protocols further fragment compliance obligations across manufacturing jurisdictions. Stakeholders must monitor evolving certification reciprocity agreements between flag states and classification societies.
Market Dynamics
ISO 3159 certification requirements are forcing a structural split between heritage mechanical manufacturers and quartz-based entrants, as naval procurement officers now mandate traceable accuracy documentation for all bridge-mounted timepieces.
Growth Catalysts
- NATO Naval Modernization:Defense procurement programs across member states are mandating certified chronometers for new vessel classes, creating institutional demand for precision timekeeping infrastructure.
- EU Marine Equipment Directive:Revised compliance frameworks are accelerating replacement cycles for aging shipboard equipment, compelling fleet operators to upgrade to certified instruments.
- Oceanographic Sensor Synchronization:Deep-sea research institutions require sub-second timing accuracy across distributed instrument arrays, driving specialized chronometer deployment.
Market Restraints
- Precision Manufacturing Concentration:The Jura Arc region controls critical escapement machining expertise, creating single-point vulnerability for mechanical chronometer supply.
- Raw Material Volatility:Nickel-iron alloy prices for balance springs fluctuate with stainless steel feedstock markets, compressing margins on heritage product lines.
- Quartz Substitution Pressure:GPS-disciplined oscillators deliver equivalent accuracy at fractional maintenance cost, eroding addressable market for traditional spring-driven mechanisms.
Strategic Opportunities
- Research Vessel Retrofit Cycles:University-operated fleets in Norway and Germany face aging bridge equipment, creating replacement demand for certified electronic chronometers.
- Dual-Technology Hybrid Platforms:Manufacturers combining mechanical display with quartz oscillator core can satisfy ceremonial requirements while meeting operational accuracy standards.
- Service Network Unbundling:Independent calibration laboratories in Hamburg and Rotterdam are capturing aftermarket maintenance revenue previously held by original manufacturers.
Industry Challenges
- Master Horologist Scarcity:Assembly of tourbillon escapements requires decade-long training pipelines that Swiss technical institutes struggle to populate.
- Certification Timeline Compression:ISO 3159 testing protocols demand 15-day continuous observation periods, constraining production throughput during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Chronometers Market |
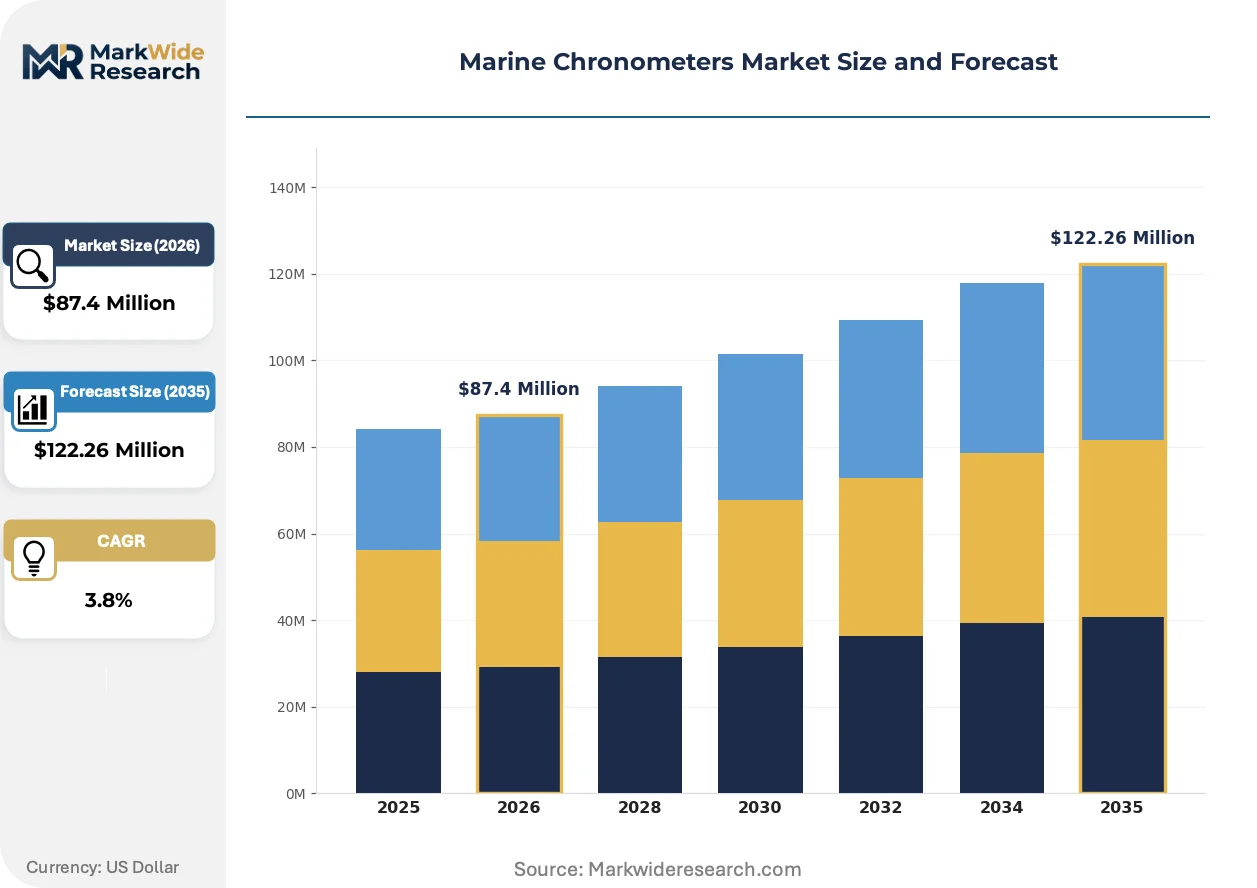
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $122.26 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Hybrid, Quartz Application: Navigation, Timing, Research, Exploration End User: Shipping Companies, Research Institutions, Recreational Boaters, Museums Technology: GPS, Atomic Clocks, Traditional Timekeeping, Digital Display |
| Companies Covered | Rolex SA, Omega SA, Patek Philippe, A. Lange & Söhne, Ulysse Nardin, Glashütte Original, Steinhart, Longines, IWC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Chronometers Market Shifts & Advancements
Digital synchronization protocols are displacing standalone mechanical autonomy as the dominant design paradigm, while heritage craftsmanship commands premium positioning in ceremonial and collector segments.
Atomic clock reference distribution via Ethernet is bifurcating vessel architecture between legacy bridge-mounted chronometers and distributed network time protocol systems. Container shipping operators are adopting IP-based timing infrastructure for integrated navigation suites. This technology compression is eliminating redundant standalone instruments on new-build vessels while preserving mechanical units for regulatory compliance backup.
REACH chemical restrictions on nickel alloy formulations are compelling Swiss manufacturers to reformulate balance spring compositions. The industrial consequence extends production timelines as new metallurgical recipes undergo stability validation. Heritage mechanical segments face the steepest compliance burden, whereas quartz oscillator suppliers utilizing silicon components encounter minimal regulatory friction.
Naval procurement officers are consolidating vendor relationships through framework agreements that bundle chronometer supply with decade-long calibration service contracts. This purchasing concentration displaces transactional spot-buying for individual instruments. The shift is most pronounced in German and French defense procurement, where maintenance cost predictability outweighs upfront capital expenditure minimization.
Marine Chronometers Market Segmentation
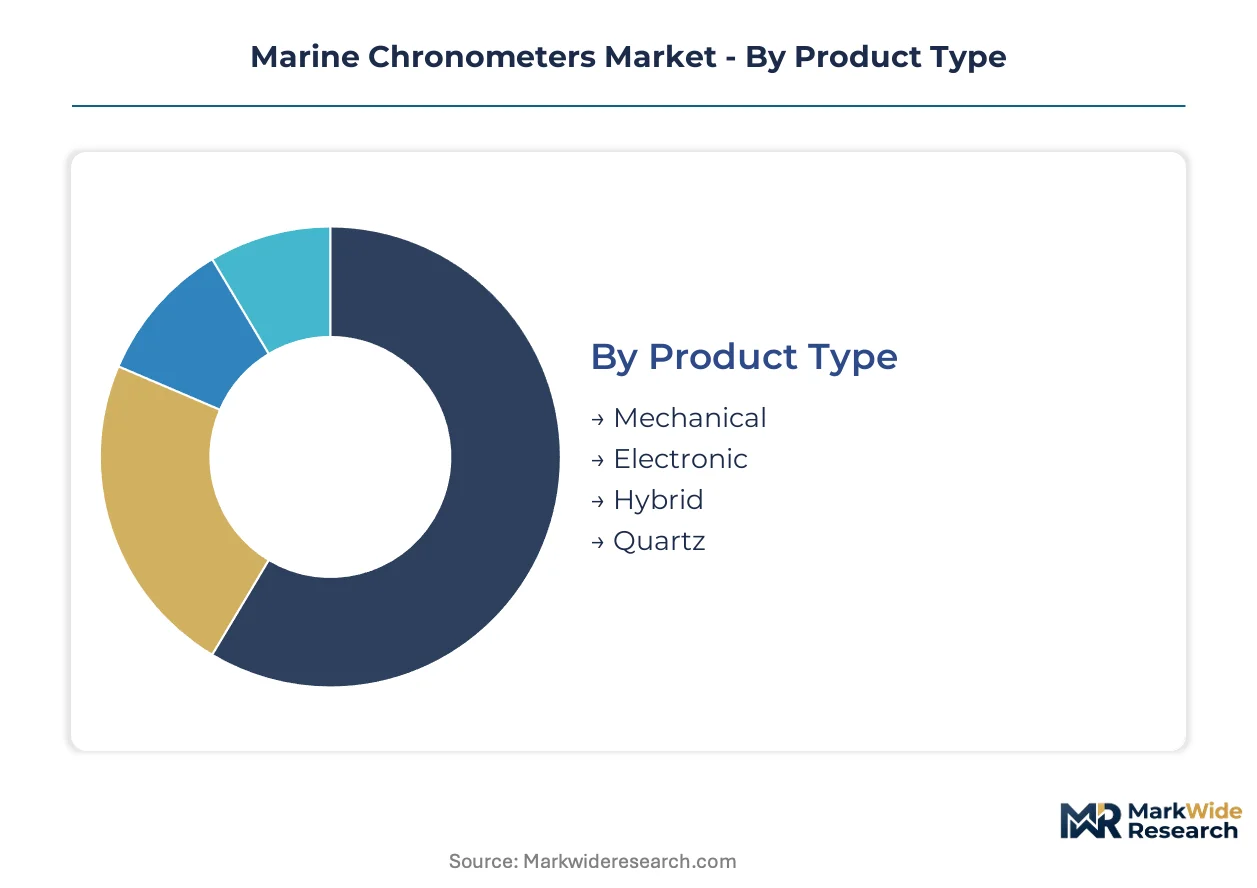
Segmentation in marine chronometers reveals how substitution pressures and certification requirements reshape procurement patterns across naval, commercial, and institutional buyers. Each dimension exposes different vulnerability to GPS-based alternatives and divergent compliance burdens under flag-state regulations.
Product Type:
Electronic and quartz segments face the most acute substitution pressure from GPS-disciplined oscillators, while mechanical chronometers defend niche positions through ceremonial mandates and collector premiums.
- Mechanical:Spring-driven escapements mounted on gimbal-stabilized platforms achieve fractional-second daily accuracy through tourbillon compensation. Swiss Jura Arc manufacturers dominate supply for NATO naval commissioning ceremonies and museum collections, constrained by decade-long horologist training pipelines and REACH nickel-alloy reformulation delays.
- Electronic:Quartz oscillators stabilized against temperature and vibration deliver maintenance simplicity for operational bridge deployment. German and Norwegian research vessel operators prioritize these units for integrated navigation suites, though GPS synchronization is eroding standalone demand.
- Hybrid:Mechanical display dials concealing quartz oscillator cores satisfy dual requirements for traditional aesthetics and modern accuracy.
- Quartz:Standardized oscillator modules with minimal calibration needs capture commercial shipping retrofit cycles.
Mechanical chronometers anchor the volume base in heritage procurement while electronic segments gain share at the steepest rate through defense modernization programs.
Application:
Cost tier stratification separates bridge-critical navigation deployments from discretionary exploration equipment, with research applications commanding premium pricing for sub-second synchronization requirements.
- Navigation:Bridge-mounted chronometers certified to ISO 3159 for dead-reckoning backup when GPS signals degrade. EU-flagged vessels under the Marine Equipment Directive drive replacement demand, particularly among German and French fleet operators consolidating vendor relationships through framework agreements.
- Timing:Distributed time reference distribution across vessel systems via NTP protocols. Container shipping lines in Rotterdam and Hamburg adopt IP-based infrastructure, eliminating redundant standalone instruments on new-builds.
- Research:Oceanographic sensor arrays require synchronized sampling across deep-sea instrument networks. Norwegian university fleets and German marine institutes represent concentrated demand for certified electronic units with traceable accuracy documentation.
- Exploration:Expedition-grade timepieces for private polar and circumnavigation voyages.
Navigation applications dominate current procurement volume while research deployments demonstrate the steepest expansion trajectory as deep-sea mapping investments accelerate.
End User:
Customer type determines contract structure, with institutional buyers favoring decade-long calibration bundles and recreational purchasers driving spot-market transactional volume.
- Shipping Companies:Commercial fleet operators under US Coast Guard and EU Marine Equipment Directive carriage requirements. German and French defense procurement officers mandate certified chronometers with bundled service contracts, displacing spot-buying for individual instruments.
- Research Institutions:University-operated fleets in Norway and Germany face aging bridge equipment replacement cycles. Independent calibration laboratories in Hamburg and Rotterdam capture aftermarket maintenance revenue previously held by original manufacturers.
- Recreational Boaters:Private vessel owners prioritizing cost minimization over certification compliance.
- Museums:Curatorial acquisition of heritage mechanical pieces for horological collections.
Shipping companies provide the revenue foundation while research institutions expand most quickly through synchronized sensor network investments.
Technology:
Supply concentration in atomic clock reference distribution and silicon oscillator manufacturing creates asymmetric margin structures across technology tiers.
- GPS:Satellite-disciplined oscillators delivering equivalent accuracy to mechanical chronometers at fractional maintenance cost. Eroding addressable market for traditional spring-driven mechanisms across commercial shipping segments.
- Atomic Clocks:Cesium or rubidium frequency standards distributing reference signals via Ethernet for distributed vessel architecture. Naval procurement programs across NATO member states specify these for next-generation combat systems.
- Traditional Timekeeping:Mechanical escapement craftsmanship concentrated in Swiss Jura Arc manufacturing clusters. Master horologist scarcity and ISO 3159 certification timeline compression constrain production throughput during demand surges.
- Digital Display:LCD or LED readouts integrated with quartz oscillator cores for operational clarity.
Traditional timekeeping retains ceremonial anchoring while atomic clock distribution climbs the fastest through naval modernization procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Northern European maritime chronometer demand through its container shipping density and research vessel homeporting. German fleet operators under KBA maritime equipment protocols drive replacement cycles for certified bridge instruments.
Germany
Naval modernization programs at Thyssenkrupp Marine Systems generate institutional demand for ISO 3159-certified timepieces. The KBA enforces carriage requirements for commercial shipping under EU Marine Equipment Directive harmonization. Hamburg clusters independent calibration laboratories that now capture aftermarket service revenue from original manufacturers.
Switzerland
Heritage horology manufacturing concentrates in the Jura Arc where century-old escapement expertise supports NATO naval commissioning ceremonies. Swissmedic-equivalent horological oversight governs precision instrument certification for export markets. Geneva and Le Locle host master horologists whose decade-long training pipelines constrain mechanical chronometer throughput during demand surges.
United States
The US Coast Guard mandates certified chronometers aboard commercial vessels under 46 CFR navigation equipment regulations. Norfolk Naval Station procurement officers specify atomic clock reference distribution for next-generation combat systems. Newport News Shipbuilding integrates precision timekeeping infrastructure into nuclear carrier construction programs.
Norway
University-operated research fleets in Bergen and Trondheim require synchronized sensor arrays for deep-sea mapping operations. The Norwegian Maritime Authority aligns certification requirements with EU Marine Equipment Directive standards. Stavanger serves North Sea offshore vessel operators upgrading bridge equipment to meet flag-state compliance deadlines.
France
Direction Générale de l'Armement procurement frameworks bundle chronometer supply with decade-long calibration service contracts. The Port of Le Havre anchors commercial fleet operator demand under ANSM maritime equipment oversight. Brest naval base specifications drive adoption of hybrid mechanical-quartz platforms for ceremonial and operational dual requirements.
Marine Chronometers Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and heritage positioning. The vendor base stratifies between consolidated heritage manufactures with century-old Jura Arc facilities and fragmented quartz-assembly specialists serving commercial retrofit cycles. Three archetypes dominate: tourbillon craftsmen defending ceremonial premiums, quartz module integrators capturing operational volume, and hybrid-platform engineers bridging regulatory compliance with traditional aesthetics. Competitive moves concentrate on framework agreement consolidation for naval procurement and independent calibration laboratory expansion into aftermarket service capture.
Within the heritage craftsmanship tier, Rolex SA and Omega SA exemplify divergent strategic positioning—Rolex through in-house chronometer testing protocols, Omega through extended naval service networks. Ulysse Nardin occupies a distinct expedition-grade niche where marine heritage commands collector premiums. These three Swiss-based entities anchor the competitive structure while quartz-specialist entrants erode commercial shipping addressable market through GPS-disciplined oscillator substitution.
| Leading Market Players |
|---|
| Rolex SA |
| Omega SA |
| Patek Philippe |
| A. Lange & Söhne |
| Ulysse Nardin |
| Glashütte Original |
| Steinhart |
| Longines |
| IWC |
| Others |
Supply & Pricing Matrix
Capacity utilization at Swiss Jura Arc escapement machining facilities runs above eighty percent, compressing mechanical chronometer output and establishing hard price floors that quartz competitors cannot undercut without sacrificing ISO 3159 certification credibility.
Pricing Analysis
Certification level under ISO 3159 and EU Marine Equipment Directive compliance creates the primary spread between premium mechanical units and operational quartz deployments. Three-tier pricing structure across heritage ceremonial, certified operational, and commercial retrofit levels reflects differential after-sales bundling intensity. Cost compression in commercial shipping segments stems from GPS-disciplined oscillator substitution. Research institutions exhibit least price sensitivity due to sub-second synchronization requirements, while recreational boaters drive transactional spot-market volume at minimal margins.
Supply Chain Analysis
Switzerland and Germany anchor precision escapement fabrication and quartz oscillator assembly respectively, with Norway emerging as a research vessel retrofit demand cluster. Nickel-iron alloys for balance springs and silicon wafers for quartz stabilization cores constitute critical input dependencies. REACH chemical restrictions on nickel formulations introduce regulatory friction that extends production timelines. Distribution runs through naval procurement frameworks, independent calibration laboratories in Hamburg and Rotterdam, and direct manufacturer relationships with oceanographic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master horologist training pipelines require decade-long commitments, creating persistent capability scarcity that constrains mechanical chronometer throughput regardless of capital deployment intensity.
For Market Incumbents: Fortify Jura Arc manufacturing clusters through captive escapement machining capacity and accelerated ISO 3159 certification reciprocity negotiations with German KBA and French ANSM regulators. GPS-disciplined oscillator substitution threatens commercial shipping addressable market; vertical integration into silicon oscillator sourcing defends hybrid platform margins. For New Entrants and Emerging Players: Differentiate on electronic chronometer calibration service unbundling, targeting Norwegian and German research vessel operators with independent laboratory accreditation. White space concentrates in aftermarket maintenance capture from original manufacturers and expedition-grade hybrid platform development for polar circumnavigation segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors quartz-specialist entrants with naval framework agreement eligibility over heritage mechanical pure-plays facing REACH compliance headwinds. Long-term viability hinges on dual-technology platform engineering capabilities. The signal to watch is NATO procurement officer consolidation of vendor relationships toward decade-long calibration bundles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Technology Platform Development | Hybrid mechanical-quartz architectures satisfy Brest naval base ceremonial-operational dual requirements. |
| Independent Calibration Laboratory Accreditation | Hamburg and Rotterdam facilities capture aftermarket revenue from Rolex SA and Omega SA service networks. |
| ISO 3159 Certification Reciprocity Expansion | Swissmedic-equivalent oversight alignment with KBA and ANSM accelerates EU-flagged vessel market access. |
| Silicon Oscillator Supply Integration | Upstream control over quartz stabilization core production compresses hybrid platform cost structures. |
| Research Vessel Framework Agreement Pursuit | Norwegian university fleet procurement concentrates synchronized sensor array timing demand. |
Research Methodology
A standing panel of naval procurement officers, master horologists at Jura Arc manufactures, independent calibration laboratory directors in Hamburg and Rotterdam, and oceanographic institute fleet managers provided ongoing calibration against secondary validation from EU Marine Equipment Directive filings, Swissmedic-equivalent precision instrument certifications, KBA maritime equipment protocols, and customs trade data for nickel-iron alloy imports. Bottom-up vessel fleet analysis and top-down defense procurement budget triangulation anchored volume estimates.
Consistency checks against NATO naval modernization program disclosures and German Thyssenkrupp Marine Systems supplier announcements validated trajectory assumptions across the analysis window. Segmentation modeling incorporated product type mechanical-electronic-hybrid splits, application navigation-timing-research distinctions, and end-user institutional versus commercial procurement patterns. CAGRs derived from instrument replacement cycle analysis and fleet operator survey data on certification compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense expenditure trajectories or REACH nickel-alloy exemption pathways would require recalibration. Forecasts reflect assumptions on master horologist training pipeline throughput and ISO 3159 testing protocol duration stability. Recalibration cycles align with material shifts in EU Marine Equipment Directive enforcement intensity and GPS-disciplined oscillator accuracy improvements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Commercial Hovercraft Market
Marine
Marine Interiors Market
Marine
Ballast Water Management Market
Marine
Europe Recreational Boating Market
Marine
Marine Salvage Services Market
Marine
Marine Airbags Market
Marine
Jack-Up Vessels Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Boat Ladder Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Marine Shackle Market
Marine
LNG Bunkering Vessel Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Yacht Shell Doors Market
Marine
Marine Engines Market
Marine
Sliding Fender Market