
 Embedded Finance Market | 2026-2036
Embedded Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Finance Market Analysis
API infrastructure is broadening access to core banking functions for non-financial platforms. Stripe leverages its global payments network to anchor embedded finance capabilities across software ecosystems. Marqeta specializes in card-issuing technology that extends programmable payment controls to fintech developers. Solaris sustains European market presence through its full-stack banking-as-a-service license coverage.
Embedded finance integrates financial services—payments, lending, insurance, and investments—directly into non-financial digital platforms through API-driven architecture, typically processing transactions via RESTful interfaces with sub-second latency. Its primary commercial purpose eliminates friction by allowing consumers to access credit, complete purchases, or secure coverage without leaving the host application interface. Payment Solutions and Lending Services command the largest current revenue pools as merchants prioritize checkout conversion and working capital access. API Integration functions as the foundational technology layer, while Cloud Computing enables the elastic infrastructure required for transaction scaling across Industry Verticals including E-commerce and Retail.
The Federal Reserve, the Office of the Comptroller of the Currency, and the Consumer Financial Protection Bureau shape US embedded finance through bank partnership oversight, fintech charter frameworks, and consumer disclosure requirements. The European Banking Authority enforces PSD2-driven open banking standards that mandate account access APIs for licensed third parties. Stakeholders must monitor how divergent national approaches to banking-as-a-service licensing affect cross-border platform expansion and compliance architecture.
Market Dynamics
API standardization is compressing time-to-market for non-financial platforms seeking banking functionality, while open banking mandates in the European Union and United Kingdom force legacy institutions to expose core systems through standardized interfaces.
Growth Catalysts
- PSD2 Compliance Mandates:European Banking Authority enforcement requires account access APIs for licensed third parties, accelerating platform integration timelines across retail and e-commerce verticals.
- Cloud Infrastructure Elasticity:Distributed computing architectures enable transaction scaling without proportional capital expenditure, lowering barriers for mid-market software platforms entering financial services.
- Merchant Checkout Conversion Pressure:E-commerce operators embed lending at point-of-sale to reduce cart abandonment, creating pull-through demand for card-issuing and buy-now-pay-later infrastructure.
Market Restraints
- Bank Partnership Dependency:Sponsored bank relationships concentrate among a limited pool of federally chartered institutions in the United States, creating single-point-of-failure risk for platform operators.
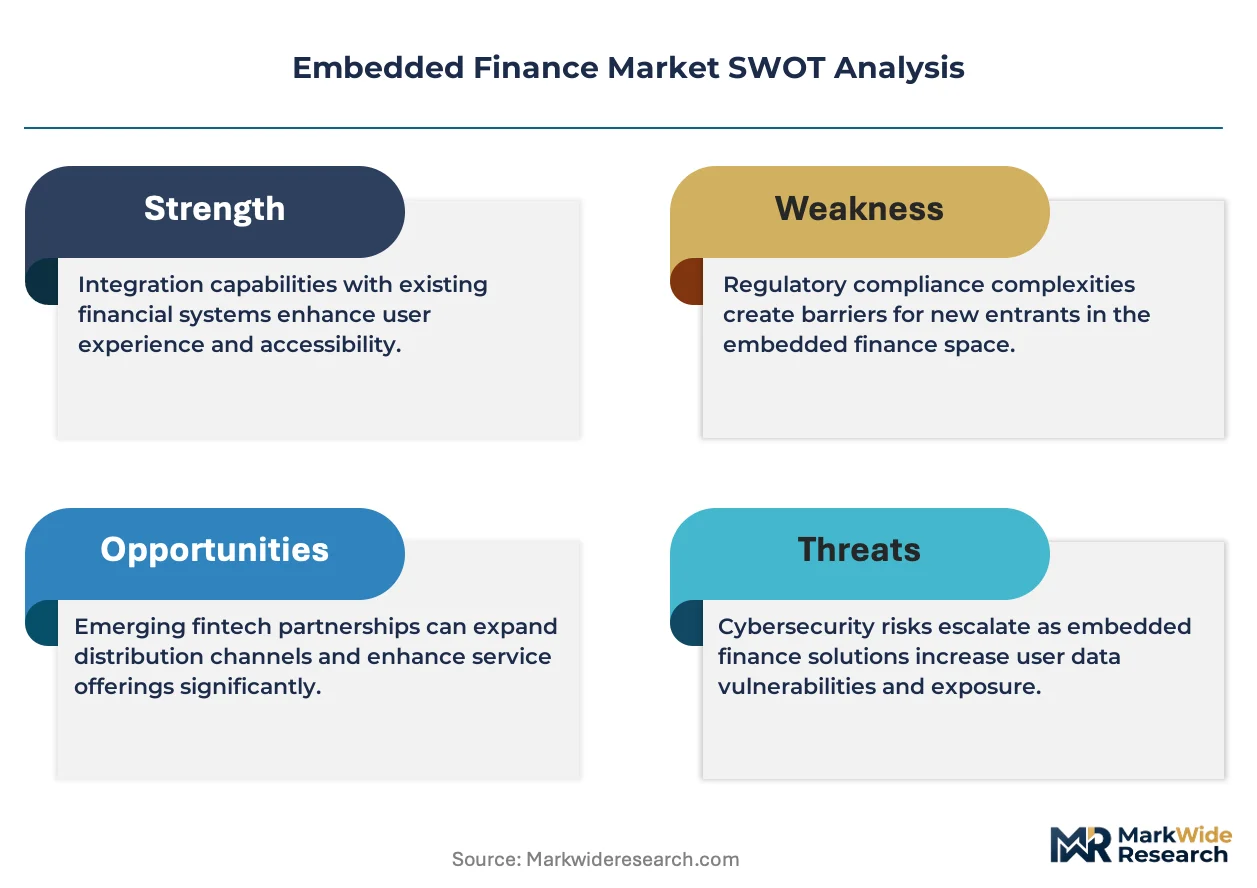
- Compliance Architecture Costs:Multi-jurisdictional licensing requirements impose fixed overhead that scales disproportionately for smaller platform entrants, favoring well-capitalized incumbents.
- Core Banking System Rigidity:Legacy mainframe architectures at established financial institutions resist real-time API integration, forcing middleware complexity that extends implementation timelines.
Strategic Opportunities
- Embedded Insurance Penetration:Point-of-sale coverage integration remains underdeveloped relative to payments and lending, offering first-mover positioning for platforms targeting travel and electronics verticals.
- Wealth Management Convergence:Robo-advisory APIs are converging with retail banking platforms, enabling automated investment allocation within consumer budgeting applications.
- India Stack Expansion:Unified Payments Interface infrastructure and account aggregator frameworks create regulatory tailwinds for domestic fintech platforms seeking full-stack banking licenses.
Industry Challenges
- Specialized Engineering Talent Scarcity:Shortage of professionals combining financial services domain knowledge with cloud-native architecture expertise extends platform build cycles.
- Cross-Border Licensing Complexity:Divergent national approaches to banking-as-a-service authorization create compliance fragmentation for platforms operating across multiple jurisdictions.
- Real-Time Reconciliation Demands:Sub-second transaction settlement requirements strain legacy ledger systems, forcing costly infrastructure rearchitecture for established financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Finance Market |
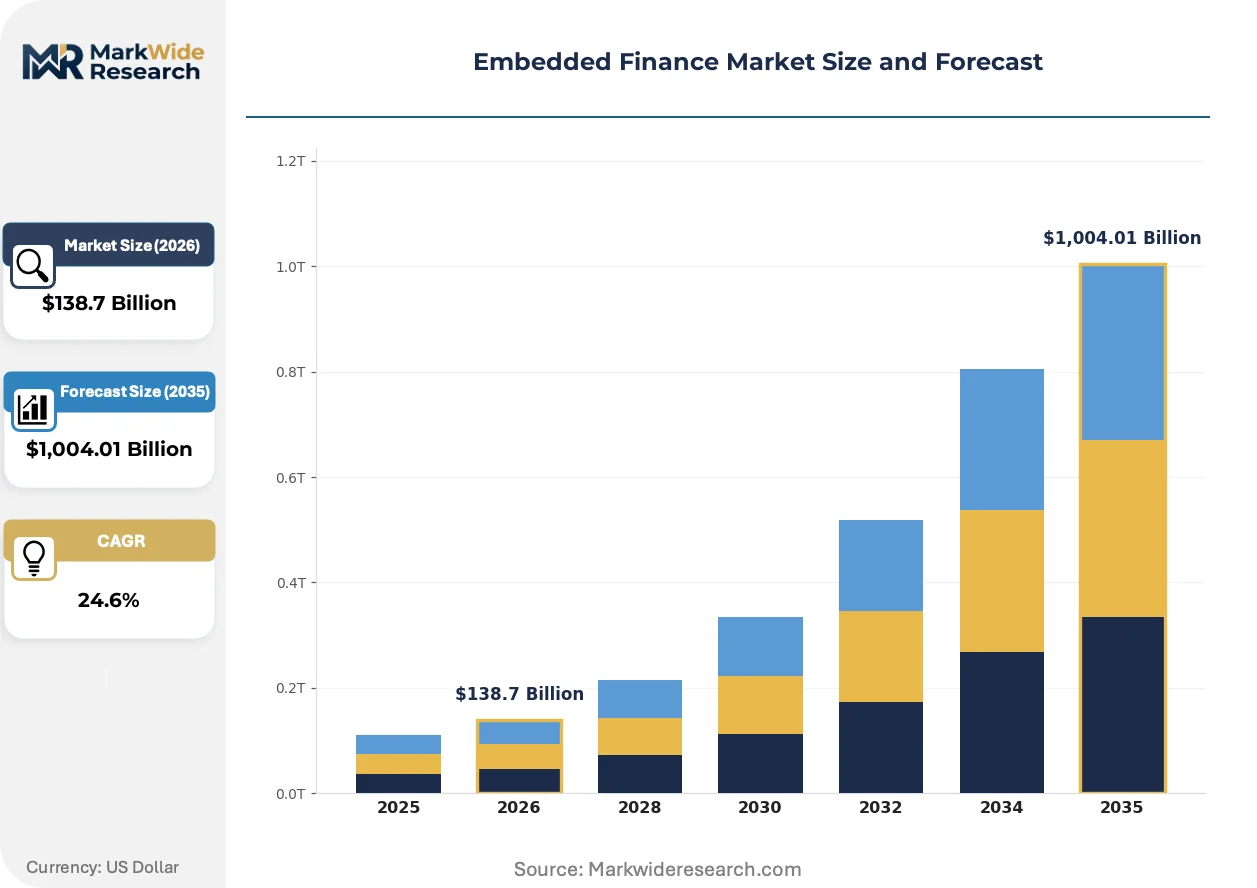
| Market Size in 2026 | $138.7 Billion |
| Market Size in 2035 | $1,004.01 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Solutions, Lending Services, Insurance Offerings, Investment Products Industry Vertical: E-commerce, Healthcare, Travel, Retail Technology: Blockchain, API Integration, Cloud Computing, Machine Learning Customer Type: Small Businesses, Enterprises, Startups, Freelancers |
| Companies Covered | Gemba, Galileo, Stripe, Treasury Prime, Solaris, Adyen, Unit, Computools, Marqeta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Finance Market Emerging Trajectories
Programmable payment infrastructure is reshaping how software platforms monetize user relationships, with card-issuing technology migrating from specialized vendors to general-purpose developer tools.
Event-driven architecture is overtaking batch processing as the dominant paradigm for transaction orchestration. Modern platforms stream payment authorization decisions through message brokers rather than polling legacy systems. E-commerce merchants and SaaS providers are adopting this approach to enable real-time balance checks and dynamic spending controls. The shift is compressing settlement windows from days to seconds, eliminating float-based revenue models that sustained traditional payment processors.
The European Banking Authority's PSD2 enforcement timeline is forcing account aggregation standardization across member states. Third-party providers now access payment initiation and account information services through regulated APIs, displacing screen-scraping methods. Retail banking applications in Germany and the Netherlands are responding by building native marketplace features that compete directly with independent personal finance managers.
Small and medium enterprises are consolidating financial service procurement through vertical software platforms rather than direct bank relationships. Construction management and healthcare practice software now embed business accounts, expense cards, and invoice financing as core features. This pattern is most visible in the United States, where technology infrastructure and banking partnerships matured earliest, though similar consolidation is emerging among United Kingdom professional services platforms.
Embedded Finance Market Segmentation
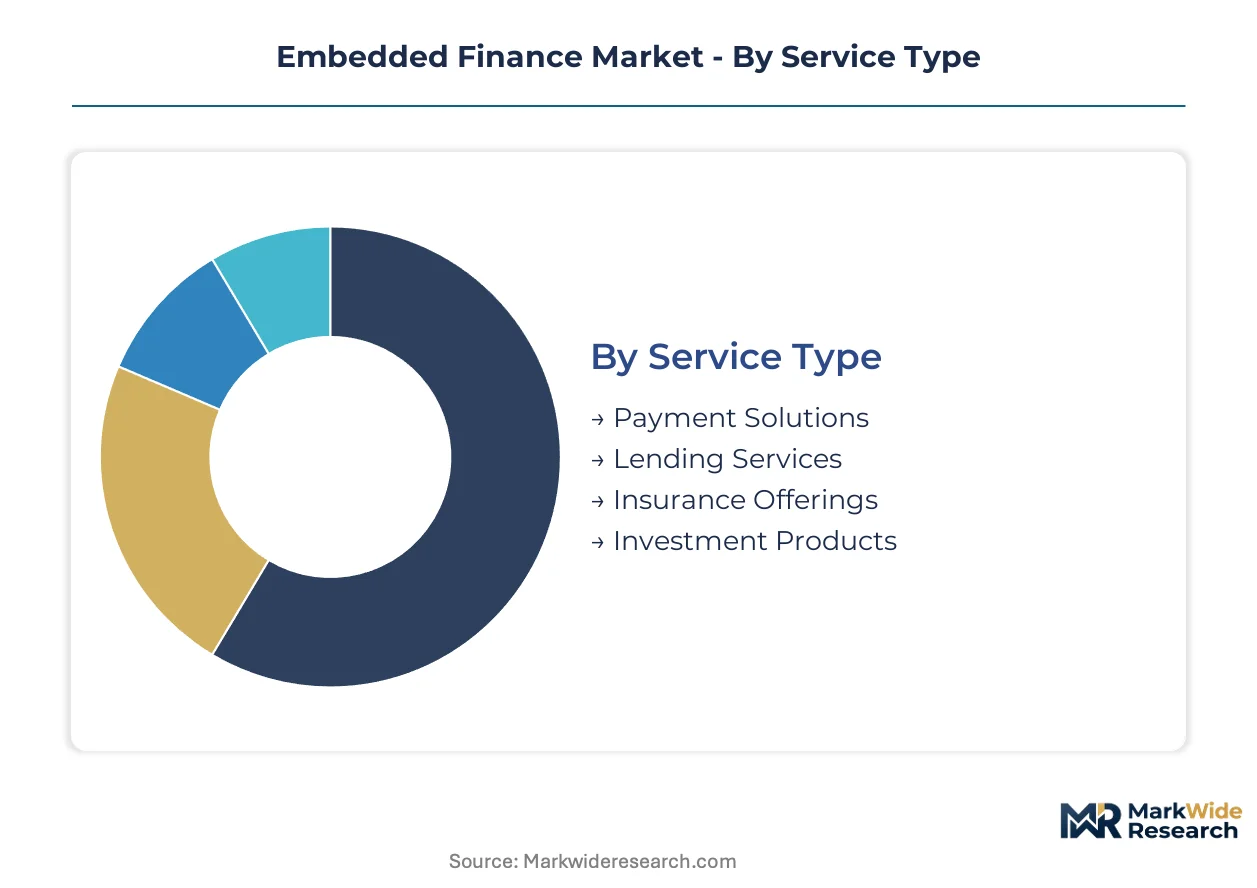
Embedded finance segmentation reveals how platform operators select technical and commercial entry points based on existing infrastructure maturity and partnership availability. Distinct service types, vertical applications, and technology stacks create divergent margin profiles and implementation timelines across the ecosystem.
Service Type:
Platform operators upgrade service portfolios in cycles tied to merchant checkout conversion benchmarks and regulatory clarity on bank sponsorship models.
- Payment Solutions:RESTful API architectures process card transactions with sub-second latency, embedding checkout flows directly into e-commerce interfaces. Demand concentrates among United States merchants prioritizing cart abandonment reduction, driven by sponsor bank partnership density in that market.
- Lending Services:Point-of-sale credit products integrate underwriting algorithms into purchase workflows, enabling instant approval without redirecting consumers. United Kingdom retailers lead adoption following PSD2-mandated open banking data availability for affordability checks.
- Insurance Offerings:Parametric coverage triggers automated payouts through smart contract integration, with travel platforms embedding cancellation protection at booking confirmation.
- Investment Products:Micro-investing round-up features attach to payment flows, targeting freelancer income volatility management through automated portfolio allocation.
Payment Solutions sits at the top of the volume ranking, with Lending Services climbing the fastest.
Industry Vertical:
Vertical selection follows customer acquisition cost differentials, with platforms prioritizing sectors where financial service penetration lags software adoption.
- E-commerce:Checkout-embedded BNPL and one-click payment options reduce friction in high-velocity transaction environments. German marketplaces accelerate integration following BaFin licensing clarity for installment credit at point-of-sale.
- Healthcare:Patient financing and insurance eligibility verification embed into practice management software, addressing out-of-pocket cost transparency gaps. United States ambulatory care networks drive demand through high-deductible plan proliferation.
- Travel:Dynamic currency conversion and trip protection bundle at booking engines, with Netherlands-based platforms leveraging EU-wide passporting for cross-border coverage.
- Retail:In-store mobile payment acceptance and merchant cash advance products integrate through POS terminal APIs, serving brick-and-click inventory financing needs.
E-commerce maintains the steepest expansion trajectory among verticals, while Healthcare gains share fastest through regulatory pressure on price transparency.
Technology:
Technology stack decisions hinge on legacy system replacement cycles and cloud infrastructure commitment levels among platform engineering teams.
- API Integration:Standardized REST and GraphQL interfaces abstract core banking functions into developer-accessible endpoints, enabling non-financial platforms to embed services without building from regulated infrastructure. United States fintech infrastructure maturity accelerates deployment timelines relative to other markets.
- Cloud Computing:Elastic compute architectures scale transaction processing without proportional capital expenditure, supporting mid-market platform entry into financial services. Frankfurt and Amsterdam data center clusters serve European latency requirements under GDPR data residency constraints.
- Blockchain:Distributed ledger settlement reduces correspondent banking dependency for cross-border remittance embedding, with Singapore-based platforms piloting programmable money for B2B invoice reconciliation.
- Machine Learning:Real-time underwriting models analyze alternative data streams for credit decisions, deployed most extensively in markets with thin-file consumer populations.
API Integration dominates current deployment volume, with Cloud Computing expanding most quickly as mid-market platforms enter the sector.
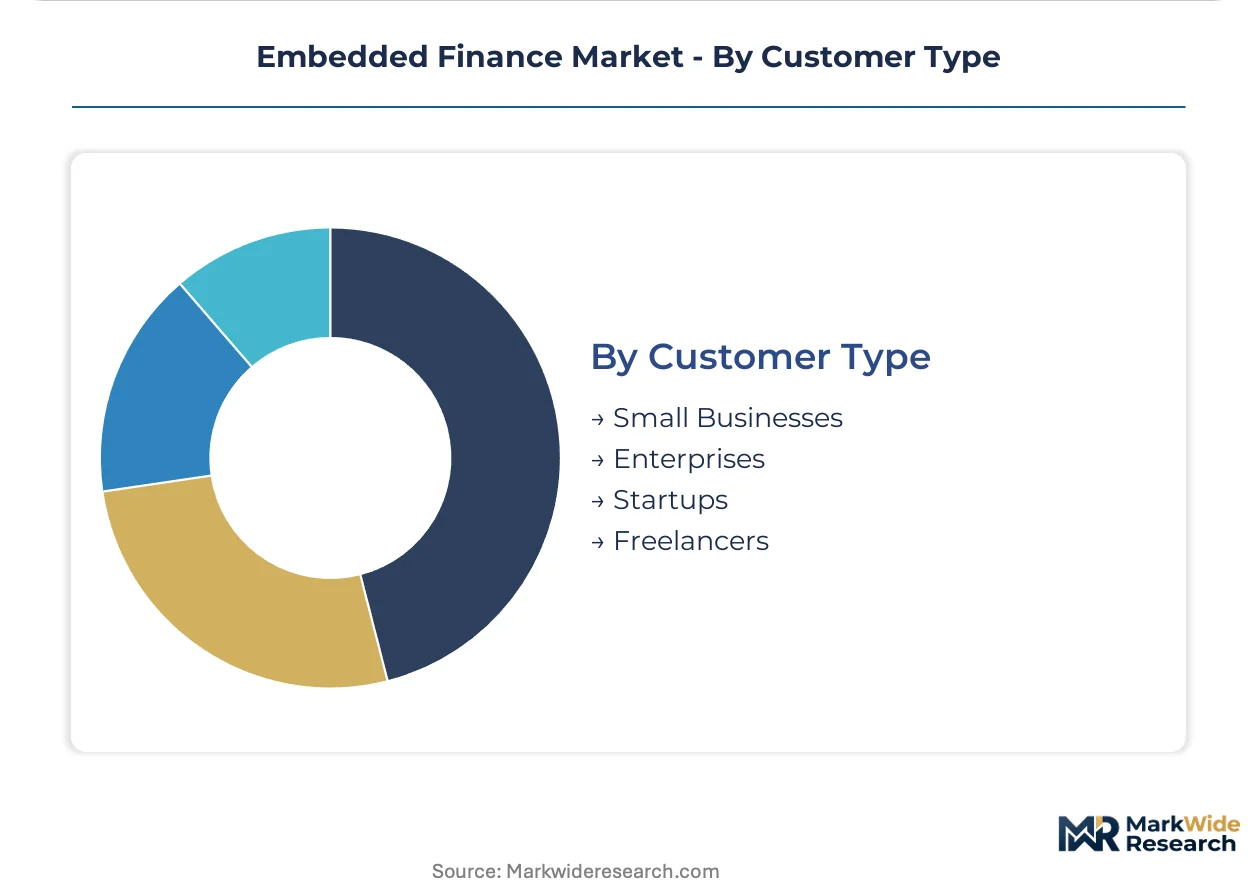
Customer Type:
Customer segmentation reflects platform monetization model selection between transaction volume aggregation and high-value service customization.
- Small Businesses:Consolidated financial service procurement through vertical software reduces administrative overhead, with construction and healthcare practice platforms in the United States embedding accounts, cards, and invoice financing as core features.
- Enterprises:Custom treasury management and multi-entity card programs require dedicated implementation resources, favoring platforms with dedicated account engineering teams.
- Startups:Rapid onboarding and pay-as-you-scale pricing attract venture-backed companies prioritizing capital efficiency over feature depth.
- Freelancers:Income smoothing tools and tax withholding automation address irregular cash flow patterns, with United Kingdom platforms responding to IR35 contractor classification changes.
Small Businesses anchor current platform revenue, with Enterprises generating the fastest-growing contract values through multi-year service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's payments infrastructure density anchors embedded finance innovation, with sponsor bank partnerships and API standardization creating divergent regulatory environments across major economies.
United States
Merchant checkout conversion pressure and SaaS platform consolidation drive demand for card-issuing and lending APIs. The Office of the Comptroller of the Currency and Consumer Financial Protection Bureau oversee bank-fintech partnership frameworks. New York and San Francisco host the densest concentrations of banking-as-a-service infrastructure providers.
United Kingdom
PSD2-mandated open banking data availability accelerates point-of-sale credit adoption among retailers. The Financial Conduct Authority enforces affordability check standards for embedded lending products. London's fintech cluster leads European platform development for account aggregation services.
Germany
BaFin licensing clarity for installment credit at point-of-sale stimulates e-commerce integration demand. The Federal Financial Supervisory Authority governs banking-as-a-service authorization under EU passporting rules. Berlin and Frankfurt data centers serve latency requirements under GDPR residency constraints.
India
Unified Payments Interface infrastructure and account aggregator frameworks enable domestic fintech platform expansion. The Reserve Bank of India regulates full-stack banking licenses and payment system access. Mumbai and Bangalore clusters concentrate developer talent for API-first financial infrastructure.
Singapore
Cross-border remittance embedding and programmable money pilots attract B2B invoice reconciliation platforms. The Monetary Authority of Singapore oversees digital banking licenses and sandbox frameworks. The city-state's data center infrastructure serves Southeast Asian transaction routing requirements.
Embedded Finance Market Vendor Landscape
Global majors compete with regional champions across API infrastructure and sponsor bank access, creating a tiered structure where scale-driven payment networks, specialized card-issuing technology providers, and full-stack banking-as-a-service platforms occupy distinct positions. Strategic differentiation clusters around three archetypes: horizontal infrastructure aggregators, vertical software-embedded specialists, and licensed bank-direct operators. Competitive moves concentrate on strategic partnerships with federally chartered institutions and geographic expansion through regulatory sandbox entry.
Among infrastructure-focused platforms, Stripe and Marqeta exemplify the horizontal aggregation archetype, while Solaris occupies a position representing European licensed banking-as-a-service specialization. These anchors demonstrate how geographic origin and regulatory authorization scope determine competitive positioning within the embedded finance ecosystem.
| Leading Market Players |
|---|
| Gemba |
| Galileo |
| Stripe |
| Treasury Prime |
| Solaris |
| Adyen |
| Unit |
| Computools |
| Marqeta |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure spot pricing indices cascade through embedded finance supply chains, compressing margins for mid-market API platforms while concentrating pricing power among hyperscale providers with captive data center capacity. This cost structure forces tiered service differentiation between bare-metal orchestration and fully managed banking-as-a-service bundles.
Pricing Analysis
Input-cost pass-through from sponsor bank licensing fees and compliance architecture investments drives pricing stratification across embedded finance tiers. Three-tier pricing separates enterprise-grade dedicated ledger instances from multi-tenant standard deployments and economy API gateway access. Pricing pressure stems from cloud compute commoditization and sponsor bank consolidation, which squeezes intermediary margins. Small business platforms exhibit highest price sensitivity due to per-transaction cost visibility, while enterprise buyers prioritize SLA guarantees over unit economics.
Supply Chain Analysis
Core banking system dependency rests on legacy mainframe providers concentrated in the United States, Germany, and India, with middleware abstraction layers sourced from specialized fintech infrastructure vendors. Critical inputs include federal banking charters, API standardization frameworks, and elastic cloud compute capacity. Single-source vulnerability concentrates around sponsor bank relationships, where platform operators rely on limited federally chartered institutions for regulatory coverage. Distribution runs through direct API marketplace integrations and vertical software platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded finance market reads as a late-cycle quality story, with merchant demand shifting toward premium specifications including sub-second latency guarantees and multi-jurisdictional compliance coverage.
For Market Incumbents: Deploy sponsor bank diversification to mitigate concentration risk among limited federally chartered institutions. Consolidate API infrastructure through backward integration into cloud-native ledger systems, countering the threat from specialized card-issuing technology entrants. Fortify compliance architecture investments to maintain margin position against regulatory fragmentation across European and United Kingdom markets. For New Entrants and Emerging Players: Mid-market healthcare practice management platforms represent the most penetrable buyer archetype, with financial service procurement consolidation lagging software adoption. White-space targets include embedded insurance at point-of-sale for travel verticals and automated tax withholding for United Kingdom freelancers responding to IR35 classification changes. Go-to-market execution should anchor on vertical-specific workflow integration rather than horizontal API commoditization. For Investors and Strategic Acquirers: Asymmetric upside sits with full-stack banking-as-a-service platforms holding European Economic Area passporting rights. Long-term viability over the next decade hinges on regulatory authorization scope expansion and sponsor bank relationship depth. Watch for inflection signals in India Stack license issuance velocity and Reserve Bank of India payment system access approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Sponsor Bank Diversification | Reduces single-point-of-failure risk for platform operators dependent on limited federally chartered United States institutions. |
| API Standardization Investment | Accelerates PSD2 compliance timelines for European platforms seeking account aggregation market entry. |
| Vertical Software Integration | Captures construction and healthcare practice management procurement consolidation in United States mid-market segments. |
| Cloud-Native Ledger Migration | Eliminates legacy mainframe dependency that extends implementation timelines for real-time transaction processing. |
| Cross-Border Licensing Expansion | Enables EU-wide passporting for United Kingdom platforms navigating post-Brexit regulatory divergence. |
Methodological Framework
Multiple input streams — primary interviews with banking-as-a-service platform executives, sponsor bank partnership directors, and fintech regulatory counsel — were reconciled against secondary validation from European Banking Authority PSD2 implementation reports, Federal Reserve bank partnership oversight filings, and cloud infrastructure provider capex disclosures. Bottom-up transaction volume estimates and top-down market sizing triangulation anchored the analytical framework.
Data-stream reconciliation across service type, industry vertical, technology stack, and customer segmentation dimensions shaped the projection methodology. Growth trajectories were derived from elasticity modeling of merchant checkout conversion benchmarks and open banking API adoption curves. Key forecast inputs included sponsor bank licensing capacity constraints and cloud compute price elasticity parameters.
Underlying measurement precision varies by segment; payment solutions and lending services carry tighter precision than emerging insurance and investment product categories. Forecasts reflect assumptions around regulatory timeline adherence and sponsor bank partnership availability. A small set of triggers — India Stack license issuance velocity, Federal Reserve fintech charter framework evolution, and core banking system modernization capex cycles — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Asia-Pacific Financial Analytics Market
FinTech
UAE Fintech Market
FinTech
MENA Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
Supply Chain Finance Market
FinTech
Robo Advisory Market
FinTech
Account Checking Software Market
FinTech
Autonomous Finance Market
FinTech
Robo-Advisory Services Market
FinTech
Canada AI in Fintech Market
FinTech
Smart Lending Platform Market
FinTech
Smart Financial Solutions Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Netherlands AI in Fintech Market
FinTech
Germany AI in Fintech Market