
 Smart Financial Solutions Market | 2026-2036
Smart Financial Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Financial Solutions Market Insights
Buyer concentration among large retail banking institutions is expanding as mid-tier credit unions and community banks fragment across specialized fintech vendors. BPC Group leverages its core banking platform specialization to anchor deployments across emerging market financial institutions. GRGBanking competes through manufacturing scale in self-service terminals and smart branch infrastructure. Virtusa Corp. differentiates via cloud-native engineering capabilities that sustain multi-year transformation contracts with tier-one banks.
Smart financial solutions encompass integrated software and hardware systems that automate transaction processing, risk analytics, and customer-facing financial services through API-orchestrated architectures and real-time data pipelines. These systems process structured and unstructured financial data at sub-second latency to enable instant payments, dynamic credit scoring, and personalized portfolio recommendations. Personal finance management and investment advisory services within the service type dimension command premium pricing due to recurring subscription structures and embedded wealth fees. AI analytics and blockchain within the technology segment represent the fastest-expanding capability investments as institutions seek explainable risk models and immutable transaction ledgers.
The US Federal Reserve, the European Banking Authority, and the Monetary Authority of Singapore shape market access through open banking mandates, operational resilience requirements, and digital banking licensing frameworks that dictate API security standards and data portability rules. The EU AI Act adds algorithmic governance obligations for automated credit and insurance underwriting systems. Stakeholders must monitor how divergent cross-border compliance timelines affect platform architecture decisions and partnership strategies.
Market Dynamics
API-orchestrated architectures are compressing deployment timelines across retail banking institutions, forcing legacy core system vendors to restructure their integration layers or lose multi-year transformation contracts to cloud-native competitors.
Growth Catalysts
- Open Banking Mandates:The European Union's PSD2 and the United Kingdom's Open Banking Standard compel incumbent banks to expose customer data through standardized APIs, creating immediate demand for middleware and consent-management platforms.
- Real-Time Payment Rails:The Federal Reserve's FedNow service and similar instant settlement infrastructures in Singapore and Brazil require sub-second transaction processing capabilities that legacy batch systems cannot deliver.
- AI-Driven Personalization:Wealth management divisions within tier-one banks are deploying machine learning models for dynamic portfolio rebalancing, generating recurring software licensing revenue for analytics vendors.
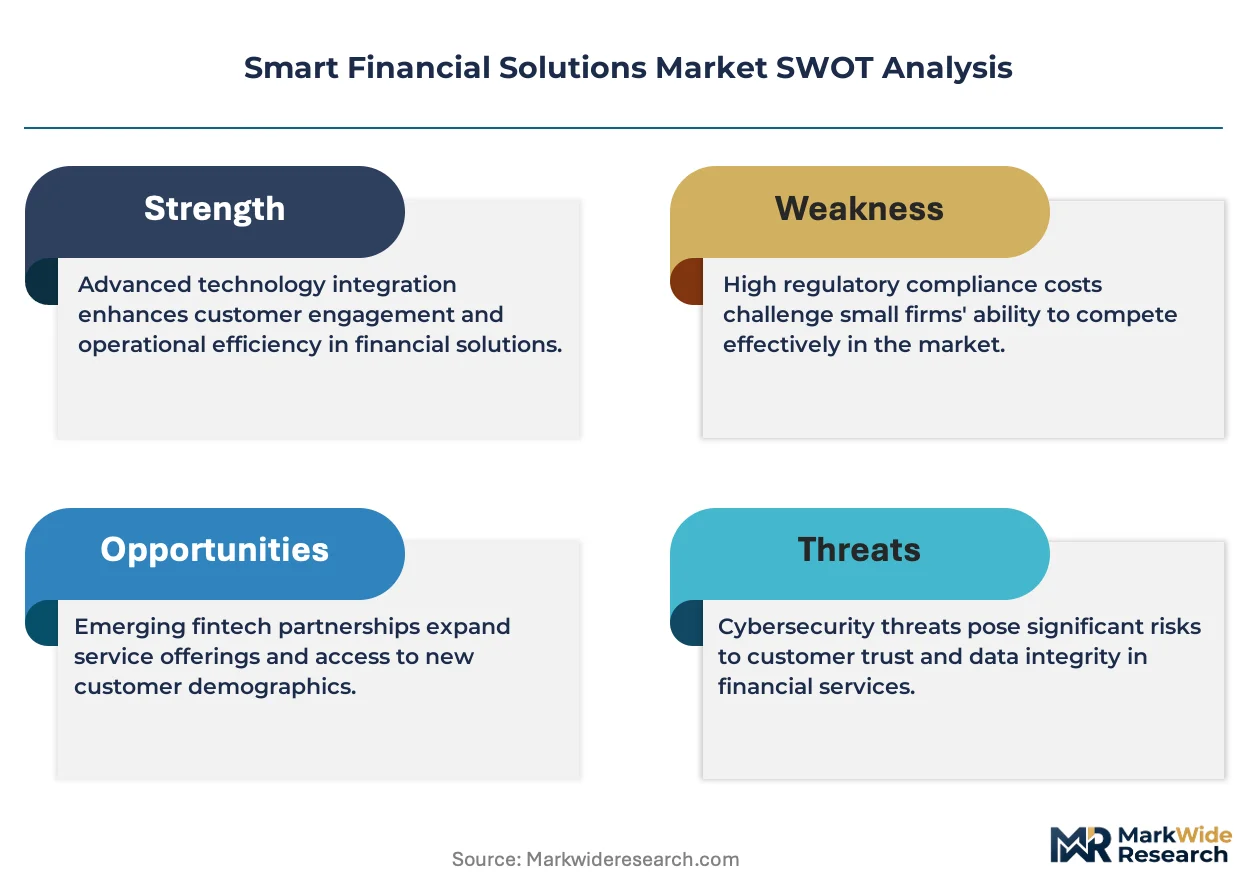
Market Restraints
- Cloud Concentration Risk:Hyperscaler dominance in financial services infrastructure creates single-point-of-failure exposure and escalating egress cost structures for mid-tier institutions.
- EU AI Act Compliance Burden:Algorithmic governance requirements for automated credit decisions impose documentation and audit trails that extend product development cycles by twelve to eighteen months.
- Core Banking Vendor Lock-In:Proprietary data schemas and closed integration protocols at incumbent platform providers raise switching costs above replacement thresholds for most regional banks.
Strategic Opportunities
- Embedded Finance Expansion:Non-banking platforms in e-commerce and logistics sectors seek white-labeled banking-as-a-service stacks, opening distribution channels beyond traditional financial institutions.
- Blockchain Settlement Layers:Distributed ledger interoperability between correspondent banking networks and central bank digital currency pilots creates infrastructure replacement demand across ASEAN markets.
- Explainable AI Mandates:Regulatory pressure for transparent risk scoring models favors specialized vendors with interpretable machine learning frameworks over black-box alternatives.
Industry Challenges
- Legacy System Integration Complexity:COBOL-based core banking platforms at established institutions resist API-native connectivity, requiring costly abstraction layers that degrade performance.
- Specialized Talent Scarcity:Shortages of engineers proficient in both financial domain logic and cloud-native microservices architecture constrain deployment velocity for transformation programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Financial Solutions Market |
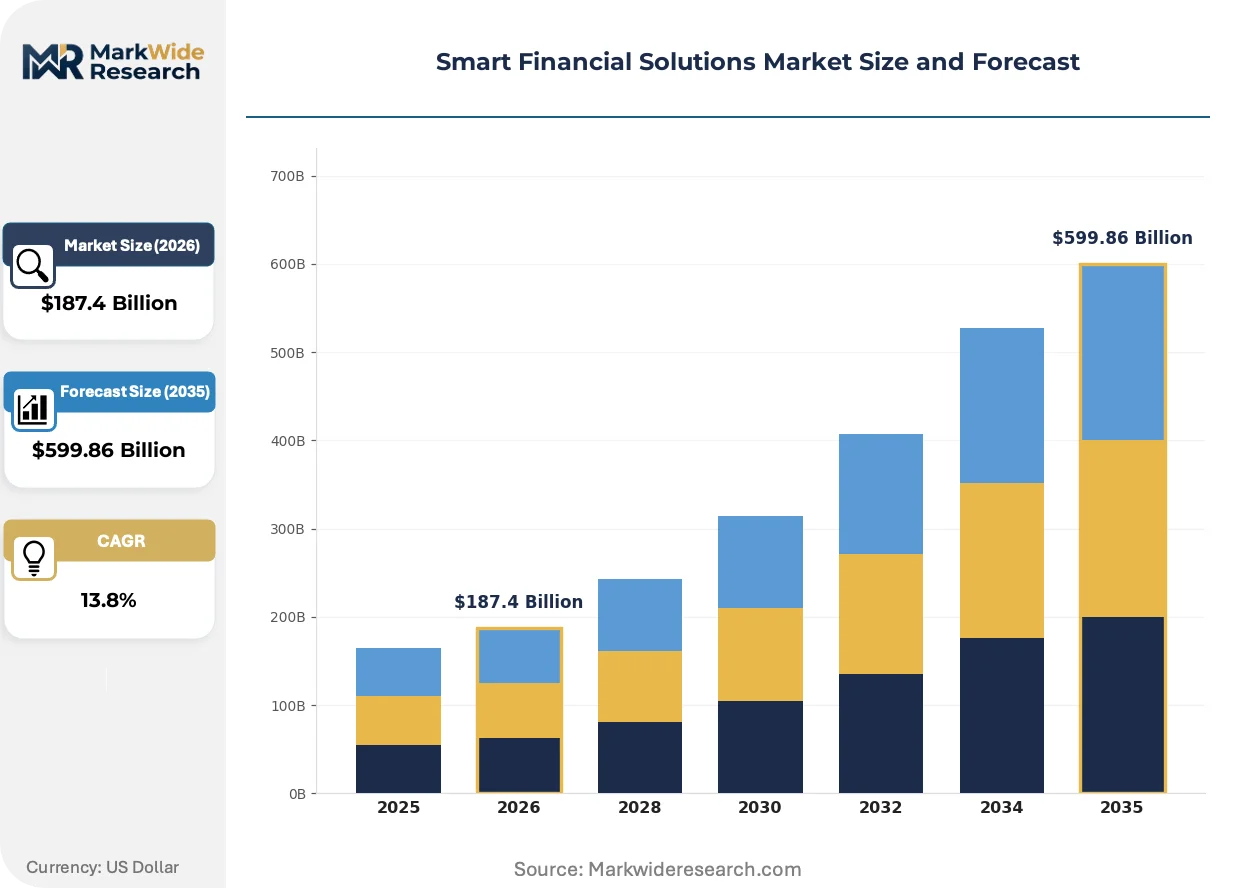
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $599.86 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Finance Management, Investment Advisory, Risk Assessment, Budgeting Tools Client Type: Individuals, Small Businesses, Corporations, Non-Profits Technology: AI Analytics, Blockchain, Mobile Applications, Cloud Computing Offering: Software Solutions, Consulting Services, Automated Platforms, Training Programs |
| Companies Covered | IMS Evolve, BPC Group, Miles Technologies, Zicom SaaS Pvt. Ltd, GRGBanking, ESQ Business Services, Inc., hIOTron, Dialog Axiata PLC, Virtusa Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Financial Solutions Market Trends and Innovations
Real-time data pipelines are redefining competitive differentiation in financial services, compressing the window between transaction occurrence and actionable insight from days to milliseconds across customer-facing and risk-management functions.
Event-driven architecture is overtaking request-response patterns in payment processing infrastructure. Tier-one banks in the United States and United Kingdom are migrating transaction streams to Apache Kafka and equivalent message brokers to enable instant fraud detection and dynamic liquidity management. This architectural shift is overtaking traditional enterprise service buses that introduced latency incompatible with instant payment rails.
The EU AI Act's risk-based classification system for automated decision-making is restructuring vendor qualification processes. High-risk credit and insurance underwriting algorithms now require conformity assessments and human oversight mechanisms that favor established providers with compliance documentation. European retail banks are responding by segmenting procurement between explainable model vendors and black-box alternatives relegated to low-risk use cases.
Subscription-based pricing for core banking software is displacing perpetual license models that dominated procurement for three decades. Mid-tier credit unions in the United States are favoring vendors offering consumption-aligned fees over upfront capital commitments, shifting vendor revenue recognition from implementation milestones to ongoing relationship value. This pattern is most visible in community banking segments where regulatory capital constraints limit technology investment flexibility.
Smart Financial Solutions Market Segmentation
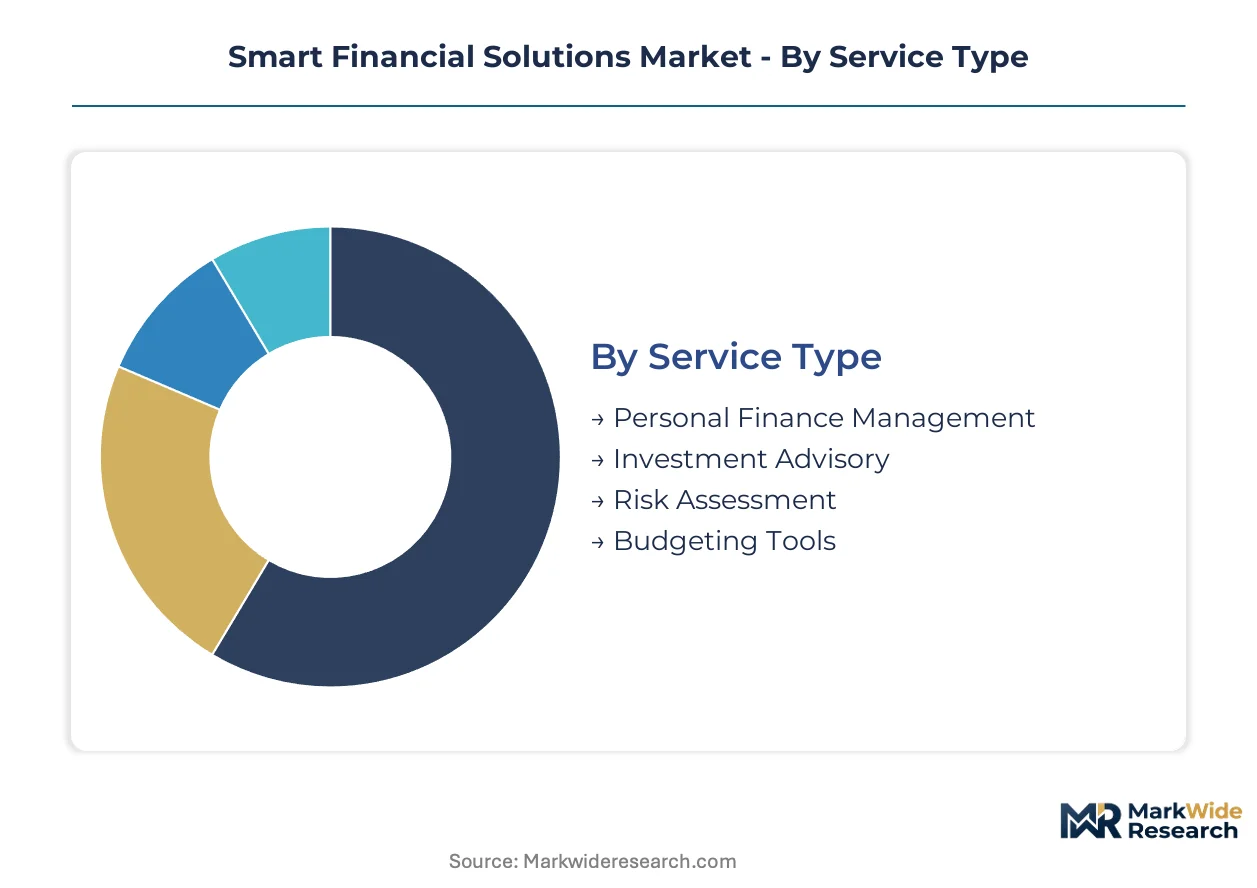
Smart financial solutions segment along four intersecting dimensions that determine deployment architecture, pricing models, and vendor selection criteria. Service type and technology choices dominate procurement decisions at tier-one banks, while client type and offering format shape go-to-market economics for emerging fintech entrants.
Service Type:
Customization intensity varies sharply across this category, with white-labeled wealth tools demanding bespoke integration while standardized budgeting utilities deploy through template configurations.
- Personal Finance Management:Aggregation platforms consolidate accounts, transactions, and liabilities into unified dashboards with predictive cash flow modeling. Demand clusters among United States regional banks seeking to match fintech-native user experiences without core system replacement.
- Investment Advisory:Robo-advisory engines automate portfolio construction, rebalancing, and tax-loss harvesting through algorithmic decision trees. United Kingdom wealth managers under Financial Conduct Authority suitability rules favor these platforms to document advice trails and reduce compliance overhead.
- Risk Assessment:Real-time credit scoring and fraud detection systems process behavioral biometrics and transaction patterns.
- Budgeting Tools:Categorical spending analysis and savings goal frameworks target credit union members with limited financial literacy.
Most installed capacity flows through Personal Finance Management. Expansion is steepest in Investment Advisory.
Client Type:
Revenue per seat climbs across this spectrum, with corporate treasury implementations commanding implementation fees that dwarf individual subscription economics.
- Corporations:Multi-entity cash management, intercompany netting, and foreign exchange hedging platforms require SAP and Oracle ERP integration. Singapore headquarters of ASEAN multinationals drive regional procurement for these solutions under Monetary Authority of Singapore liquidity reporting mandates.
- Small Businesses:Integrated invoicing, payroll, and working capital forecasting tools target owner-operators with limited accounting staff. United States community banks bundle these offerings to defend deposit relationships against Square and Stripe expansion.
- Individuals:Mobile-first budgeting and micro-investment applications compete on user acquisition cost.
- Non-Profits:Grant compliance tracking and donor-advised fund administration address specialized reporting requirements.
Corporations absorb the highest absolute technology spend. Small Businesses deliver the fastest expansion trajectory as embedded finance penetration deepens.
Technology:
Capital intensity separates this category, with blockchain infrastructure requiring dedicated node networks while cloud deployments leverage shared hyperscaler resources.
- AI Analytics:Explainable machine learning frameworks for credit underwriting and anti-money laundering generate regulatory documentation automatically. European Union banks prioritize these capabilities to satisfy EU AI Act conformity assessment requirements for high-risk algorithmic decisions.
- Blockchain:Distributed ledger settlement layers and smart contract automation target correspondent banking and trade finance digitization. Brazil's central bank digital currency pilot and Project Dunbar cross-border experiments in Singapore and South Africa stimulate infrastructure investment.
- Mobile Applications:Native iOS and Android development with biometric authentication and offline transaction queuing.
- Cloud Computing:Containerized microservices architectures on AWS, Azure, and GCP with multi-region failover.
Cloud Computing carries the dominant installed base. AI Analytics is climbing the fastest as explainability mandates harden.
Offering:
Margin structure diverges here, with software subscriptions generating recurring revenue streams while training programs deliver one-time fees with higher upfront margins.
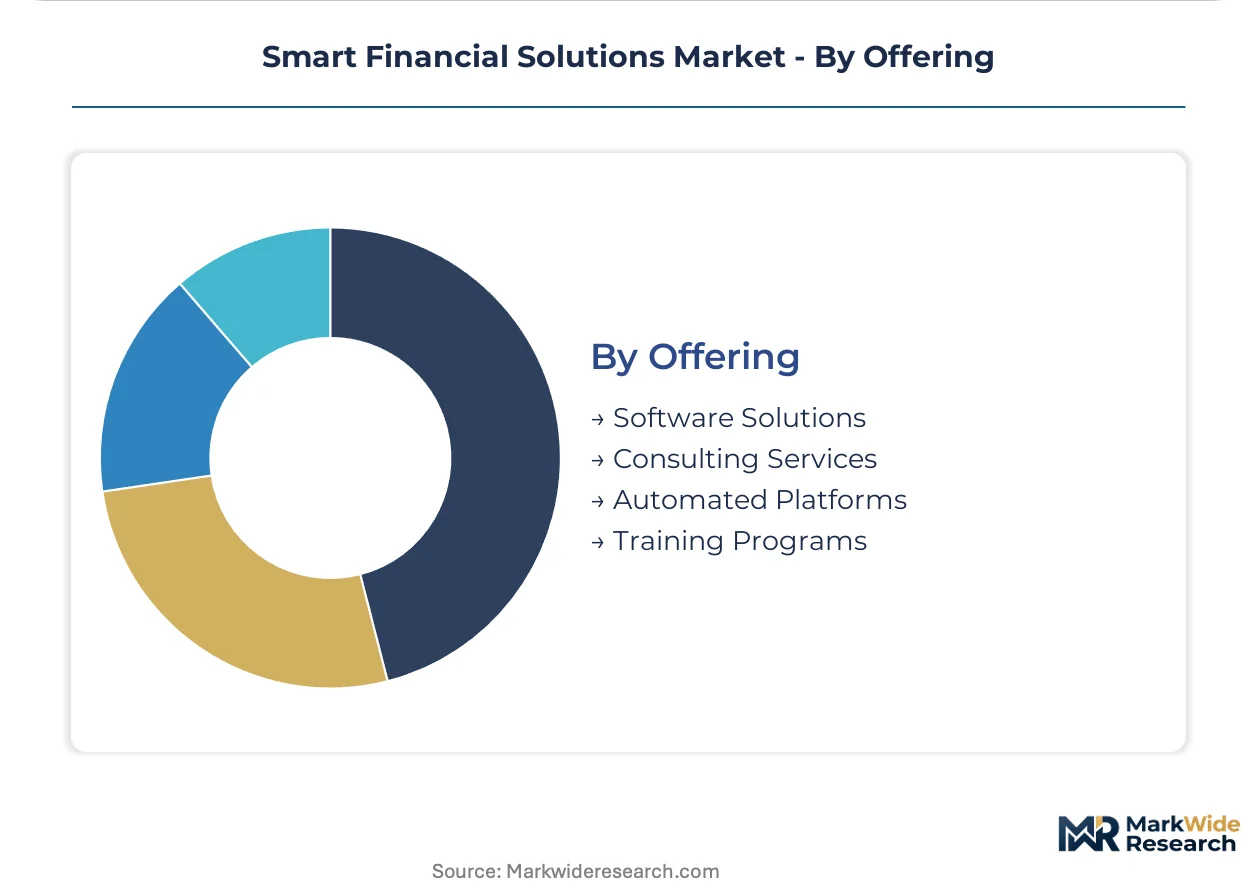
- Software Solutions:Licensed platforms for core banking, payment processing, and regulatory reporting with API-native integration layers. United States credit unions favor subscription pricing over perpetual licenses to preserve regulatory capital flexibility.
- Automated Platforms:Self-service configuration environments allowing business users to deploy workflows without engineering intervention. United Kingdom building societies adopt these to accelerate product launches under Open Banking Standard competitive pressure.
- Consulting Services:Implementation, data migration, and change management for transformation programs.
- Training Programs:Certification courses for platform administration and regulatory compliance.
Software Solutions account for the majority of deployed capacity. Automated Platforms are gaining share fastest as business-user empowerment reduces IT backlog bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement among consolidated banking institutions while Germany fragments demand across cooperative and public-sector banks with divergent technology roadmaps.
United States
The Federal Reserve's FedNow instant payment service drives infrastructure replacement demand as regional banks abandon batch processing systems. The SEC's cybersecurity disclosure rules for publicly traded financial institutions accelerate zero-trust architecture investments. New York's financial district anchors cloud-native core banking migrations among money-center banks seeking API orchestration capabilities.
Germany
Sparkassen and Volksbanken cooperatives pursue modular platform upgrades to satisfy PSD2 open banking mandates without full core replacement. BaFin's operational resilience requirements impose recovery time objectives that strain legacy COBOL architectures. Frankfurt's banking cluster concentrates regulatory technology vendors serving compliance documentation needs for algorithmic credit decisions.
United Kingdom
Building societies and challenger banks compete on user experience through Open Banking Standard-enabled account aggregation services. The Financial Conduct Authority's consumer duty rules mandate transparent fee disclosure across digital wealth platforms. London's fintech corridor hosts banking-as-a-service infrastructure providers serving embedded finance deployments in e-commerce and logistics sectors.
Singapore
ASEAN multinational headquarters drive treasury management platform procurement under Monetary Authority of Singapore liquidity reporting frameworks. Project Guardian tokenization pilots and Dunbar cross-border CBDC experiments stimulate distributed ledger infrastructure investment. The Marina Bay financial district concentrates API-native banking stack vendors serving Southeast Asian expansion strategies.
Brazil
Pix instant payment ubiquity forces traditional banks to modernize transaction processing architectures for sub-second settlement. The central bank's Drex digital currency pilot creates infrastructure demand for programmable money and smart contract settlement layers. São Paulo's financial technology cluster anchors open finance platform development serving Latin American embedded finance expansion.
Smart Financial Solutions Market Competitive Landscape
United States vendors anchor the cloud-native transformation tier; European specialists hold regulatory compliance integration positions. The vendor base splits between consolidated platform providers serving tier-one banking institutions and fragmented specialists targeting mid-tier credit unions and community banks. Three archetypes dominate: core banking modernizers, API middleware specialists, and embedded finance infrastructure providers. Strategic moves concentrate on multi-year transformation contract capture and banking-as-a-service partnership formation.
Within the core banking modernization tier, BPC Group and GRGBanking exemplify divergent geographic specializations. BPC Group represents European-origin platform consolidation targeting emerging market financial institutions with modular deployment architectures. GRGBanking occupies a position among Asia-Pacific hardware-integrated solution providers combining self-service terminal manufacturing with software stack delivery. Virtusa Corp. anchors the cloud-native engineering services archetype, sustaining multi-year relationships with tier-one banking institutions through microservices transformation capabilities. These three entities illustrate how vendor positioning fragments across technology maturity levels and client sophistication tiers rather than consolidating around unified platform standards.
| Leading Market Players |
|---|
| IMS Evolve |
| BPC Group |
| Miles Technologies |
| Zicom SaaS Pvt. Ltd |
| GRGBanking |
| ESQ Business Services, Inc. |
| hIOTron |
| Dialog Axiata PLC |
| Virtusa Corp. |
| Others |
Pricing and Supply Chain Analysis
Large retail banking institutions concentrate procurement among tier-one vendors, anchoring subscription-based SaaS pricing as the dominant commercial model across core banking and middleware platforms.
Pricing Analysis
Capacity additions in cloud-native engineering hubs are reshaping price floors for API middleware and core banking subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and regulatory certification grade. Price differentiation stems from FedNow compliance bundling and EU AI Act documentation depth. Mid-tier credit unions exhibit highest price sensitivity due to regulatory capital constraints, while tier-one banks prioritize capability over cost.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler infrastructure concentration in United States, Ireland, and Singapore data center clusters. Software component dependencies draw from Apache Kafka streaming platforms, Kubernetes orchestration layers, and specialized AI inference chips. Tariff exposure on semiconductor imports threatens margin stability for hardware-integrated terminal manufacturers. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving regional bank transformation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Financial Solutions Market functions as a stable compounder, with open banking mandates and real-time payment infrastructure driving recurring platform replacement cycles across regulated financial institutions.
For Market Incumbents: Cement multi-year transformation contract capture through FedNow and instant payment rail certifications. Deepen API-native integration layers to defend against cloud-native challengers. Prioritize EU AI Act compliance documentation to maintain European procurement eligibility against specialized regulatory technology entrants.
For New Entrants and Emerging Players: Launch via banking-as-a-service white-label stacks targeting United States community banks and United Kingdom building societies. Penetrate embedded finance partnerships with e-commerce and logistics platforms seeking licensed banking infrastructure. Exploit explainable AI mandates to displace black-box credit scoring incumbents in European high-risk underwriting segments.
For Investors and Strategic Acquirers: Consolidated banking technology vendors are the most active acquirer in this space, seeking API middleware specialists to fill capability gaps. Long-term viability rests on recurring revenue visibility from subscription pricing transitions. Monitor central bank digital currency pilot expansions as infrastructure replacement demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | FedNow certification accelerates instant payment capability deployment among regional banks. |
| Regulatory Compliance Investment | EU AI Act documentation capabilities secure high-risk underwriting procurement eligibility. |
| Strategic Partnership | Embedded finance alliances with logistics platforms expand distribution beyond traditional banking. |
| Acquisition of Specialist Firm | Explainable AI vendors attract consolidation interest from core banking platform providers. |
| Geographic Expansion | ASEAN treasury management platforms capture Monetary Authority of Singapore liquidity reporting demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged chief technology officers at tier-one banks, digital transformation leads at regional credit unions, API platform engineers, regulatory compliance officers, and banking-as-a-service partnership directors. Secondary validation drew from Federal Reserve payment system disclosures, European Banking Authority open banking implementation reports, SEC cybersecurity filings, and Monetary Authority of Singapore digital banking licensing frameworks. Bottom-up deployment tracking and top-down market sizing triangulated volume estimates.
Segment-weighting approaches applied service type, client type, technology choice, and offering format as analytical dimensions across the projection horizon. CAGRs derived from deployment velocity modeling against regulatory mandate timelines. Industry-specific inputs included FedNow adoption curves, EU AI Act conformity assessment schedules, and central bank digital currency pilot expansion patterns.
Several conditions sit outside the modeled scope, including geopolitical disruptions to hyperscaler infrastructure access and unanticipated regulatory fragmentation across ASEAN markets. Forecasts reflect documented assumptions about open banking mandate enforcement consistency and instant payment rail interoperability standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Australia Fintech Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
Financial Consolidation Software Market
FinTech
Smart Advisors Market
FinTech
China AI in Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
Spend Management Platform Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
North America Fintech Market
FinTech
Fintech Lending Market
FinTech
Financial Cloud Market
FinTech
India AI in Fintech Market
FinTech
Financial Management Software Market
FinTech
Stock Trading App Market