
 Germany AI in Fintech Market | 2026-2036
Germany AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Germany AI in Fintech Market Insights
Direct API distribution between neobanks and AI vendors is tilting away from legacy middleware providers. Hawk AI sustains dominance in transaction monitoring through specialized anti-money-laundering algorithms. Aleph Alpha anchors European language-model development with sovereign AI infrastructure for financial clients. Taxfix leverages automated tax-optimization tools to occupy the retail investor segment.
Germany AI in Fintech deploys machine learning, natural language processing, and neural networks to automate risk assessment, personalize wealth advisory, and detect anomalous transactions in real-time payment rails. Fraud detection solutions lead solution-category deployment as regulatory pressure intensifies, while robo-advisory platforms capture fastest growth among wealth managers seeking scalable portfolio construction. Natural language processing applications in customer support mature rapidly, though machine learning retains the deepest margin pools through proprietary training data and model refinement cycles.
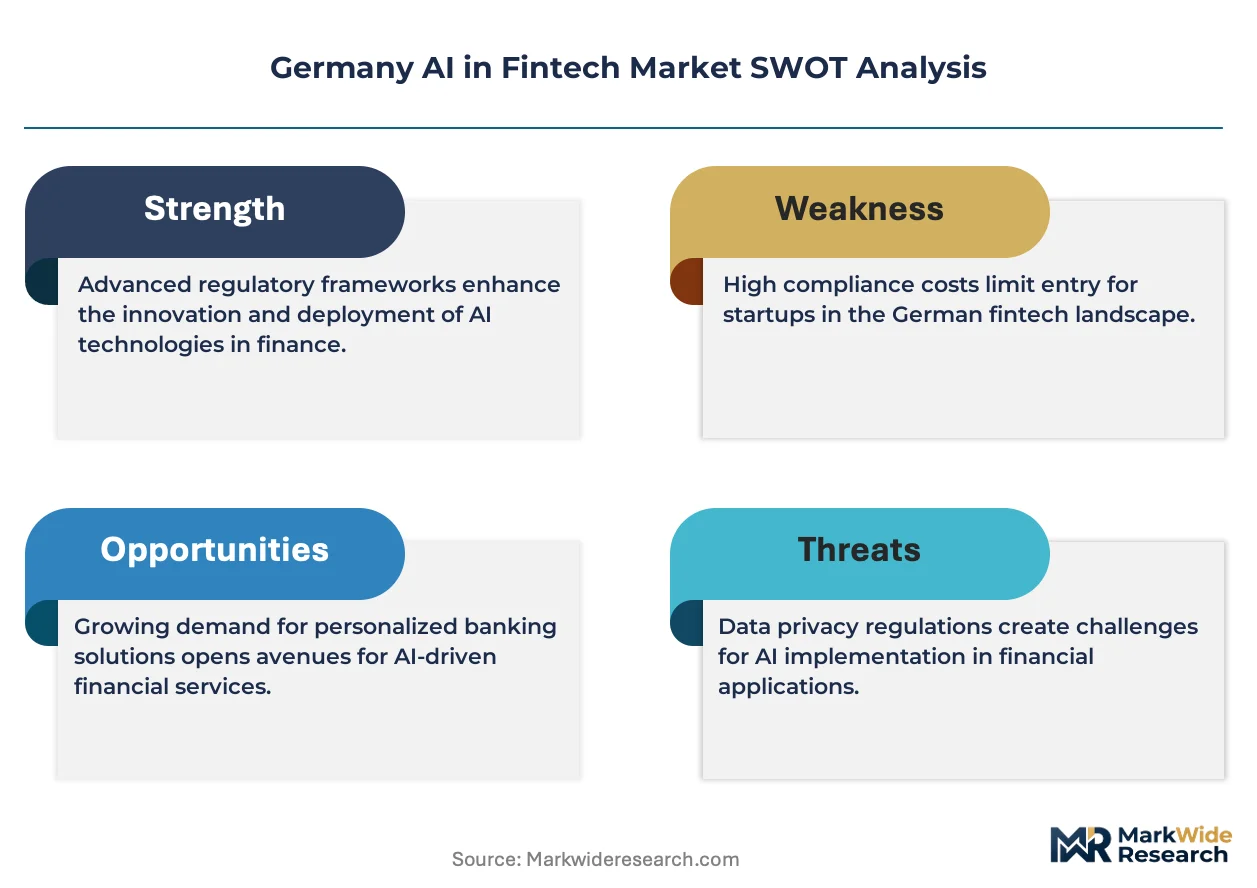
BaFin's AI supervisory guidelines and the EU AI Act's risk-based classification system shape product development timelines and vendor liability structures for automated financial decisions. KBA oversight of automotive-finance AI and Bundesbank payment-system standards further constrain market access for non-compliant providers. Stakeholders must monitor forthcoming EU-level algorithmic auditing mandates and calibrate compliance investments against the speed of model-deployment roadmaps.
Market Dynamics
BaFin's AI supervisory guidelines are compressing deployment timelines for automated credit decisions, forcing German banks to re-architect risk engines before algorithmic auditing mandates take effect.
Growth Catalysts
- EU AI Act risk classification:High-risk system designations for credit scoring are accelerating vendor investment in explainable model architectures. German retail banks now prioritize interpretable machine learning pipelines to preempt compliance gaps.
- Real-time payment rails:Instant payment infrastructure expansion under Bundesbank standards is creating embedded demand for transaction monitoring AI. Payment service providers require sub-second anomaly detection to meet settlement windows.
- Berlin fintech corridor:Venture concentration in Kreuzberg and Mitte districts is producing specialized talent pools for NLP-driven customer support tools. Neobanks recruit directly from Technical University AI labs.
Market Restraints
- GPU compute costs:Training cycles for large language models consume cloud infrastructure budgets that mid-tier fintechs cannot absorb. Sovereign AI alternatives from Aleph Alpha remain capacity-constrained.
- BaFin liability uncertainty:Automated decision-making accountability rules lack final interpretation, freezing procurement for high-stakes underwriting applications. Legal departments demand human-in-the-loop architectures that erode efficiency gains.
- Legacy core banking integration:Cobol-based deposit systems require expensive API middleware to feed data into modern ML pipelines. Savings banks face 18-24 month integration timelines.
Strategic Opportunities
- SME lending automation:Underpenetrated Mittelstand credit segments lack structured data for traditional scoring. Alternative data aggregation from ERP systems and trade registers enables new origination models.
- Tax-optimization tools:Retail investor segments show latent demand for automated capital gains harvesting. Integration with brokerage APIs creates sticky revenue streams beyond transaction fees.
- Cross-border compliance:German AI vendors can export transaction monitoring systems to Austrian and Swiss banks facing similar AML complexity. Shared German-language regulatory logic reduces localization costs.
Industry Challenges
- Model risk management talent:Quantitative validation specialists who understand both machine learning and BaFin capital requirements command premium compensation. Traditional risk departments lack retraining bandwidth.
- Explainability engineering:SHAP and LIME implementation for neural credit models requires specialized MLOps teams that German universities produce insufficiently. Vendors compete for scarce interpretability engineers.
- Data residency constraints:Bundesbank payment data localization rules prevent cloud-native training on cross-border infrastructure. Fintechs must maintain redundant German-only compute environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany AI in Fintech Market |
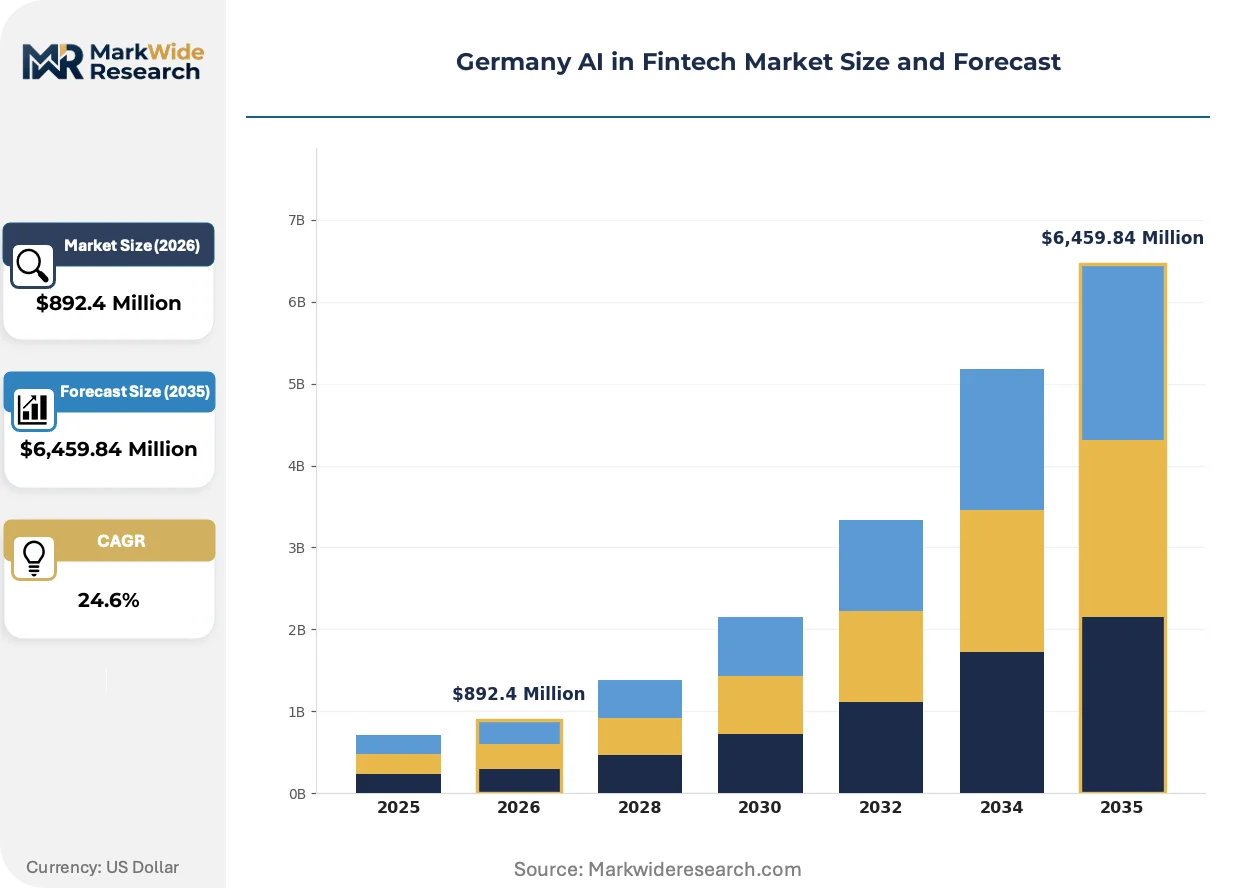
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $6,459.84 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Fraud Detection, Credit Scoring, Robo-Advisors, Customer Support Application: Wealth Management, Payment Processing, Risk Management, Investment Analysis End User: Retail Investors, Financial Institutions, Insurance Companies, Wealth Managers Technology: Machine Learning, Natural Language Processing, Neural Networks, Decision Trees |
| Companies Covered | Taxfix, Galytix, Hawk AI, Payhawk, Alphastream, Yokoy, Aleph Alpha, Pleo, Solaris, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany AI in Fintech Market Trends and Innovations
Federated learning architectures and sovereign cloud infrastructure are redrawing competitive boundaries between domestic AI developers and hyperscale providers in German financial services.
Transformer-based natural language processing is collapsing the cost structure of customer support operations in retail banking. Deutsche Bank and Commerzbank are deploying German-language dialogue systems for mortgage inquiries, compressing average handling times from twelve minutes to ninety seconds. This compression is eliminating tier-one offshore call center contracts and reallocating branch staff to advisory roles.
BaFin's algorithmic auditing draft guidelines are mandating documentation standards that favor established vendors with compliance infrastructure over lean fintech entrants. The industrial consequence is a two-tier market where incumbent banks delay procurement until interpretability frameworks mature. Wealth management robo-advisors face the tightest scrutiny, with several platforms redesigning portfolio construction logic to satisfy human-override requirements.
Corporate treasury departments are unbundling payment infrastructure from relationship banking, selecting AI-powered cash forecasting tools through direct vendor relationships rather than bundled offerings. This disintermediation is most visible in Baden-Württemberg's automotive supply chain, where mid-cap manufacturers subscribe to standalone liquidity optimization platforms. Savings banks in the region report declining treasury service attach rates as procurement autonomy shifts to CFO offices.
Germany AI in Fintech Market Segmentation
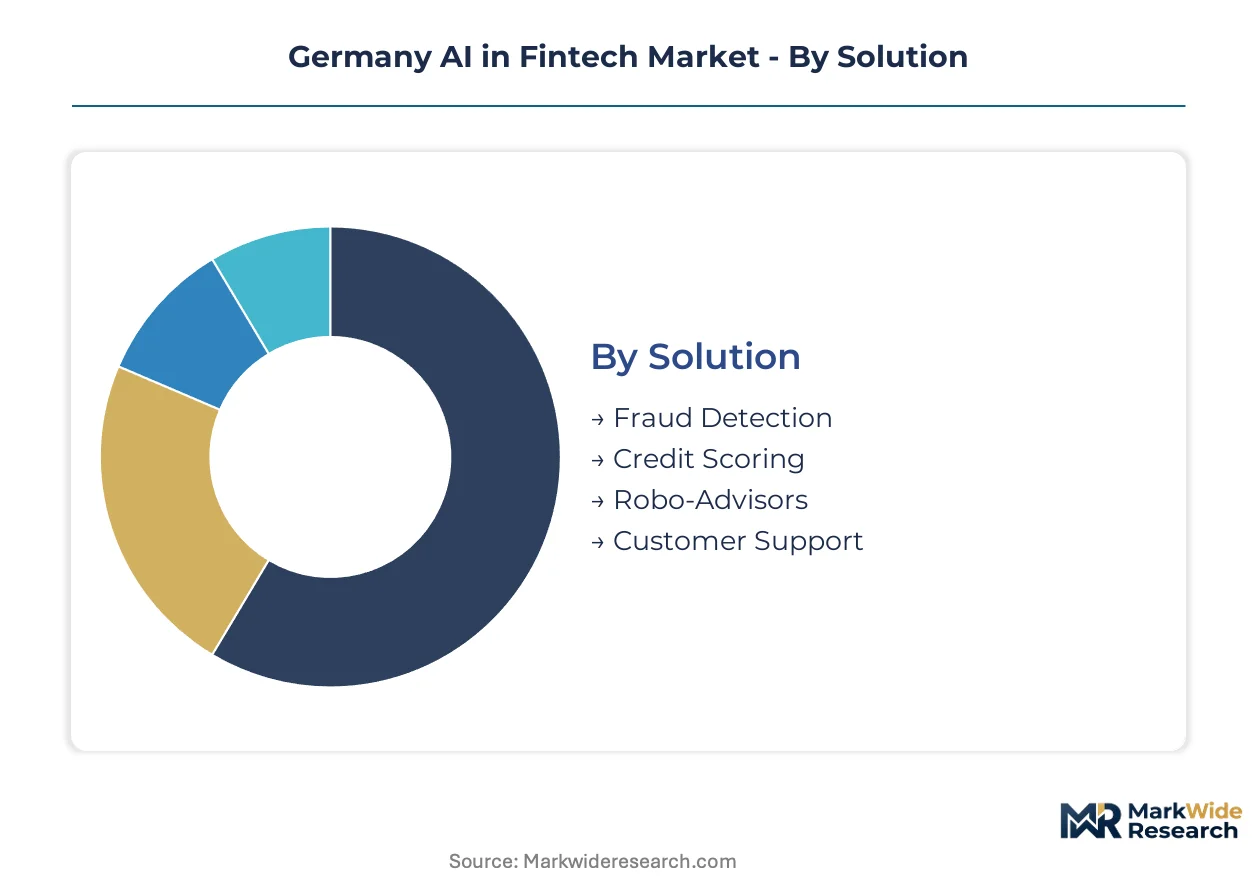
German fintech AI vendors configure product roadmaps around four intersecting dimensions. Solution types determine compliance burden under BaFin guidelines. Application focus shapes data architecture requirements and integration complexity with legacy core banking systems.
Solution:
Mature deployment patterns dominate transaction monitoring and credit infrastructure, while advisory automation remains emergent.
- Fraud Detection:Real-time anomaly detection systems process payment rails under Bundesbank settlement windows. German retail banks embed these tools directly into instant payment infrastructure to meet sub-second detection mandates. Transaction monitoring solutions absorb the largest share of AI procurement budgets as AML regulatory pressure intensifies.
- Credit Scoring:Machine learning pipelines automate Mittelstand lending decisions using alternative data from ERP systems and trade registers. BaFin's explainability requirements force interpretable model architectures that slow deployment timelines. Savings banks prioritize this segment to reduce manual underwriting costs in SME segments.
- Robo-Advisors:Automated portfolio construction tools target retail wealth accumulation with tax-optimization features. Platforms redesign recommendation engines to satisfy human-override mandates in draft auditing guidelines.
- Customer Support:German-language NLP systems compress mortgage inquiry handling from twelve minutes to ninety seconds. Deutsche Bank and Commerzbank deployments eliminate tier-one offshore call center contracts.
Fraud Detection handles the majority of throughput; Robo-Advisors is the fastest mover on share.
Application:
Cost tier stratification separates infrastructure-heavy payment processing from advisory applications with lighter compute demands.
- Wealth Management:Scalable portfolio construction and tax-loss harvesting automation capture retail investor segments. Robo-advisory platforms face tightest BaFin scrutiny for human-override compliance.
- Payment Processing:Sub-second anomaly detection embedded in real-time rails meets Bundesbank settlement standards. Payment service providers require continuous model retraining on transaction flows.
- Risk Management:Proprietary training data and model refinement cycles retain deepest margin pools. Quantitative validation specialists command premium compensation for ML and capital requirement expertise.
- Investment Analysis:Alternative data aggregation enables new origination models for underpenetrated credit segments. NLP-driven sentiment analysis matures rapidly for equity research automation.
Payment Processing commands the largest infrastructure investment; Wealth Management is expanding most quickly on regulatory clarity.
End User:
Customer type determines procurement autonomy and integration complexity with existing technology stacks.
- Retail Investors:Tax-optimization tools and automated advisory interfaces create sticky revenue streams beyond transaction fees. Direct API relationships with neobanks bypass legacy middleware providers.
- Financial Institutions:Cobol-based deposit systems require expensive API middleware to feed data into modern ML pipelines. Savings banks face 18-24 month integration timelines for core banking modernization.
- Insurance Companies:Underwriting automation and claims processing AI face emerging regulatory frameworks for algorithmic decision accountability.
- Wealth Managers:Scalable portfolio construction tools address high-net-worth advisory capacity constraints. Human-in-the-loop architectures erode efficiency gains but satisfy compliance departments.
Financial Institutions represent the largest contract value concentration; Retail Investors are gaining share fastest through neobank distribution channels.
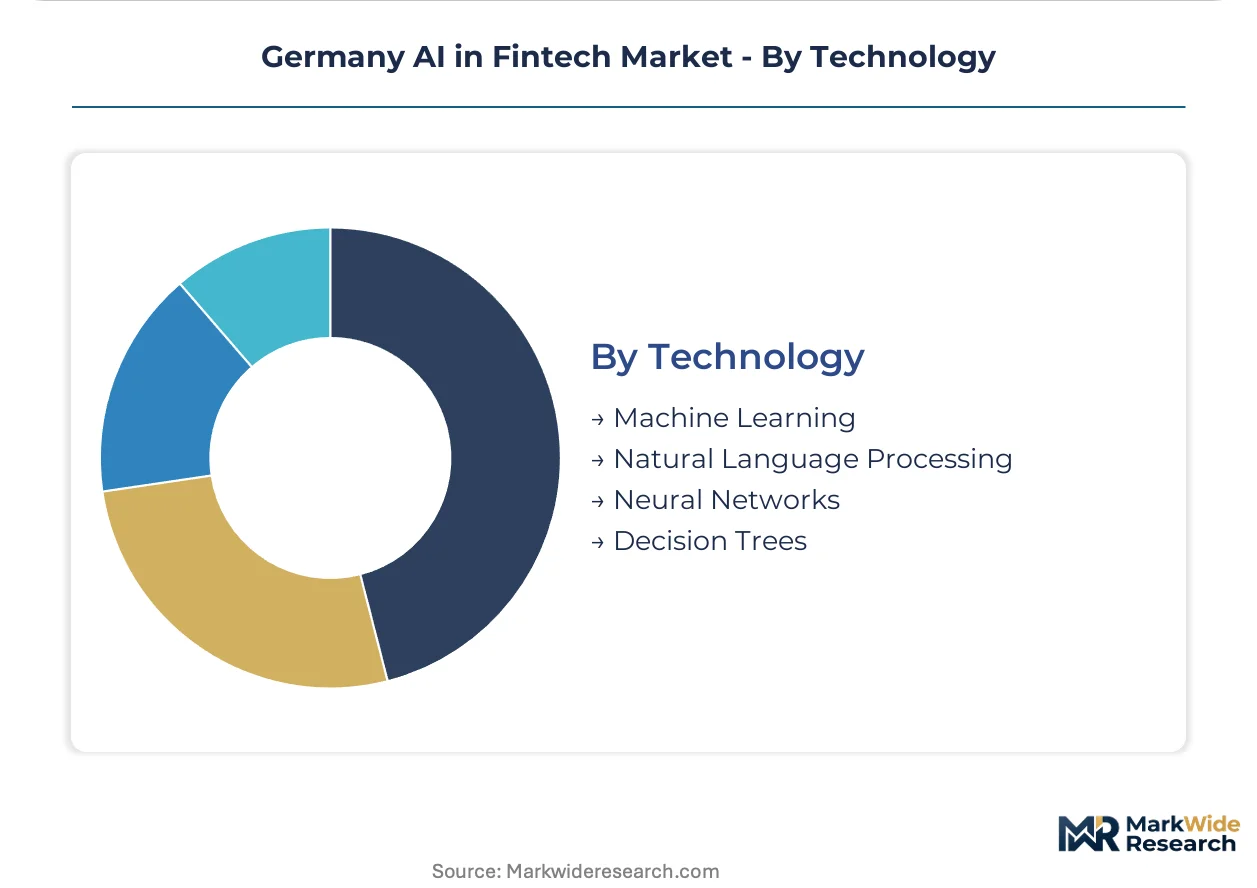
Technology:
Supply concentration in GPU compute and sovereign infrastructure alternatives shapes vendor selection criteria.
- Machine Learning:Proprietary training data and model refinement cycles generate deepest margin pools in credit scoring and risk applications. Interpretable pipelines preempt compliance gaps under EU AI Act high-risk designations.
- Natural Language Processing:Transformer-based German-language dialogue systems collapse customer support cost structures. Technical University AI labs in Berlin supply specialized talent for neobank recruitment.
- Neural Networks:SHAP and LIME implementation requirements strain MLOps team availability. Vendors compete for scarce interpretability engineers to satisfy BaFin documentation standards.
- Decision Trees:Transparent logic satisfies explainability mandates for automated underwriting applications. Mid-tier fintechs deploy these as interpretability-compliant alternatives to black-box neural architectures.
Machine Learning retains the dominant deployment footprint; Natural Language Processing shows the steepest expansion trajectory on customer service automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Frankfurt's banking district while Berlin's fintech corridor operates on venture-subsidized unit economics. This asymmetry shapes vendor procurement patterns across German sub-regions.
Bavaria
Munich's insurance and automotive finance clusters drive demand for underwriting automation and treasury AI. KBA oversight of automotive-finance algorithms constrains model deployment timelines. The Bavarian fintech ecosystem in Munich and Nuremberg attracts specialized talent from Technical University AI labs for NLP-driven customer tools.
Baden-Württemberg
Automotive supply chain manufacturers in Stuttgart seek standalone liquidity optimization platforms outside bundled banking relationships. BaFin's draft algorithmic auditing guidelines create procurement freezes for high-stakes applications. Corporate treasury departments in Karlsruhe and Mannheim disintermediate relationship banks through direct AI vendor contracts.
North Rhine-Westphalia
Cologne and Düsseldorf house legacy savings banks facing 18-24 month core banking modernization timelines for ML integration. Cobol-based deposit systems require expensive API middleware to feed modern pipelines. The Ruhr industrial belt generates Mittelstand credit demand that alternative data aggregation from ERP systems could serve.
Hesse
Frankfurt's concentration of systemically important banks absorbs the largest share of AI procurement budgets for transaction monitoring. Bundesbank payment-system standards mandate sub-second anomaly detection for instant settlement windows. The Mainz-Wiesbaden corridor hosts compliance infrastructure vendors serving EU-wide algorithmic auditing requirements.
Berlin-Brandenburg
Kreuzberg and Mitte districts concentrate neobank headquarters recruiting directly from Humboldt and TU Berlin AI programs. GPU compute costs constrain training cycles for mid-tier fintechs lacking hyperscale cloud budgets. Sovereign AI alternatives from domestic providers remain capacity-constrained despite regulatory preference for data residency.
Germany AI in Fintech Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying interpretable model architectures and German-language NLP engines. The vendor base stratifies between full-stack fraud detection suites and narrow compliance tools. Three archetypes dominate: transaction monitoring specialists with AML regulatory depth, sovereign language-model providers with data residency guarantees, and tax-optimization platforms with retail distribution. Competitive moves center on strategic partnerships with neobanks and portfolio expansion into adjacent compliance verticals.
Among Berlin-based fintechs, Taxfix and Yokoy exemplify the automated advisory archetype targeting retail and corporate expense segments respectively. Hawk AI anchors the transaction monitoring tier with specialized anti-money-laundering algorithms. Aleph Alpha occupies a distinctive position as the sovereign infrastructure alternative to hyperscale cloud providers, though capacity constraints limit mid-tier fintech access.
| Leading Market Players |
|---|
| Taxfix |
| Galytix |
| Hawk AI |
| Payhawk |
| Alphastream |
| Yokoy |
| Aleph Alpha |
| Pleo |
| Solaris |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in GPU cloud infrastructure across Frankfurt and Berlin data centers is compressing training-cycle economics for mid-tier fintechs while concentrating pricing power with hyperscale providers that absorb utilization shocks. This utilization asymmetry forces domestic AI vendors toward sovereign infrastructure alternatives that trade cost premiums for data residency compliance.
Pricing Analysis
The customization-premium spread between configured-to-order model architectures and standard SaaS-tiered subscriptions reaches three-to-one multiples in German fintech AI procurement. Subscription pricing dominates for transaction monitoring and customer support tools, while project-based licensing prevails for credit scoring implementations requiring BaFin-compliant explainability engineering. Price differentiation rests on certification tier—EU AI Act high-risk system designation carries 40-60% cost premiums—and vertical integration depth, with full-stack vendors capturing margin pools unavailable to component suppliers. Cost compression in standard NLP applications is intensifying because transformer-based dialogue systems commoditize rapidly; retail investors show highest price sensitivity, while systemically important banks in Hesse absorb premiums for sub-second anomaly detection guarantees.
Supply Chain Analysis
Contract-manufacturing concentration in GPU foundries rests with Taiwan Semiconductor Manufacturing and Samsung Foundry, which supply the compute layers underlying German fintech AI deployment. Geographic supply concentration centers on Taiwan, South Korea, and USA for advanced semiconductors; Germany and Netherlands for sovereign cloud infrastructure; and Ireland and Finland for EU-regulated data center capacity. Raw material dependencies span high-bandwidth memory modules, specialized AI accelerators, and redundant German-only compute environments mandated by Bundesbank localization rules. Single-source vulnerability in NVIDIA GPU supply creates procurement risk for training-intensive applications. Distribution runs through direct API relationships between neobanks and AI vendors, bypassing legacy middleware providers that previously intermediated enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German fintech AI is cycling through a compliance-driven investment recovery as BaFin's algorithmic auditing mandates force re-architecture of automated decision systems ahead of enforcement deadlines.
For Market Incumbents: Insulate core transaction monitoring revenue by embedding explainable model architectures before draft auditing guidelines crystallize; acquire scarce interpretability engineering talent from Technical University Berlin labs to preempt compliance gaps that freeze competitor procurement. Vertical integration into sovereign cloud infrastructure reduces hyperscale dependency as data residency constraints tighten. For New Entrants and Emerging Players: Build out white-space positions in Mittelstand credit scoring automation, where alternative data aggregation from ERP systems and trade registers enables origination models that incumbent savings banks cannot deploy within 18-24 month legacy integration timelines. Tax-optimization tools for retail investors offer the most penetrable segment given sticky revenue potential beyond transaction fees; pursue direct API distribution partnerships with neobanks to bypass legacy middleware gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sovereign AI infrastructure as GPU compute costs and redundant German-only environment requirements strain mid-tier fintech balance sheets. Long-term viability favors vendors with compliance infrastructure depth and established BaFin relationships over lean entrants facing documentation standard mandates. Acquisition targets should demonstrate interpretable pipeline architectures and existing high-risk system certifications; monitor EU-level algorithmic auditing mandate finalization as the decisive inflection signal for procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable Model Architecture Investment | BaFin's draft guidelines favor vendors with pre-built interpretability frameworks over lean entrants. |
| Sovereign Cloud Infrastructure Partnership | Aleph Alpha's capacity-constrained alternative to hyperscale providers addresses data residency demand. |
| Alternative Data Aggregation Platform | ERP system integration unlocks Mittelstand credit segments that traditional scoring cannot serve. |
| Direct API Distribution Channel | Neobank relationships disintermediate legacy middleware and compress customer acquisition economics. |
| Cross-Border Compliance Export | German-language regulatory logic reduces localization costs for Austrian and Swiss AML system sales. |
Research Methodology
Operator-level perspectives from BaFin supervisory staff, neobank CTOs, savings bank risk officers, and AI vendor solution architects anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against BaFin regulatory filings, Bundesbank payment-system standards, EU AI Act implementation guidance, and venture capital fintech investment databases. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from disclosed procurement budgets at systemically important banks.
Scenario-bracketing across conservative, baseline, and accelerated regulatory enforcement cases bounded the forecast range over the projection horizon. Segmentation dimensions modeled include solution type, application focus, end-user category, and technology layer, with cross-cutting analysis of deployment model complexity and compliance tier. CAGRs derived from fitted growth curves calibrated to historical fintech AI adoption patterns in comparable European jurisdictions, incorporating GPU compute cost trajectories and BaFin staffing expansion timelines as industry-specific inputs.
Stress conditions across algorithmic auditing mandate timing, GPU supply availability, and sovereign infrastructure capacity scaling were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory clarity progression and mid-tier fintech capital access continuity. Quarterly review of BaFin guidance publication velocity and neobank customer acquisition cost trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Services Cloud Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Netherlands AI in Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
US AI in Fintech Market
FinTech
Vietnam Fintech Market
FinTech
Malaysia Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
Financial Cloud Market
FinTech
Decentralized Finance Technology Market
FinTech
Spain AI in Fintech Market
FinTech
Germany Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
IT Financial Management Tools Market
FinTech
Robo-Advisory Services Market
FinTech
Fintech Lending Market