
 Robo Advisory Market | 2026-2036
Robo Advisory Market Size, Share, and Industry Trends Forecast 2026-2036
Robo Advisory Market Intelligence
Certified financial planner scarcity is redrawing competitive boundaries in automated wealth management. Betterment leverages its early-mover infrastructure to sustain low-cost ETF portfolio construction at scale. Vanguard Digital Advisor anchors its robo offering inside one of the world's largest mutual fund ecosystems, competing on expense ratio compression rather than feature proliferation.
Robo advisory denotes algorithm-driven portfolio construction and rebalancing delivered through digital interfaces with minimal human intervention, typically executing trades via API connections to custodial brokers and optimizing for Modern Portfolio Theory parameters such as Sharpe ratio maximization or tax-alpha generation. The primary commercial purpose is democratizing access to diversified, rules-based investment management for account balances below traditional wealth management minimums. Hybrid service models now capture the widest margin pools as firms charge premium basis points for periodic human advisor access while digital-only tiers drive customer acquisition volume. Passive management strategies dominate assets under algorithmic advice, though tax-loss harvesting modules represent the fastest-growing feature attachment as investors seek after-return optimization.
The SEC examines robo advisors under the Investment Advisers Act fiduciary standard, while the EU's MiFID II suitability and appropriateness tests constrain algorithmic recommendation engines across European Economic Area distribution. The UK's Financial Conduct Authority operationalized specific guidance on automated advice governance, including algorithm validation and client understanding verification. Stakeholders must monitor whether emerging AI-specific financial regulations in the United States and European Union trigger additional explainability requirements for black-box portfolio construction models.
Market Dynamics
The fiduciary standard's algorithmic application is compressing advisory margins while forcing infrastructure consolidation among automated wealth platforms. Custodial API economics and tax-loss harvesting module development now determine competitive viability more than brand recognition.
Growth Catalysts
- SEC Fiduciary Rule Evolution:The Investment Advisers Act's fiduciary interpretation tightens algorithmic disclosure requirements, accelerating compliance technology investment across US-registered platforms.
- Mobile-First Platform Architecture:Retail millennials and Gen Z investors demand native app experiences, pulling development resources away from desktop interfaces toward iOS and Android optimization.
- Modern Portfolio Theory Automation:Sharpe ratio maximization and tax-alpha generation modules execute via API connections to custodial brokers, eliminating manual rebalancing labor.
Market Restraints
- Certified Financial Planner Scarcity:Human advisor availability constraints limit hybrid model scaling as firms compete for credentialed talent to staff premium service tiers.
- Algorithm Validation Costs:EU MiFID II suitability and appropriateness tests impose ongoing compliance architecture expenses that compress digital-only margin structures.
- Black-Box Explainability Requirements:Emerging AI-specific financial regulations threaten additional governance burdens for proprietary portfolio construction models.
Strategic Opportunities
- United Kingdom Regulatory Sandbox:Financial Conduct Authority approval pathways enable faster algorithmic advice deployment than full authorization timelines in other jurisdictions.
- Tax-Loss Harvesting Attachment:After-return optimization modules represent underpenetrated feature expansion beyond core passive management offerings.
- Hybrid Service Tier Penetration:Periodic human advisor access commands premium basis points while digital-only tiers drive customer acquisition volume.
Industry Challenges
- Algorithm Governance Talent Gap:Firms struggle to hire technologists who understand both quantitative finance and SEC examination protocols.
- Legacy Custodial Integration:API standardization delays with established broker-dealers slow automated trade execution deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robo Advisory Market |
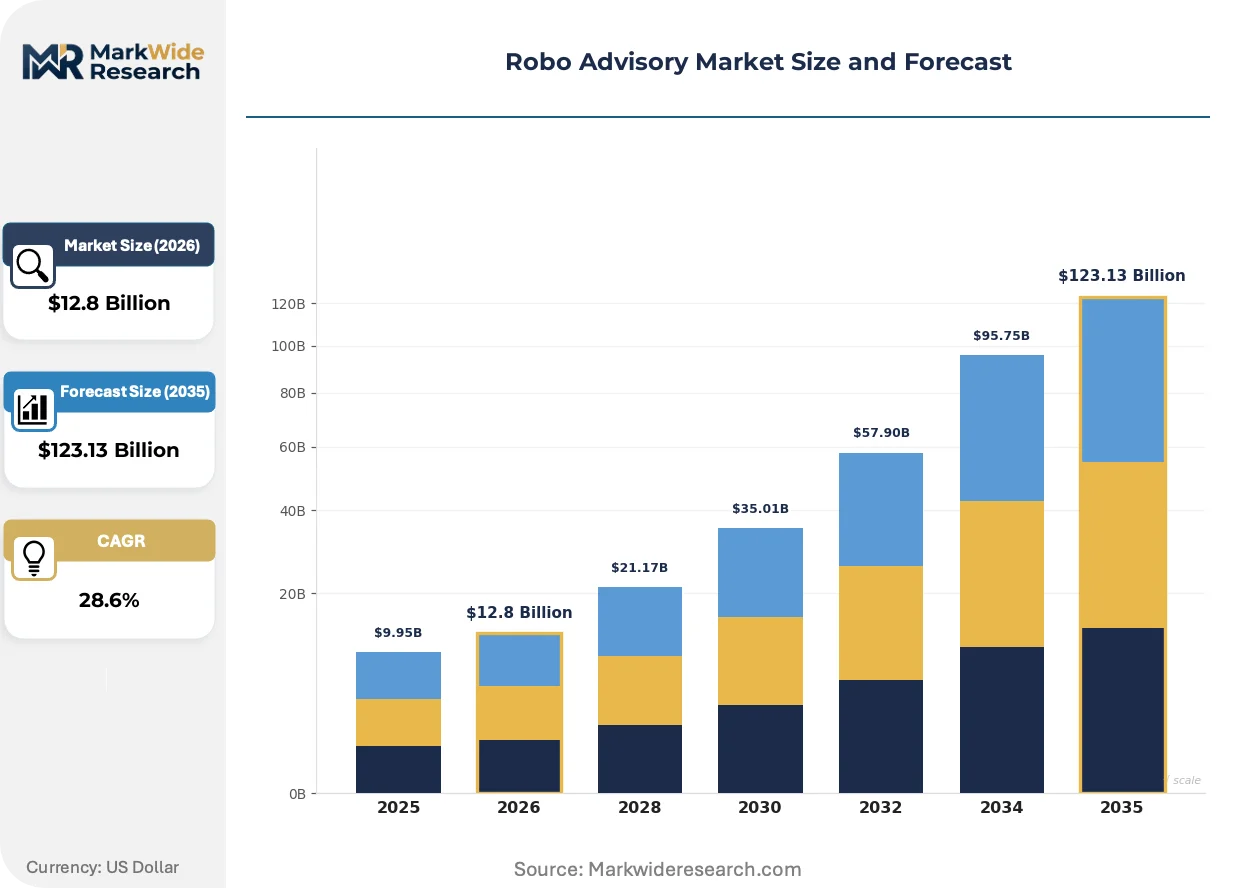
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $123.13 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: Full Service, Hybrid, Digital Only, Investment Management End User: Individual Investors, Small Businesses, Wealth Management Firms, Financial Institutions Technology Stack: AI Algorithms, Machine Learning, Data Analytics, Cloud Computing Investment Strategy: Passive Management, Active Management, Tax-Loss Harvesting, Risk Parity |
| Companies Covered | Betterment, Fidelity Go, Vanguard Digital Advisor, SigFig, Acorns, Empower, Wealthfront, Ellevest, Schwab Intelligent Portfolios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robo Advisory Market Strategic Shifts & Innovations
Algorithmic advice infrastructure is fragmenting between pure-play automation and human-augmented delivery models. Regulatory technology investments now consume development budgets previously allocated to feature differentiation.
Tax-loss harvesting engines are miniaturizing into modular microservices that platforms embed via API rather than building natively. Wealthfront and Betterment pioneered integrated harvesting, but mid-tier platforms now license third-party modules to compress development timelines. This componentization is miniaturizing the competitive moat of early movers while democratizing after-return optimization.
The EU AI Act's risk classification framework for financial algorithms imposes documentation and human oversight mandates on automated portfolio construction. European Economic Area distribution now requires algorithmic impact assessments before deployment. UK platforms operating under Financial Conduct Authority guidance face lighter touch requirements, creating regulatory arbitrage pressure.
Advisory procurement is compressing toward subscription and flat-fee models away from traditional assets-under-management pricing. Retail investors compare robo platforms on total cost transparency rather than hidden expense ratios. This behavioral shift pressures revenue per account while forcing scale economics to dominate profitability.
Robo Advisory Market Segmentation
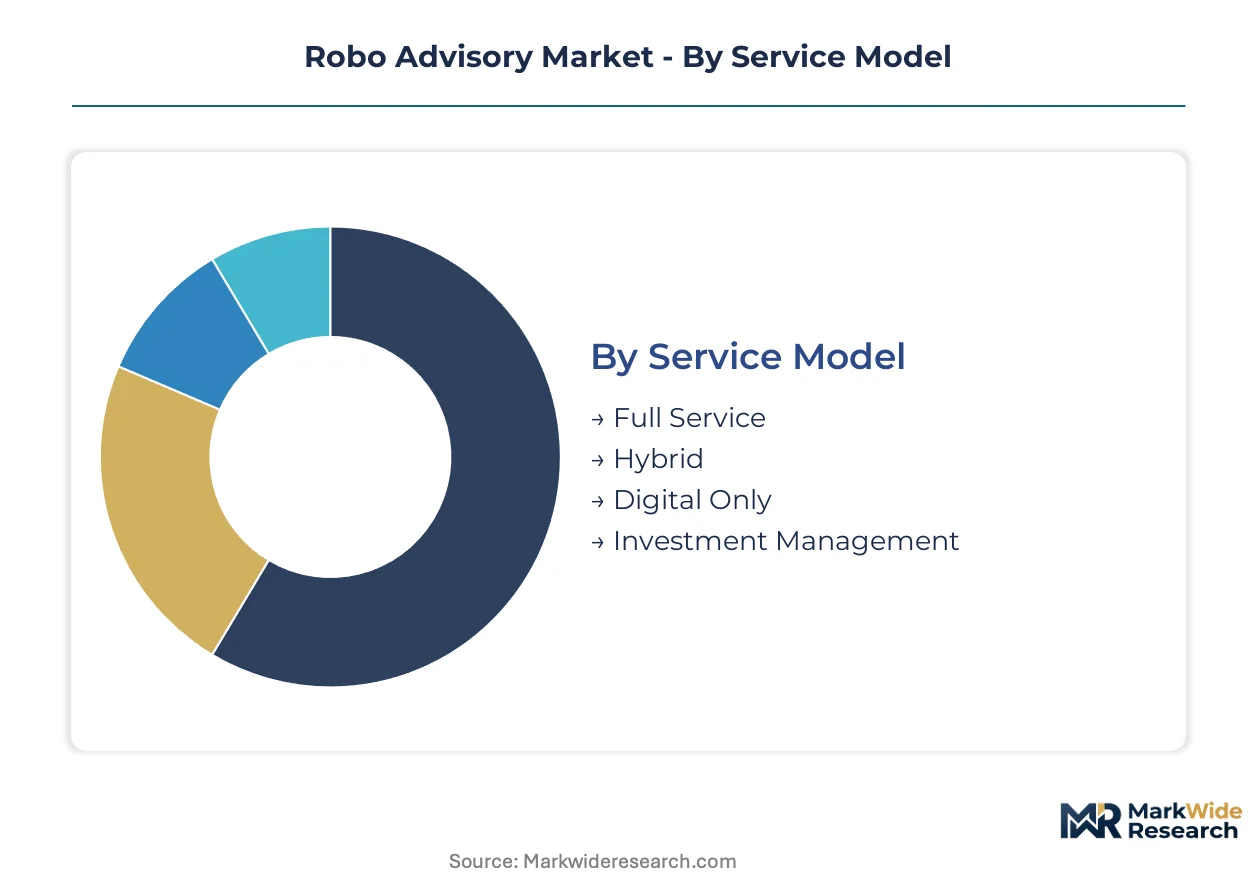
Service model architecture determines margin structure and regulatory burden across automated wealth platforms. End user concentration shapes API integration requirements and advisor staffing ratios. Technology stack choices separate proprietary development costs from licensed module economics.
Service Model:
Full Service and Hybrid offerings concentrate demand in the United States and United Kingdom where fiduciary litigation risk drives human advisor attachment. Digital Only tiers export most cleanly to jurisdictions with lighter algorithmic governance frameworks.
- Full Service:Comprehensive wealth planning combining algorithmic portfolio construction with dedicated human advisor access. Demand concentrates among high-net-worth segments in the United States where SEC fiduciary examination intensity makes human oversight a defensive necessity.
- Hybrid:Periodic advisor consultations layered over automated core infrastructure. The United Kingdom Financial Conduct Authority sandbox approvals accelerated deployment here, as lighter ongoing governance costs preserve margin compression tolerance.
- Digital Only:Pure automation executing Modern Portfolio Theory parameters via custodial APIs. Export-led adoption runs through EU jurisdictions where MiFID II suitability tests nonetheless constrain recommendation engine design.
- Investment Management:Discrete algorithmic execution without holistic planning modules. Compact offering attracts cost-sensitive retail flows in markets with established ETF custody infrastructure.
Full Service commands the established base. The steepest expansion runs through Hybrid.
End User:
Individual Investors drive volume economics through mobile-native acquisition channels. Financial Institutions and Wealth Management Firms concentrate in cost tier differentiation, with larger entities demanding white-label customization.
- Individual Investors:Retail account holders accessing diversified portfolios below traditional wealth management minimums. Millennial and Gen Z demographics in the United States pull development resources toward iOS and Android optimization over desktop interfaces.
- Small Businesses:Employer-sponsored retirement plan administration via automated allocation engines. Compact segment constrained by ERISA fiduciary complexity in the United States and equivalent pension governance elsewhere.
- Wealth Management Firms:Established advisors licensing robo infrastructure to compress service delivery costs for mass-affluent clients. Demand concentrates where certified financial planner scarcity makes human-augmented automation economically necessary.
- Financial Institutions:Banks and broker-dealers embedding algorithmic advice into existing customer relationships. White-label procurement patterns favor vendors with established custodial API integrations.
Individual Investors anchor volume economics. Financial Institutions are climbing the fastest for enterprise licensing revenue.
Technology Stack:
AI Algorithms and Machine Learning development concentrates in technology-forward jurisdictions with deep quantitative finance talent pools. Cloud Computing adoption spreads most quickly where data residency requirements remain permissive.
- AI Algorithms:Proprietary portfolio construction engines optimizing for Sharpe ratio maximization and tax-alpha generation. Black-box explainability requirements under emerging EU AI Act mandates threaten additional documentation burdens for European Economic Area deployment.
- Machine Learning:Predictive models for client risk profiling and behavioral forecasting. Demand concentrates among platforms seeking to reduce human advisor intervention frequency in hybrid service tiers.
- Data Analytics:Aggregation and visualization of portfolio performance metrics. Compact module increasingly licensed from third-party vendors rather than developed natively.
- Cloud Computing:Scalable infrastructure for trade execution and client interface delivery. Regulatory arbitrage pressure emerges as UK platforms face lighter data governance than EU counterparts under GDPR financial application.
AI Algorithms command the established base. Machine Learning is gaining share fastest for behavioral prediction capabilities.
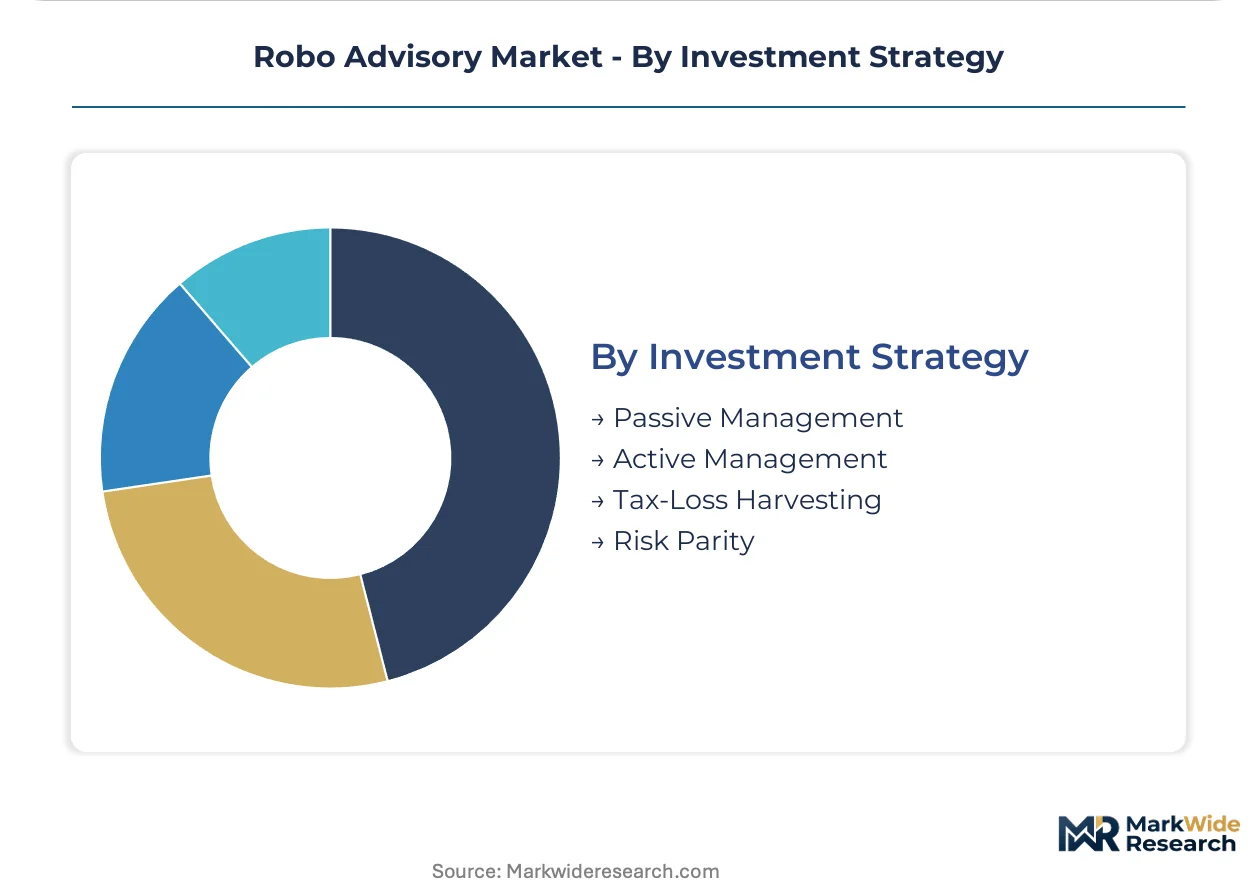
Investment Strategy:
Passive Management dominates assets under algorithmic advice through low-cost ETF construction. Tax-Loss Harvesting attachment rates concentrate in the United States where wash sale rules create optimization complexity worth module pricing.
- Passive Management:Rules-based ETF portfolio construction tracking market-cap-weighted or factor indices. Volume concentration in the United States reflects Vanguard and BlackRock custody infrastructure availability.
- Active Management:Algorithmic security selection attempting alpha generation beyond benchmark returns. Compact segment constrained by fee compression pressure and SEC scrutiny of performance advertising claims.
- Tax-Loss Harvesting:Automated realization of capital losses to offset gains and optimize after-return outcomes. Demand concentrates in the United States where IRS wash sale rules make manual execution labor-intensive.
- Risk Parity:Allocation frameworks balancing risk contribution across asset classes rather than capital weighting. Niche adoption among sophisticated investors seeking diversification beyond traditional 60/40 structures.
Passive Management commands the established base. Tax-Loss Harvesting is expanding most quickly as platforms compete on after-return optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC's fiduciary rule evolution anchors algorithmic wealth management governance in the United States, while the EU's MiFID II suitability framework and the UK Financial Conduct Authority's sandbox approvals create divergent compliance architectures across developed markets.
United States
Millennial and Gen Z retail investors drive mobile-first platform adoption through native iOS and Android interfaces. The SEC's Investment Advisers Act fiduciary standard tightens algorithmic disclosure requirements, forcing compliance technology investment. New York and San Francisco anchor development clusters where Betterment and Wealthfront built category-defining infrastructure.
United Kingdom
Digital wealth platforms accelerate deployment through Financial Conduct Authority regulatory sandbox approvals with lighter ongoing governance costs. MiFID II equivalence discussions shape cross-border algorithmic advice distribution. London concentrates fintech development talent alongside established asset management headquarters.
Germany
Conservative retail investor preferences sustain demand for hybrid service models combining automation with periodic human advisor access. BaFin scrutiny of algorithmic suitability tests imposes documentation burdens on recommendation engines. Frankfurt's banking cluster hosts white-label platform licensing for established financial institutions.
Canada
Cost-conscious retail flows concentrate in digital-only tiers executing passive ETF strategies through established custody infrastructure. CSA harmonized securities regulation shapes fiduciary disclosure requirements for automated advice. Toronto's financial district anchors domestic platform development alongside cross-border expansion targeting US investors.
Australia
SMSF trustee demand pulls algorithmic portfolio construction toward tax-optimization modules and after-return enhancement features. ASIC regulatory guidance on robo advice licensing imposes competence and technology governance requirements. Sydney and Melbourne fintech clusters concentrate platform development for Asia-Pacific market entry.
Robo Advisory Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across automated wealth management. Early-mover infrastructure advantages have consolidated around scale-driven platforms with established custodial API integrations, while newer entrants compete through specialized feature modules and demographic targeting. Three strategic archetypes dominate: pure-play automation specialists, incumbent asset manager digital arms, and fintech platforms with hybrid human advisor networks. Competitive moves concentrate on tax-loss harvesting module licensing and white-label infrastructure partnerships rather than proprietary development races.
Within the pure-play automation tier, Betterment and Wealthfront occupy foundational positions exemplifying algorithmic-first portfolio construction at scale. Vanguard Digital Advisor anchors the incumbent asset manager archetype, leveraging mutual fund ecosystem integration to compete on expense ratio compression. Schwab Intelligent Portfolios represents the brokerage-integrated model, embedding automated advice within established custodial relationships.
| Leading Market Players |
|---|
| Betterment |
| Fidelity Go |
| Vanguard Digital Advisor |
| SigFig |
| Acorns |
| Empower |
| Wealthfront |
| Ellevest |
| Schwab Intelligent Portfolios |
| Others |
Cost & Logistics Intelligence
API-first custodial connectivity replacing legacy broker-dealer integrations is redrawing supply geography toward cloud-native infrastructure hubs while compressing platform economics through modular component licensing.
Pricing Analysis
Geographic price spreads between United States and European Economic Area platforms reflect divergent regulatory compliance burdens rather than feature differentiation. Subscription and flat-fee models displace assets-under-management pricing as retail investors demand total cost transparency. Price differentiation hinges on hybrid advisor access frequency and tax-loss harvesting module inclusion. Cost compression in digital-only tiers intensifies as third-party API licensing erodes proprietary development premiums, with individual investors exhibiting highest price sensitivity while high-net-worth segments tolerate premium basis points for human advisor attachment.
Supply Chain Analysis
Just-in-time infrastructure deployment dominates as platforms provision cloud computing resources elastically against volatile retail acquisition cycles rather than maintaining fixed capacity reserves. Supply concentration centers on the United States, United Kingdom, and Germany where custodial API ecosystems and quantitative finance talent clusters coexist. Core inputs encompass cloud computing instances, machine learning development frameworks, and licensed financial data feeds. Single-source vulnerability runs through dominant custodial API providers whose outage windows halt trade execution. Distribution runs through direct-to-consumer mobile applications and white-label enterprise licensing to established financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tax-loss harvesting module licensing represents a service-attach opportunity expanding faster than core portfolio construction infrastructure as platforms seek after-return differentiation without proprietary development cycles.
For Market Incumbents: Secure exclusive custodial API partnerships to defend execution moats against emerging cloud-native entrants. Consolidate algorithm validation capabilities in-house to preempt SEC examination scrutiny of third-party model governance. Deepen vertical integration into tax-optimization microservices rather than licensing from specialist vendors. For New Entrants and Emerging Players: Anchor in United Kingdom regulatory sandbox pathways where Financial Conduct Authority approvals compress deployment timelines relative to full EU authorization. Target mid-tier wealth management firms facing certified financial planner scarcity as white-label infrastructure buyers. Pursue mobile-native user acquisition in millennial and Gen Z demographics through social media channel integration rather than traditional financial advertising. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with established custodial integrations and compliance technology infrastructure over pure algorithmic development shops. Long-term viability hinges on hybrid service tier penetration commanding sustainable premium pricing. Monitor SEC fiduciary rule evolution intensity as inflection indicator for compliance technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Tax-Loss Harvesting Module Licensing | Third-party API integration compresses development timelines for mid-tier platforms seeking after-return optimization. |
| Hybrid Service Tier Expansion | Periodic human advisor access commands premium basis points while digital-only tiers drive customer acquisition volume. |
| Custodial API Partnership Deepening | Exclusive execution relationships with established broker-dealers create defensive moats against cloud-native entrants. |
| Regulatory Technology Investment | Algorithm validation and explainability infrastructure preempts SEC examination scrutiny and EU AI Act compliance burdens. |
| Mobile-Native Platform Optimization | iOS and Android interface excellence captures millennial and Gen Z retail flows away from desktop-legacy competitors. |
Research Approach
A standing panel of robo platform product executives, SEC examination specialists, custodial API integration engineers, and retail wealth management advisors provided ongoing calibration across primary fieldwork. Secondary validation drew from SEC Investment Adviser Public Disclosure filings, EU MiFID II implementation reports, Financial Conduct Authority sandbox approval records, and cloud infrastructure provider financial disclosures. Bottom-up account aggregation and top-down regulatory framework analysis were triangulated against disclosed assets under management and platform revenue metrics.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled service model architecture, end user concentration, technology stack composition, and investment strategy attachment rates as core segmentation dimensions. CAGRs were derived through algorithmic adoption curve analysis and regulatory compliance cost trajectory modeling. Forecast inputs incorporated mobile-native user acquisition velocity and hybrid advisor staffing ratio economics.
Underlying assumptions cover SEC fiduciary rule stability, EU AI Act implementation timelines, and custodial API standardization progress, with deviation risk concentrated in emerging black-box explainability mandates and certified financial planner availability constraints. Revision becomes warranted when regulatory examination intensity crosses thresholds triggering platform consolidation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Spend Management Platform Market
FinTech
Fintech Technologies Market
FinTech
United Kingdom AI in Fintech Market
FinTech
North America AI in Fintech Market
FinTech
Malaysia Fintech Market
FinTech
Africa AI in Fintech Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
China Fintech Market
FinTech
France AI in Fintech Market
FinTech
Generative AI in Fintech Market
FinTech
Latin America AI in Fintech Market
FinTech
India AI in Fintech Market
FinTech
Financial Audit Software Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Germany Fintech Market
FinTech
Global Saas Spend Management Software Market