
 Supply Chain Finance Market | 2026-2036
Supply Chain Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Supply Chain Finance Market Outlook
Multi-sourced working capital programs is decoupling treasury functions from single-bank dependency across large corporate supply chains. JPMorgan Chase & Co anchors its position through proprietary on-premises deployment infrastructure serving Fortune 500 accounts payable networks. Deutsche Bank competes in European reverse factoring through deep correspondent banking relationships with automotive and industrial conglomerates. Taulia differentiates via cloud-based SaaS integration with enterprise ERP systems, capturing mid-market manufacturers seeking rapid deployment without IT overhead.
Supply chain finance encompasses a set of technology-enabled funding solutions that optimize cash conversion cycles by allowing buyers to extend payment terms while suppliers receive early payment against receivables, typically facilitated through dynamic discounting algorithms or bank-intermediated credit structures. The primary commercial purpose is to reduce working capital friction in buyer-dominated supply chains where payment terms often stretch beyond supplier liquidity tolerance. Reverse factoring currently dominates financing type volumes because it transfers buyer credit risk to financing institutions, unlocking lower-cost capital for tier-two and tier-three suppliers. Fintech companies represent the fastest-growing service provider category, displacing traditional financial institutions through API-native onboarding and real-time invoice validation. Cloud-based deployment models are capturing margin pools from legacy on-premises installations as banks and non-bank lenders seek scalable infrastructure without per-client hardware commitments.
Regulatory frameworks including RBI's trade receivables discounting system in India, the EU's CSRD sustainability disclosure requirements affecting supply chain due diligence, and ISO 20022 messaging standards are reshaping platform architecture and data reporting obligations across jurisdictions. RBI mandates electronic invoice registration on its TReDS platform, while CSRD compels large EU corporates to audit supplier payment practices as part of extended value chain disclosures. Stakeholders must monitor how open banking regulations and real-time payment infrastructure investments alter the competitive boundary between bank-led and fintech-led supply chain finance orchestration.
Market Dynamics
Multi-bank API orchestration is fragmenting single-institution dominance in corporate working capital programs, forcing treasury departments to manage liquidity across competing platform architectures rather than consolidated banking relationships.
Growth Catalysts
- ISO 20022 messaging standards:Harmonized data protocols reduce reconciliation friction between ERP systems and financier platforms, accelerating invoice validation cycles for mid-market manufacturers.
- India:RBI's TReDS mandate and PLI-linked working capital incentives draw fintech-bank consortiums into supplier financing ecosystems, expanding addressable supplier bases.
- Automotive reverse factoring:Tier-one assemblers deploy extended payment term programs to preserve own liquidity while maintaining tier-two supplier solvency through bank-intermediated early payment.
Market Restraints
- Credit risk concentration:Buyer-default exposure concentrates in single-obligor programs, limiting fintech scalability without bank balance sheet backing.
- Data sovereignty requirements:EU GDPR and India's data localization mandates fragment cloud infrastructure deployment, raising compliance costs for cross-border platform operators.
- Legacy ERP integration:On-premises SAP and Oracle installations resist real-time API connectivity, delaying SaaS adoption in industrial conglomerates with decades-old systems.
Strategic Opportunities
- SME supplier onboarding:API-native validation tools reduce KYC friction for unbanked tier-three suppliers in fragmented manufacturing supply chains.
- Sustainability-linked financing:EU CSRD disclosure requirements create demand for ESG-scored receivables products that reward supplier decarbonization milestones.
- Embedded finance convergence:Procurement software platforms integrate working capital APIs directly into purchase-to-pay workflows, bypassing standalone SCF portals.
Industry Challenges
- Interoperability talent scarcity:Shortage of engineers fluent in both banking core systems and modern cloud architecture delays platform migration timelines.
- Invoice fraud detection:Deepfake documentation and duplicate financing across multiple platforms require real-time blockchain verification investments.
- Regulatory arbitrage complexity:Divergent licensing regimes for non-bank lenders across jurisdictions fragment product standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supply Chain Finance Market |
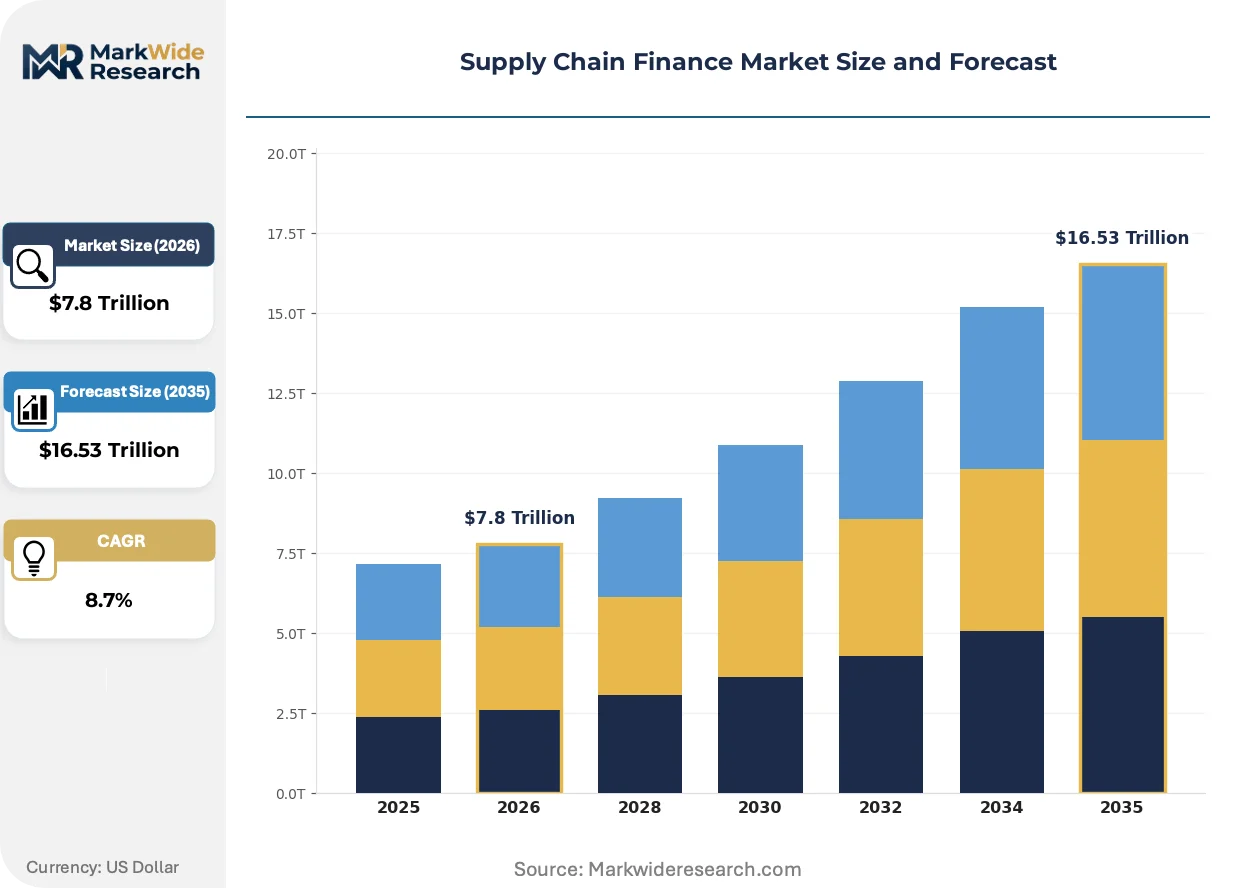
| Market Size in 2026 | $7.8 Trillion |
| Market Size in 2035 | $16.53 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Supplier Financing, Invoice Financing, Reverse Factoring, Working Capital Loans Service Provider: Banks, Fintech Companies, Asset-Based Lenders, Traditional Financial Institutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Software as a Service Customer Segment: Small and Medium Enterprises, Large Corporations, Multinational Companies, Startups |
| Companies Covered | Orbian, C2FO, PrimeRevenue, JPMorgan Chase & Co, GT Nexus, Demica, Ariba, Deutsche Bank, Taulia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supply Chain Finance Market Strategic Shifts
Distributed ledger infrastructure and open banking mandates are converging to displace bilateral paper-based trade finance, creating programmable money flows that self-execute against verified delivery milestones.
Blockchain-based smart contracts are rewriting settlement certainty in commodity trade finance by automating payment release upon IoT-confirmed delivery events. Agricultural traders and metals processors adopt these instruments fastest where physical inspection costs exceed digital verification overhead. The technology is compressing counterparty risk premiums and collapsing documentary processing from weeks to hours.
EU CSRD sustainability disclosure requirements now compel large corporates to audit supplier payment practices as part of extended value chain reporting obligations. This regulatory pressure forces procurement departments to document days-payable-outstanding metrics and justify term extensions beyond sector norms. Automotive and industrial equipment manufacturers face the steepest compliance burden, accelerating adoption of transparent reverse factoring programs that demonstrate supplier liquidity support.
Buyer-led financing models are displacing traditional supplier-initiated receivables discounting as procurement teams seize working capital optimization as a strategic priority. Large retailers and manufacturers now mandate early payment programs as a condition of supplier qualification, shifting negotiation leverage decisively toward the obligor. This pattern concentrates most visibly in German automotive supply chains and US retail private-label sourcing networks, where payment term extension has become a margin defense tactic against input cost inflation.
Supply Chain Finance Market Segmentation
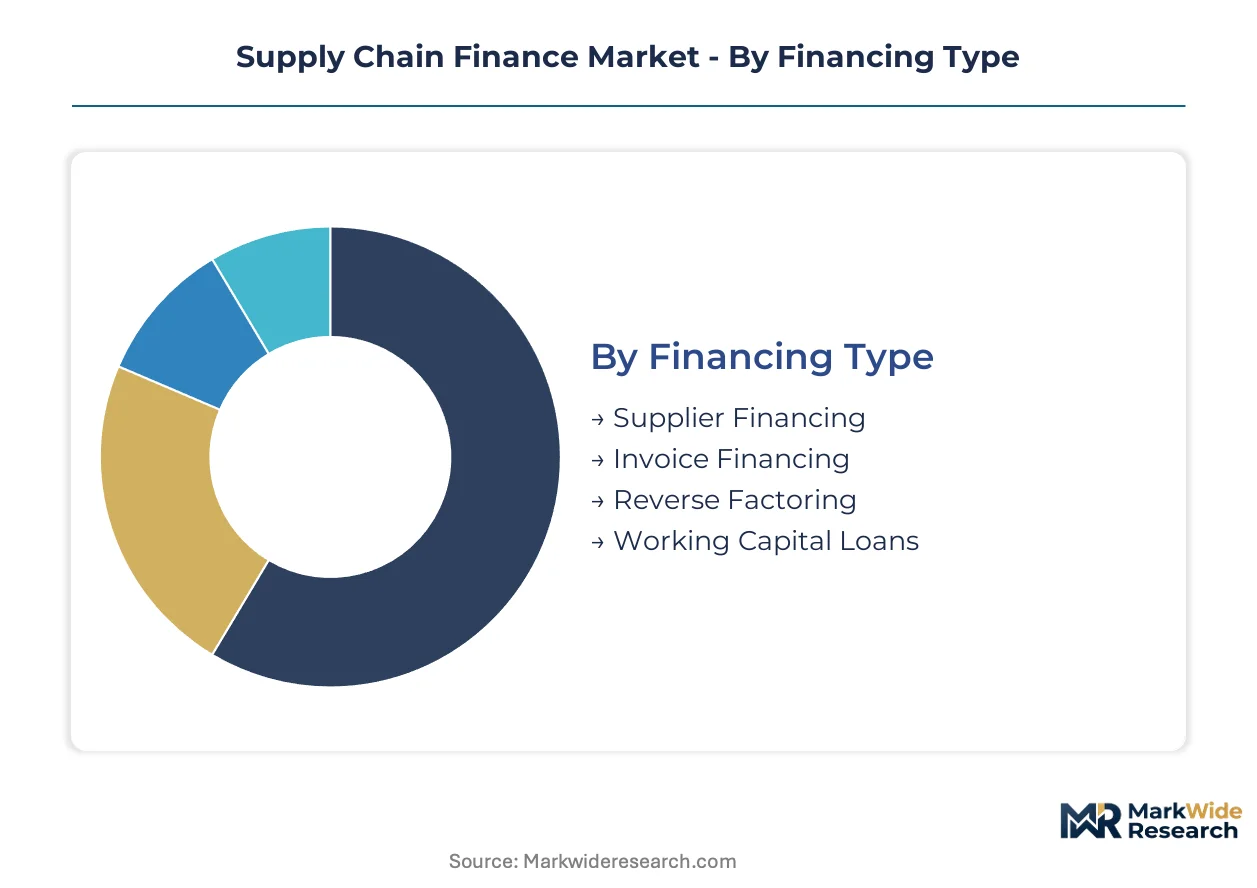
Segmentation in supply chain finance reveals how capital intensity, technical architecture, and buyer size reshape platform economics. Distinct financing instruments carry divergent balance sheet requirements, while deployment models determine scalability across buyer-supplier networks.
Financing Type:
Capital intensity varies sharply across instruments, with balance sheet-heavy products demanding deeper institutional backing than technology-enabled alternatives.
- Reverse Factoring:Bank-intermediated programs transfer buyer credit risk to financing institutions, enabling tier-two suppliers to access capital at the buyer's superior credit rating. German automotive assemblers and US retail networks deploy this instrument most aggressively to extend payment terms without triggering supplier insolvency.
- Invoice Financing:Suppliers pledge individual receivables against early payment, retaining credit exposure themselves. Indian manufacturing clusters and European mid-market exporters favor this structure where buyer creditworthiness varies across fragmented customer bases.
- Supplier Financing:Direct lending relationships between financiers and suppliers bypass buyer orchestration entirely. Asset-based lenders dominate this segment for inventory-heavy industrial suppliers.
- Working Capital Loans:General-purpose credit lines collateralized by receivables, inventory, or cash flow projections. Regional banks retain strong positions in this commoditized category.
Reverse factoring absorbs the bulk of installed capacity; invoice financing is expanding most quickly as API-native validation reduces onboarding friction for smaller suppliers.
Service Provider:
Margin profiles diverge between regulated balance sheet operators and technology orchestrators that capture fees without credit risk retention.
- Fintech Companies:API-native platforms automate invoice validation, supplier onboarding, and multi-bank orchestration without holding credit exposure. These operators capture SaaS fees and transaction commissions while scaling across jurisdictions faster than regulated lenders.
- Banks:Deposit-funded institutions leverage existing corporate relationships to anchor reverse factoring programs, absorbing credit risk in exchange for net interest margin. JPMorgan Chase and Deutsche Bank compete through proprietary infrastructure and correspondent networks.
- Asset-Based Lenders:Specialized non-bank financiers collateralize specific receivables and inventory positions for suppliers outside prime credit tiers.
- Traditional Financial Institutions:Captive finance arms of industrial conglomerates and legacy trade finance specialists with limited technology modernization.
Banks retain the dominant share of credit risk deployment; fintech companies are climbing the fastest as open banking mandates erode data moats.
Deployment Model:
Upfront infrastructure commitments separate legacy on-premises installations from variable-cost cloud alternatives.
- Cloud-Based:Scalable multi-tenant architecture enables rapid supplier onboarding without per-client hardware investment. Mid-market manufacturers adopt this model to bypass IT overhead and accelerate time-to-value.
- Software as a Service:Subscription pricing bundles platform access with continuous feature updates, shifting capital expenditure to operating expenditure for treasury departments.
- On-Premises:Proprietary hardware installations serving Fortune 500 accounts payable networks with stringent data sovereignty requirements. JPMorgan Chase maintains significant deployed base here.
- Hybrid:Sensitive core systems remain on-premises while supplier-facing portals leverage cloud scalability. European automotive manufacturers favor this architecture under GDPR constraints.
On-premises retains entrenched positions at the largest corporates; cloud-based solutions are gaining share fastest as ISO 20022 standardization reduces migration friction.
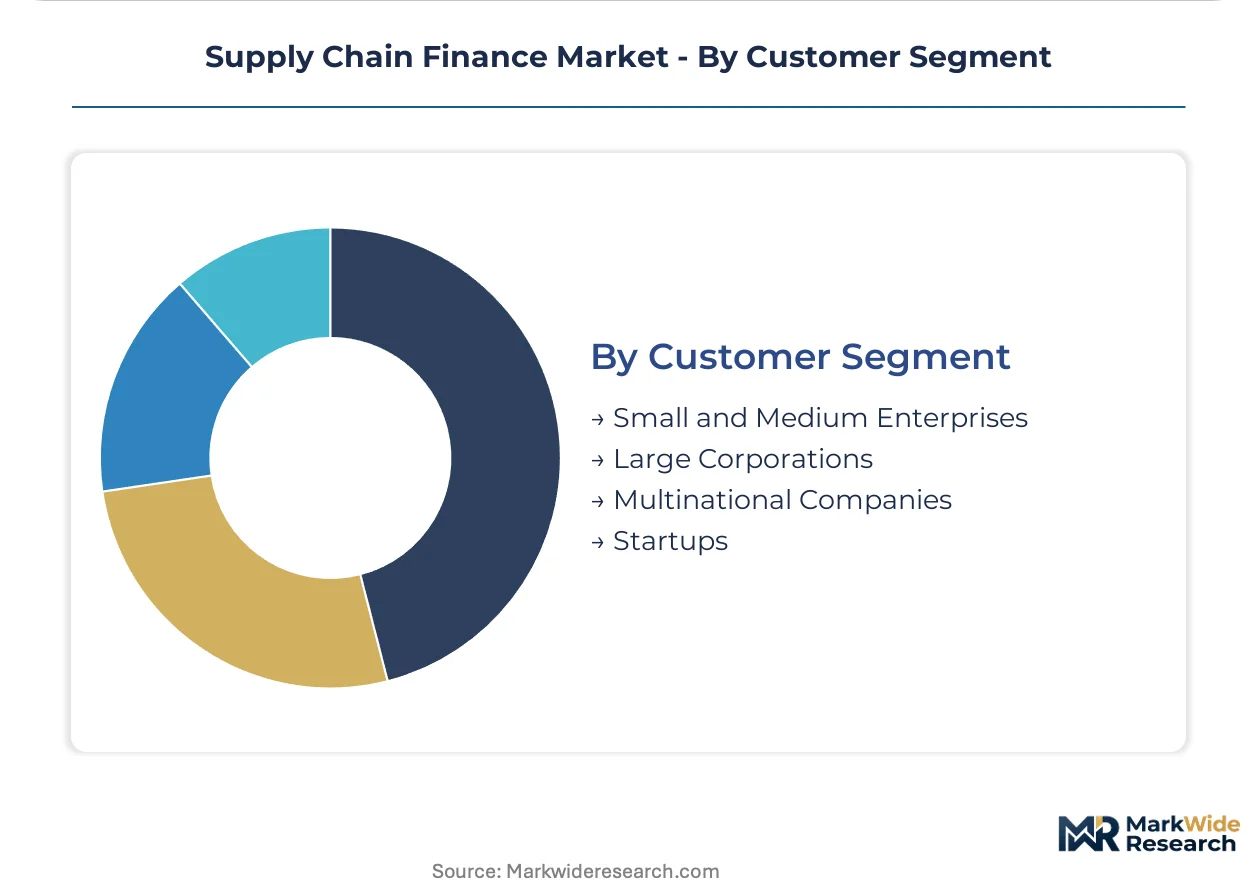
Customer Segment:
Working capital sophistication and bargaining power create tiered demand patterns across buyer size categories.
- Large Corporations:Sophisticated treasury functions negotiate multi-bank programs and mandate supplier participation in reverse factoring networks. These buyers capture the steepest payment term extensions.
- Multinational Companies:Cross-border supply chains require jurisdiction-compliant platforms handling multi-currency receivables and divergent regulatory regimes.
- Small and Medium Enterprises:Fragmented supplier bases and limited treasury staff drive demand for fully outsourced, API-integrated solutions with minimal configuration.
- Startups:Venture-backed growth companies prioritize speed over cost, accepting premium financing rates to preserve equity runway.
Large corporations command the deepest program penetration; small and medium enterprises represent the steepest expansion trajectory as platform economics improve for sub-scale buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates working capital demand through RBI's TReDS mandate and PLI-linked supplier financing incentives, while Germany and the United States anchor automotive reverse factoring volumes. China and the United Kingdom complete the demand core through divergent regulatory pathways.
India
Mumbai and Delhi-NCR manufacturing clusters drive fintech-bank consortium formation around electronic invoice discounting. RBI mandates TReDS platform registration for receivables above specified thresholds, compressing supplier onboarding timelines. Tamil Nadu automotive suppliers and Gujarat textile exporters represent the fastest TReDS adoption corridors as working capital incentives flow through PLI-linked schemes.
Germany
Stuttgart and Munich automotive assemblers deploy extended payment term programs to preserve liquidity against input cost pressure. BaFin supervision of non-bank lenders shapes fintech licensing requirements for platform operators. Bavarian industrial equipment manufacturers and Baden-Württemberg tier-one suppliers anchor continental reverse factoring volumes through bank-intermediated early payment structures.
United States
Detroit automotive networks and Dallas-Fort Worth retail procurement hubs concentrate buyer-led financing program deployment. SEC disclosure requirements for supplier payment practices influence treasury transparency standards. Southeast manufacturing corridors and Midwest industrial clusters drive cloud-based platform adoption as mid-market manufacturers bypass legacy IT infrastructure.
China
Shanghai and Shenzhen electronics assemblers integrate supply chain finance APIs into procurement workflows at scale. SAMR oversight of fintech platforms shapes data localization requirements for cross-border receivables processing. Yangtze River Delta automotive suppliers and Pearl River Delta consumer electronics manufacturers represent the densest smart contract pilot deployment for IoT-triggered payment release.
United Kingdom
London-based multinational treasury functions negotiate multi-bank programs across European supplier networks. FCA open banking mandates accelerate API-native platform adoption for mid-market exporters. Midlands automotive component clusters and Northern England industrial suppliers drive demand for hybrid cloud deployments under GDPR constraints.
Supply Chain Finance Market Competitive Environment
Strategic partnerships dominate the current landscape as platform operators seek bank balance sheet backing to scale beyond credit risk limitations. The vendor base stratifies across three tiers: deposit-funded institutions with proprietary infrastructure, API-native fintech orchestrators capturing SaaS fees without credit exposure, and hybrid consortia combining technology velocity with regulated lending capacity. Consolidation pressure concentrates most visibly in mid-market SaaS providers seeking correspondent banking relationships, while geographic expansion and technology licensing represent parallel competitive vectors.
Within the deposit-funded tier, JPMorgan Chase & Co and Deutsche Bank occupy positions defined by on-premises deployment scale and correspondent network depth. Taulia exemplifies the cloud-native archetype through ERP-integrated SaaS models that reduce IT overhead for mid-market treasury departments. These three anchors illustrate how competitive positioning diverges between balance sheet-heavy and technology-lightweight operating models across buyer-supplier network orchestration.
| Leading Market Players |
|---|
| Orbian |
| C2FO |
| PrimeRevenue |
| JPMorgan Chase & Co |
| GT Nexus |
| Demica |
| Ariba |
| Deutsche Bank |
| Taulia |
| Others |
Value Chain & Pricing Dynamics
Automotive manufacturers' mandated payment term extensions to 120 days are forcing fintech platforms and bank consortiums to restructure working capital products, compressing margins on reverse factoring arrangements while elevating API-native orchestration premiums. Suppliers absorbing longer cash conversion cycles demand faster onboarding and real-time validation, shifting platform economics toward volume-scaled SaaS tiers.
Pricing Analysis
Volume-scaled transaction fees dominate bank-led reverse factoring, while SaaS subscription tiers capture mid-market manufacturers seeking variable cost structures without balance sheet commitment. Price differentiation hinges on ISO 20022 compliance certification and multi-bank API orchestration depth, with cloud-native platforms commanding premiums over legacy on-premises installations. Pricing pressure stems from fintech entrants automating supplier onboarding at lower unit economics, eroding incumbent bank margins. Small and medium enterprises exhibit highest price sensitivity, while Fortune 500 treasury functions prioritize integration reliability over cost.
Supply Chain Analysis
Regional data centers in Mumbai, Frankfurt, and Singapore anchor cloud infrastructure for multi-tenant platform deployment, with hub-and-spoke distribution patterns extending to tier-two supplier clusters. Platform development concentrates in India, Germany, and the United States, drawing engineering talent from fintech corridors and banking technology hubs. Raw material dependencies include semiconductor chips for IoT validation hardware, optical fiber for low-latency connectivity, and specialized cooling systems for data center operations. Single-source vulnerability in cloud hyperscaler concentration poses structural risk. Distribution runs through direct API integration into ERP systems rather than standalone portal access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native orchestration platforms are displacing legacy on-premises installations as ISO 20022 standardization and open banking mandates accelerate API-first working capital solutions. This technology transition rewards operators with scalable multi-tenant architecture and real-time invoice validation capabilities.
For Market Incumbents: Extend proprietary correspondent banking networks into hybrid cloud deployments to counter fintech API-native threats. Deepen vertical integration through captive data center infrastructure in India and Germany under RBI and GDPR localization mandates. Prioritize certification investment in ISO 20022 message handling to maintain enterprise treasury relationships against SaaS entrants.
For New Entrants and Emerging Players: Capture SME supplier onboarding white space through automated KYC tools and blockchain-based invoice verification. India's TReDS-mandated manufacturing clusters and US Midwest industrial corridors represent most penetrable geographies. Lead with embedded finance partnerships integrating working capital APIs directly into procurement software workflows.
For Investors and Strategic Acquirers: The window for entry favors API-native fintech platforms with bank balance sheet partnerships over pure technology orchestrators. Long-term viability hinges on regulatory licensing breadth across RBI, BaFin, and FCA jurisdictions. Monitor CSRD sustainability disclosure enforcement as inflection indicator for ESG-scored receivables product demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Bank API Orchestration | Reduces single-institution dependency for corporate treasury departments managing liquidity across competing platforms. |
| ISO 20022 Compliance Investment | Accelerates invoice validation cycles and reduces reconciliation friction between ERP systems and financier platforms. |
| Cloud Infrastructure Localization | Satisfies RBI data residency mandates and GDPR sovereignty requirements for cross-border platform operators. |
| Blockchain Invoice Verification | Addresses deepfake documentation and duplicate financing risks through distributed ledger transparency. |
| ESG-Linked Receivables Products | Aligns with EU CSRD disclosure requirements rewarding supplier decarbonization milestones through preferential financing rates. |
Study Parameters
Multi-period observation of invoice validation cycle times, supplier onboarding velocity, and platform transaction volumes anchored the trend analysis, supplemented by interviews with treasury operations directors, fintech platform engineers, commercial banking relationship managers, and procurement technology specialists. Secondary validation drew from RBI TReDS registration disclosures, BaFin non-bank licensing records, SEC supplier payment practice filings, and ISO 20022 implementation timelines across major correspondent banks. Bottom-up segment sizing triangulated against top-down working capital demand estimates derived from automotive and industrial production forecasts.
Input-output matrices modeled financing type deployment, service provider revenue mix, and cloud versus on-premises adoption curves across the projection horizon. Segmentation dimensions included financing instrument structure, platform deployment architecture, buyer size category, and regional regulatory framework cluster. CAGRs were derived from trend extrapolation of electronic invoice registration volumes and fintech-bank consortium formation rates, cross-referenced against working capital optimization intensity in automotive and retail procurement networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to open banking mandate enforcement timing and cross-border data localization rule harmonization. Outputs reflect documented assumptions regarding ISO 20022 adoption velocity and regulatory clarity for non-bank lender licensing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Business Analytics in Fintech Market
FinTech
Financial Analytics Market
FinTech
Micro-Investing Platform Market
FinTech
Saudi Arabia Fintech Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
China AI in Fintech Market
FinTech
Spend Management Platform Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Transaction Monitoring Software Market
FinTech
Hand Account Software Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
US AI in Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
Financial App Market
FinTech
China Fintech Market
FinTech
Germany AI in Fintech Market