
 Greece Property and Casualty Insurance Market | 2026-2036
Greece Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Property and Casualty Insurance Market Insights
Comprehensive coverage tier upgrades is reorganizing the competitive landscape in Greek property and casualty insurance. Allianz Hellas Insurance Company SA leverages its multinational reinsurance backing to sustain superior capital reserves against catastrophe risks. Ethniki Hellenic General Insurance Co SA anchors its position through an extensive branch network penetrating secondary cities and island economies. European Reliance General Insurance Co SA differentiates via specialized commercial lines serving the shipping and logistics corridor.
Property and casualty insurance constitutes risk transfer instruments covering physical asset damage, liability exposure, and financial loss from operational interruption, with policies structured around actuarial pricing models incorporating geographic peril mapping and claims severity distributions. The primary commercial purpose centers on enabling business continuity and asset protection for policyholders exposed to natural catastrophe, theft, fire, and third-party liability contingencies. Auto policy lines dominate premium volume through mandatory third-party liability obligations tied to Greece's national vehicle registry, while commercial coverage exhibits the fastest expansion as SMEs formalize risk management practices. Distribution channel segmentation reveals broker networks capturing the largest share of commercial placements due to their advisory role in complex coverage structuring, whereas direct online platforms gain traction among individual purchasers seeking standardized homeowners and renters products.
The Bank of Greece enforces Solvency II-derived capital requirements and conducts stress testing on domestic insurers, compelling carriers to hold higher quality capital against earthquake and flood exposure concentrated in coastal zones. EU Green Deal alignment pressures through EIOPA guidelines are reshaping product design toward climate risk disclosure and sustainable asset allocation within investment portfolios. Stakeholders must monitor how regulatory tightening on catastrophe reserving intersects with evolving customer expectations for digital claims settlement speed.
Market Dynamics
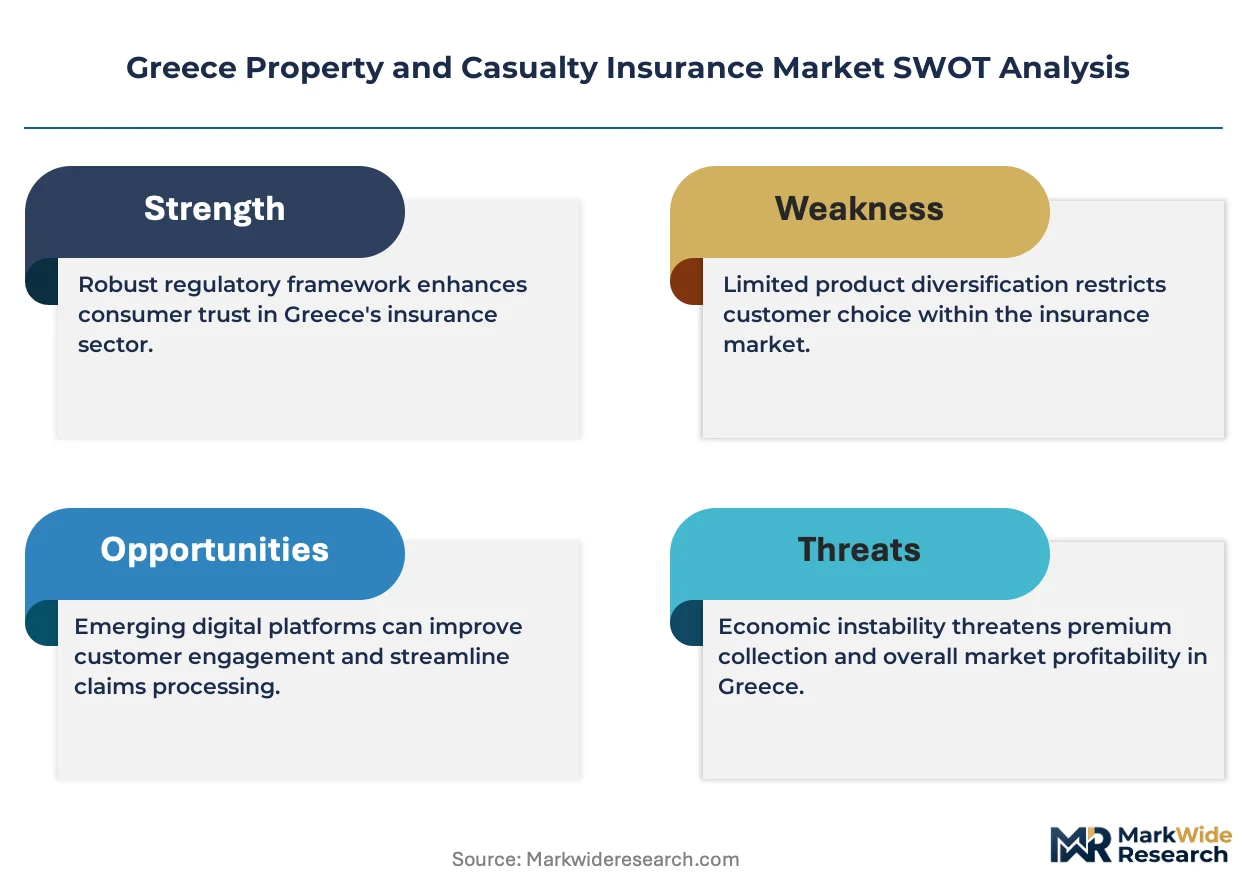
Solvency II transposition by the Bank of Greece is compressing capital adequacy margins for domestic carriers while elevating barriers for smaller underwriters unable to access diversified reinsurance pools.
Growth Catalysts
- EU Green Deal alignment:EIOPA guidelines on climate risk disclosure are forcing product redesign toward sustainable asset allocation, creating premium differentiation for compliant carriers.
- Tourism sector formalization:Small hospitality operators in Crete and the Cyclades are purchasing commercial property coverage at accelerating rates as bank lending requirements tighten.
- Telematics integration:Usage-based motor policies leveraging real-time driving data are decomposing traditional risk-pooling models and attracting younger policyholders in Attica.
Market Restraints
- Reinsurance cost escalation:Catastrophe bond spreads for earthquake exposure are compressing domestic underwriting margins as global climate loss ratios deteriorate.
- Branch network fixed costs:Ethniki Hellenic's extensive island presence anchors operational drag that direct digital competitors avoid entirely.
- Regulatory reserving friction:Solvency II stress-testing requirements for flood exposure in coastal Thessaly are locking capital that could deploy into growth segments.
Strategic Opportunities
- Underpenetrated Peloponnese:Agricultural cooperative formations in Messenia and Laconia present latent demand for crop and equipment coverage with minimal incumbent saturation.
- Embedded distribution partnerships:Digital banking platforms operated by Eurobank and Piraeus Bank are opening white-label insurance attachment points at loan origination.
- Parametric catastrophe products:Satellite-triggered earthquake and wildfire payouts are bypassing traditional claims adjustment friction for commercial property holders.
Industry Challenges
- Actuarial talent scarcity:Catastrophe modeling expertise concentrated in Athens struggles to serve decentralized branch operations in island economies.
- Legacy core system integration:Mainframe policy administration platforms at established carriers resist API connectivity with insurtech distribution partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Property and Casualty Insurance Market |
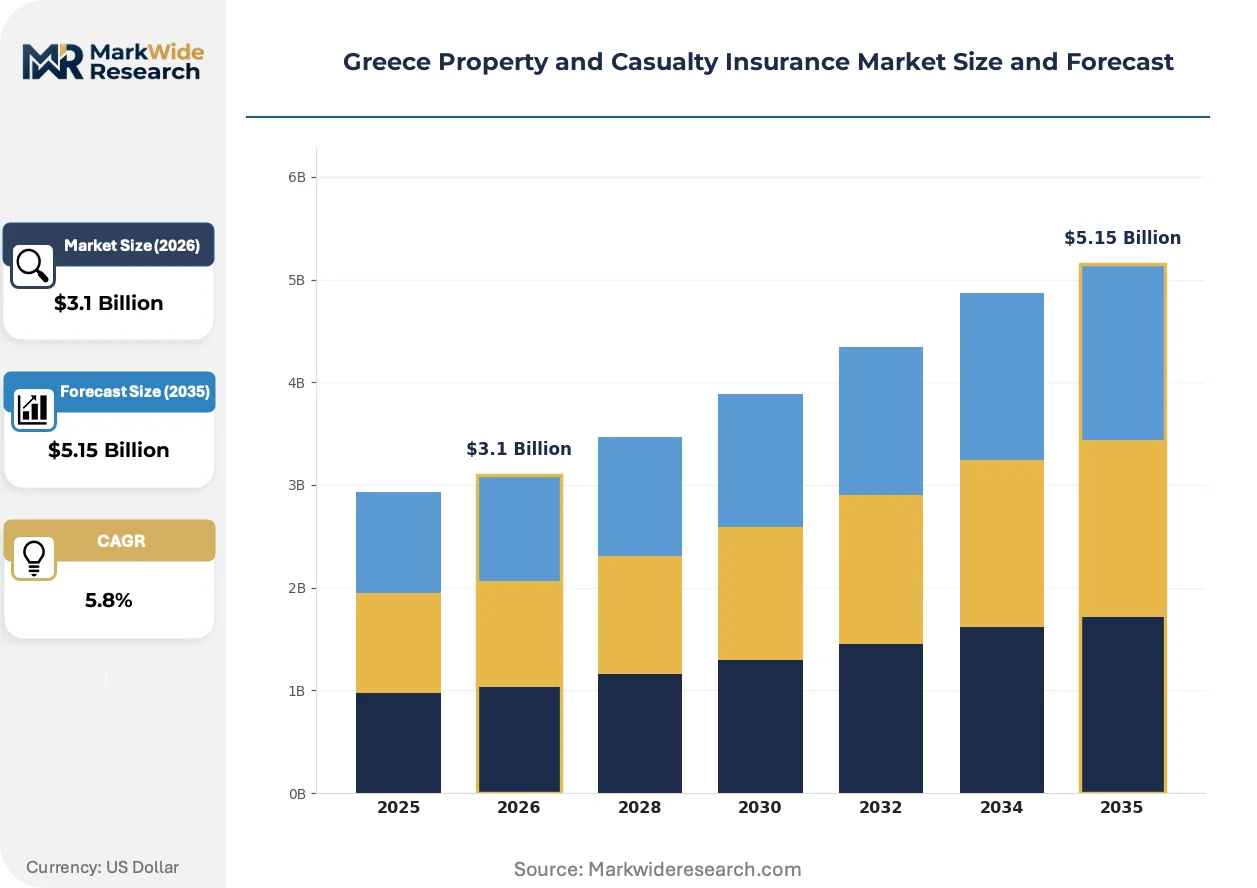
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Homeowners, Renters, Auto, Commercial Coverage Level: Comprehensive, Third-Party, Liability, Limited Distribution Channel: Online, Agents, Brokers, Direct Sales Customer Type: Individuals, Small Businesses, Corporations, Non-Profits |
| Companies Covered | Allianz Hellas Insurance Company SA, ERGO Insurance Company SA, Ethniki Hellenic General Insurance Co SA, AXA Insurance SA, European Reliance General Insurance Co SA, Generali Hellas Insurance Company SA, Groupama Phoenix Hellenic Insurance SA, Eurobank Insurance, Intersalonika Genikon Asfaliseon Anonimi Etairia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Property and Casualty Insurance Market Trends and Innovations
Digital claims settlement infrastructure is compressing customer retention cycles while regulatory climate disclosure mandates are rewiring investment portfolio construction across the Greek carrier base.
Telematics-enabled motor underwriting is decomposing traditional demographic risk segmentation into real-time behavioral pricing. Fleet operators in Thessaloniki and Patras are adopting connected vehicle platforms at accelerating velocity. This granularity is compressing cross-subsidization between safe and risky drivers, threatening volume-dependent incumbents.
EIOPA's sustainable finance disclosure requirements are forcing Greek insurers to reweight sovereign bond holdings toward green-labeled issues. The Bank of Greece's supervisory guidance on climate scenario testing is elevating capital charges for carbon-intensive real estate collateral. Commercial property underwriters are responding by demanding energy performance certificates before quoting coverage in Attica's office submarket.
Broker commissions face compression as direct digital platforms capture standardized homeowners and auto renewals. Younger demographics in Athens and Piraeus are completing purchase journeys entirely through mobile-optimized interfaces, bypassing traditional advisory relationships. This channel rotation is most visible in the renters insurance segment, where price transparency tools have collapsed information asymmetries.
Greece Property and Casualty Insurance Market Segmentation
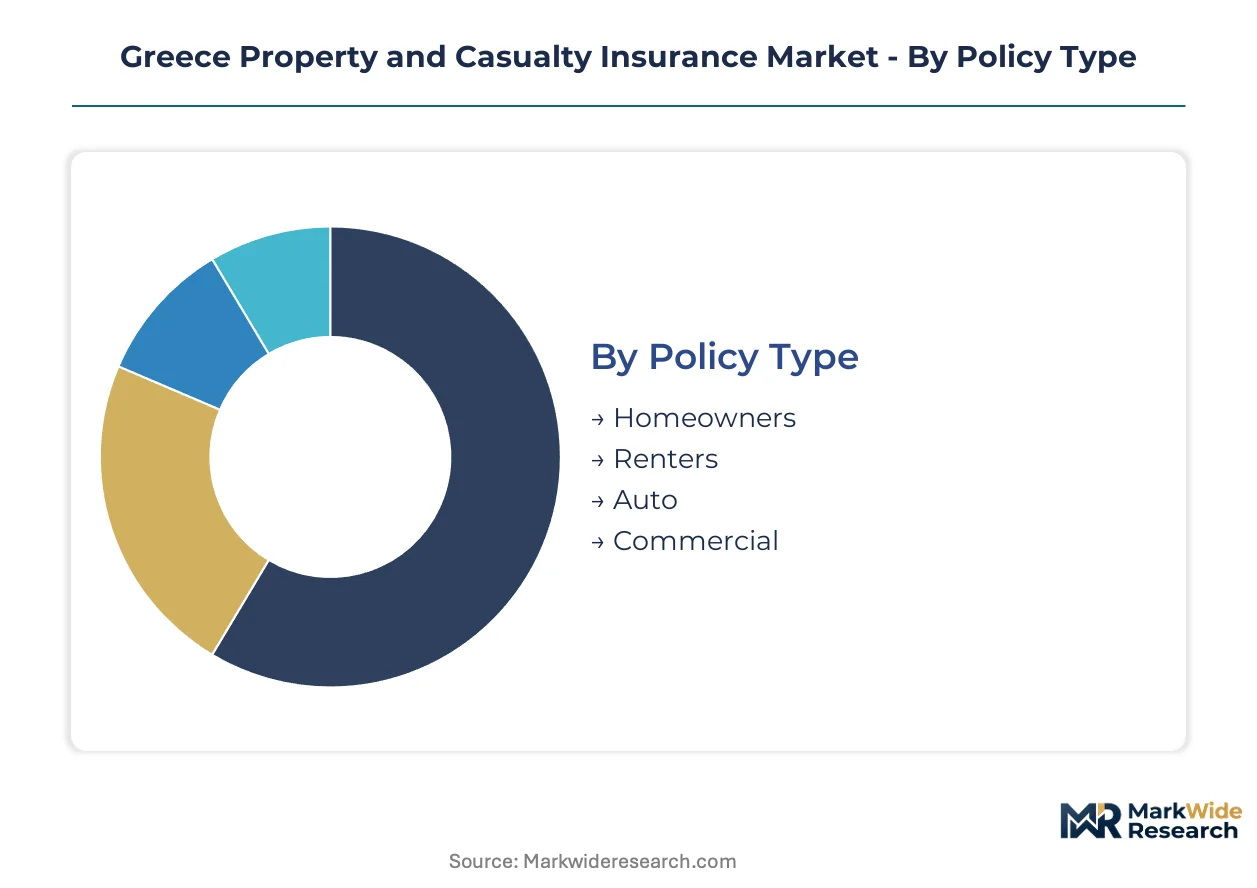
Segmentation in Greek property and casualty insurance reveals how risk transfer instruments align with distinct buyer capabilities, distribution access, and regulatory obligations. Understanding these divisions exposes where capital efficiency concentrates and where underwriting margins face compression.
Policy Type:
Domestic consumption patterns dominate all four policy categories, with auto and homeowners lines anchored in mandatory coverage requirements and commercial expansion driven by tourism sector formalization.
- Homeowners:Multi-peril contracts covering fire, earthquake, and theft exposure for residential properties. Demand clusters in Attica's apartment stock and Cyclades vacation homes where bank lending mandates coverage. Regulatory earthquake reserves elevate pricing in coastal seismic zones.
- Auto:Third-party liability constitutes the legal minimum tied to national vehicle registration, while comprehensive coverage expands among fleet operators adopting telematics platforms. Thessaloniki and Patras vehicle density sustains premium volume leadership.
- Commercial:Property and liability bundles serving hospitality, shipping, and retail operations. Crete and Rhodes hotel operators drive uptake as EU recovery fund disbursements require formal risk transfer documentation.
- Renters:Contents and liability protection for leasehold occupants. Younger demographics in Athens and Piraeus favor digital purchase paths for standardized low-limit contracts.
Auto holds the largest share; momentum sits with Commercial as tourism SMEs formalize coverage.
Coverage Level:
Cost tier stratification separates price-sensitive mandatory purchasers from premium buyers seeking asset protection and business continuity guarantees.
- Comprehensive:All-risk contracts covering named perils plus operational interruption. Commercial property holders in Attica's office submarket select this tier to satisfy energy performance certificate requirements now embedded in underwriting criteria.
- Third-Party:Minimum legal coverage for auto liability and basic property damage. Mandatory motor obligations sustain volume despite thin margins compressing carrier profitability.
- Liability:Professional indemnity and general liability protection against third-party claims. Shipping operators in Piraeus and logistics corridors purchase elevated limits to match contractual counterparty requirements.
- Limited:Named-peril contracts with restricted scope and lower premiums. Agricultural cooperatives in Messenia select this tier for equipment coverage amid budget constraints.
Third-Party generates the highest transaction volume; Comprehensive is climbing the fastest as EIOPA climate disclosure requirements reshape product architecture.
Distribution Channel:
Customer type and transaction complexity determine channel selection, with advisory needs sustaining intermediary relevance despite digital encroachment on standardized products.
- Brokers:Independent intermediaries structuring complex commercial placements and negotiating reinsurance terms. Tourism sector expansion in island economies depends on broker networks penetrating secondary cities beyond Athens.
- Agents:Tied representatives of single carriers distributing homeowners and auto policies. Branch network fixed costs at Ethniki Hellenic create operational drag that direct competitors bypass.
- Online:Direct-to-consumer platforms capturing standardized renewals through mobile-optimized interfaces. Piraeus and Athens younger demographics complete entire purchase journeys without advisory contact.
- Direct Sales:Carrier-employed teams targeting corporate accounts and affinity group schemes. Eurobank and Piraeus Bank digital platforms enable embedded white-label attachment at loan origination.
Brokers command commercial placement share; Online is gaining share fastest as price transparency tools collapse information asymmetries in personal lines.
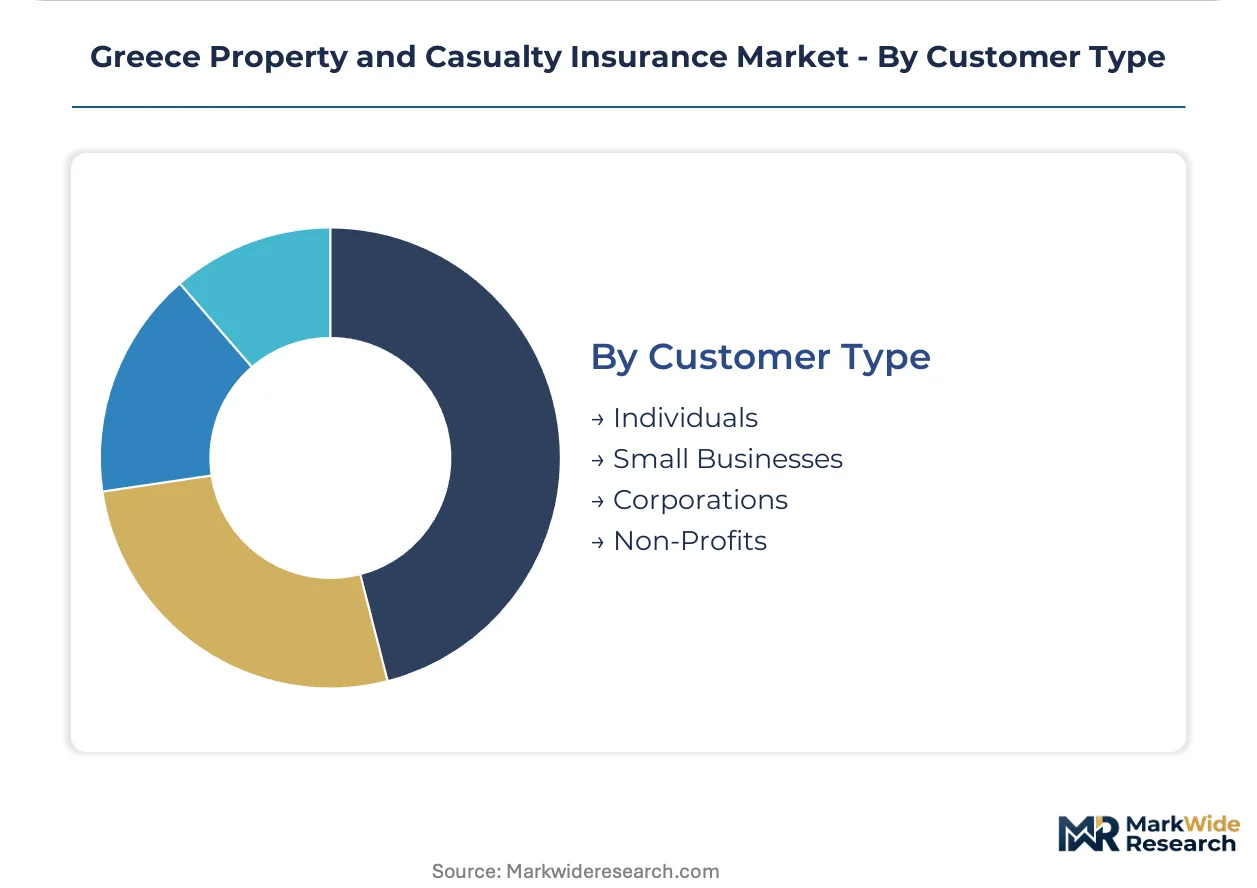
Customer Type:
Organizational scale and risk sophistication segment buyers into distinct service tiers with diverging margin profiles and retention economics.
- Corporations:Large enterprises with dedicated risk management functions purchasing tailored coverage and captive fronting arrangements. Shipping conglomerates in the Attica corridor negotiate global program structures with multinational reinsurance backing.
- Small Businesses:SMEs formalizing coverage to meet bank lending and EU fund compliance requirements. Cyclades and Crete hospitality operators drive fastest expansion as tourism receipts recover.
- Individuals:Household purchasers of homeowners, auto, and renters protection. Attica motor fleet density and apartment concentration sustain premium volume leadership.
- Non-Profits:Cultural institutions and social enterprises with constrained budgets seeking liability and property coverage. Museum and archaeological site operators face distinctive valuation challenges for irreplaceable assets.
Individuals constitute the largest customer base; Small Businesses show steepest expansion trajectory as regulatory formalization accelerates across tourism-dependent regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greece's property and casualty insurance sector generates modest cross-border premium flows, with domestic carriers ceding catastrophe exposure to international reinsurance markets while attracting EU-based capacity for commercial lines. The Attica region dominates underwriting volume, though regional dispersion patterns reveal distinct risk profiles across the country's geographic extremities.
Attica
Athens anchors the national insurance infrastructure, hosting the headquarters of Allianz Hellas, Ethniki Hellenic, and European Reliance. Motor fleet density in the capital sustains premium volume leadership, while commercial property exposure concentrates in Piraeus port logistics corridors. The Bank of Greece's Solvency II supervisory unit operates from Athens, conducting stress tests on domestic earthquake reserves.
Crete
Tourism SME formalization drives accelerating commercial property coverage purchases across Heraklion and Chania hospitality clusters. EU recovery fund disbursement requirements mandate documented risk transfer, pushing small hotel operators toward comprehensive bundles. Local broker networks penetrate secondary cities where carrier branch presence remains thin.
Cyclades
Island economies exhibit distinctive underwriting challenges, with Mykonos and Santorini vacation home construction elevating insured values against seismic and wildfire perils. Bank lending mandates sustain homeowners policy attachment rates among foreign-owned properties. Reinsurance cost escalation for earthquake exposure compresses domestic carrier margins in this high-hazard zone.
Thessaly
Agricultural cooperative formations in Larissa and Volos present latent demand for crop and equipment coverage with minimal incumbent saturation. Solvency II stress-testing requirements for flood exposure in coastal Thessaly lock capital that could deploy into growth segments. Parametric catastrophe products bypass traditional claims adjustment friction for commercial grain storage facilities.
Peloponnese
Messenia and Laconia olive oil processing cooperatives seek equipment breakdown and business interruption protection as operations scale. Limited branch network penetration by established carriers creates white-space opportunity for digital distribution platforms. Telematics-enabled commercial auto coverage gains traction among Patras-based fleet operators serving cross-peninsular logistics routes.
Greece Property and Casualty Insurance Market Competitive Landscape
Listed leaders compete with private specialists across capital adequacy and distribution reach. The Greek property and casualty insurance sector exhibits moderate consolidation, with multinational-backed carriers holding superior reinsurance access against domestic players reliant on regional broker networks. Three archetypes dominate: EU-headquartered giants leveraging group reinsurance pools, Hellenic incumbents anchored by extensive branch infrastructure, and niche specialists targeting shipping and logistics corridors. Competitive intensity manifests through embedded banking partnerships and parametric product innovation rather than price warfare.
Among multinational-backed carriers, Allianz Hellas Insurance Company SA and AXA Insurance SA exemplify the scale-driven archetype, occupying positions sustained by diversified catastrophe reinsurance backing. Ethniki Hellenic General Insurance Co SA anchors the domestic incumbent tier, its extensive island branch network representing traditional distribution density that digital competitors bypass. European Reliance General Insurance Co SA sits within the specialization vector, exemplifying targeted commercial line focus on maritime and logistics risk transfer where technical pricing expertise creates defensive positioning.
| Leading Market Players |
|---|
| Allianz Hellas Insurance Company SA |
| ERGO Insurance Company SA |
| Ethniki Hellenic General Insurance Co SA |
| AXA Insurance SA |
| European Reliance General Insurance Co SA |
| Generali Hellas Insurance Company SA |
| Groupama Phoenix Hellenic Insurance SA |
| Eurobank Insurance |
| Intersalonika Genikon Asfaliseon Anonimi Etairia |
| Others |
Pricing and Supply Chain Analysis
Reinsurance treaty renewals replacing traditional proportional arrangements are redistributing risk-bearing capacity toward London and Zurich while compressing domestic carrier margins through collateralized cost escalation. This substitution simultaneously concentrates supply geography in EU financial centers and intensifies pricing pressure on Greek underwriters lacking diversified retrocession access.
Pricing Analysis
Small business buyers anchor premium stratification across comprehensive, third-party, liability, and limited tiers. Price differentiation hinges on catastrophe exposure grading and Solvency II capital charge tiering, with coastal seismic zones commanding elevated reserves. Cost compression in commercial lines is intensifying because global climate loss ratios deteriorate reinsurance affordability. Price sensitivity concentrates among agricultural cooperatives selecting limited coverage, while shipping conglomerates in Piraeus demonstrate lowest elasticity due to contractual counterparty mandates.
Supply Chain Analysis
Germany, France, and the United Kingdom anchor reinsurance capacity provision for Greek catastrophe exposure. Risk transfer draws from international retrocession pools, satellite-based parametric triggers, and domestic broker placement networks. Single-source vulnerability concentrates in earthquake bond issuance windows during Q1 treaty renewals. Distribution runs through independent broker advisory channels for commercial placements and direct digital platforms for standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded banking API ecosystems are transforming distribution economics, with Eurobank and Piraeus Bank white-label integrations creating interoperability lock-in that rewards first-mover platform consolidation.
For Market Incumbents: Secure reinsurance treaty diversification across London and Zurich markets before Q1 renewal windows compress further. Consolidate branch network digitization in island economies where legacy fixed costs face direct platform competition. Solvency II capital adequacy pressure demands selective geographic retrenchment from overexposed coastal seismic zones.
For New Entrants and Emerging Players: Lead with parametric catastrophe products targeting Thessaly agricultural cooperatives and Peloponnese equipment coverage gaps. Underpenetrated Messenia and Laconia present white-space demand with minimal Ethniki Hellenic branch saturation. Go-to-market execution favors embedded distribution partnerships with digital banking platforms at loan origination moments.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors carriers with diversified reinsurance backing and API-native infrastructure. Long-term viability across the next decade hinges on climate risk modeling capabilities and sustainable asset allocation compliance. Acquisition targets should demonstrate telematics integration depth or parametric product development pipelines. Monitor EIOPA climate disclosure enforcement stringency as the critical inflection signal for portfolio reweighting timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Satellite-triggered payouts bypass claims adjustment friction for commercial property holders in high-hazard zones. |
| Embedded Banking Partnership | White-label insurance attachment at Eurobank and Piraeus Bank loan origination captures formalizing SME demand. |
| Telematics Platform Integration | Real-time behavioral pricing attracts younger policyholders in Attica while compressing cross-subsidization. |
| Reinsurance Treaty Diversification | London and Zurich capacity access reduces collateralized cost exposure from deteriorating climate loss ratios. |
| Climate Risk Modeling Investment | EIOPA disclosure compliance and Bank of Greece stress-testing elevate capital efficiency for prepared carriers. |
Research Methodology
A spread of perspectives from underwriting executives, reinsurance brokers, Bank of Greece supervisory staff, and tourism sector risk managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against regulatory filings, EIOPA guidance documents, and EU recovery fund disbursement records. Bottom-up premium volume estimates triangulated against top-down macroeconomic exposure assessments.
Segmentation dimensions modeled span policy type, coverage level, distribution channel, customer type, and regional hazard cluster across the projection horizon. CAGRs derived from trend extrapolation of formalization rates in tourism SMEs and telematics adoption velocity in commercial fleets. Forecast inputs incorporated Solvency II capital requirement trajectories and reinsurance market cycle positioning.
Forecasts assume regulatory continuity in EU Solvency II implementation and EIOPA climate disclosure regimes; material policy shifts would require re-modeling. Specific risks include catastrophic earthquake frequency exceeding modeled severities and abrupt reinsurance capacity withdrawal from climate-exposed zones. Recalibration cycles align with material shifts in global retrocession pricing and domestic SME formalization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
MENA Health and Medical Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
France Property and Casualty Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Europe Extended Warranty Market
Insurance
Insurance Big Data Analytics Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Family Floater Health Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Takaful Market
Insurance
Umbrella Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Event Insurance Market
Insurance
Germany Car Insurance Market