
 UAE Fintech Market | 2026-2036
UAE Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Fintech Market Analytics
Modular bundling of payments, lending, and treasury tools into single-platform suites is hardening as the dominant product configuration pattern across UAE fintech. Wio Bank leverages its cloud-native infrastructure to anchor digital banking services for SMEs seeking integrated cash management. Tabby competes through buy-now-pay-later specialization embedded directly at merchant checkout points. NymCard sustains its position by controlling card-issuing technology stacks that power multiple neobank brands across the Gulf.
UAE fintech encompasses technology-enabled financial services delivered through software platforms, API protocols, and mobile interfaces that automate payments, credit underwriting, wealth allocation, and compliance verification with sub-second transaction latency. These systems serve retail consumers, corporate treasuries, and financial institutions seeking operational efficiency and real-time data visibility. Payment processing dominates current transaction volumes across the Emirates, while investment platforms represent the fastest-expanding segment as robo-advisory assets under management climb. Artificial Intelligence applications in credit scoring and fraud detection command the deepest margin pools due to proprietary algorithm development and regulatory licensing barriers.
The UAE Central Bank governs licensing and operational standards for payment service providers and digital banks, while SAMA-aligned open banking rules shape API interoperability requirements across the financial sector. DFSA regulations in the Dubai International Financial Centre impose additional cybersecurity and customer protection standards that filter market access for foreign entrants. Stakeholders must monitor evolving stablecoin and digital asset frameworks as the Emirates advances its central bank digital currency roadmap.
Market Dynamics
Cloud-native core banking infrastructure is compressing time-to-market for new entrants while forcing incumbents into parallel modernization sprints. The UAE Central Bank's licensing velocity for digital banks accelerates this structural churn.
Growth Catalysts
- Open Banking Framework:The UAE Central Bank's API standardization mandates interoperability between traditional banks and fintech platforms, reducing integration friction for payment aggregators.
- SME Cash Management:Underbanked small and medium enterprises across Dubai and Abu Dhabi demand integrated treasury tools that combine payments, lending, and foreign exchange in single interfaces.
- Embedded Finance:Merchant checkout systems now incorporate buy-now-pay-later and working capital products directly at point-of-sale, removing friction from credit origination.
Market Restraints
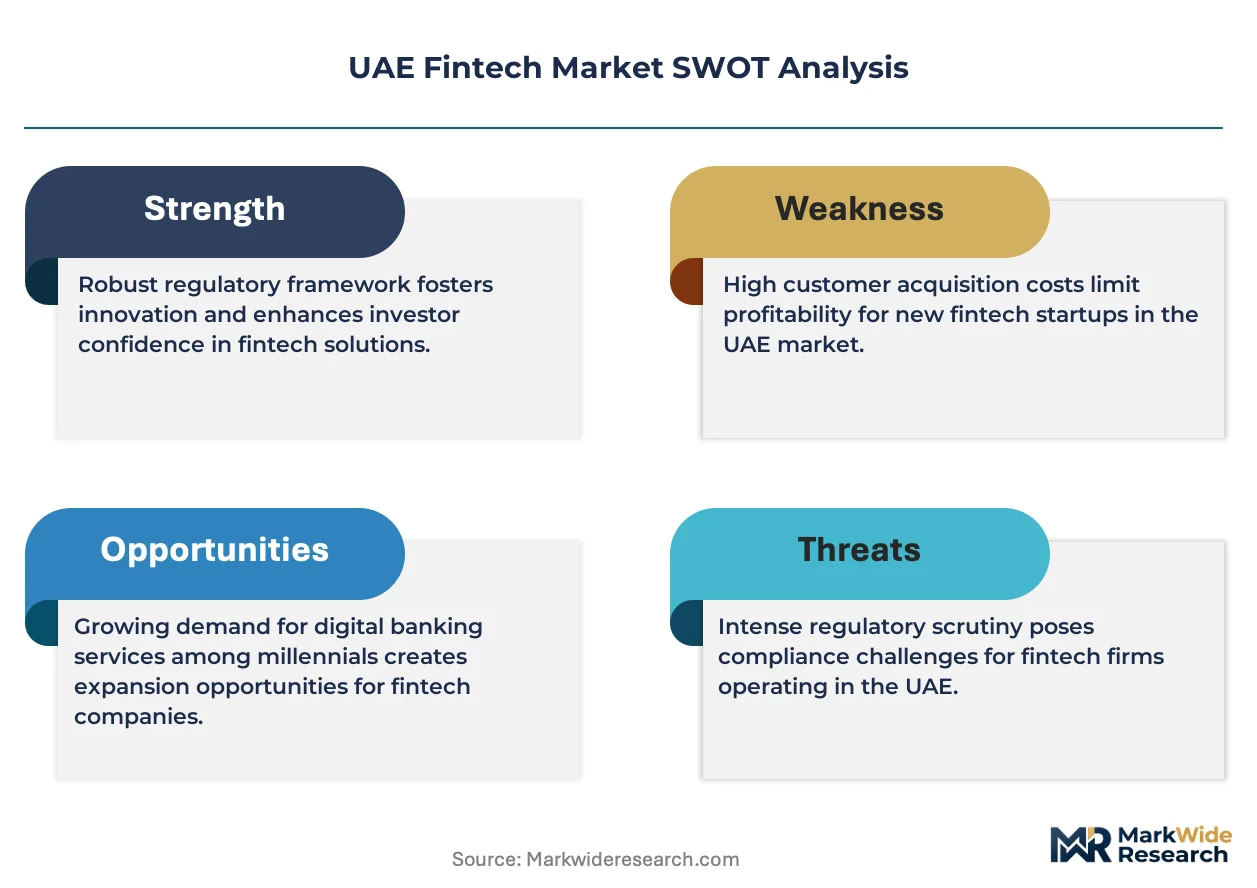
- Regulatory Fragmentation:DFSA rules in Dubai International Financial Centre impose cybersecurity standards that diverge from UAE Central Bank requirements, forcing dual compliance architectures.
- Core Banking Migration Costs:Legacy mainframe systems at incumbent institutions require multi-year transformation programs before API-layer connectivity becomes feasible.
- Qualified Engineering Talent:Scarcity of cloud infrastructure specialists and regulatory compliance architects in the Emirates inflates compensation and extends hiring cycles.
Strategic Opportunities
- Ras Al Khaimah and Northern Emirates:Lower operational costs and emerging free zone incentives attract fintech back-office operations and secondary licensing hubs outside Dubai-Abu Dhabi concentration.
- Islamic Finance Integration:Sharia-compliant robo-advisory and takaful-enabled embedded insurance products address underserved segments with differentiated compliance architecture.
- Cross-Border Remittance APIs:Corridor-specific payment rails connecting UAE to South Asia and East Africa leverage real-time settlement protocols for diaspora worker segments.
Industry Challenges
- Data Sovereignty Compliance:Local storage mandates for financial transaction records complicate multi-cloud deployment strategies and increase infrastructure redundancy costs.
- Third-Party Risk Management:Concentrated reliance on card scheme networks and cloud hyperscalers creates systemic vulnerability points requiring enhanced due diligence frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Fintech Market |
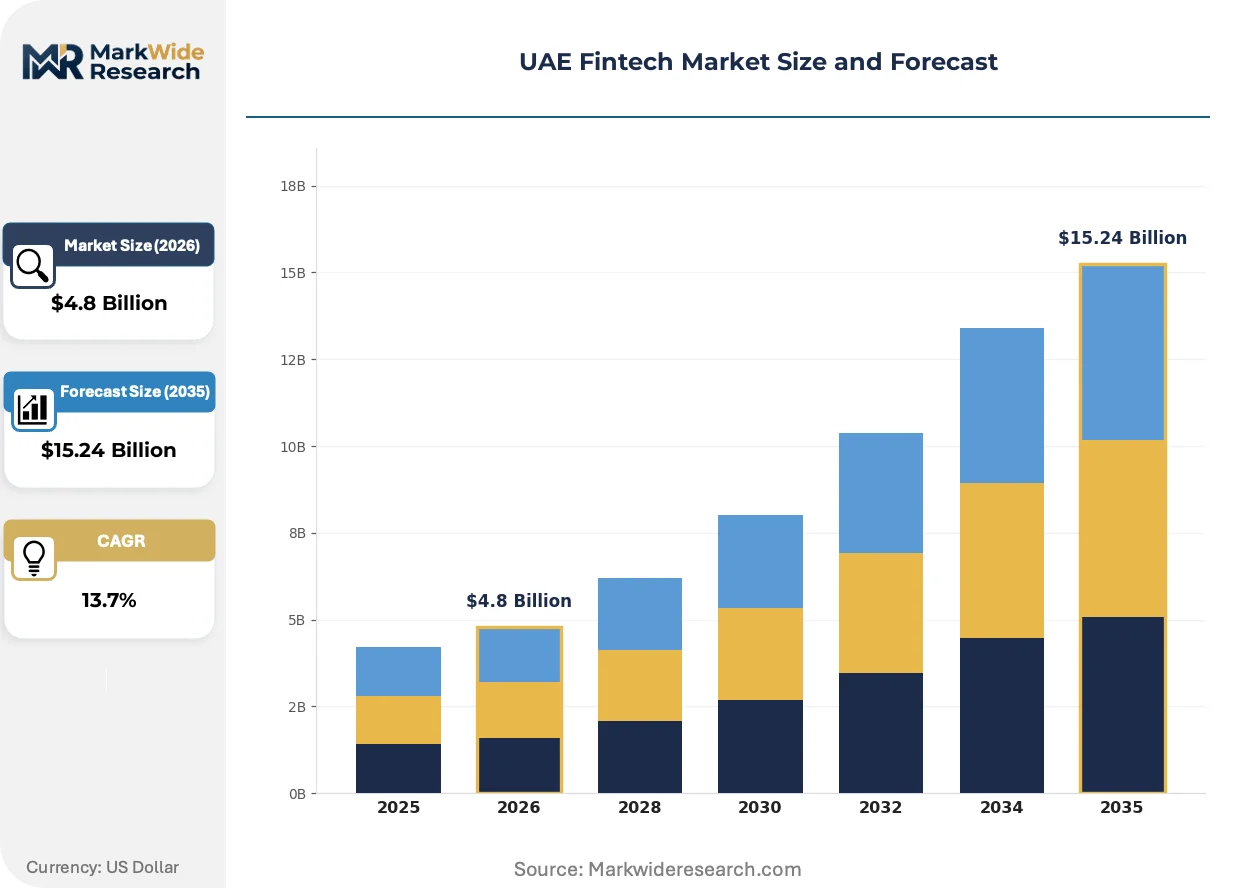
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Digital Banking, Investment Platforms, Wealth Management Customer Type: Retail Consumers, SMEs, Corporates, Financial Institutions Technology: Blockchain, Artificial Intelligence, Machine Learning, API Integration Delivery Model: Mobile App, Web-Based Platform, SaaS, P2P |
| Companies Covered | Wio Bank, NymCard, Tabby, Comfi, NOW Money, PayTabs, YAP, Daleel, Sarwa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Fintech Market Evolving Landscape
Artificial intelligence is compressing decision latency across credit underwriting and fraud detection while regulators race to frame algorithmic accountability standards. These shifts are restructuring competitive moats around proprietary data assets rather than distribution scale.
Banking-as-a-Service middleware is modularizing product assembly for neobanks and non-financial brands seeking embedded financial capabilities. Retail conglomerates and logistics platforms in the Emirates adopt these stacks to launch branded payment and lending products within quarters rather than years. The technology is modularizing vendor relationships, allowing buyers to swap individual components rather than replacing entire core systems.
The UAE Central Bank's stablecoin and central bank digital currency roadmap is forcing payment service providers to architect dual-compatible settlement infrastructure. Licensed entities must demonstrate technical readiness for dirham-denominated digital currency circulation while maintaining fiat rails. Digital wallet operators and remittance platforms face the steepest compliance adaptation curves under this evolving framework.
Merchant procurement of financial services is fragmenting across specialized providers rather than consolidating through universal banking relationships. Small retailers in Dubai's commercial districts now source payment acceptance from one vendor, working capital from another, and foreign exchange hedging from a third. This unbundling is most visible among food service and trading sector SMEs seeking best-in-class terms for each function.
UAE Fintech Market Segmentation
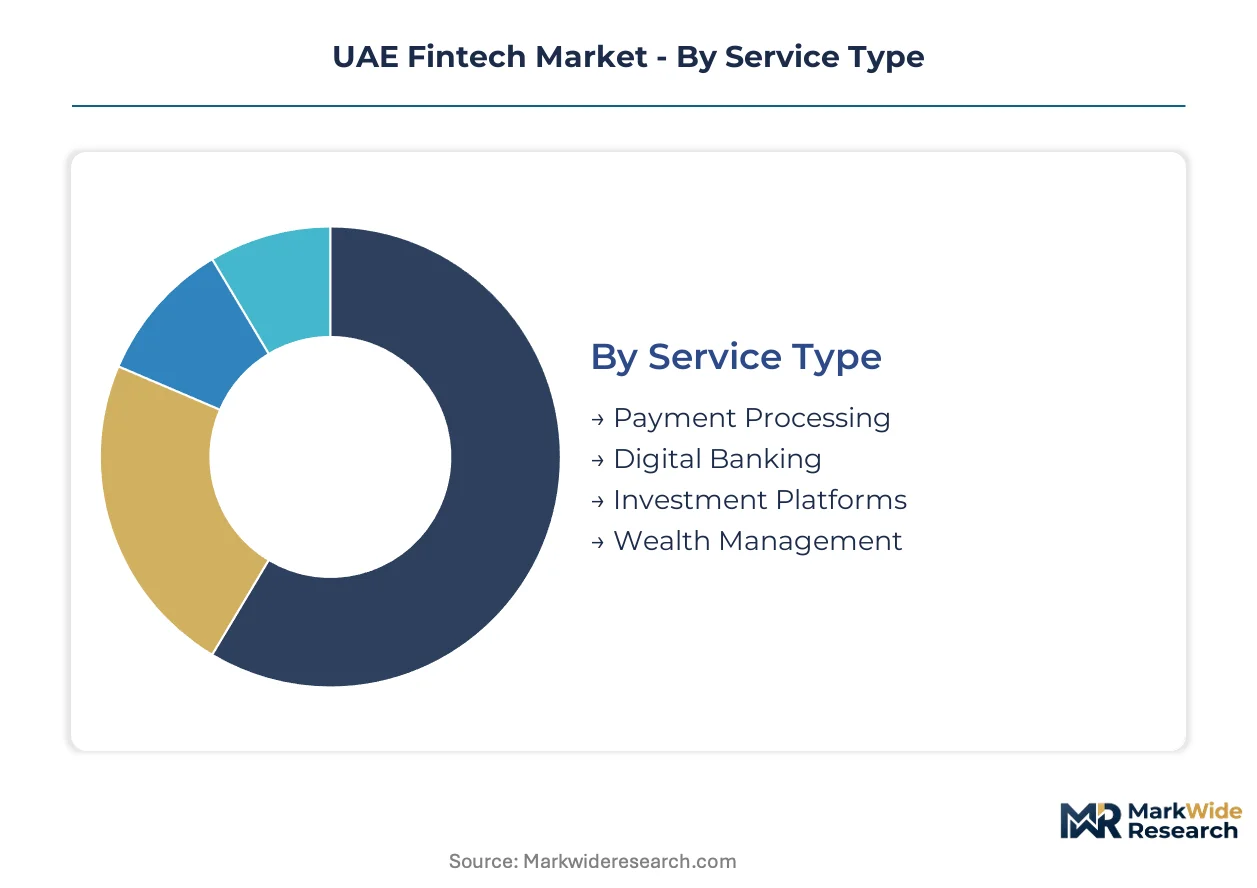
Segmentation in the UAE fintech market reveals divergent capital requirements and margin structures across service layers. Each dimension carries distinct regulatory burdens and technology investment profiles that shape competitive entry strategies.
Service Type:
Capital intensity varies sharply across service types, with infrastructure-heavy segments demanding multi-year licensing and technology buildouts before revenue generation begins.
- Payment Processing:Real-time transaction routing systems require PCI-DSS compliance architecture and direct central bank settlement access. Dubai and Abu Dhabi retail merchants drive volume concentration as mobile wallet adoption accelerates checkout digitization.
- Digital Banking:Cloud-native core banking platforms demand the steepest upfront investment due to UAE Central Bank licensing fees and minimum capital requirements. SME cash management needs in the Emirates are concentrating demand for integrated treasury and lending interfaces.
- Investment Platforms:Robo-advisory engines with SCA registration requirements serve retail wealth accumulation in the Emirates.
- Wealth Management:Hybrid advisory models blending algorithmic allocation with human oversight target high-net-worth segments in Dubai.
Payment Processing absorbs the bulk of installed capacity; Digital Banking is expanding most quickly.
Customer Type:
Customer archetypes determine pricing power and retention economics, with enterprise segments commanding annual contract values that dwarf per-transaction retail yields.
- Retail Consumers:Mass-market users with low switching costs and high price sensitivity dominate transaction volumes across UAE digital wallets.
- SMEs:Underbanked small enterprises across Ras Al Khaimah and Sharjah seek bundled payments, lending, and foreign exchange tools in single platforms.
- Corporates:Treasury departments at Emirates-based multinationals demand API-native cash visibility and multi-currency hedging capabilities.
- Financial Institutions:Banks and neobanks licensing Banking-as-a-Service middleware represent the highest-margin customer segment with multi-year contract structures.
SMEs generate the densest transaction flow per capita; Financial Institutions deliver the steepest margin expansion.
Technology:
Technology stack selection dictates regulatory scrutiny depth and engineering talent acquisition costs across the Emirates.
- Blockchain:Distributed ledger infrastructure for trade finance and cross-border settlement requires sandbox licensing through the UAE Central Bank's regulatory laboratory.
- Artificial Intelligence:Proprietary credit scoring and fraud detection algorithms command premium licensing fees from UAE financial institutions seeking sub-second decision latency.
- Machine Learning:Pattern recognition systems for transaction monitoring and AML compliance serve mid-tier payment processors in Dubai.
- API Integration:Open banking middleware connecting traditional banks to fintech platforms benefits from UAE Central Bank interoperability mandates.
Artificial Intelligence captures the deepest R&D investment; API Integration is climbing the fastest as open banking deadlines approach.
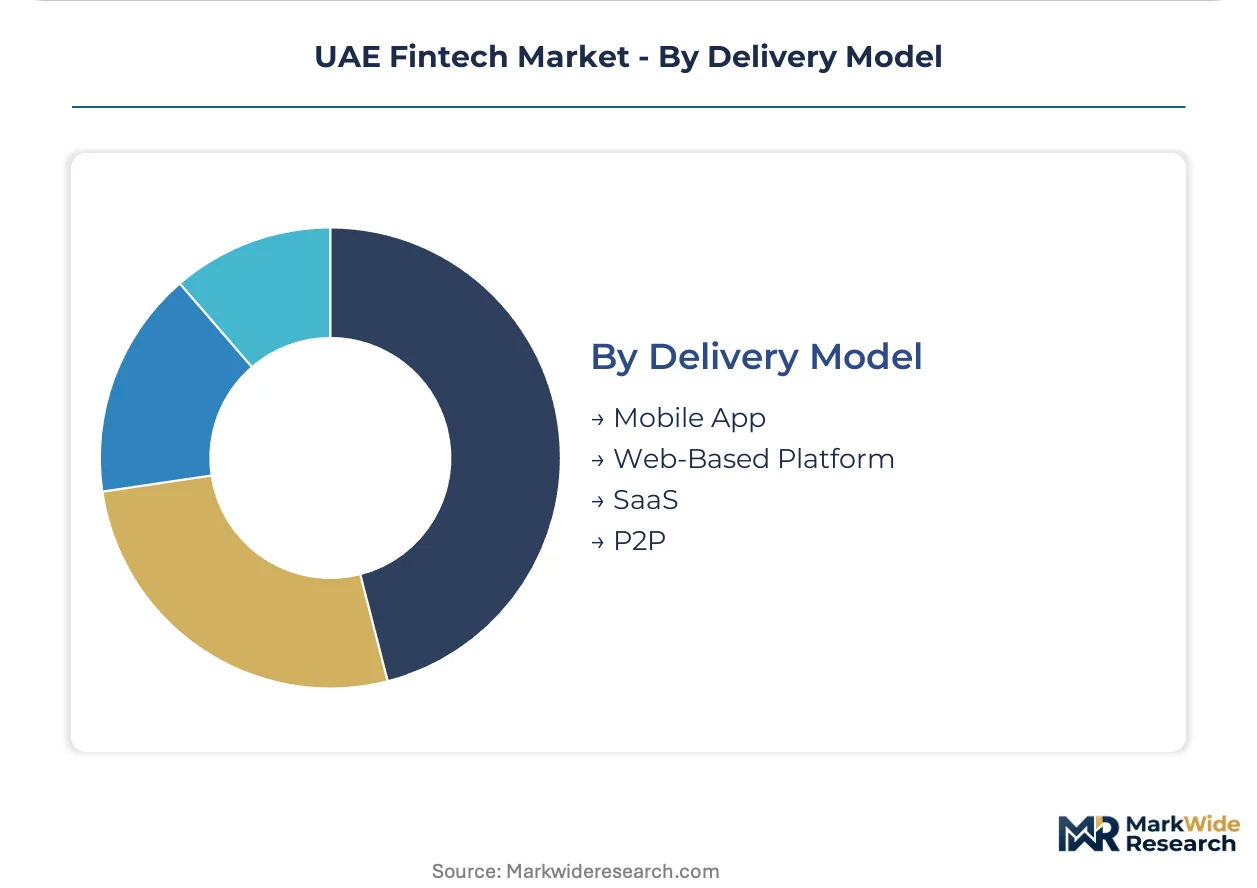
Delivery Model:
Delivery architecture determines customer acquisition economics and operational scalability across Emirates population centers.
- Mobile App:Native iOS and Android applications dominate retail consumer engagement in Dubai and Abu Dhabi with biometric authentication integration.
- Web-Based Platform:Browser-accessible dashboards serve corporate treasury users requiring multi-screen workflow management.
- SaaS:White-label infrastructure licensed to non-financial brands enables rapid embedded finance deployment across UAE retail conglomerates.
- P2P:Direct person-to-person transfer protocols leverage real-time settlement rails for diaspora remittance corridors.
Mobile App commands the largest user base; SaaS is gaining share fastest as non-bank brands enter financial services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Financial Centre's zero-tax framework and 100% foreign ownership provisions concentrate fintech headquarters and licensing activity. Abu Dhabi Global Market competes through its digital banking sandbox and regulatory laboratory. Sharjah and the Northern Emirates attract back-office operations through lower operational costs.
Dubai
Mobile wallet penetration among retail consumers drives payment processing volume concentration. The Dubai Financial Services Authority imposes cybersecurity standards that filter market access for foreign entrants. DIFC Gate Avenue clusters neobank headquarters and Banking-as-a-Service middleware providers seeking proximity to institutional capital.
Abu Dhabi
SME treasury automation and integrated cash management tools attract venture deployment. Abu Dhabi Global Market's digital banking sandbox accelerates licensing velocity for cloud-native entrants. Al Maryah Island hosts investment platform operators and robo-advisory engines targeting high-net-worth segments.
Sharjah
Lower commercial real estate costs draw fintech back-office operations from Dubai-anchored competitors. The UAE Central Bank's nationwide open banking mandates apply uniformly across the emirate. Sharjah Research Technology and Innovation Park emerging as secondary hub for API development and compliance architecture teams.
Ras Al Khaimah
Free zone incentives targeting blockchain and distributed ledger infrastructure attract sandbox-licensed entities. Ras Al Khaimah Economic Zone offers streamlined licensing for payment service providers. The emirate's industrial zones host cross-border remittance platforms serving South Asian corridor demand.
Northern Emirates
Fujairah and Ajman capture operational spillover from saturated Dubai-Abu Dhabi corridors. Local storage mandates for financial transaction records complicate multi-cloud deployment across these jurisdictions. Emerging logistics and trading SME segments generate demand for embedded working capital products.
UAE Fintech Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the UAE fintech landscape. Cloud-native digital banks and payment processors fragment share among vertical-specific entrants. Three archetypes dominate: licensed digital banks with full-stack infrastructure, embedded finance specialists integrating at merchant checkout, and Banking-as-a-Service middleware providers licensing technology stacks. Competitive moves concentrate on API-layer partnerships and regulatory sandbox positioning ahead of central bank digital currency readiness deadlines.
Within the licensed digital bank tier, Wio Bank exemplifies cloud-native infrastructure deployment for SME cash management. NymCard occupies a position controlling card-issuing technology stacks that power multiple regional neobank brands. Tabby represents the embedded finance archetype through buy-now-pay-later specialization at merchant checkout points.
| Leading Market Players |
|---|
| Wio Bank |
| NymCard |
| Tabby |
| Comfi |
| NOW Money |
| PayTabs |
| YAP |
| Daleel |
| Sarwa |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure specialists concentrated in Dubai and Abu Dhabi command compensation premiums that compress margins for digital banking entrants, widening pricing spreads between premium API-native suites and economy-tier white-label configurations.
Pricing Analysis
Short lead-time deployment premiums apply to cloud-native core banking stacks promising sub-quarter market entry, while spot inventory discounts emerge for modular card-issuing components with standard PCI-DSS certification. SaaS-tiered subscription models dominate, with price differentiation anchored in UAE Central Bank licensing tier and API throughput scale. Pricing pressure stems from hyperscaler compute cost inflation eroding middleware margins. Retail consumers exhibit highest price sensitivity; financial institutions licensing full-stack infrastructure show lowest elasticity.
Supply Chain Analysis
UAE Central Bank sandbox qualification gates access to card scheme networks and real-time settlement rails, filtering vendor eligibility. Technology sourcing concentrates in the United States, India, and Singapore for cloud infrastructure, compliance software, and API middleware respectively. Raw material dependencies span hyperscaler compute capacity, encryption hardware modules, and biometric authentication sensors. Single-source vulnerability concentrates in card scheme network access. Distribution runs through direct enterprise sales teams for institutional clients and app marketplace placement for retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE fintech market operates as a cost-of-compliance story where UAE Central Bank digital banking licensing fees and minimum capital requirements erect barrier-to-entry moats favoring capitalized incumbents.
For Market Incumbents: To counter cloud-native neobank entrants, legacy institutions should accelerate core banking API-layer modernization and acquire UAE Central Bank sandbox positioning ahead of central bank digital currency deadlines. Priority levers include in-house production of proprietary credit scoring algorithms and captive supply of compliance architecture talent.
For New Entrants and Emerging Players: Enter via Ras Al Khaimah free zone incentives targeting blockchain infrastructure and cross-border remittance corridors with lower operational burn rates. The most penetrable segment sits among underbanked trading SMEs in Sharjah and Northern Emirates seeking embedded working capital at point-of-sale. Go-to-market should leverage Banking-as-a-Service middleware partnerships to compress time-to-revenue.
For Investors and Strategic Acquirers: Re-rating potential sits with card-issuing technology stack controllers given open banking API mandate acceleration and neobank brand proliferation across the Gulf. Long-term viability favors entities with dual-compatible settlement infrastructure for fiat and central bank digital currency rails. The signal to watch is UAE Central Bank stablecoin framework publication timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Layer Partnership Formation | UAE Central Bank interoperability mandates force rapid integration between traditional banks and fintech platforms. |
| Sandbox Licensing Positioning | Regulatory laboratory access accelerates time-to-market for cloud-native digital banking entrants. |
| Islamic Finance Product Development | Sharia-compliant robo-advisory and takaful-enabled insurance address underserved segments with differentiated architecture. |
| Cross-Border Remittance Corridor Buildout | South Asian and East African diaspora worker segments demand real-time settlement protocols. |
| Core Banking Modernization Program | Legacy mainframe transformation enables API connectivity for incumbent institutions facing neobank competition. |
Research Methodology
Document review covered UAE Central Bank regulatory filings, DFSA cybersecurity standards, and SCA investment platform registrations, complemented by interviews with digital bank CTOs, payment processor compliance officers, neobank product leads, and Banking-as-a-Service vendor sales directors. Secondary validation drew from SEC filings of regional fintech investors, hyperscaler capex disclosures, and open banking API specification documents. Bottom-up transaction volume modeling and top-down market sizing triangulated segment-level estimates.
Market value and volume outputs across the projection horizon reflect segmented modeling of service type, customer archetype, technology stack, and delivery model dimensions. CAGRs derive from trend extrapolation of mobile wallet adoption curves, SME digital banking penetration rates, and robo-advisory asset accumulation patterns. Industry-specific inputs include UAE Central Bank licensing velocity data and DFSA sandbox admission timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory framework delays or hyperscaler service disruptions. Model outputs reflect assumptions around open banking deadline adherence and central bank digital currency technical readiness demonstration. A model refresh is warranted upon material change in UAE Central Bank stablecoin issuance timeline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Fintech Crisis Management Market
FinTech
Netherlands AI in Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
Global Fundraising Software Market
FinTech
Digital Banking Platform Market
FinTech
Fintech Technologies Market
FinTech
France AI in Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Embedded Finance Market
FinTech
North America AI in Fintech Market
FinTech
France BNPL Market
FinTech
Fintech-As-A-Service Platform Market
FinTech
Global Saas Spend Management Software Market
FinTech
North America Fintech Market
FinTech
Asia-Pacific Fintech Market