
 Canada AI in Fintech Market | 2026-2036
Canada AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Canada AI in Fintech Market Insights
OSFI's Guideline B-13 on technology and cyber risk management is restructuring how Canadian financial institutions procure AI infrastructure, forcing vendors to embed audit-ready governance layers into core platforms. Wealthsimple leverages automated portfolio construction to sustain its direct-to-consumer wealth management position. RBC anchors enterprise-grade AI deployment through its Borealis AI research division. MasterCard Canada competes on real-time transaction intelligence across North American payment corridors.
Canada AI in Fintech encompasses the integration of machine learning, natural language processing, and predictive analytics into financial services workflows for automated decision-making, risk quantification, and customer interaction at scale. These systems process structured and unstructured data through neural architectures to generate credit scores, flag anomalous transactions, and execute conversational interfaces with sub-second latency requirements. Fraud detection applications dominate current deployment value as banks absorb escalating digital transaction volumes, while predictive analytics segments expand fastest among investment firms seeking alternative data alpha generation. Cloud-based deployment leads technology adoption as OSFI-compliant Canadian data residency frameworks mature, though hybrid architectures retain margin concentration among tier-one institutions with legacy mainframe dependencies.
Health Canada does not directly regulate this sector, but the Office of the Superintendent of Financial Institutions enforces technology risk capital reserves that shape AI procurement budgets across federally regulated banks. The Personal Information Protection and Electronic Documents Act constrains data training pipelines, forcing model developers to implement differential privacy and federated learning architectures. Provincial securities commissions in Ontario and Quebec layer additional algorithmic trading disclosure requirements onto fintech AI deployments. Stakeholders must monitor how forthcoming federal AI legislation intersects with existing financial services rulebooks to determine compliance architecture investments.
Market Dynamics
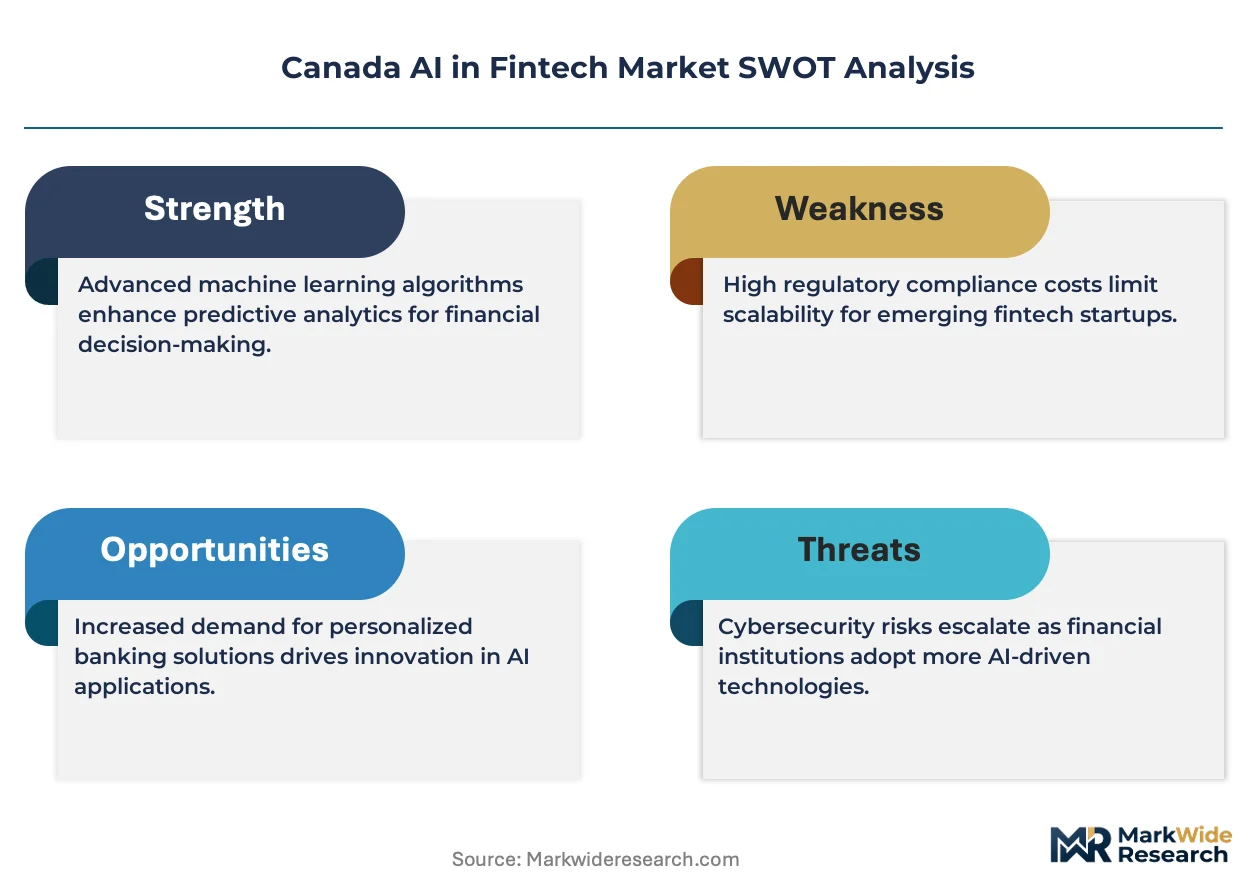
OSFI's Guideline B-13 is compressing AI procurement cycles across Canadian banking as institutions race to deploy audit-ready governance layers before compliance deadlines tighten. This regulatory pressure is restructuring vendor relationships and capital allocation priorities nationwide.
Growth Catalysts
- Regulatory Compliance Mandates:OSFI's technology risk capital reserve requirements force federally regulated banks to accelerate AI infrastructure investments. Compliance-driven procurement now dominates enterprise budgeting cycles.
- Payment Volume Surge:Digital transaction growth across Canadian retail and commercial banking generates exponential training data for fraud detection algorithms. Machine learning deployment scales with transaction throughput.
- Montreal AI Research Corridor:Concentrated academic-industry partnerships between McGill, Université de Montréal, and Mila produce specialized fintech talent pipelines. This geographic clustering reduces recruitment friction for model development teams.
Market Restraints
- Compute Cost Volatility:GPU and specialized AI accelerator pricing fluctuates with global semiconductor supply constraints. Canadian institutions face dollar-denominated procurement exposure against domestic currency budgets.
- Data Residency Requirements:OSFI-compliant cloud infrastructure concentrates among three domestic providers. Limited vendor choice restricts negotiation leverage and architectural flexibility for tier-two institutions.
- Explainability Limitations:Deep neural networks for credit scoring resist interpretability standards required under PIPEDA fairness provisions. Model developers sacrifice predictive accuracy for regulatory defensibility.
Strategic Opportunities
- Atlantic Canada Expansion:Halifax and St. John's emerging fintech clusters offer lower operational costs than Toronto. Provincial economic development incentives reduce facility and talent acquisition expenses.
- Open Banking Convergence:Consumer-directed finance frameworks enable AI-powered aggregation and advisory services. Data portability mandates create new training datasets for personalized financial products.
- Climate Risk Analytics:OSFI climate disclosure requirements drive demand for predictive models assessing loan portfolio physical and transition risks. Early movers capture advisory relationships with resource-dependent sectors.
Industry Challenges
- Specialized Talent Scarcity:Production-grade MLOps engineers with financial services domain knowledge command premium compensation. Retention pressure intensifies as US technology firms recruit from Canadian teams.
- Legacy Core Integration:Mainframe-dependent institutions face multi-year timelines to expose transaction data through API layers compatible with real-time AI inference. Hybrid architectures introduce latency and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada AI in Fintech Market |
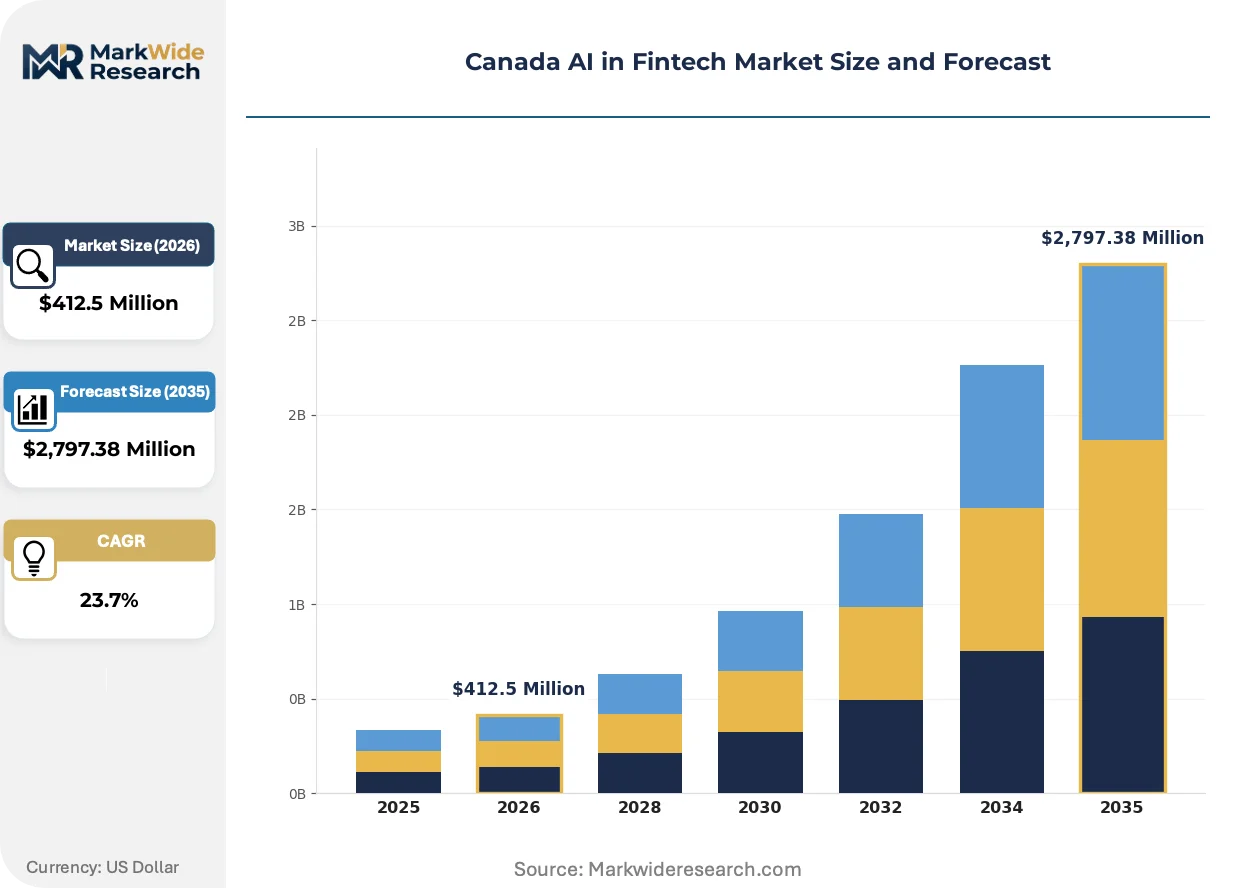
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $2,797.38 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Assessment, Customer Service, Credit Scoring Technology: Machine Learning, Natural Language Processing, Deep Learning, Predictive Analytics End User: Banking Institutions, Investment Firms, Payment Processors, Insurance Companies Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Chimoney, Finofo, FriedmannAI, Propra, Wealthsimple, RBC, Hubdoc, MasterCard Canada, Bitbuy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada AI in Fintech Market Trends and Innovations
Federated learning architectures are gaining traction as Canadian institutions seek to train models across distributed datasets without centralizing sensitive customer information. This technical shift responds directly to PIPEDA constraints and OSFI data governance expectations.
Edge computing deployment for real-time fraud detection is decentralizing transaction scoring from centralized cloud infrastructure to payment terminal and mobile device processors. Canadian payment networks adopt this architecture to reduce latency below 100 milliseconds for contactless transactions. The shift compresses infrastructure costs while improving customer experience at point-of-sale.
PIPEDA amendments and provincial privacy legislation in Quebec and British Columbia impose algorithmic impact assessment requirements on automated credit decisions. Financial institutions must document fairness testing and disparate outcome monitoring before deployment. Wealth management and consumer lending segments face the steepest compliance documentation burdens as they scale predictive underwriting.
Subscription-based AI tooling procurement is displacing perpetual license models among mid-market credit unions and regional banks. Vendors now price per API call or model inference rather than upfront enterprise agreements. This pattern concentrates in Ontario and Quebec where smaller institutions lack capital reserves for large technology commitments.
Canada AI in Fintech Market Segmentation
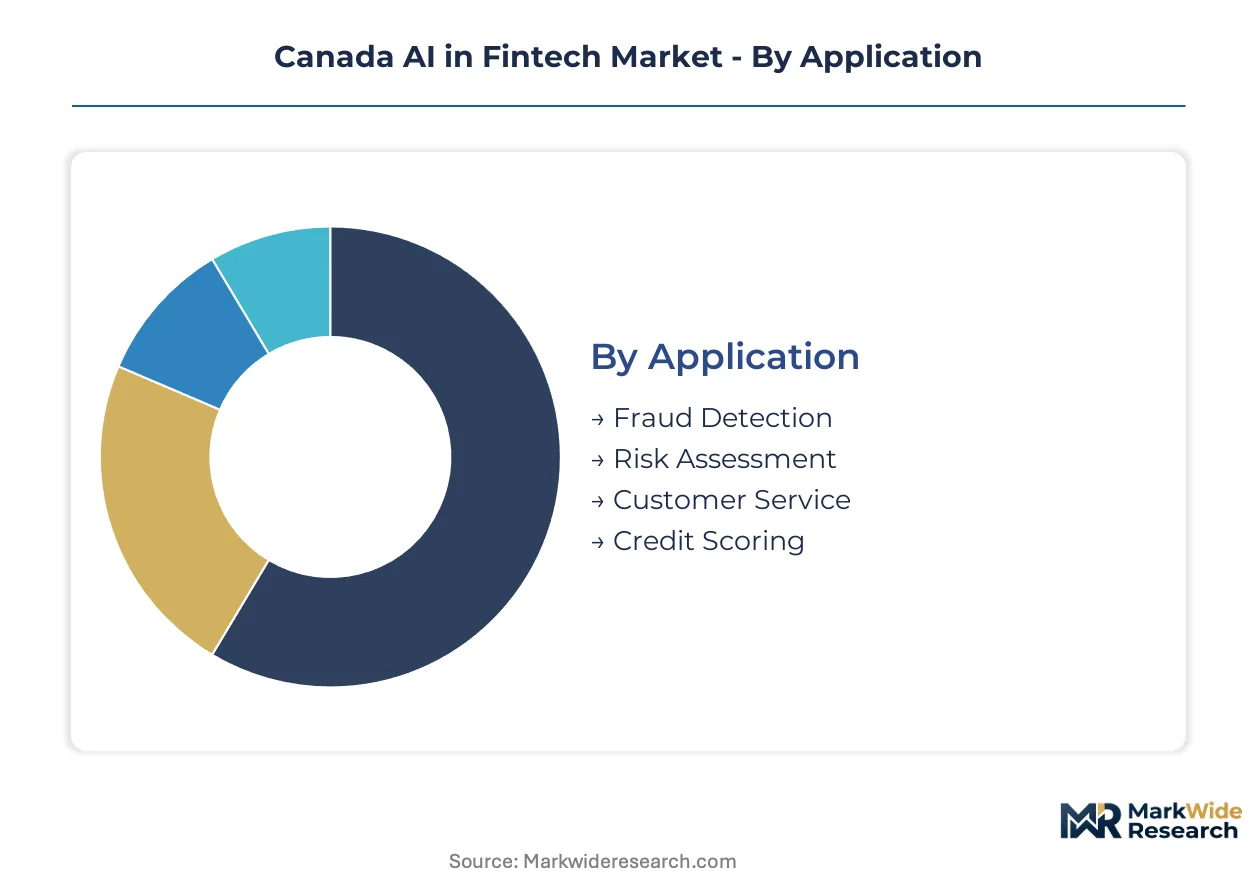
Segmentation reveals how Canadian financial institutions prioritize AI investments across compliance-driven applications, infrastructure architectures, and customer-facing workflows. Understanding these divisions exposes where OSFI regulatory pressure concentrates procurement budgets and which technology choices dominate institutional roadmaps.
Application:
Fraud detection buyers prioritize real-time inference latency and audit trail completeness, while risk assessment purchasers emphasize model interpretability for regulatory defensibility.
- Fraud Detection:Real-time transaction scoring systems process millions of daily events through ensemble machine learning architectures. Canadian banks deploy these tools across Toronto and Montreal payment corridors to meet OSFI technology risk capital requirements. Compliance-driven procurement dominates enterprise budgeting.
- Risk Assessment:Predictive models quantify credit, market, and operational exposures using alternative data streams and neural network architectures. Investment firms in Montreal's AI research corridor absorb these capabilities fastest for portfolio construction and stress testing.
- Customer Service:Conversational AI interfaces handle routine banking inquiries through natural language processing pipelines.
- Credit Scoring:Automated underwriting engines assess borrower risk using machine learning on structured and unstructured financial data.
Fraud detection leads volumes today; credit scoring is gaining share fastest as open banking frameworks expand training data availability.
Technology:
Technology selection hinges on data volume requirements, with high-throughput institutions favoring deep learning while explainability mandates push others toward interpretable machine learning approaches.
- Machine Learning:Supervised and unsupervised algorithms power fraud detection, credit scoring, and customer segmentation across Canadian banking. Random forests and gradient-boosted trees dominate where OSFI auditors demand model interpretability.
- Deep Learning:Multi-layer neural networks process unstructured data for document analysis and complex pattern recognition. Toronto-based institutions deploy these architectures for high-frequency trading signals and alternative data alpha generation.
- Natural Language Processing:Text and speech analysis engines extract sentiment and intent from customer communications and regulatory filings.
- Predictive Analytics:Time-series forecasting and statistical modeling support portfolio optimization and climate risk quantification.
Machine learning leads volumes today; deep learning is climbing the fastest as GPU infrastructure costs moderate.
End User:
End user differentiation centers on regulatory scrutiny intensity, with federally regulated banks facing stricter OSFI technology risk requirements than provincially supervised entities.
- Banking Institutions:Federally regulated banks anchor enterprise AI deployment through dedicated research divisions and captive infrastructure. RBC's Borealis AI and similar programs concentrate talent in Toronto and Montreal for proprietary model development.
- Payment Processors:Real-time transaction networks require sub-100 millisecond inference latency at massive scale. MasterCard Canada and domestic networks deploy edge computing architectures across North American payment corridors.
- Investment Firms:Asset managers and hedge funds consume alternative data and predictive analytics for alpha generation.
- Insurance Companies:Property, casualty, and life insurers apply AI to claims processing, underwriting automation, and fraud detection.
Banking institutions lead volumes today; payment processors are expanding most quickly as contactless transaction volumes surge.
Deployment:
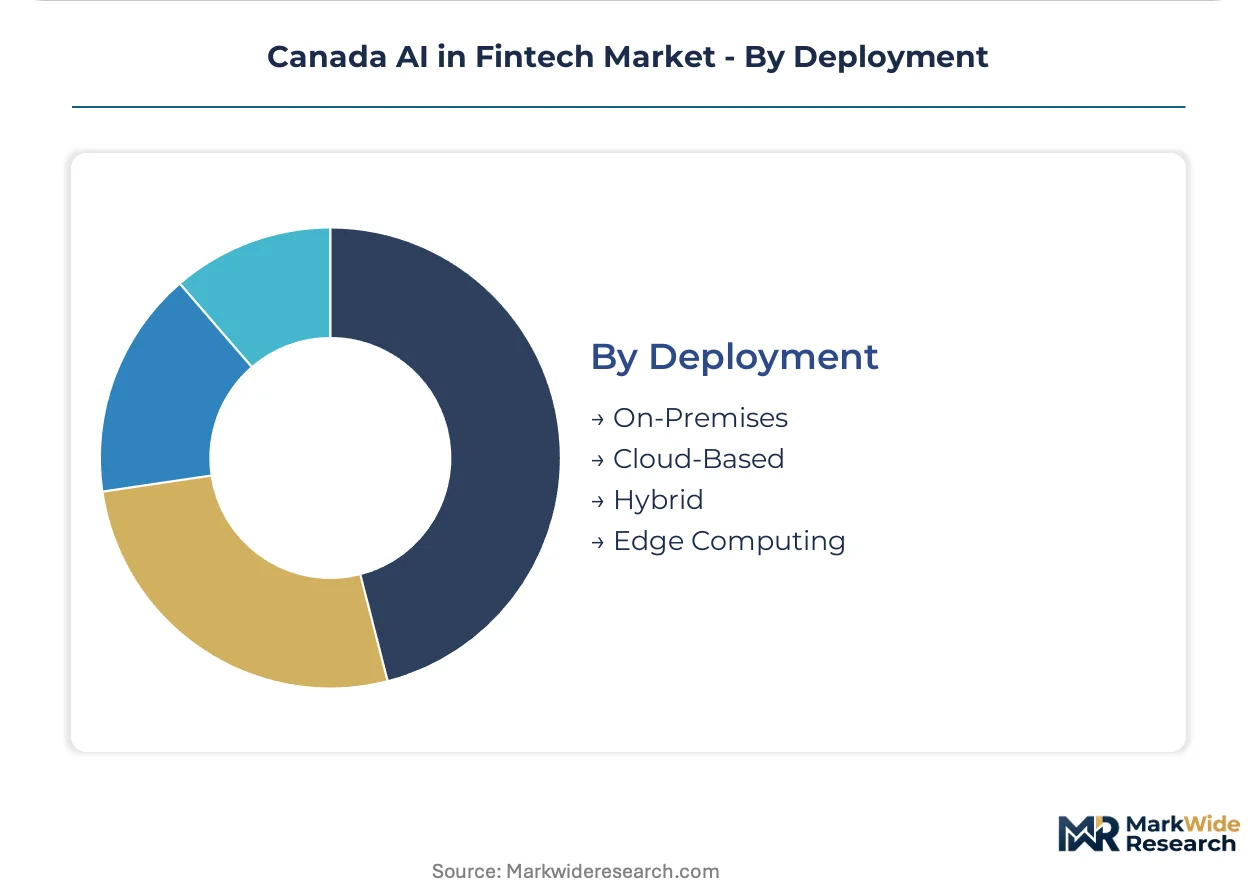
Deployment architecture selection reflects data residency requirements and legacy system constraints, with OSFI compliance pushing cloud adoption while mainframe dependencies sustain hybrid installations.
- Cloud-Based:OSFI-compliant Canadian data residency frameworks mature, concentrating procurement among three domestic providers. Tier-two institutions lacking capital reserves for on-premises infrastructure default to subscription-based API consumption models.
- Hybrid:Tier-one banks with legacy mainframe dependencies maintain on-premises transaction processing while offloading analytics to cloud environments. This architecture introduces latency and failure modes but preserves core system stability.
- On-Premises:Fully captive infrastructure serves institutions with strictest data sovereignty requirements or specialized latency demands.
- Edge Computing:Decentralized processing at payment terminals and mobile devices enables real-time fraud scoring without cloud round-trips.
Cloud-based deployment leads volumes today; edge computing is gaining share fastest as contactless latency requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian AI in fintech emerged from Toronto's established banking infrastructure and Montreal's academic AI research foundations, with early deployment concentrated in fraud detection for the country's federally regulated financial institutions.
Ontario
Toronto's financial district anchors enterprise AI procurement as RBC and major banks deploy machine learning for real-time transaction monitoring. OSFI's Guideline B-13 compliance deadlines accelerate infrastructure spending across federally regulated institutions headquartered here. The Waterloo-Toronto corridor concentrates fintech startups leveraging proximity to banking decision-makers and venture capital.
Quebec
Montreal's AI research corridor generates specialized talent pipelines through McGill, Université de Montréal, and Mila partnerships with financial institutions. The Autorité des marchés financiers layers algorithmic trading disclosure requirements onto provincially supervised entities. Investment firms in Montreal absorb predictive analytics capabilities fastest for alternative data alpha generation.
British Columbia
Vancouver's technology sector concentrates wealth management AI development as firms address PIPEDA amendments requiring algorithmic impact assessments. The British Columbia Securities Commission enforces disclosure frameworks for automated investment advice. Fintech clusters here focus on subscription-based tooling procurement for mid-market credit unions.
Alberta
Calgary's energy finance sector drives demand for climate risk analytics as OSFI disclosure requirements reshape loan portfolio assessment. Provincial economic development incentives attract AI infrastructure investment for resource-dependent sector advisory services. Payment processors here deploy edge computing architectures for contactless transaction latency reduction.
Atlantic Canada
Halifax and St. John's emerging fintech clusters offer lower operational costs than central Canadian metros for AI development teams. Provincial incentives reduce facility and talent acquisition expenses for institutions seeking alternatives to Toronto and Montreal pricing. Federated learning architectures gain traction here as institutions train models across distributed datasets without centralizing sensitive information.
Canada AI in Fintech Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Canadian AI in fintech, with tier-one banks maintaining captive research divisions while mid-market institutions subscribe to API-based tooling. The market structures around three archetypes: federally regulated banks with proprietary AI divisions, specialized fintech challengers with direct-to-consumer positioning, and global payment networks with real-time infrastructure scale. Consolidation pressure intensifies as OSFI compliance requirements favor vendors with embedded audit-ready governance layers. Strategic partnerships between academic institutions and financial services firms accelerate talent acquisition and model development timelines.
Within the banking archetype, RBC anchors enterprise-grade deployment through its Borealis AI research division, while Wealthsimple exemplifies the direct-to-consumer challenger model with automated portfolio construction capabilities. MasterCard Canada occupies a position on the payment network vector, competing through real-time transaction intelligence across North American corridors. These three represent distinct competitive positioning strategies: captive research investment, consumer-facing automation, and infrastructure-scale inference deployment.
| Leading Market Players |
|---|
| Chimoney |
| Finofo |
| FriedmannAI |
| Propra |
| Wealthsimple |
| RBC |
| Hubdoc |
| MasterCard Canada |
| Bitbuy |
| Others |
Pricing and Supply Chain Analysis
OSFI compliance tiering bifurcates AI procurement into audit-ready premium platforms and basic API tooling, with this divergence manifesting in both subscription pricing stratification and vendor certification requirements across Canadian financial infrastructure procurement.
Pricing Analysis
Subscription-based SaaS tiers dominate Canadian fintech AI procurement, with pricing stratifying across enterprise-grade, mid-market, and credit union levels based on OSFI audit readiness and data residency certification. Price differentiation rests on governance layer depth and inference latency guarantees rather than raw model performance. Cost compression in mid-market tiers intensifies as GPU infrastructure commoditizes, while federally regulated banks show lowest price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Freight costs for specialized AI hardware remain secondary to semiconductor fabrication concentration in Taiwan, South Korea, and the United States, where GPU and TPU supply feeds Canadian cloud infrastructure buildouts. Raw material dependencies span advanced silicon wafers, high-bandwidth memory modules, and liquid cooling systems. Single-source vulnerability around NVIDIA accelerator supply creates procurement risk for tier-one institutions scaling deep learning deployments. Distribution runs through hyperscaler channel partners and direct OEM relationships with domestic data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada AI in Fintech represents a late-cycle quality story where procurement shifts toward audit-ready governance specifications as OSFI enforcement tightens compliance premiums for infrastructure investments.
For Market Incumbents: Anchor enterprise positioning through captive MLOps infrastructure that embeds OSFI B-13 audit trails directly into model deployment pipelines. Deepen backward integration into specialized talent acquisition via Montreal-Toronto academic partnerships to defend against US technology firm recruitment. Consolidate vendor relationships around three domestic cloud providers with proven data residency frameworks. For New Entrants and Emerging Players: Federated learning architectures offer a technology-first wedge into Atlantic Canada credit unions seeking PIPEDA-compliant model training without centralized data exposure. Target Halifax and St. John's clusters where provincial incentives reduce facility costs and incumbent presence thins. Pursue subscription-based API pricing to bypass capital reserve barriers facing tier-two institutions. For Investors and Strategic Acquirers: Consolidation pressure builds where OSFI compliance costs exceed standalone infrastructure economics for mid-market vendors. Long-term viability favors platforms with embedded governance layers and proven federal bank relationships. Acquisition targets cluster around MLOps specialists with financial services domain certification. Watch for inflection where provincial open banking mandates expand training data availability for consumer lending algorithms.| Strategic Initiative | Industry Significance |
|---|---|
| OSFI-Compliant Cloud Migration | Federally regulated banks shift procurement to domestic providers with proven data residency frameworks. |
| Federated Learning Platform Launch | Atlantic Canada institutions deploy distributed training architectures satisfying PIPEDA constraints. |
| Montreal AI Corridor Partnership | Université de Montréal and Mila partnerships accelerate specialized fintech talent pipelines. |
| Edge Computing Infrastructure Buildout | Payment processors deploy terminal-level inference to meet sub-100 millisecond latency requirements. |
| Climate Risk Analytics Product Line | Calgary energy finance sector adopts predictive models for OSFI-mandated loan portfolio assessment. |
Research Methodology
Bottom-up banking institution modeling reconciled against top-down cloud infrastructure tracking forms the analytical core, combining primary interviews with OSFI compliance officers, MLOps engineers at tier-one banks, fintech CTOs, and provincial securities commission staff with secondary validation through OSFI regulatory filings, hyperscaler capex disclosures, and Canadian cloud provider infrastructure announcements.
Input-output matrices map AI deployment volumes across application segments, technology architectures, and end-user categories throughout the forecast period. Segmentation dimensions include fraud detection versus credit scoring workflows, machine learning versus deep learning technology stacks, and cloud-based versus hybrid deployment models. CAGRs derive from installed base growth rates and average revenue per institution trends, with inputs from GPU pricing indices and regulatory compliance timeline shifts.
The model holds under stable OSFI enforcement intensity and continued digital payment volume growth; deviation in federal AI legislation timing or semiconductor export restrictions would shift infrastructure investment trajectories. Stakeholders should weight assumptions against their own operating context and compliance readiness timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Netherlands AI in Fintech Market
FinTech
Lendtech Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Japan AI in Fintech Market
FinTech
Fintech Crisis Management Market
FinTech
Europe Embedded Finance Market
FinTech
Singapore Fintech Market
FinTech
Supply Chain Finance Market
FinTech
AI in Fintech Market
FinTech
Cloud AI in Fintech Market
FinTech
Wealthtech Solutions Market
FinTech
Autonomous Finance Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Global Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
Europe Fintech Cloud Market