
 Robo-Advisory Services Market | 2026-2036
Robo-Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Robo-Advisory Services Market Analytics
Subscription-based portfolio rebalancing is repositioning the core revenue model away from AUM-dependent fees toward predictable recurring revenue. Vanguard Group leverages its mutual fund dominance to anchor hybrid robo-human advisory flows at scale. Betterment specializes in goal-based financial planning interfaces that differentiate its user experience from commodity allocation engines. Wealthfront Corporation extends its technology stack into banking products, competing across the full retail financial services spectrum.
Robo-advisory services deploy algorithmic engines to automate portfolio construction, tax-loss harvesting, and rebalancing against client risk profiles and time horizons. These platforms integrate modern portfolio theory with execution algorithms that minimize tracking error and transaction costs across diversified asset classes. Automated Investment leads service type revenue as the entry-point functionality for first-time digital wealth users. Machine Learning within the Technology segment captures expanding margin pools as predictive analytics improve cash forecasting and behavioral nudging. Retail Investors anchor client type volume, though High-Net-Worth Individuals represent the fastest-growing segment as hybrid advisory models gain credibility among affluent households.
The SEC enforces fiduciary standards through Regulation Best Interest, compelling platforms to document algorithmic suitability logic and conflict disclosures. The EU's MiFID II suitability framework and GDPR data governance requirements shape product architecture for cross-border providers. FINRA examination priorities increasingly target AI model governance and cybersecurity protocols at registered investment advisers. Stakeholders must monitor evolving algorithmic accountability standards as regulators weigh explainability mandates against proprietary model protection.
Market Dynamics
Algorithmic fiduciary compliance is restructuring platform economics as the SEC's Regulation Best Interest and EU MiFID II suitability mandates force documentation of automated decision logic. This regulatory compression favors incumbents with compliance infrastructure while raising barriers for new entrants.
Growth Catalysts
- Machine Learning Integration:Predictive analytics engines now forecast cash flows and nudge behavioral adjustments, deepening client engagement metrics for retail platforms.
- Retail Investor Democratization:Automated portfolio tools deliver institutional-grade diversification to mass-affluent households previously excluded from wealth management services.
- MiFID II Suitability Framework:European regulatory harmonization creates cross-border passporting opportunities for algorithmic advisory providers operating under unified compliance standards.
Market Restraints
- Proprietary Model Protection:Explainability mandates under emerging algorithmic accountability standards threaten to expose competitive intellectual property embedded in portfolio construction engines.
- Data Governance Friction:GDPR compliance costs and cross-border data localization requirements impose structural overhead on cloud-native platform architectures.
- Hybrid Advisory Substitution:Human-augmented wealth management retains preference among high-net-worth segments resistant to fully automated relationship models.
Strategic Opportunities
- Banking Product Convergence:Technology stack extension into high-yield savings and lending products captures full-spectrum retail financial relationships beyond pure investment management.
- Goal-Based Interface Innovation:Specialized planning tools targeting specific life objectives differentiate user experience from commodity asset allocation engines.
- Tax-Loss Harvesting Automation:Sophisticated execution algorithms minimize tracking error while optimizing after-tax returns across taxable brokerage accounts.
Industry Challenges
- AI Model Governance Expertise:FINRA examination priorities demand specialized compliance personnel capable of documenting algorithmic suitability logic and conflict disclosure protocols.
- Legacy System Integration:Established broker-dealer infrastructure requires costly middleware development to embed robo-advisory capabilities within existing client relationship management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robo-Advisory Services Market |
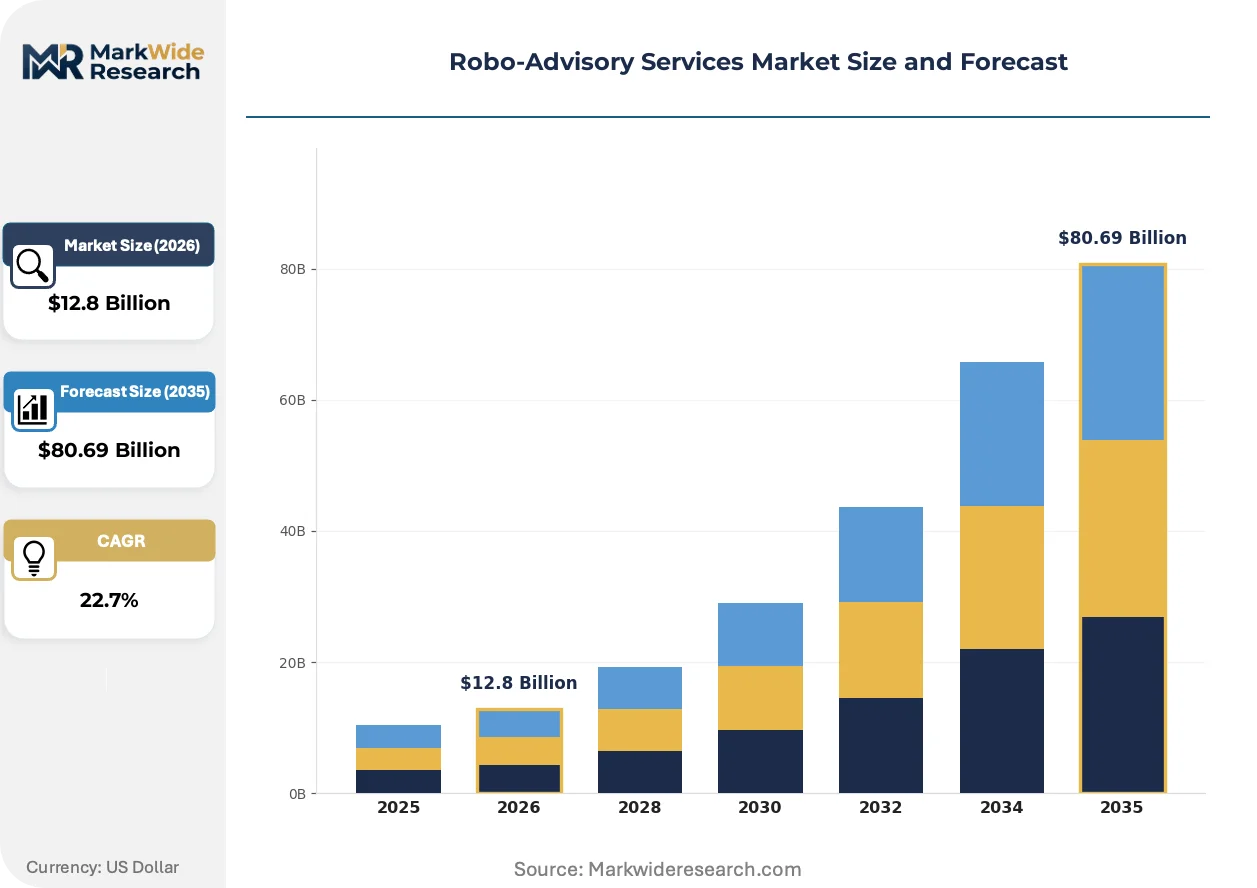
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $80.69 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automated Investment, Financial Planning, Portfolio Management, Tax Optimization Client Type: Retail Investors, High-Net-Worth Individuals, Institutions, Corporations Technology: AI Algorithms, Machine Learning, Blockchain, Data Analytics Investment Strategy: Passive Management, Active Management, Asset Allocation, Impact Investing |
| Companies Covered | Vanguard Group, Charles Schwab, Betterment, Wealthfront Corporation, SigFig Wealth Management, Empower Advisory Group, Ellevest, Acorns Grow, SoFi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robo-Advisory Services Market Evolving Landscape
Platform architecture is fragmenting into composable service layers as specialized providers unbundle portfolio construction, custody, and client interface functions. This decomposition enables faster feature iteration while complicating vendor management.
Natural language processing is modularizing client onboarding workflows. Conversational interfaces extract risk tolerance and time horizon data through unstructured dialogue rather than static questionnaires. Mass-market platforms deploy these engines to compress account opening friction. The technology is modularizing Know-Your-Customer compliance into discrete, automatable micro-services.
The SEC's Regulation Best Interest enforcement is tightening documentation requirements for algorithmic recommendation trails. Registered investment advisers must now maintain audit-ready records of suitability logic and conflict disclosures. Retail-facing platforms bear the heaviest compliance burden as examination resources concentrate on high-volume automated advice channels.
Subscription pricing is displacing traditional asset-under-management fee structures across digital wealth platforms. Predictable recurring revenue models attract venture financing and stabilize cash flows independent of market volatility. This shift is most visible in the United States where fintech infrastructure supports direct billing relationships with mass-affluent households.
Robo-Advisory Services Market Segmentation
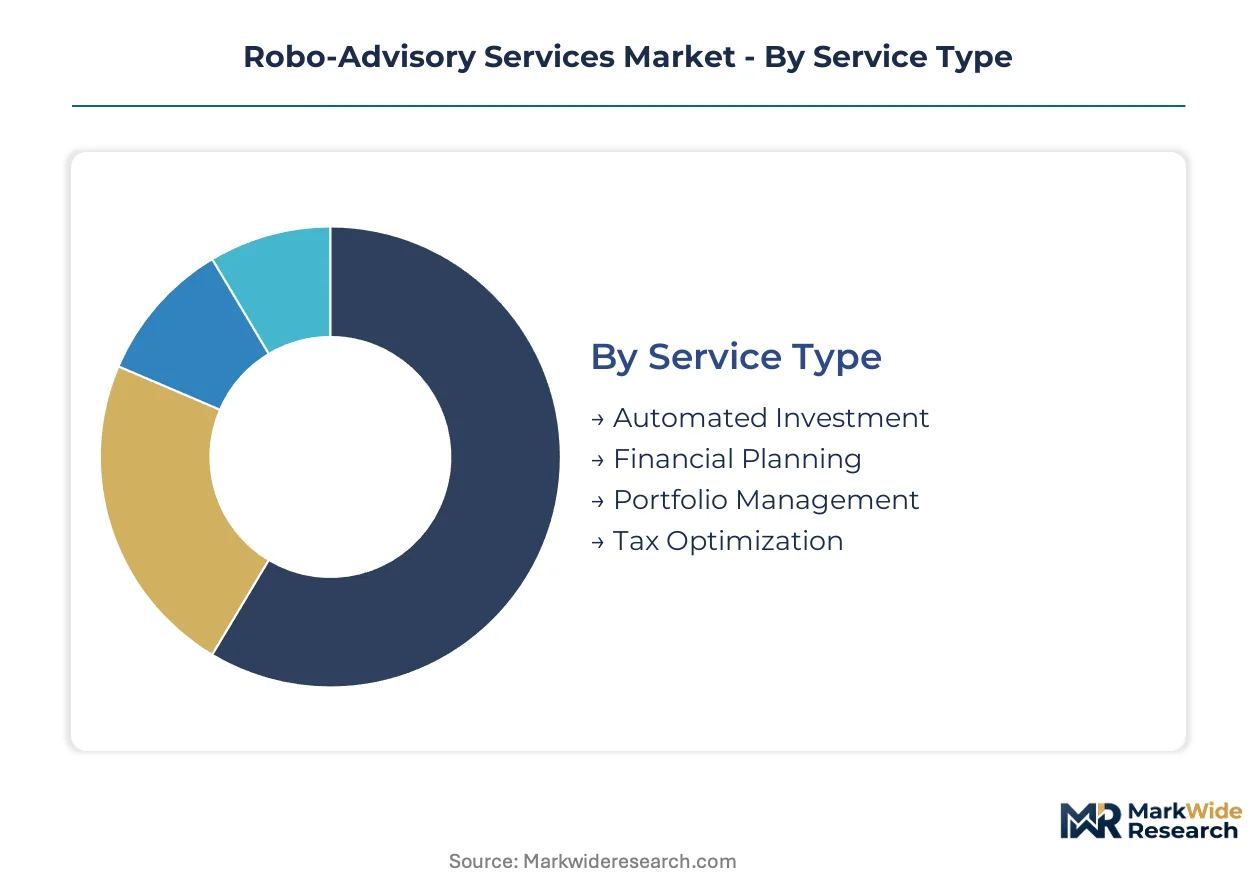
Segmentation in robo-advisory services reveals how regulatory compliance burdens, technology sophistication, and client sophistication requirements stratify platform economics. Each dimension carries distinct SEC fiduciary documentation obligations and MiFID II suitability mandates that reshape vendor investment priorities.
Service Type:
SEC Regulation Best Interest and EU MiFID II impose tiered documentation requirements: automated investment demands algorithmic audit trails, while tax optimization requires granular conflict disclosure protocols.
- Automated Investment:Core algorithmic portfolio construction engines execute modern portfolio theory across diversified asset classes with minimal tracking error. Retail platforms in the United States concentrate demand here as entry-point functionality for first-time digital wealth users seeking low-cost diversification.
- Tax Optimization:Sophisticated execution algorithms harvest tax losses while maintaining portfolio exposure through substitute securities. High-net-worth households in taxable brokerage accounts drive adoption as after-tax return maximization becomes a primary platform selection criterion.
- Financial Planning:Goal-based interfaces translate life objectives into funded liability streams with automated contribution scheduling.
- Portfolio Management:Continuous rebalancing engines maintain target allocations against drift thresholds with cost-minimizing trade sequencing.
Leading the category by volume: Automated Investment. Growing fastest: Tax Optimization.
Client Type:
Margin structures diverge sharply across client tiers, with retail subscribers generating predictable recurring revenue while institutional mandates demand bespoke algorithmic customization.
- Retail Investors:Mass-affluent households accessing institutional-grade diversification through subscription-based pricing models independent of market volatility. Silicon Valley fintech clusters and established broker-dealer infrastructure in the United States accelerate deployment velocity for this segment.
- High-Net-Worth Individuals:Affluent households adopting hybrid robo-human advisory models that combine algorithmic efficiency with relationship manager oversight. This segment climbs fastest as credibility gaps narrow and platforms document fiduciary compliance rigorously.
- Institutions:Pension funds and endowments requiring white-label algorithmic infrastructure with custom risk overlay parameters.
- Corporations:Employer-sponsored retirement plan sponsors seeking automated 401(k) allocation guidance for participant bases.
Dominating revenue contribution: Retail Investors. Steepest expansion trajectory: High-Net-Worth Individuals.
Technology:
Technology selection determines compliance architecture complexity, with machine learning models facing heightened FINRA examination scrutiny for explainability and bias documentation.
- Machine Learning:Predictive analytics engines forecast cash flows and nudge behavioral adjustments through personalized intervention timing. Cloud-native platforms invest here to deepen engagement metrics and reduce churn among retail subscriber bases.
- AI Algorithms:Natural language processing modularizes client onboarding by extracting risk tolerance through unstructured dialogue rather than static questionnaires. GDPR data governance requirements in Europe impose structural overhead on these conversational deployment architectures.
- Data Analytics:Descriptive and diagnostic capabilities underpin portfolio performance attribution and client reporting transparency.
- Blockchain:Distributed ledger infrastructure enables fractional asset ownership and automated smart contract execution for alternative investment access.
Capturing expanding margin pools: Machine Learning. Facing regulatory headwinds: AI Algorithms.
Investment Strategy:
Strategy taxonomy reflects the maturity curve of algorithmic advisory, with passive management commoditized and impact investing requiring novel data integration for environmental and social scoring.
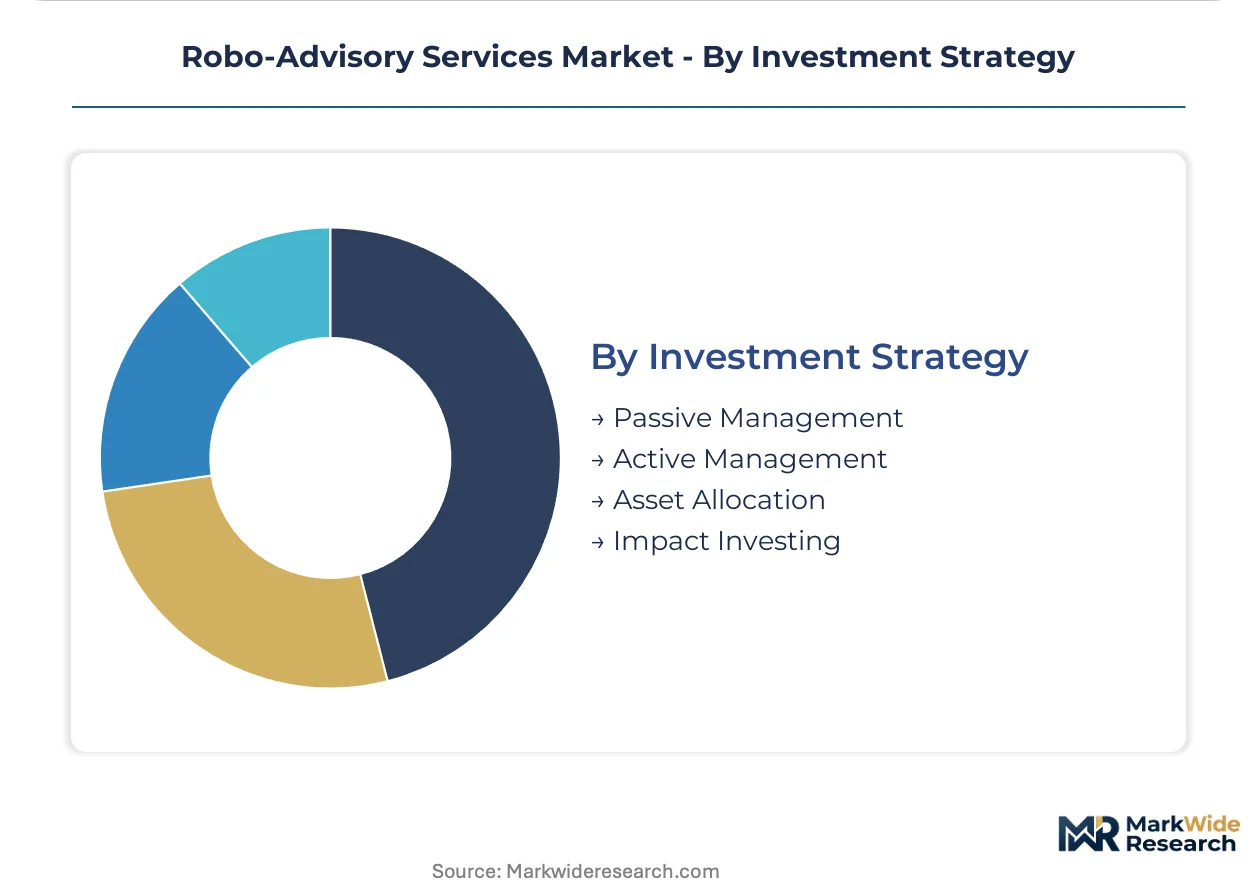
- Passive Management:Index-tracking portfolios minimize expense ratios and tax drag through low-turnover implementation. Vanguard Group anchors hybrid flows at scale by leveraging mutual fund dominance to deliver these strategies efficiently.
- Impact Investing:Environmental, social, and governance integration demands proprietary data feeds and scoring methodologies that differentiate platform offerings. European MiFID II sustainability preferences accelerate adoption as suitability frameworks mandate explicit values alignment documentation.
- Active Management:Factor-based and tactical allocation overlays seek excess returns through systematic deviation from capitalization weights.
- Asset Allocation:Strategic mix determination across geographies, sectors, and asset classes based on client time horizon and risk capacity.
Commoditized foundation: Passive Management. Gaining share fastest: Impact Investing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors robo-advisory deployment velocity through its dense concentration of fintech infrastructure and venture capital networks. Algorithmic wealth management platforms cluster around established broker-dealer ecosystems and cloud-native technology stacks.
United States
Retail investor demand concentrates in mass-affluent households seeking low-cost diversification through subscription-based pricing models. SEC Regulation Best Interest mandates algorithmic audit trails and conflict disclosure protocols for automated recommendation engines. New York and Boston broker-dealer corridors host hybrid advisory platforms combining human oversight with algorithmic efficiency.
United Kingdom
Wealth management digitization accelerates among affluent households adopting hybrid robo-human advisory models. FCA consumer duty requirements impose explicit value-for-money documentation on automated investment services. London fintech clusters drive natural language processing integration into client onboarding workflows.
Germany
Retail banking integration creates demand for full-spectrum financial services beyond pure investment management. BaFin suitability requirements under EU MiFID II harmonization mandate explicit values alignment documentation for sustainability preferences. Frankfurt's established custody infrastructure supports white-label algorithmic deployment for regional banks.
Japan
Demographic shifts toward aging populations generate demand for goal-based financial planning interfaces targeting retirement liability streams. FSA guidelines on digital advisory suitability require granular risk profiling documentation for automated portfolio construction. Tokyo's asset management district hosts partnerships between domestic banks and specialized fintech providers.
Singapore
Cross-border wealth management demand from Southeast Asian high-net-worth individuals drives hybrid advisory platform adoption. MAS digital advisory licensing framework creates regulatory clarity for algorithmic portfolio services operating across multiple jurisdictions. The city-state's fund domiciliation ecosystem supports tax-loss harvesting automation for regional taxable brokerage accounts.
Robo-Advisory Services Market Competitive Landscape
Capital-heavy asset managers compete with asset-light technology platforms for algorithmic advisory market share. Incumbent mutual fund complexes leverage existing custody infrastructure and brand recognition to anchor hybrid service flows. Three strategic archetypes dominate: diversified asset managers with proprietary fund ecosystems, pure-play fintech platforms with specialized user interfaces, and bank-affiliated providers with integrated deposit-lending capabilities. Competitive dynamics center on M&A activity absorbing specialized technology stacks and strategic partnerships embedding robo-advisory modules within established wealth management workflows.
Within the diversified asset manager tier, Vanguard Group and Charles Schwab occupy positions defined by scale-driven cost advantages and existing brokerage infrastructure. Betterment and Wealthfront Corporation exemplify the pure-play technology archetype, with the former representing goal-based interface specialization and the latter anchoring banking product convergence strategies. SigFig Wealth Management sits within the white-label technology provider segment, enabling algorithmic deployment for institutions lacking in-house development capabilities.
| Leading Market Players |
|---|
| Vanguard Group |
| Charles Schwab |
| Betterment |
| Wealthfront Corporation |
| SigFig Wealth Management |
| Empower Advisory Group |
| Ellevest |
| Acorns Grow |
| SoFi Technologies |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure costs cascade through robo-advisory platform economics, compressing margins for asset-light entrants while enabling scale advantages for incumbents with captive data center capacity or long-term hyperscaler contracts. This input cost structure stratifies pricing power across subscription tiers, with platforms bearing higher compute intensity forced toward premium positioning.
Pricing Analysis
Outcome-linked subscription pricing anchors client acquisition, with platforms charging recurring fees tied to portfolio performance thresholds or goal-achievement metrics rather than pure AUM percentages. Price differentiation separates hybrid advisory bundles with human overlay from fully automated tiers, with SEC fiduciary documentation costs widening the gap between compliant and non-compliant providers. Pricing pressure intensifies in the mass-retail segment as venture-backed platforms subsidize user growth through below-cost onboarding offers. Corporate retirement plan sponsors exhibit lowest price sensitivity due to liability-driven procurement criteria, while individual retail subscribers demonstrate highest elasticity to fee changes.
Supply Chain Analysis
Cross-border data transfer costs impose structural overhead on cloud-native architectures, particularly for European providers navigating GDPR localization requirements against centralized AWS, Azure, and Google Cloud regions. Supply concentration clusters in the United States, Ireland, and Singapore as primary hyperscaler availability zones, with Frankfurt and Tokyo serving regional compliance hubs. Platform technology stacks draw from open-source machine learning frameworks, proprietary execution algorithms, and licensed market data feeds. Single-source vulnerability concentrates in custody and clearing infrastructure, where established broker-dealers control access to fractional share execution and tax-lot accounting. Distribution runs through direct-to-consumer digital channels, white-label institutional deployments, and embedded partnerships within banking ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning inference engines are displacing rules-based portfolio construction as the core technology stack, forcing legacy platforms into costly retooling cycles or strategic obsolescence. This transition phase rewards first movers with training data scale and regulatory documentation rigor.
For Market Incumbents: Lock in hybrid advisory workflows by embedding algorithmic efficiency within existing human relationship manager infrastructure, defending against pure-play fintech disintermediation through custody control and brand trust. Prioritize MiFID II and SEC Regulation Best Interest compliance documentation as a competitive moat, raising barriers for undercapitalized entrants lacking specialized governance personnel. Capacity addition in European data residency zones addresses GDPR friction while capturing cross-border passporting opportunities. For New Entrants and Emerging Players: API-first distribution partnerships with regional banks and credit unions represent the most penetrable channel, bypassing direct customer acquisition costs that incumbents amortize across existing bases. White-label technology provision for employer-sponsored retirement plans offers concentrated B2B volume with lower fiduciary liability exposure than retail-facing deployments. Target goal-based financial planning interfaces as the differentiation vector, where natural language processing and behavioral nudging capabilities remain underdeveloped among established providers. For Investors and Strategic Acquirers: FINRA examination priority shifts toward AI model governance is the leading indicator that regulatory technology capabilities will command acquisition premiums across the valuation stack. Long-term viability centers on platforms demonstrating algorithmic explainability documentation and audit-ready suitability logic, with distressed assets likely emerging from venture-backed entrants that underestimated compliance infrastructure costs. Watch for consolidation signals when specialized machine learning teams become acquisition targets by diversified asset managers seeking in-house predictive analytics capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Advisory Platform Integration | Combines algorithmic efficiency with human relationship manager oversight to capture high-net-worth migration from pure automation. |
| Banking Product Stack Extension | Captures full-spectrum retail financial relationships through high-yield savings and lending beyond pure investment management. |
| Regulatory Technology Investment | Builds defensible moats through SEC and MiFID II compliance documentation ahead of explainability mandate enforcement. |
| Natural Language Processing Deployment | Compresses client onboarding friction through conversational risk tolerance extraction rather than static questionnaire workflows. |
| White-Label Infrastructure Licensing | Enables regional banks and credit unions to deploy algorithmic advisory without proprietary development capacity. |
Research Methodology
SEC enforcement actions, FINRA examination priorities, and EU regulatory guidance documents formed the secondary backbone for compliance architecture analysis, cross-referenced against platform disclosure filings and custody infrastructure records. Primary interviews with chief technology officers at registered investment advisers, regulatory affairs leads at fintech platforms, and procurement officers at employer-sponsored retirement plan sponsors validated algorithmic deployment patterns and pricing model evolution. Bottom-up triangulation against top-down market sizing from venture financing disclosures and AUM reporting produced volume and value estimates across service type and client segments.
Historical trendline analysis of subscription pricing adoption and hybrid advisory penetration established baseline growth trajectories, with projection modeling incorporating service type segmentation, technology stack sophistication tiers, and regional regulatory framework clusters. CAGRs derived from fitted growth curves adjusted for regulatory implementation timelines and venture capital cycle dynamics. Forecast inputs included cloud infrastructure cost trajectories, machine learning talent availability by geography, and fiduciary documentation burden escalation under emerging algorithmic accountability standards.
Inputs from regulatory filings and platform disclosures were available through the study window; gaps in proprietary algorithmic performance data and undisclosed client churn rates introduce uncertainty bands around subscriber lifetime value projections. Stakeholders should weight assumptions against their own operating context and regulatory examination history.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
United Kingdom AI in Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
UAE Fintech Market
FinTech
Financial Analytics Market
FinTech
Singapore Fintech Market
FinTech
Europe Fintech Cloud Market
FinTech
Hand Account Software Market
FinTech
Financial Consolidation Software Market
FinTech
China AI in Fintech Market
FinTech
Fintech-As-A-Service Market
FinTech
France AI in Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
Netherlands AI in Fintech Market
FinTech
AI in Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
Financial Fraud Detection Software Market