
 Embedded Lending Market | 2026-2036
Embedded Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Lending Market Analysis
Asset-light balance sheet partnerships between banks and technology platforms is fragmenting competitive boundaries in consumer credit distribution. Affirm leverages direct merchant integrations to sustain checkout presence across major retail verticals. Klarna anchors European market development through its banking license and super-app strategy. Afterpay competes aggressively in the Australian and North American markets via its pay-in-four model.
Embedded lending refers to the integration of credit origination, underwriting, and servicing directly within non-financial digital platforms through API-connected infrastructure, typically involving automated decision engines that process alternative data streams in under two seconds. The architecture enables commerce platforms to offer financing without redirecting customers to external banking interfaces. Point of Sale Financing leads service type revenue pools due to its direct attachment to high-ticket merchant transactions. API Integration dominates deployment architecture as platforms prioritize real-time connectivity over white-label builds. Buy Now Pay Later occupies the fastest-expanding service tier, though margin compression intensifies as regulatory scrutiny tightens repayment terms.
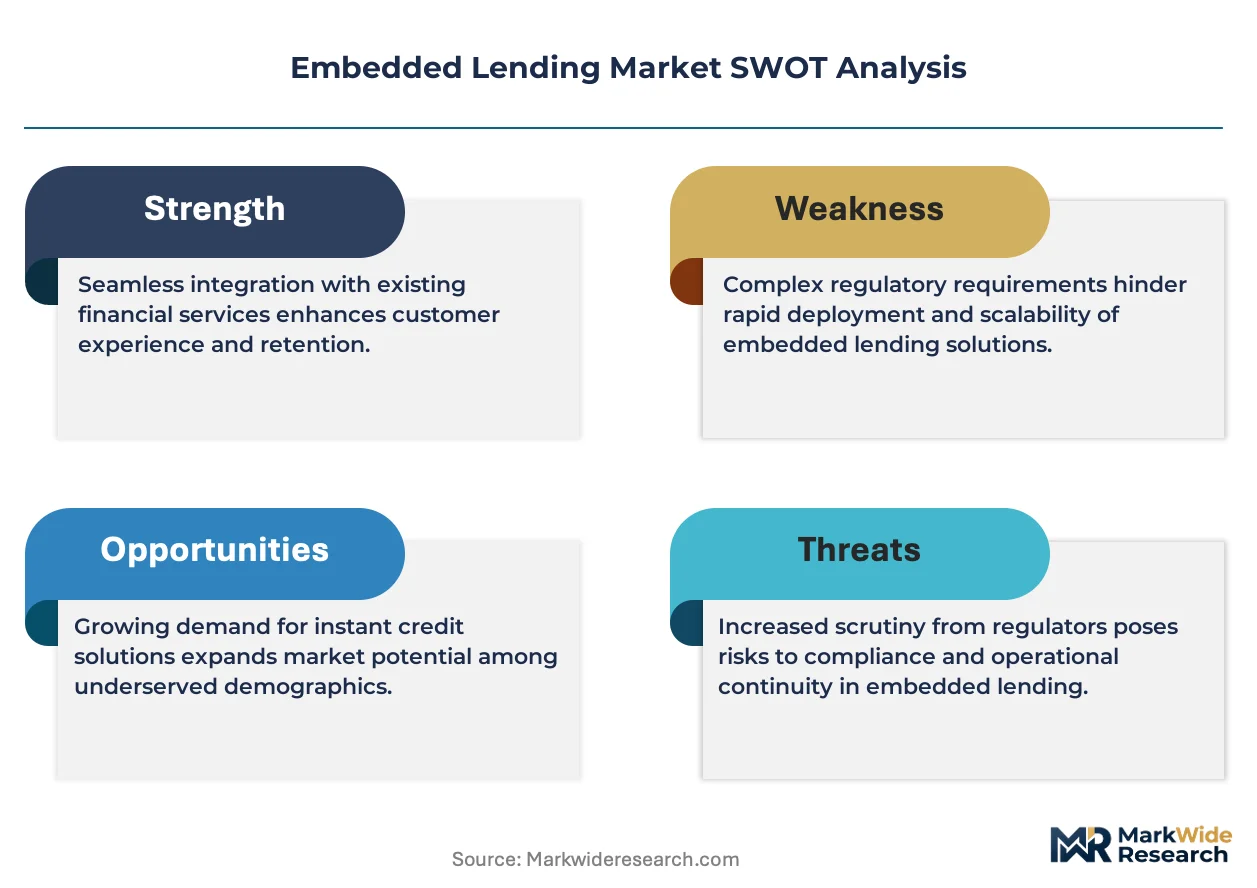
The Consumer Financial Protection Bureau supervises embedded credit products in the United States through its Buy Now, Pay Later oversight framework, while the EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions. The UK's Financial Conduct Authority mandates affordability assessments that reshape platform risk models. Stakeholders must monitor evolving jurisdictional licensing requirements as regulators distinguish between merchant-facilitated credit and regulated lending activity.
Market Dynamics
Real-time API infrastructure is compressing origination timelines from days to milliseconds, forcing incumbent banks to dismantle legacy middleware stacks and reprice risk through alternative data streams.
Growth Catalysts
- Open Banking APIs:PSD2 mandates in the European Union require banks to expose customer data through standardized interfaces, enabling non-financial platforms to embed credit decisions without building proprietary data infrastructure.
- Checkout Conversion Optimization:E-commerce merchants facing cart abandonment pressure deploy point-of-sale financing to reduce friction at payment gates, particularly in furniture and electronics verticals.
- Alternative Data Proliferation:Cash-flow underwriting models leveraging bank transaction histories and employment verification APIs expand addressable borrower pools beyond traditional FICO-bound segments.
Market Restraints
- Capital Intensity of Balance Sheet Commitments:Platforms originating loans face funding cost volatility as warehouse credit lines reprice with central bank rate movements, compressing net interest margins.
- Algorithmic Audit Requirements:The EU AI Act imposes documentation burdens on automated underwriting engines, extending compliance timelines and raising fixed technology costs for cross-border deployment.
- Merchant Concentration Risk:Revenue dependence on a narrow cohort of large retail partners exposes platforms to volume cliff events when major accounts switch providers or internalize lending functions.
Strategic Opportunities
- SMB Working Capital Embedding:B2B procurement platforms in India represent underpenetrated terrain where invoice financing APIs can attach to enterprise resource planning workflows.
- Regulatory Arbitrage via Banking Licenses:Securing deposit-taking authority in Sweden or Germany reduces funding spreads and insulates platforms from third-party capital market disruptions.
- Voice Commerce Integration:Smart speaker ecosystems and automotive infotainment systems create novel origination channels where conversational interfaces handle credit applications without screen-based authentication.
Industry Challenges
- Model Risk Management Talent Scarcity:Platforms struggle to recruit quantitative analysts capable of validating machine learning credit models under supervisory scrutiny from the Consumer Financial Protection Bureau.
- Legacy Core Banking Integration:Partnerships with chartered institutions frequently stall on middleware incompatibility between modern API stacks and decades-old mainframe architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Lending Market |
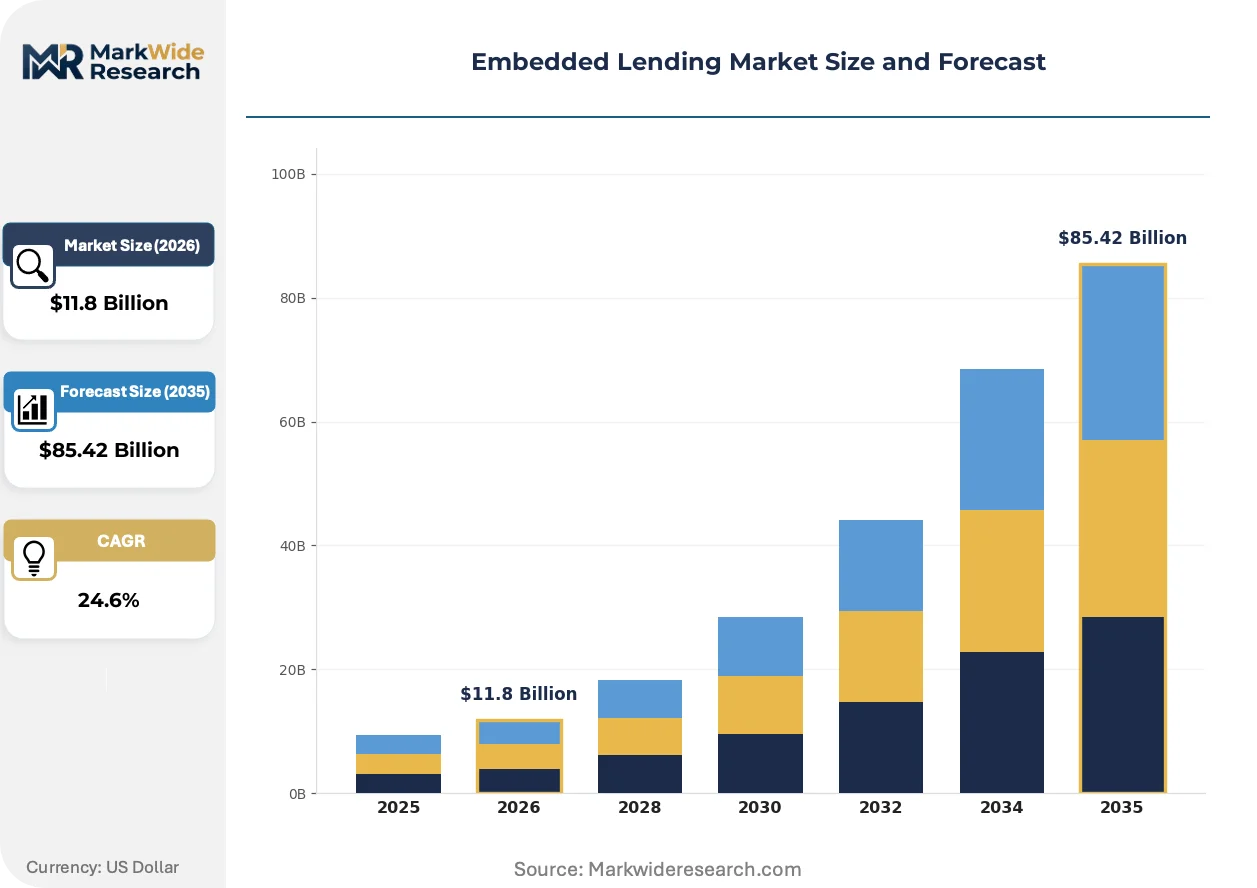
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $85.42 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Point of Sale Financing, Digital Wallets, Invoice Financing, Buy Now Pay Later Integration Level: API Integration, White Label Solutions, Plugin Solutions, Direct Integration End User: E-commerce Platforms, Financial Institutions, Retailers, Marketplaces Technology: Blockchain, Artificial Intelligence, Machine Learning, Data Analytics |
| Companies Covered | Turnkey Lender, Lendflow, Afterpay, Banxware, Affirm, Klarna, Tapwater, Alchemy, Migo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Lending Market Emerging Trajectories
Embedded lending architectures are fragmenting into specialized component stacks, with distinct competitive arenas forming around decision engines, capital provision, and merchant-facing user experience layers.
Decisioning infrastructure is hybridizing traditional credit bureau scores with real-time cash-flow analytics and behavioral biometrics. Mid-market retailers in the United States adopt these composite models fastest, driven by thin-file customer bases that conventional underwriting excludes. The technology is hybridizing risk assessment timelines, collapsing what required days into sub-second responses that match e-commerce checkout pacing.
The EU AI Act mandates explainability thresholds for automated lending decisions affecting European consumers. Lenders must now generate human-readable rationale outputs for declined applications, forcing re-architecture of black-box neural networks into interpretable model ensembles. Buy-now-pay-later providers operating across Germany and France face the steepest compliance curves as national regulators issue supplementary guidance on algorithmic fairness testing.
Merchant procurement departments now bundle credit origination capabilities into RFP requirements for payment processors, treating embedded finance as a table-stakes feature rather than a premium add-on. This specification shift compresses vendor selection cycles and elevates technical integration speed above standalone pricing in competitive evaluations. The pattern is most pronounced among direct-to-consumer brands headquartered in California and New York that operate without physical retail footprints.
Embedded Lending Market Segmentation
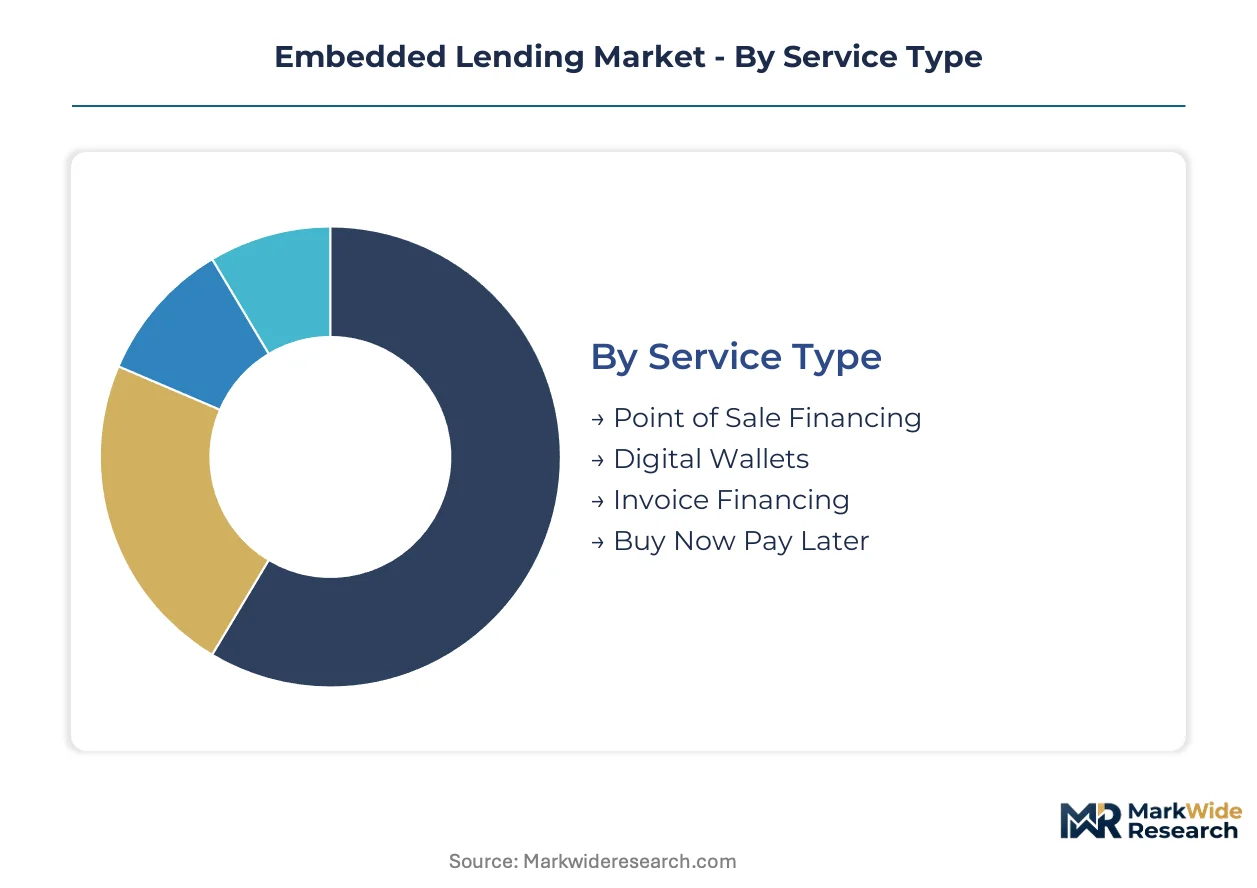
Segmentation in embedded lending reveals how credit infrastructure fragments across technical architectures, merchant integration depths, and decisioning technologies. Each dimension carries distinct capital requirements, regulatory exposure, and partnership dynamics that reshape competitive positioning.
Service Type:
After-sales service intensity varies sharply across service types, with transaction-linked products demanding continuous merchant support while balance-sheet-heavy offerings require ongoing portfolio management.
- Point of Sale Financing:Credit origination embedded directly at merchant checkout terminals, typically structured as installment loans with fixed repayment schedules. Demand concentrates in United States furniture and electronics retailers where average transaction sizes justify underwriting costs. Merchant switching costs rise as platforms integrate with inventory management systems.
- Buy Now Pay Later:Short-term, interest-free installment products repaid in four or fewer payments, dominating apparel and beauty verticals. United Kingdom and German consumers drive volume through fashion e-commerce, though regulatory caps on late fees compress unit economics.
- Digital Wallets:Stored-value accounts with embedded credit lines for recurring purchases, common in ride-hailing and food delivery apps.
- Invoice Financing:Receivables-based working capital for B2B transactions, gaining traction among Indian manufacturing procurement platforms.
By volume, Point of Sale Financing leads. By growth pace, Buy Now Pay Later is ahead.
Integration Level:
Cost tier differentiation separates enterprise-grade API stacks from budget-conscious plugin alternatives, with deployment complexity scaling directly with merchant technical maturity.
- API Integration:Direct server-to-server connectivity enabling real-time credit decisions within native checkout flows. Large United States retailers and marketplaces demand sub-500 millisecond response times, forcing platforms to maintain edge computing infrastructure across multiple availability zones.
- White Label Solutions:Fully branded credit products where the platform provides technology while partners hold regulatory licenses. European neobanks favor this model to bypass lengthy banking charter timelines in Germany and France.
- Plugin Solutions:Pre-built connectors for major e-commerce platforms requiring minimal developer resources.
- Direct Integration:Custom-built implementations for merchants with proprietary technology stacks.
API Integration commands the highest deployment spend per merchant. Plugin Solutions expand most quickly among mid-market retailers lacking internal engineering teams.
End User:
Customer type stratification distinguishes platform-scale deployments from individual merchant implementations, with contract structures and revenue models diverging accordingly.
- E-commerce Platforms:Marketplace operators embedding credit for third-party sellers, requiring multi-tenant risk architectures. United States-based platforms serving direct-to-consumer brands drive implementation velocity as checkout conversion becomes a competitive battleground.
- Retailers:Individual merchants offering branded financing, common in big-ticket categories. Australian and Canadian furniture chains increasingly internalize lending functions after initial platform partnerships.
- Financial Institutions:Banks and credit unions white-labeling embedded credit for digital channels.
- Marketplaces:Multi-vendor platforms facilitating credit access for small sellers.
Retailers generate the deepest revenue per relationship. E-commerce Platforms are gaining share fastest through network effects across seller bases.
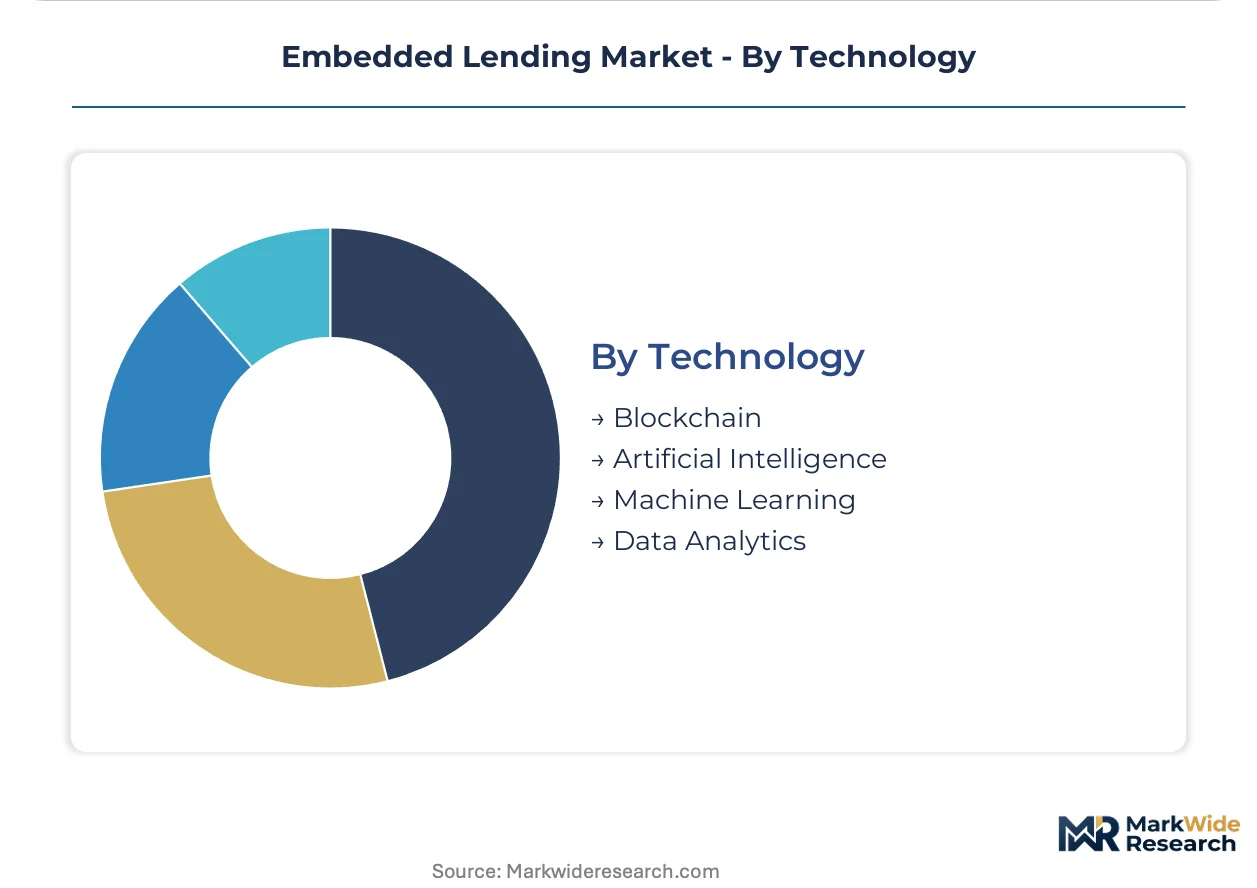
Technology:
Technology maturity separates production-grade decisioning stacks from experimental infrastructure, with regulatory scrutiny intensifying around opaque algorithmic systems.
- Artificial Intelligence:Neural network-based underwriting combining traditional credit data with behavioral signals. United States platforms face Consumer Financial Protection Bureau examination of model fairness, forcing documentation investments that raise fixed costs.
- Machine Learning:Supervised learning models for fraud detection and pricing optimization, deployed across European markets subject to EU AI Act explainability mandates.
- Blockchain:Distributed ledger infrastructure for loan origination and servicing transparency.
- Data Analytics:Descriptive and predictive tools for portfolio monitoring and merchant risk assessment.
Data Analytics underpins the broadest installed base. Artificial Intelligence carries the steepest expansion trajectory despite compliance burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant acquirers and e-commerce platforms concentrate embedded lending demand in five national markets where checkout conversion pressures and open banking regulations have matured fastest.
United States
Furniture and electronics retailers drive point-of-sale financing adoption as cart abandonment rates pressure checkout optimization. The Consumer Financial Protection Bureau supervises Buy Now Pay Later products through its dedicated oversight framework. Silicon Valley and New York City host the densest cluster of API infrastructure providers serving direct-to-consumer brands.
Germany
Industrial procurement platforms embed invoice financing for mid-sized manufacturing suppliers facing working capital gaps. The EU AI Act imposes algorithmic transparency requirements on automated underwriting engines deployed nationwide. Frankfurt anchors banking license applications from fintechs seeking deposit-taking authority to reduce funding costs.
United Kingdom
Fashion e-commerce merchants deploy pay-in-four products to capture thin-file consumers excluded from traditional credit scoring. The Financial Conduct Authority mandates affordability assessments that reshape platform risk models. London's fintech corridor concentrates white-label solution providers partnering with neobanks.
India
B2B marketplace operators attach working capital credit to enterprise resource planning workflows for manufacturing procurement. The Reserve Bank of India regulates digital lending through its scale-based framework for non-banking financial companies. Mumbai and Bangalore host decision-engine providers serving regional supply chain platforms.
Australia
Big-ticket retail chains internalize lending functions after initial platform partnerships mature. The Australian Securities and Investments Commission supervises buy-now-pay-later providers under updated credit licensing requirements. Sydney concentrates merchant-facing user experience layer specialists competing for Pacific Rim expansion contracts.
Embedded Lending Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three tiers. The market structure consolidates around banking-licensed platforms with balance sheet capacity and fragments among API-only infrastructure providers. Two strategic archetypes dominate: merchant-integrated checkout specialists and white-label technology enablers. Competitive moves center on securing banking charters in Northern Europe and embedding voice commerce interfaces into smart speaker ecosystems.
Within the banking-licensed tier, Klarna and Affirm exemplify platform-scale operators that combine direct merchant relationships with deposit-taking infrastructure. Afterpay occupies a position bridging pay-in-four specialization with geographic expansion across Pacific Rim markets. These three companies represent contrasting archetypes for how embedded lending providers balance regulatory capital requirements against merchant acquisition velocity.
| Leading Market Players |
|---|
| Turnkey Lender |
| Lendflow |
| Afterpay |
| Banxware |
| Affirm |
| Klarna |
| Tapwater |
| Alchemy |
| Migo |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European API infrastructure is compressing origination fees as platforms compete for merchant integrations, forcing pricing discipline that favors balance-sheet-heavy operators over pure-technology vendors. This utilization dynamic reshapes supplier selection criteria and pushes consolidation toward licensed deposit-takers with funding cost advantages.
Pricing Analysis
Decision-engine sophistication creates the primary spread between premium API stacks and commodity plugin alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects merchant technical maturity and transaction volume commitments. Cost compression in standard-tier SaaS subscriptions is intensifying because venture-backed entrants prioritize market share capture over unit economics. Mid-market retailers lacking internal engineering teams exhibit highest price sensitivity, while enterprise marketplaces prioritize sub-500 millisecond response guarantees over absolute cost.
Supply Chain Analysis
Specialized decision-engine providers in the United States, Germany, and India hold concentrated capacity for real-time underwriting infrastructure. The supply chain draws from cloud computing hyperscalers, alternative data aggregators, and chartered banking partners for balance sheet capacity. Single-source vulnerability sits with dominant employment verification APIs that multiple platforms share. Distribution runs through direct enterprise sales teams for large merchants and self-serve developer portals for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant procurement departments now treat embedded finance as table-stakes rather than premium add-on, fragmenting vendor selection across specialized component layers and creating niche opportunities for decision-engine specialists and capital-provision intermediaries.
For Market Incumbents: Harden API response time guarantees through edge computing expansion across multiple availability zones to defend against latency-focused challengers. Deepen banking license coverage in Northern Europe to insulate funding costs from central bank rate volatility. Vertical integration into merchant-facing user experience layers counters white-label disintermediation threats from neobank partners. For New Entrants and Emerging Players: Pursue B2B procurement platform integrations in India where invoice financing APIs attach to enterprise resource planning workflows with minimal incumbent saturation. Voice commerce integration for smart speaker ecosystems represents the most penetrable origination channel lacking established platform control. Developer-first go-to-market positioning accelerates adoption among direct-to-consumer brands without physical retail footprints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among banking-licensed platforms combining merchant relationships with deposit-taking infrastructure. Long-term viability centers on regulatory capital efficiency rather than pure origination velocity. Acquisition target archetype: decision-engine specialists with EU AI Act compliance documentation already complete. The signal to watch is merchant switching frequency as procurement departments consolidate vendor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Banking License Acquisition | Deposit-taking authority in Sweden or Germany reduces funding spreads and insulates from capital market disruptions. |
| Voice Commerce Integration | Smart speaker ecosystems create novel origination channels without screen-based authentication requirements. |
| Edge Computing Expansion | Sub-500 millisecond response times across multiple availability zones meet enterprise marketplace demands. |
| EU AI Act Compliance Architecture | Explainable model ensembles satisfy algorithmic transparency mandates for automated underwriting decisions. |
| SMB Working Capital Embedding | Invoice financing APIs attach to enterprise resource planning workflows in underpenetrated B2B procurement platforms. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, platform technical documentation, and merchant procurement databases. Conversations with embedded lending platform executives, merchant payments directors, alternative data providers, and banking partnership leads inform competitive positioning assessments. Secondary sources include Consumer Financial Protection Bureau oversight frameworks, EU AI Act implementation guidance, Financial Conduct Authority affordability assessment rules, and Reserve Bank of India digital lending circulars. Bottom-up merchant adoption modeling triangulates against top-down market sizing from transaction volume proxies.
Forecast inputs span service type penetration curves, integration level deployment costs, end-user platform scale effects, and technology compliance burden trajectories. Segmentation dimensions modeled encompass service type, integration architecture, end-user category, and decision-engine technology maturity. CAGRs derive from logistic adoption curves fitted to merchant checkout integration timelines and open banking API proliferation patterns. Capital cost volatility and regulatory licensing timelines constitute industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in central bank rate movements and warehouse credit line pricing would shift the trajectory. Forecasts reflect assumptions regarding merchant switching cost stickiness and regulatory distinction between merchant-facilitated credit and regulated lending activity. Quarterly review of merchant procurement RFP specifications and national licensing requirement changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Factoring Market