
 Advanced Authentication in Financial Services Market | 2026-2036
Advanced Authentication in Financial Services Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Authentication in Financial Services Market Insights
Behavioral biometrics is recalibrating authentication economics by reducing reliance on static credential resets and hardware token replacement cycles. Mastercard leverages its network-scale transaction data to anchor risk-based authentication decisions across issuing banks. Thales competes through dedicated cryptographic hardware and secure element manufacturing that sustains high-assurance environments for tier-one financial institutions.
Advanced authentication in financial services encompasses identity verification technologies that combine possession, inherence, and knowledge factors to validate user legitimacy during account access or transaction authorization, typically operating with sub-second latency thresholds and FIDO2 cryptographic protocol compliance. Biometric methods dominate current deployment value as fingerprint, facial, and voice recognition systems displace OTP hardware across mobile banking channels, while passwordless architectures represent the fastest-expanding segment as FIDO Alliance standards mature and browser-native passkey support widens. Cloud-based deployment models capture expanding margin pools by converting capital-intensive on-premise identity infrastructure into recurring subscription revenue with faster integration timelines.
PCI DSS mandates govern payment authentication architecture for card-issuing institutions, NIST SP 800-63 frameworks shape federal banking contractor requirements, and GDPR data minimization principles constrain biometric data retention policies across European operations. These regulatory layers collectively elevate compliance-certified vendors while disqualifying point solutions lacking audit-ready documentation. Stakeholders must monitor FIDO Alliance specification evolution and central bank digital currency authentication requirements as these will determine next-generation procurement criteria.
Market Dynamics
Passwordless authentication architectures are compressing hardware token replacement cycles while FIDO2 protocol maturation forces incumbent vendors to abandon legacy credential stacks or face displacement.
Growth Catalysts
- PSD2 Strong Customer Authentication:European banks must deploy multi-factor verification for electronic payments, mandating biometric or possession-based methods that accelerate procurement of certified authentication platforms.
- Cloud-native identity infrastructure:Financial institutions are migrating from on-premise directories to subscription-based authentication services, converting capital expenditure into recurring revenue relationships with faster deployment timelines.
- Behavioral biometrics integration:Continuous authentication based on keystroke dynamics and device interaction patterns reduces friction in mobile banking while maintaining PSD2 compliance thresholds.
Market Restraints
- Biometric data retention constraints:GDPR Article 9 restrictions on processing special category data force European banks to implement shorter retention windows and explicit consent mechanisms, increasing compliance architecture costs.
- Hardware security module concentration:Production of FIPS 140-2 certified cryptographic processors concentrates among limited semiconductor foundries, creating supply vulnerability for high-assurance deployments.
- Legacy core banking integration:Mainframe-based authentication protocols in tier-one institutions resist API-based modernization, extending implementation timelines and requiring middleware layers.
Strategic Opportunities
- Central bank digital currency authentication:Pilot programs for retail CBDC wallets in multiple jurisdictions will require novel cryptographic identity binding, creating first-mover advantage for FIDO-certified vendors.
- Voice biometric expansion:Contact center authentication in commercial banking segments remains underpenetrated by behavioral methods, offering white space for passive verification during natural conversation flows.
- NIST SP 800-63-4 alignment:Updated federal digital identity guidelines emphasizing phishing-resistant authenticators create procurement tailwinds for federal banking contractors and their technology suppliers.
Industry Challenges
- Cryptographic engineering talent scarcity:FIDO protocol implementation and secure enclave development require specialized skill sets that command premium compensation and extend hiring timelines.
- Cross-border data sovereignty:Biometric template storage must satisfy divergent national requirements, complicating cloud architecture for multinational banking groups operating across European and Middle Eastern jurisdictions.
- Interoperability certification delays:FIDO Alliance conformance testing bottlenecks slow product release cycles, particularly for vendors seeking Level 2+ authenticator certifications required by regulated financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Authentication in Financial Services Market |
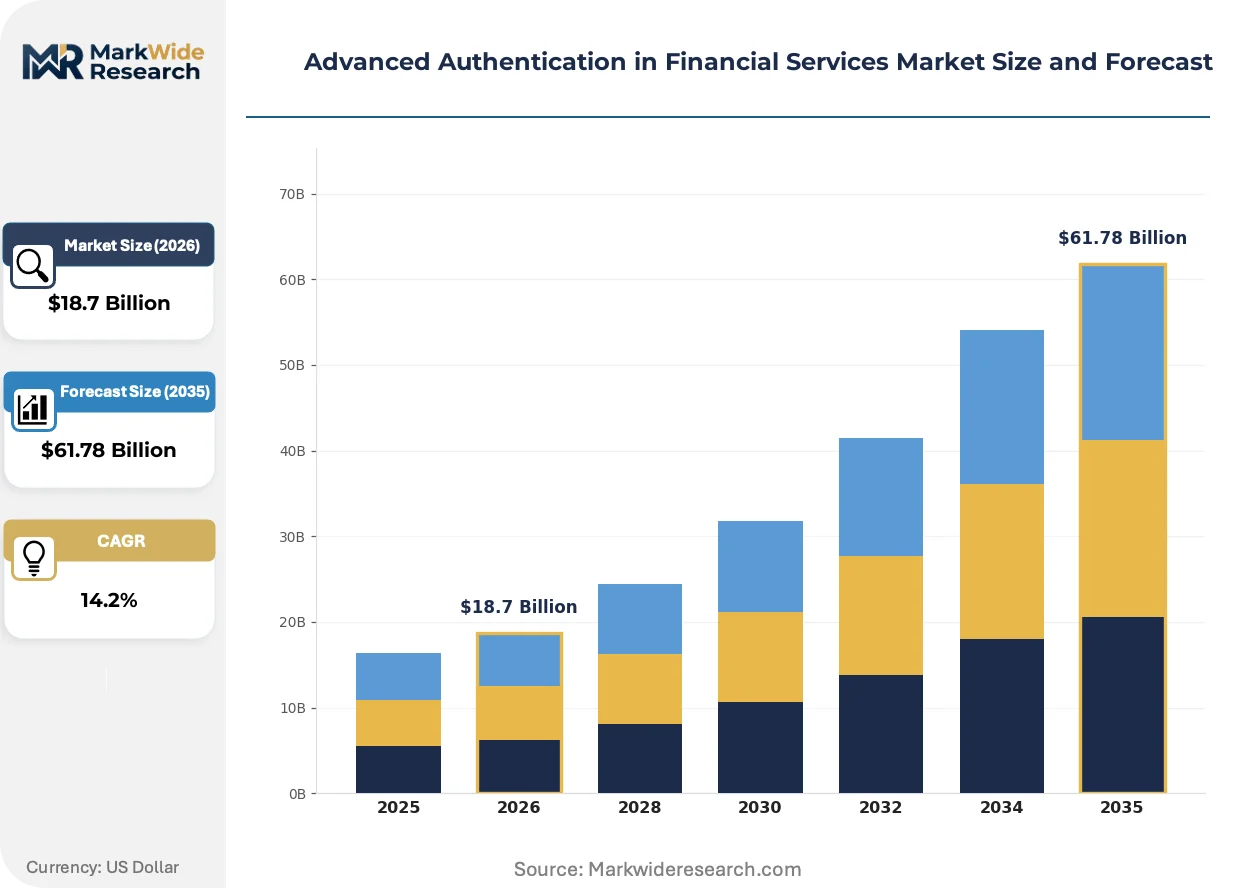
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Method: Biometric, Passwordless, OTP, Token-Based Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Service End User Type: Banks, Insurance Companies, Investment Firms, Credit Unions Compliance Standard: PCI DSS, GDPR, ISO 27001, NIST |
| Companies Covered | Mastercard, Fujitsu, Thales, Secur Envoy Ltd, Okta, Ping Identity, Broadcom Inc., Dell Inc., NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Authentication in Financial Services Market Trends and Innovations
Authentication economics are pivoting from credential management toward continuous risk assessment, embedding verification into transaction flows rather than gating access at session initiation.
Passkey architectures built on FIDO2 standards are expanding into retail mobile banking channels, replacing SMS one-time passwords and hardware tokens. Tier-one issuers in the United States and United Kingdom are piloting device-bound credentials that synchronize across ecosystems, reducing help desk password reset volume while maintaining phishing resistance. This shift is compressing revenue pools for traditional OTP hardware manufacturers and redirecting procurement budgets toward identity platform subscriptions.
GDPR data minimization principles and the EU AI Act's biometric classification requirements are reshaping European deployment architectures. Financial institutions must now implement purpose-limited biometric processing with explicit consent trails and algorithmic bias auditing, elevating compliance-certified vendors while disqualifying point solutions lacking audit-ready documentation. German and French regulators are enforcing stricter documentation standards than baseline EU requirements, creating sub-regional procurement complexity.
Commercial banking clients are unbundling authentication from core banking contracts, issuing separate RFPs for identity-as-a-service platforms with API-first integration models. This procurement fragmentation favors specialized vendors with modern architecture over incumbent core banking providers, particularly in the United Kingdom where open banking APIs have normalized modular technology sourcing. Treasury and cash management segments show the strongest unbundling momentum, driven by CFO demands for real-time visibility into authentication event logs.
Advanced Authentication in Financial Services Market Segmentation
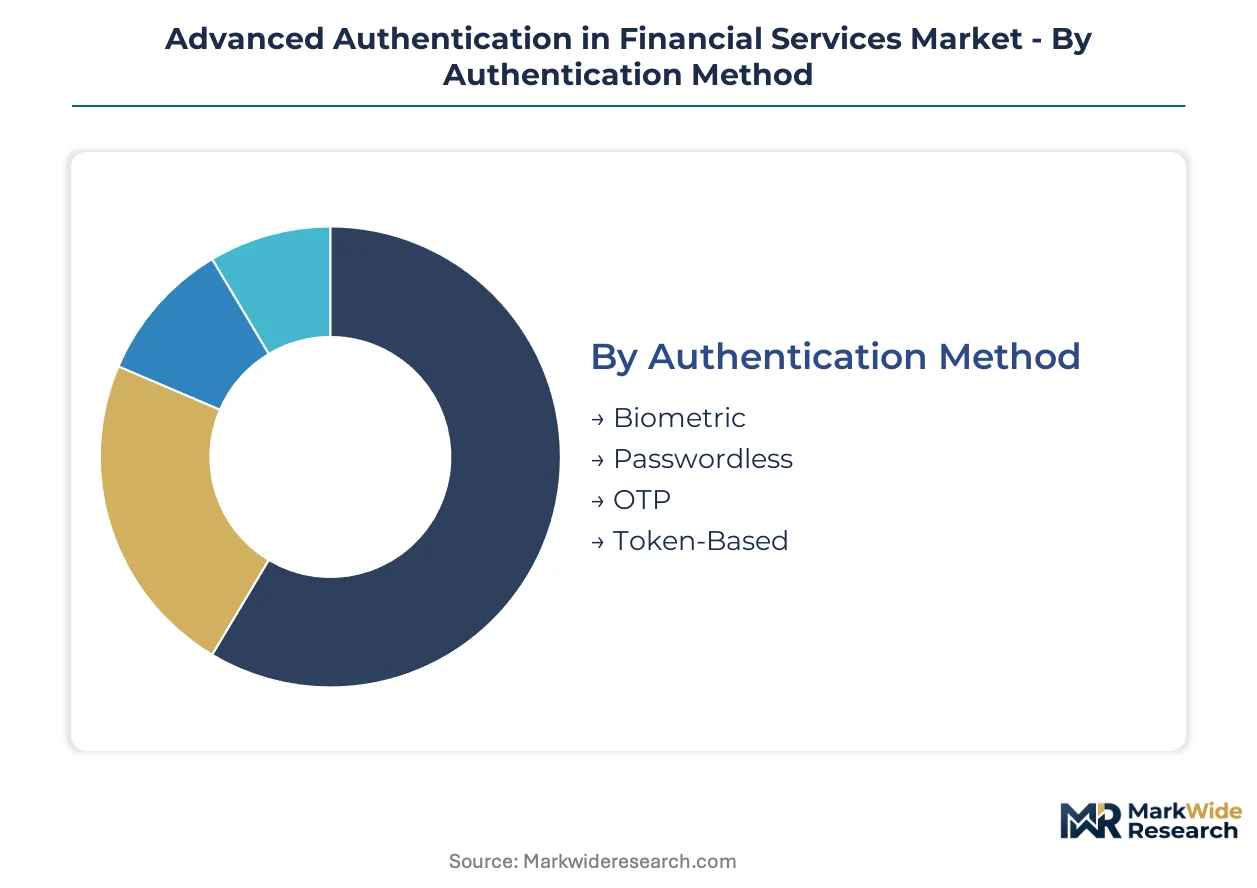
Authentication procurement in financial services fragments across method sophistication, infrastructure ownership, institutional scale, and regulatory jurisdiction. Each segmentation dimension carries distinct margin profiles and vendor qualification requirements that shape competitive positioning.
Authentication Method:
Integration depth varies sharply—biometric and passwordless systems embed directly into mobile application architectures, while OTP and token methods often operate as standalone verification layers requiring separate hardware or messaging infrastructure.
- Biometric:Fingerprint, facial, and voice recognition systems leverage device-native sensors and secure enclaves for template matching. Demand concentrates in retail mobile banking across the United States and United Kingdom, driven by PSD2 SCA mandates and consumer friction reduction targets.
- Passwordless:FIDO2 passkey architectures eliminate credential storage through public-key cryptography bound to authenticator hardware. German and French financial institutions are deploying these for corporate treasury portals, where help desk cost reduction justifies migration complexity.
- OTP:Time-synchronized codes delivered via SMS or dedicated hardware tokens retain presence in legacy commercial banking workflows.
- Token-Based:Physical and soft token generators persist in high-assurance environments requiring air-gapped verification paths.
Volume placements concentrate in Biometric; the faster expansion belongs to Passwordless.
Deployment Model:
Cost tier stratification separates capital-intensive infrastructure ownership from recurring subscription models, with hybrid architectures capturing mid-market institutions seeking staged cloud migration.
- Cloud-Based:Multi-tenant identity platforms deliver API-first authentication with sub-second latency SLAs and automatic FIDO specification updates. United States regional banks and United Kingdom challenger banks are adopting these to bypass mainframe integration bottlenecks.
- Hybrid:Sensitive credential operations remain on-premise while policy management and analytics shift to cloud instances. German universal banks favor this architecture for GDPR data residency compliance.
- On-Premise:Dedicated identity infrastructure persists in tier-one institutions with legacy core banking dependencies.
- Managed Service:Outsourced authentication operations with vendor assumption of compliance certification burden.
Cloud-Based captures the largest procurement volume; Hybrid architectures are climbing the fastest as regulatory clarity improves.
End User Type:
Customer type determines authentication complexity thresholds—retail-facing institutions prioritize frictionless mobile experiences while commercial segments demand granular audit trails and delegated authorization hierarchies.
- Banks:Universal, retail, and commercial banking operations span the full authentication sophistication spectrum from basic mobile biometric to multi-factor corporate treasury controls.
- Insurance Companies:Policyholder portal access and claims verification workflows drive demand for voice biometric and document-centric identity proofing.
- Investment Firms:High-value transaction authorization requires hardware-backed cryptographic signatures and trade-specific risk scoring integration.
- Credit Unions:Member-owned institutions with limited IT staff favor managed service deployments with bundled compliance support.
Banks account for dominant placement volume; Insurance Companies are gaining share fastest through fraud reduction investments.
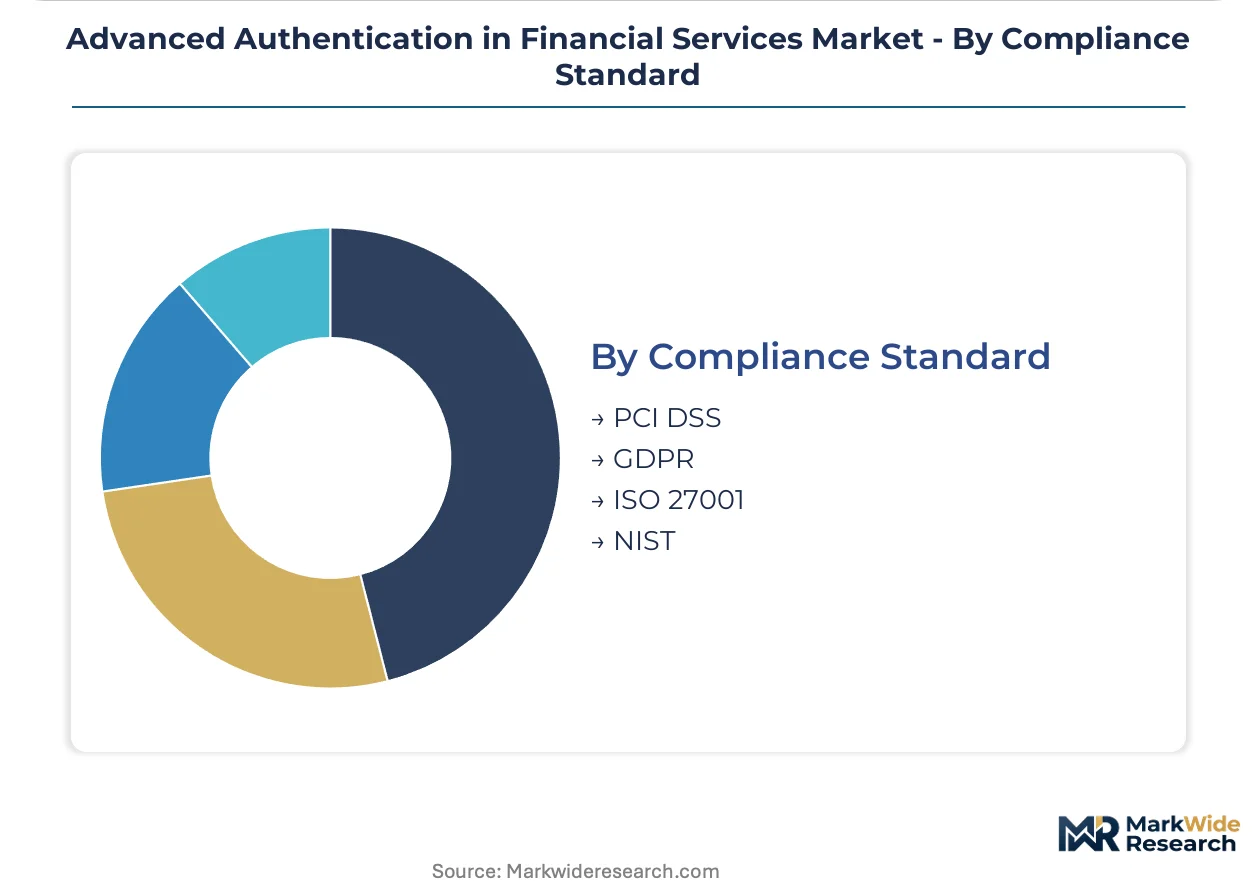
Compliance Standard:
Geographic jurisdiction dictates which certification frameworks govern procurement—European operations face GDPR biometric constraints while federal contractors in the United States navigate NIST digital identity tiers.
- PCI DSS:Payment card data protection mandates govern authentication architecture for card-issuing and acquiring institutions, requiring encrypted credential transmission and access logging.
- GDPR:European data protection law imposes purpose limitation, consent documentation, and algorithmic bias auditing on biometric processing systems.
- ISO 27001:Information security management certification provides vendor qualification shorthand for multinational banking groups standardizing procurement criteria.
- NIST:United States federal guidelines specify authenticator assurance levels with phishing resistance requirements shaping contractor technology selection.
PCI DSS governs the largest certified deployment base; NIST alignment is expanding most quickly through federal banking contractor procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services authentication procurement clusters around regulatory innovation zones where PSD2 implementation deadlines and NIST federal contracting requirements create concentrated demand spikes. Frankfurt's financial district and London's fintech corridor anchor European deployment velocity.
United States
Federal banking contractors drive NIST SP 800-63-4 alignment mandates across Washington D.C. and Northern Virginia's defense-adjacent technology corridor. The Federal Reserve's instant payment infrastructure modernization accelerates phishing-resistant authenticator procurement. New York's tier-one institutions pilot device-bound passkey synchronization across retail mobile channels.
Germany
BaFin supervisory requirements enforce stricter documentation standards than baseline EU mandates for biometric data processing. Frankfurt's universal banks favor hybrid cloud architectures that keep credential operations on-premise while shifting analytics to cloud instances. Munich's insurance conglomerates invest in voice biometric contact center deployments.
United Kingdom
Open Banking APIs normalized modular identity sourcing, unbundling authentication from core banking contracts. London's challenger banks adopt multi-tenant identity platforms to bypass mainframe integration bottlenecks. The Financial Conduct Authority's operational resilience deadlines compress procurement timelines for treasury management segments.
France
CNIL enforcement of GDPR Article 9 special category data restrictions forces shorter biometric retention windows. Paris-based commercial banks issue separate RFPs for identity-as-a-service platforms with API-first integration. The Autorité de Contrôle Prudentiel et de Résolution mandates algorithmic bias auditing for facial recognition deployments.
Japan
METI digital identity framework pilots create procurement pathways for FIDO2-certified vendors in Tokyo's financial district. Regional banks facing IT staff constraints favor managed service deployments with bundled compliance support. Osaka's insurance sector expands document-centric identity proofing for policyholder portals.
Advanced Authentication in Financial Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with network-scale transaction data aggregators commanding premium positioning against hardware-centric cryptographic vendors. The vendor base stratifies into three tiers: global payment networks with proprietary risk engines, dedicated identity platform specialists with API-first architectures, and diversified technology conglomerates with secure element manufacturing capabilities. Consolidation pressure intensifies as FIDO2 protocol maturation forces abandonment of legacy credential stacks. Strategic moves concentrate on cloud-native identity infrastructure acquisitions and cryptographic hardware supply chain vertical integration.
Within the payment network tier, Mastercard anchors risk-based authentication decisions through transaction data scale. Thales occupies a position exemplifying dedicated cryptographic hardware manufacturing for high-assurance environments. Fujitsu represents the diversified technology conglomerate archetype with secure element integration capabilities.
| Leading Market Players |
|---|
| Mastercard |
| Fujitsu |
| Thales |
| Secur Envoy Ltd |
| Okta |
| Ping Identity |
| Broadcom Inc. |
| Dell Inc. |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
PSD2 Strong Customer Authentication mandates across European banking groups have compressed procurement timelines for FIDO2-certified platforms, forcing hardware security module foundries in Taiwan and Germany to prioritize long-term contracts over spot orders and elevating pricing for expedited delivery slots.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to FIPS 140-2 Level 3 cryptographic processors where tier-one institutions face regulatory deadline pressure. Three-tier pricing structure across certified-premium, standard-compliance, and basic-utility levels tracks authentication assurance tier and GDPR audit documentation depth. Cost compression in standard tiers is intensifying because cloud-native identity platforms displace on-premise hardware bundles. Regional banks and credit unions exhibit highest price sensitivity due to constrained IT procurement budgets, while federal banking contractors in the United States show lowest sensitivity given NIST mandate non-negotiability.
Supply Chain Analysis
Dual-sourcing requirements from United States and United Kingdom financial institutions mandate qualification of at least two FIDO Alliance-certified authenticator vendors, stretching conformance testing capacity at accredited laboratories. Semiconductor fabrication for secure elements concentrates in Taiwan, South Korea, and Germany, drawing from silicon wafers, cryptographic IP cores, and FIPS-certified packaging substrates. Single-source vulnerability persists for advanced process node secure enclaves where only two foundries maintain qualified production lines. Distribution runs through direct vendor relationships with tier-one banks and value-added resellers serving mid-market institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced authentication procurement operates as a cost-of-compliance market where GDPR Article 9 biometric processing restrictions and FIDO Alliance certification requirements create substantial barrier-to-entry moats favoring audit-ready incumbent vendors over point-solution challengers.
For Market Incumbents: Anticipate displacement pressure from cloud-native identity platforms by accelerating API-first architecture roadmaps and securing FIDO2 Level 3 authenticator certifications ahead of NIST SP 800-63-4 finalization. Prioritize backward integration into cryptographic hardware supply chains to reduce exposure to Taiwan foundry concentration. Defensive consolidation through managed service capability acquisition addresses mid-market credit union demand for bundled compliance support. For New Entrants and Emerging Players: FIDO2 passkey synchronization technology offers a technology-first wedge into commercial banking treasury segments where help desk cost reduction justifies migration complexity. White space concentrates in voice biometric contact center deployments for Munich and Paris insurance conglomerates, plus hybrid cloud identity platforms for German universal banks seeking GDPR data residency compliance. A channel partnership strategy with United Kingdom open banking infrastructure providers accelerates initial reference customer acquisition without direct enterprise sales capacity. For Investors and Strategic Acquirers: The window for entry favors API-first identity platform specialists with existing FIDO Alliance Level 2+ certifications and established European data residency architectures. Long-term viability hinges on positioning for central bank digital currency authentication procurement cycles as retail CBDC pilots advance across multiple jurisdictions. Monitor FIDO Alliance specification evolution and central bank digital currency pilot announcements as inflection indicators for next-generation procurement demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Certification Investment | Level 3 authenticator certification unlocks tier-one bank procurement eligibility under NIST guidelines. |
| Cloud-Native Platform Migration | Multi-tenant SaaS architectures convert capital expenditure into recurring revenue with faster deployment timelines. |
| Biometric Data Residency Architecture | GDPR-compliant hybrid cloud deployments capture German and French universal bank procurement mandates. |
| Voice Biometric Contact Center Integration | Passive verification during natural conversation flows addresses underpenetrated commercial banking segments. |
| Managed Service Capability Buildout | Bundled compliance support attracts credit unions and regional banks with limited internal IT staff. |
Research Methodology
Document review covered FIDO Alliance specification documents, central bank digital currency pilot announcements, and regulatory filings from BaFin, the Financial Conduct Authority, and the Federal Reserve, complemented by interviews with chief information security officers at tier-one banks, identity platform product managers, FIDO Alliance certification engineers, and procurement leads at federal banking contractors. Secondary validation drew from NIST SP 800-63 guideline revisions, PCI DSS compliance documentation, and GDPR enforcement actions from CNIL and the ICO. Bottom-up authentication deployment estimates triangulated against top-down financial services IT spending allocations.
Segmented outputs across authentication method, deployment model, end user type, and compliance standard geography were generated through the projection horizon using regression analysis of historical procurement velocity and regulatory deadline clustering. CAGRs were derived from slope analysis of adoption curve inflection points observed at PSD2 implementation milestones and NIST guideline revision cycles. Industry-specific inputs included FIDO Alliance conformance testing queue lengths, central bank digital currency pilot program announcements, and biometric hardware shipment data from secure element manufacturers.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor foundry operations, abrupt FIDO Alliance specification changes, and unanticipated GDPR enforcement pattern shifts. Forecasts reflect assumptions regarding steady regulatory deadline adherence and stable cryptographic engineering talent availability. Deviation in central bank digital currency authentication standard finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Germany Fintech Market
FinTech
Russia AI in Fintech Market
FinTech
Japan AI in Fintech Market
FinTech
Latin America AI in Fintech Market
FinTech
Financial Forecasting Software Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
AI in Fintech Market
FinTech
North America AI in Fintech Market
FinTech
Fintech Technologies Market
FinTech
Transaction Monitoring Software Market
FinTech
Robo-Advisory Services Market
FinTech
Blockchain in Fintech Market
FinTech
Vietnam Fintech Market
FinTech
Smart Advisors Market
FinTech
MENA Fintech Market
FinTech
Account Checking Software Market