
 MENA Fintech Market | 2026-2036
MENA Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Fintech Market Foresight
Multi-source vendor relationships among payment processors is consolidating as platforms seek API interoperability and unified settlement rails. Tabby leverages its buy-now-pay-later infrastructure to anchor retail credit distribution across the Gulf. Fawry sustains dominance in Egyptian bill aggregation through its agent network density. MNT-Halan competes by combining ride-hailing wallets with micro-lending in a single super-app architecture.
MENA fintech encompasses digitally native financial services infrastructure spanning payment orchestration, alternative lending, and embedded wealth tools, typically deployed via mobile-first architectures with real-time KYC verification and Sharia-compliant product structuring. Its primary commercial purpose is reducing cash dependency while extending formal credit access to underbanked populations across fragmented banking markets. Payment Processing leads transaction volume but Insurtech captures widening margin pools as regulatory frameworks mature for digital policy distribution. Blockchain solutions within Cross-Border Payments are recording the fastest adoption curve, driven by remittance corridor cost pressures between the Gulf and South Asia.
Saudi Arabia's central bank licensing regime and the UAE's VARA digital asset framework are tightening operational standards for capital reserves and consumer disclosure, directly elevating compliance costs for new entrants. Egypt's FRA and the Central Bank of Egypt jointly supervise non-bank payment providers through tiered authorization thresholds that segment market access by float size. Stakeholders must monitor how divergent national licensing timelines across Riyadh, Dubai, and Cairo reshape cross-border platform economics and partnership strategies.
Market Dynamics
API interoperability mandates from Saudi Arabia's central bank are compressing settlement timelines and forcing payment processors to consolidate vendor relationships into unified technical stacks.
Growth Catalysts
- Real-time KYC infrastructure:Biometric verification networks deployed by the UAE's VARA framework are collapsing customer onboarding from days to minutes across digital banking applicants.
- Saudi licensing regime:SAMA's digital bank authorization pathway is attracting capital commitments from regional payment platforms seeking full banking privileges.
- Agent network density:Egypt's cash-heavy retail corridors are converting to digital collection points through FRA-supervised payment provider expansion.
Market Restraints
- Capital reserve requirements:VARA's operational standards for digital asset service providers are elevating minimum float thresholds beyond mid-tier entrant capacity.
- Sharia compliance complexity:Product structuring for profit-sharing instruments requires dual legal review, extending time-to-market for credit offerings.
- Cross-border settlement fragmentation:Divergent national licensing timelines between Riyadh, Dubai, and Cairo are fragmenting unified Gulf payment rails.
Strategic Opportunities
- Egyptian underbanked segments:Micro-merchant credit scoring via alternative data streams remains undeployed outside Cairo and Alexandria urban cores.
- Blockchain-API convergence:Remittance corridors between the Gulf and South Asia are enabling real-time settlement pilots that bypass correspondent banking delays.
- Embedded wealth tools:SAMA's open banking framework is permitting retail investment distribution through non-bank super-app interfaces.
Industry Challenges
- Sharia scholar certification scarcity:Qualified advisory capacity for product approval is concentrated among a limited number of regional Islamic finance institutions.
- Legacy core banking integration:Established Gulf banks are resisting API exposure to fintech partners due to cybersecurity liability concerns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Fintech Market |
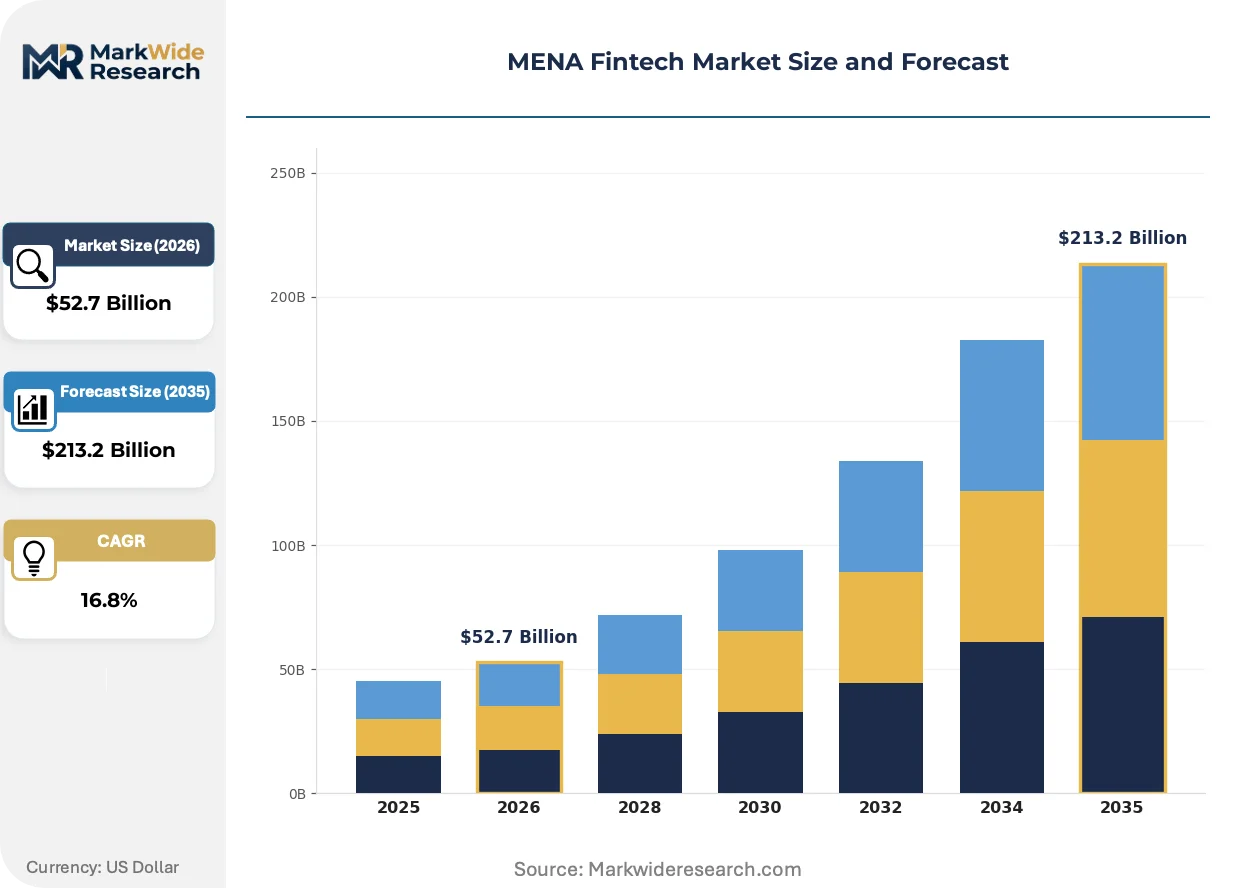
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $213.2 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Digital Banking, Investment Management, Insurtech Customer Type: Retail Investors, Small Enterprises, Corporates, Fintech Startups Technology: Blockchain, AI-Driven Analytics, Cloud Computing, Mobile Platforms Solution: Wealth Management, Peer-to-Peer Lending, Cross-Border Payments, Digital Wallets |
| Companies Covered | Tabby, Fawry, MNT-Halan, Tamara, Rasan, Wio Bank, Thndr, Paymob, STC Pay, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Fintech Market Shifts & Advancements
Payment orchestration layers are collapsing previously separate technical functions into unified middleware, compressing the vendor stack while expanding real-time capability deployment.
Embedded finance middleware is modularizing previously discrete payment, lending, and insurance functions into configurable API bundles. Retail commerce platforms across the UAE are adopting these stacks within twelve-month integration cycles. This technical architecture is modularizing the historical separation between banking and non-banking financial service delivery.
SAMA's digital bank licensing framework is tightening capital adequacy and consumer disclosure standards for new entrants. The regulatory consequence is elevating operational costs and extending authorization timelines for payment platforms seeking banking privileges. Saudi Arabia's retail credit segment is responding by consolidating partnership negotiations with incumbent banks rather than pursuing standalone licenses.
Merchant procurement of financial services is fragmenting across specialized providers rather than concentrating with single banking relationships. Small enterprises in Dubai are unbundling payment acceptance, working capital credit, and payroll services across separate platforms. This pattern is most visible in UAE retail and hospitality verticals where platform switching costs remain low.
MENA Fintech Market Segmentation
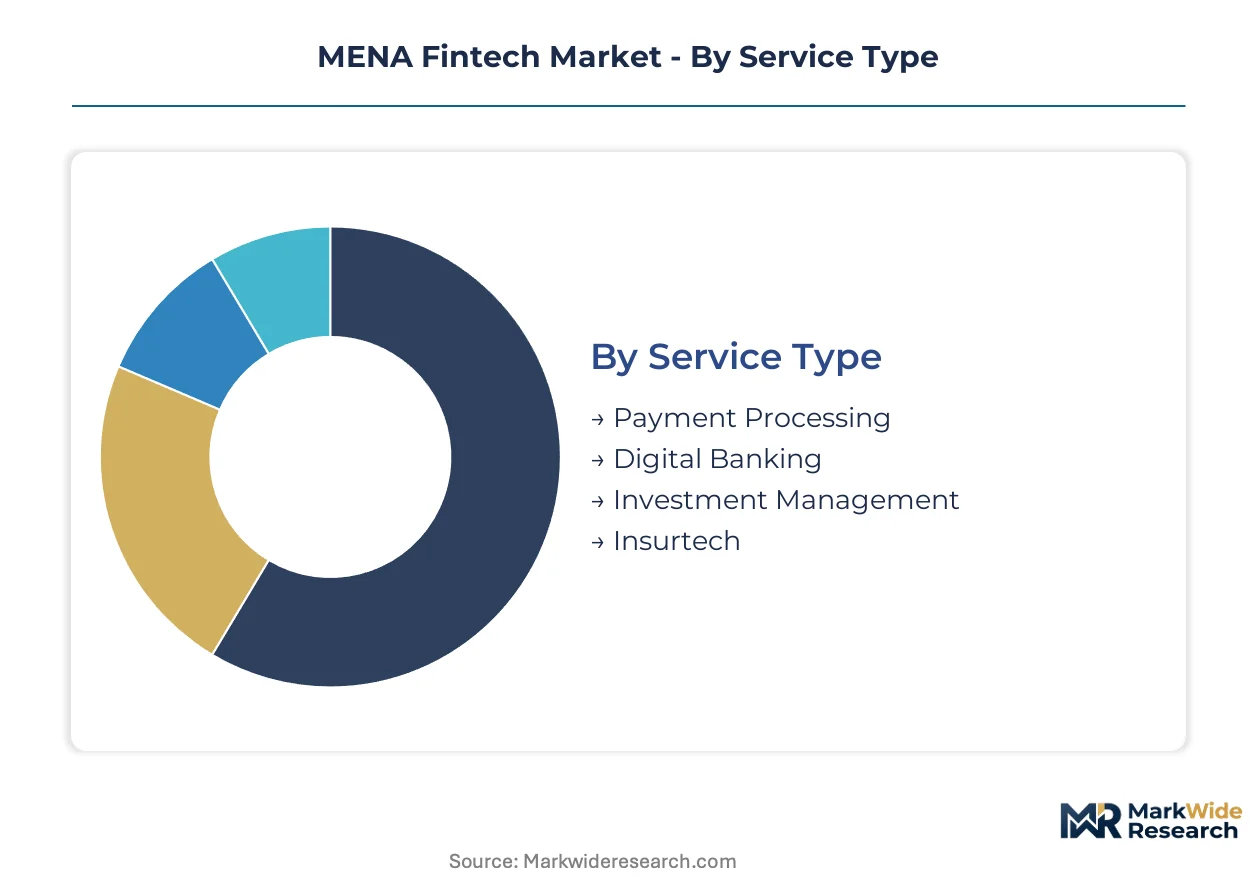
Segmentation in MENA fintech reveals how capital allocation and regulatory permissions diverge across technical architectures and customer risk profiles. Understanding these divides explains why payment processors consolidate while wealth tools fragment across licensing jurisdictions.
Service Type:
Standardization dominates payment infrastructure while customization accelerates in regulated banking and insurance verticals.
- Payment Processing:API-orchestrated transaction rails handle the majority of MENA fintech volume. Demand concentrates among Saudi small enterprises seeking unified settlement with SAMA-mandated interoperability standards.
- Digital Banking:Full-stack banking licenses from SAMA and the UAE's central bank attract capital commitments from regional platforms. Expansion is steepest in Riyadh and Dubai where regulatory sandboxes compress authorization timelines.
- Investment Management:Sharia-compliant robo-advisory tools distribute through non-bank super-app interfaces.
- Insurtech:Digital policy distribution platforms capture widening margin pools as VARA and SAMA frameworks mature for takaful products.
Most installed capacity flows through Payment Processing. Expansion is steepest in Digital Banking.
Customer Type:
Volume scales with corporate treasuries while margin concentrates in retail and startup segments requiring specialized KYC infrastructure.
- Retail Investors:Biometric verification networks deployed by VARA collapse onboarding friction for wealth and credit products. Demand concentrates in Dubai among expatriate professionals seeking cross-border remittance-linked investment tools.
- Small Enterprises:Unbundled procurement of payment acceptance, working capital credit, and payroll services fragments banking relationships. Egyptian micro-merchants outside Cairo and Alexandria remain underserved by formal credit scoring.
- Corporates:Treasury management platforms prioritize API interoperability for multi-currency liquidity operations.
- Fintech Startups:Early-stage ventures navigate tiered authorization thresholds that segment market access by float size.
Most installed capacity flows through Corporates. Retail Investors are gaining share fastest.
Technology:
Cloud and mobile architectures commoditize while blockchain and AI layers command premium integration costs.
- Blockchain:Distributed ledger infrastructure enables real-time settlement pilots bypassing correspondent banking delays in Gulf-South Asia remittance corridors. Demand concentrates in Dubai's VARA-supervised digital asset exchanges.
- AI-Driven Analytics:Alternative data streams power micro-merchant credit scoring in Egyptian cash-heavy retail corridors. Regulatory scrutiny from the FRA and Central Bank of Egypt elevates model audit requirements.
- Cloud Computing:Elastic infrastructure underpins multi-tenant fintech platforms seeking regional scale without captive data centers.
- Mobile Platforms:Super-app architectures dominate customer interface design across MENA consumer finance.
Most installed capacity flows through Mobile Platforms. Blockchain climbs the fastest.
Solution:
Wealth and lending solutions fragment across Sharia compliance requirements while payment utilities consolidate toward interoperability.
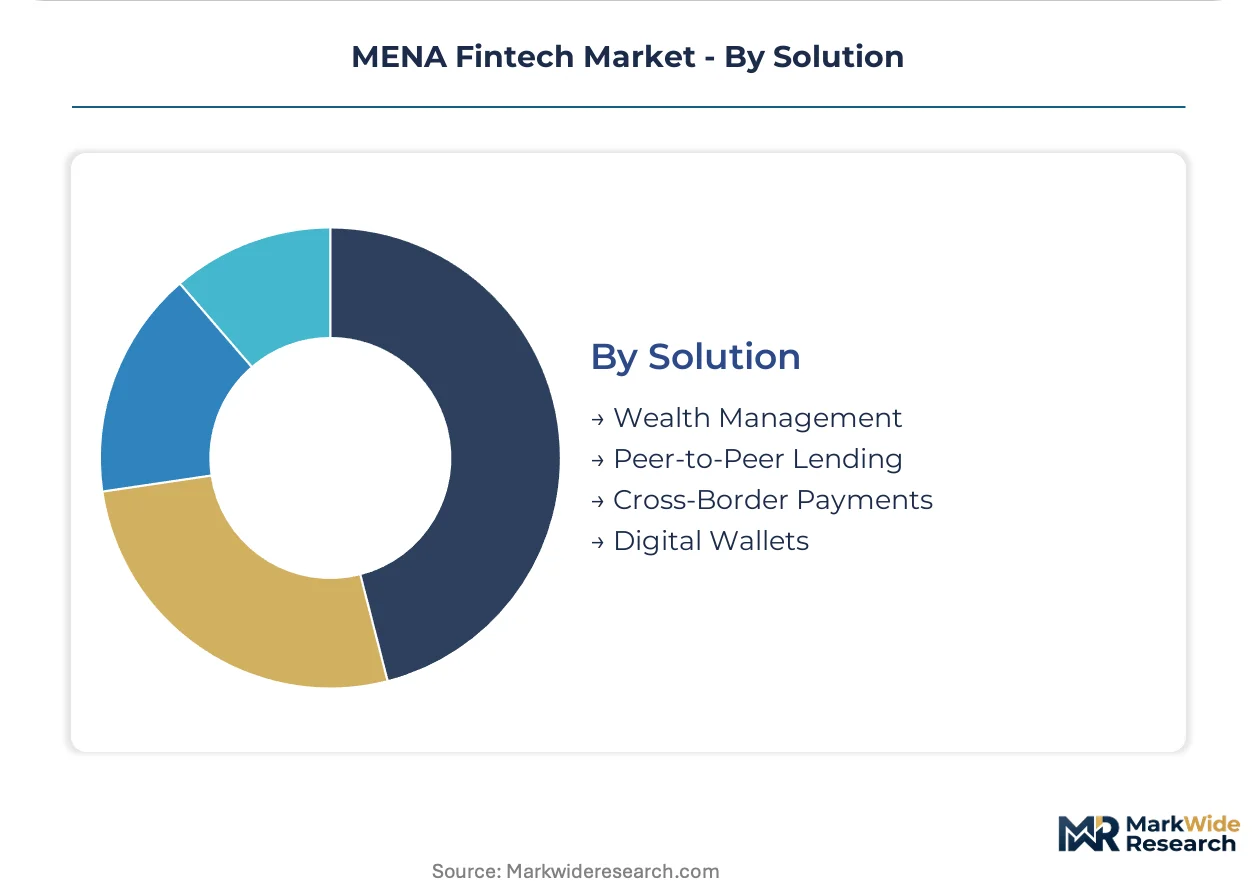
- Wealth Management:Embedded investment distribution through non-bank interfaces expands under SAMA's open banking framework. Demand concentrates among Saudi retail savers seeking profit-sharing alternatives to conventional deposits.
- Peer-to-Peer Lending:Alternative credit marketplaces face dual legal review for Sharia-compliant profit-sharing structures. Qualified scholar certification scarcity extends time-to-market for new platforms.
- Cross-Border Payments:Real-time settlement pilots leverage blockchain-API convergence to compress remittance timelines.
- Digital Wallets:Ride-hailing and retail commerce platforms integrate closed-loop payment storage with loyalty and credit features.
Most installed capacity flows through Digital Wallets. Wealth Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's regulatory sandbox environment anchors fintech innovation across the Arab world, attracting founders seeking compressed authorization timelines and unified settlement infrastructure.
United Arab Emirates
Expatriate professionals in Dubai drive demand for cross-border remittance-linked investment tools and biometric-enabled wealth products. VARA's digital asset framework elevates capital reserve requirements for new entrants. Abu Dhabi's financial free zones concentrate blockchain-API convergence pilots for real-time settlement.
Saudi Arabia
Saudi small enterprises seek unified payment settlement rails compliant with SAMA-mandated interoperability standards. SAMA's digital bank licensing pathway attracts capital commitments from regional platforms seeking full banking privileges. Riyadh's regulatory sandbox compresses authorization timelines for retail credit distribution.
Egypt
Egyptian micro-merchants outside Cairo and Alexandria remain underserved by formal credit scoring infrastructure. The FRA and Central Bank of Egypt jointly supervise non-bank payment providers through tiered authorization thresholds. Cash-heavy retail corridors in Upper Egypt convert to digital collection points through supervised payment provider expansion.
Kuwait
Corporate treasuries in Kuwait City prioritize API interoperability for multi-currency liquidity operations. The country's central bank maintains conservative licensing standards for digital banking entrants. The financial district concentrates merchant procurement fragmentation across specialized payment and payroll platforms.
MENA Fintech Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue super-app convergence and embedded finance middleware. The vendor base organizes around three strategic archetypes: buy-now-pay-later infrastructure providers, bill aggregation platforms with agent network density, and ride-hailing wallet operators combining mobility with micro-lending. Dominant competitive moves include strategic partnerships with incumbent banks and API interoperability consolidation into unified technical stacks.
Within the buy-now-pay-later archetype, Tabby and Tamara exemplify retail credit distribution models across Gulf markets. Fawry occupies a position representing bill aggregation dominance through network density. MNT-Halan anchors the super-app convergence tier, combining mobility infrastructure with financial services in a single architecture.
| Leading Market Players |
|---|
| Tabby |
| Fawry |
| MNT-Halan |
| Tamara |
| Rasan |
| Wio Bank |
| Thndr |
| Paymob |
| STC Pay |
| Others |
Supply & Pricing Matrix
Sharia scholar certification scarcity in the Gulf Cooperation Council widens pricing spreads between conventional and Sharia-compliant fintech products. Labor-cost differentials between Dubai's VARA-supervised exchanges and Cairo's FRA-regulated corridors compress margins for Egyptian payment providers while sustaining premium tiers for UAE wealth tools.
Pricing Analysis
Input-cost pass-through from compliance infrastructure dominates pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels segments by KYC automation depth and Sharia certification tier. Premium tiers command spreads for biometric-enabled onboarding and dual legal review. Price differentiation rests on VARA capital reserve thresholds and SAMA interoperability mandates. Egyptian micro-merchant segments exhibit highest price sensitivity; Saudi corporate treasuries demonstrate lowest.
Supply Chain Analysis
Workforce availability in UAE and Saudi Arabia concentrates cloud infrastructure and AI analytics development. Egypt and Jordan feed technical talent for mobile platform engineering. Raw material dependencies span biometric hardware components, distributed ledger protocols, and open banking API frameworks. Single-source vulnerability concentrates in VARA-certified compliance technology providers. Distribution runs through regional cloud hyperscalers and agent network partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is shifting toward premium specifications as SAMA's digital bank licensing elevates operational standards and compresses authorization timelines for well-capitalized entrants.
For Market Incumbents: Deploy API interoperability consolidation to compress settlement timelines and unify technical stacks. Defensive moves center on backward integration into biometric KYC infrastructure and exclusive partnerships with Sharia advisory institutions. The threat vector is emerging super-app operators combining mobility with micro-lending. Channel control through agent network density in Egyptian corridors remains critical. For New Entrants and Emerging Players: The price-point gap between premium biometric-enabled platforms and economy-tier agent-based models creates entry latitude. White-space targets concentrate in Egyptian micro-merchant credit scoring outside Cairo and Alexandria, and blockchain-API convergence for Gulf-South Asia remittance corridors. The most penetrable segment is underbanked small enterprises seeking unbundled payment and payroll services. Go-to-market angles should leverage alternative data streams for credit scoring bypassing traditional bureau dependencies. For Investors and Strategic Acquirers: Regional payment platforms seeking full banking privileges are the most active acquirer in this space. Long-term viability hinges on regulatory sandbox access and capital adequacy positioning. Acquisition target archetypes include bill aggregation platforms with dense agent networks and ride-hailing wallet operators with embedded lending infrastructure. The signal to watch is SAMA authorization timeline compression for digital bank licensing applicants.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Consolidation | SAMA mandates compress settlement timelines and force unified technical stacks across Saudi payment processors. |
| Sharia Certification Investment | Dual legal review requirements extend time-to-market for profit-sharing credit products in Gulf markets. |
| Biometric KYC Infrastructure Deployment | VARA frameworks collapse onboarding friction for Dubai expatriate professionals seeking wealth tools. |
| Agent Network Expansion | FRA-supervised payment providers convert cash-heavy Upper Egypt retail corridors to digital collection points. |
| Blockchain-API Convergence Pilots | Distributed ledger infrastructure bypasses correspondent banking delays in Gulf-South Asia remittance corridors. |
Research Methodology
Multiple input streams — primary interviews with fintech CTOs and platform engineers, regulatory filings from SAMA and VARA, and secondary validation through SEC disclosures and customs data — were reconciled to construct market estimates. Stakeholder roles included digital banking executives, Sharia advisory scholars, payment processor technical leads, and FRA compliance officers. Secondary sources encompassed central bank licensing databases, open banking framework documentation, and hyperscaler capex disclosures. Bottom-up transaction volume modeling and top-down regulatory capacity analysis were triangulated.
Data-stream reconciliation across service type, customer segment, technology layer, and geographic jurisdiction anchored the analytical framework. Segmentation dimensions modeled deployment architecture, regulatory authorization tier, and Sharia compliance status. CAGRs were derived from fitted growth curves calibrated to licensing timeline data and capital commitment announcements. Industry-specific inputs included SAMA digital bank authorization pipeline tracking and VARA operational standard evolution.
Caveats apply where regulatory timeline delays, Sharia scholar certification bottlenecks, or cross-border settlement fragmentation could materially shift the outlook. Forecasts reflect assumptions about interoperability mandate enforcement and open banking framework adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Australia Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Europe AI in Fintech Market
FinTech
Saudi Arabia Fintech Market
FinTech
Autonomous Finance Market
FinTech
China Fintech Market
FinTech
Account Checking Software Market
FinTech
Smart Financial Solutions Market
FinTech
Europe Embedded Finance Market
FinTech
US AI in Fintech Market
FinTech
Europe Fintech Cloud Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Germany Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
Global Saas Spend Management Software Market
FinTech
Financial Consolidation Software Market