
 Digital Analytics Solutions Market | 2026-2036
Digital Analytics Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Analytics Solutions Market Analysis
India's IT services corridor is pivoting toward dedicated analytics delivery centers to capture enterprise outsourcing contracts. Microsoft Corporation leverages its Azure data ecosystem to anchor cloud-based deployments across Fortune 500 accounts. IBM Corporation competes through specialized Watson analytics modules targeting risk management applications in regulated industries. Google sustains leadership in web analytics through tight integration with its advertising technology stack.
Digital analytics solutions encompass software platforms and services that ingest, process, and visualize structured and unstructured data streams to generate actionable business intelligence, typically operating across sub-second query response thresholds and petabyte-scale data lakes. These systems serve commercial and industrial users by enabling predictive modeling, real-time decision automation, and cross-channel performance measurement. Cloud-based deployment now leads solution type distribution as enterprises retire on-premise data warehouses, while predictive analytics represents the fastest-expanding solution category as organizations embed machine learning into operational workflows. Customer insights applications command the deepest margin pools due to recurring subscription structures and high switching costs among retail and finance end users.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape product architecture for vendors serving European enterprises. The SEC's climate disclosure rules and comparable FERC reporting obligations in the United States are forcing finance and energy sector buyers to expand ESG analytics capabilities. Stakeholders must monitor how fragmented regulatory timelines across jurisdictions affect platform standardization strategies and localization investment priorities.
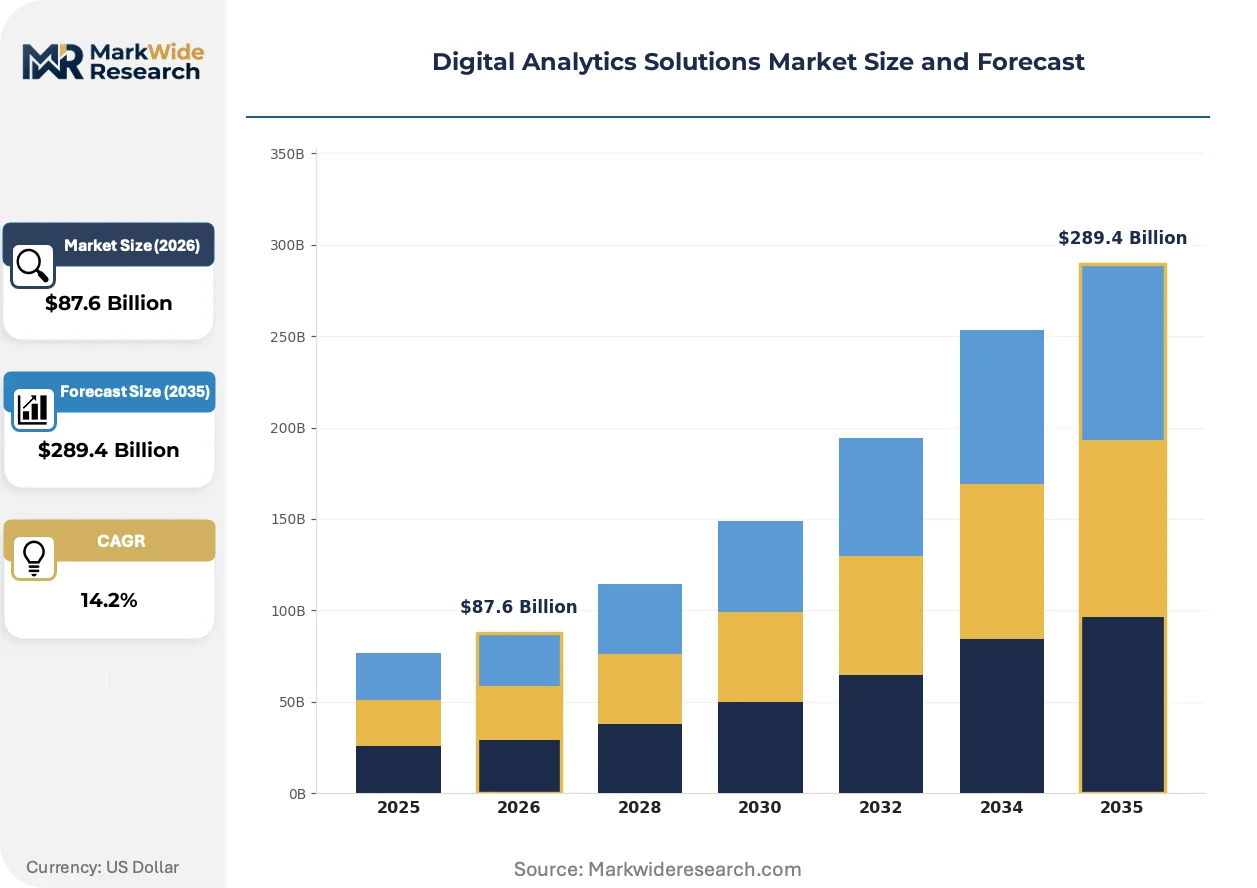
Market Dynamics
Cloud migration mandates under the EU AI Act and comparable data governance frameworks are accelerating compliance-driven procurement of digital analytics platforms across enterprise IT estates.
Growth Catalysts
- EU AI Act cloud mandates:Algorithmic transparency requirements are forcing European enterprises to replace legacy on-premise data warehouses with compliant cloud-native architectures.
- Retail customer insights platforms:North American and European retail chains are unifying online and offline behavioral data to enable real-time personalization across physical and digital touchpoints.
- Predictive analytics embedding:Machine learning operationalization into supply chain and fraud detection workflows is creating sustained platform demand from finance and logistics sectors.
Market Restraints
- GDPR data residency costs:Strict localization requirements for EU personal data are inflating infrastructure expenditure and complicating multi-region deployments.
- Cloud vendor concentration:Dominance of hyperscale providers in storage and compute layers creates dependency risk and limits negotiation leverage for enterprise buyers.
- Real-time query latency:Sub-second response thresholds for operational analytics demand specialized hardware investments that mid-market buyers struggle to justify.
Strategic Opportunities
- India analytics delivery centers:IT services corridors in Bangalore and Hyderabad are capturing enterprise outsourcing contracts through dedicated analytics talent pools.
- ESG analytics regulatory tailwinds:SEC climate disclosure rules and FERC reporting obligations are forcing finance and energy buyers to expand sustainability measurement capabilities.
- Edge-to-cloud convergence:Integration of IoT sensor streams with centralized data lakes is opening new deployment architectures for manufacturing and logistics operators.
Industry Challenges
- Machine learning engineering scarcity:Shortage of practitioners capable of deploying production-grade predictive models is delaying enterprise AI roadmaps.
- Legacy system integration friction:Mainframe and ERP data extraction complexity is extending implementation timelines and eroding projected ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Analytics Solutions Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Solution Type: Web Analytics, Social Media Analytics, Predictive Analytics, Mobile Analytics End User: Retail, Finance, Healthcare, Telecommunications Application: Customer Insights, Marketing Optimization, Risk Management, Performance Measurement |
| Companies Covered | Microsoft Corporation, IBM Corporation, AWS, Inc., Oracle Corporation, SAP SE, Google, Accenture, Capgemini, Tata Consultancy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Analytics Solutions Market Emerging Trajectories
Real-time decision automation and cross-channel measurement capabilities are redefining competitive requirements for analytics vendors serving enterprise buyers.
Streaming analytics infrastructure is expanding into operational technology environments. Manufacturing and logistics operators are adopting continuous query engines to monitor equipment health and inventory positions. This capability compression is collapsing the latency gap between data generation and actionable insight.
The EU AI Act algorithmic transparency framework is reshaping product architecture for vendors serving European enterprises. Risk classification requirements for high-stakes automated decisions are forcing explainability features into core platform design. Financial services and healthcare applications in Germany and France are experiencing the most intensive compliance engineering cycles.
Subscription-based platform procurement is displacing perpetual license models among mid-market buyers. Finance and retail segments are leading this transition, trading upfront capital expenditure for operational flexibility. United States enterprise procurement teams are most aggressively negotiating consumption-based pricing structures.
Digital Analytics Solutions Market Segmentation
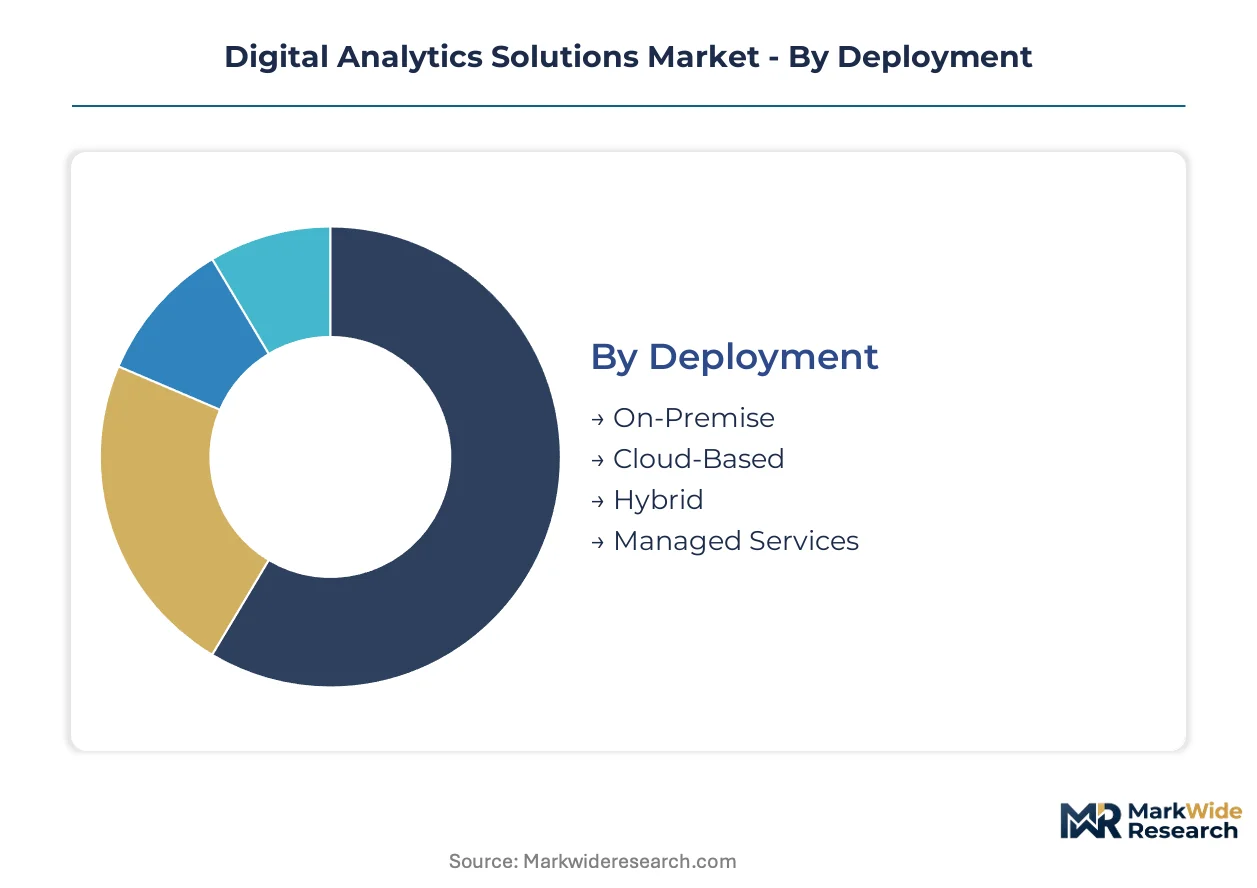
Deployment architecture, solution specialization, end-user verticals, and application focus define how vendors configure pricing, implementation timelines, and support structures. Each segmentation axis reveals distinct margin profiles and competitive intensity patterns across the digital analytics value chain.
Deployment:
Standardization dominates at the infrastructure layer while customization requirements intensify at the integration and governance tiers.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute pools enable sub-second query response for petabyte-scale workloads. United States enterprise procurement teams are negotiating consumption-based pricing structures as cloud migration mandates from the SEC and EU AI Act accelerate compliant architecture procurement.
- Hybrid:Split processing between edge nodes and centralized lakes addresses GDPR data residency requirements while preserving real-time operational capabilities. German automotive and French healthcare buyers are driving specialized compliance engineering cycles for this architecture.
- On-Premise:Dedicated hardware stacks retain foothold in classified government and defense environments with air-gapped security requirements.
- Managed Services:Third-party operational control over infrastructure and model maintenance appeals to mid-market buyers lacking internal ML engineering capacity.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulatory fragmentation forces multi-jurisdiction data strategies.
Solution Type:
Cost tier stratification separates commodity measurement tools from premium predictive platforms with embedded machine learning operationalization.
- Predictive Analytics:Production-grade ML pipelines for fraud detection and demand forecasting require specialized feature engineering and model governance. Finance sector buyers in the United States and logistics operators across North American supply chains are embedding these capabilities into operational workflows.
- Web Analytics:Session tracking and conversion funnel visualization form the baseline measurement layer with tight integration to advertising technology stacks. Retail chains across North America and Europe unify online and offline behavioral data through these platforms.
- Social Media Analytics:Sentiment extraction and influencer identification tools serve brand monitoring and crisis response functions.
- Mobile Analytics:In-app event streams and push notification optimization address retention and monetization for application publishers.
Predictive Analytics commands the deepest margin pools due to recurring subscription structures and high switching costs. Web Analytics maintains the broadest installed base across enterprise and mid-market accounts.
End User:
Customer lifetime value concentration determines platform investment intensity across verticals with divergent data maturity and regulatory exposure.
- Finance:Risk-weighted asset calculations, anti-money laundering surveillance, and SEC climate disclosure reporting demand explainable models with audit trails. United States banks and asset managers are expanding ESG analytics capabilities under FERC and SEC obligations.
- Retail:Real-time personalization engines and inventory optimization systems unify physical and digital touchpoints. North American and European chains are capturing outsourcing contracts through dedicated analytics delivery centers in India.
- Healthcare:HIPAA-compliant patient journey analytics and clinical trial optimization require specialized data governance architectures.
- Telecommunications:Network performance monitoring and churn prediction models process subscriber-level event streams at massive scale.
Finance and Retail together account for the majority of platform revenue. Healthcare is climbing fastest as HIPAA-compliant cloud architectures mature.
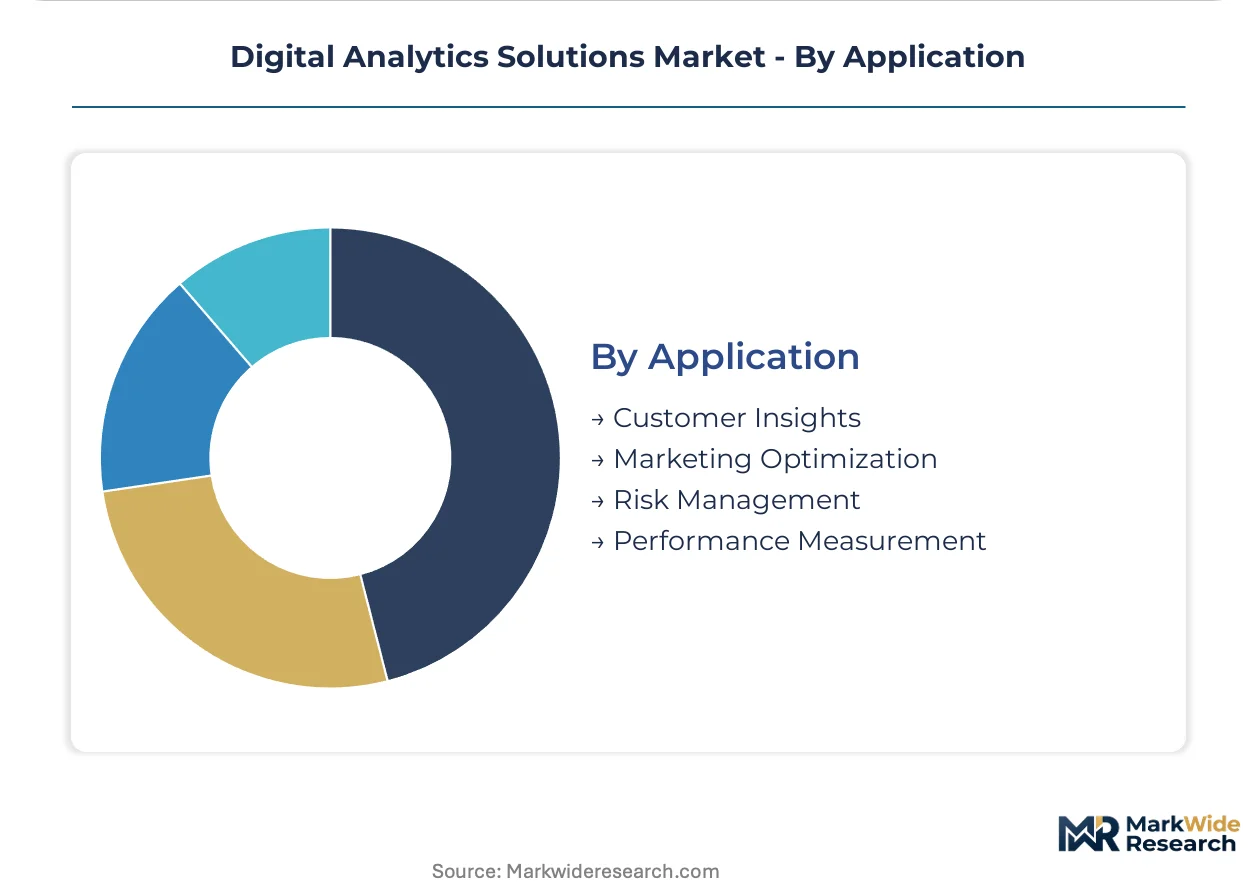
Application:
Maturity gradients separate established measurement disciplines from emerging automation use cases with higher implementation complexity.
- Customer Insights:Unified profile construction across online and offline channels enables segmentation and personalization at individual resolution. Retail and finance end users generate recurring subscription demand due to high switching costs and continuous data refresh requirements.
- Risk Management:Credit scoring, fraud detection, and operational risk quantification embed ML models into regulatory reporting workflows. United States and European regulated industries are forcing explainability features into core platform design under EU AI Act and SEC mandates.
- Marketing Optimization:Media mix modeling and attribution analysis allocate spend across digital and traditional channels.
- Performance Measurement:KPI dashboards and executive reporting consolidate metrics across business units for strategic planning cycles.
Customer Insights captures the largest share of recurring platform spend. Risk Management is gaining share fastest as compliance engineering cycles intensify across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises outspend German counterparts on analytics software by a substantial margin, while India's services corridor captures outsourcing flows from both markets. Cloud migration mandates and compliance engineering cycles are reshaping procurement patterns across these three centers.
United States
Enterprise IT modernization budgets and SEC climate disclosure rules drive platform investment. FERC reporting obligations force finance and energy buyers to expand ESG analytics capabilities. The New York Metro and Greater Boston clusters host concentrated procurement teams negotiating consumption-based pricing structures.
Germany
Automotive and industrial machinery producers demand explainable models for quality control and predictive maintenance workflows. The EU AI Act risk classification requirements force compliance engineering cycles into core platform design. Bavaria and Baden-Württemberg anchor specialized delivery centers serving Mittelstand manufacturers.
India
IT services corridors in Bangalore and Hyderabad pivot toward dedicated analytics delivery centers to capture enterprise outsourcing contracts. RBI data localization guidelines and SEBI reporting standards shape vendor selection criteria. The Karnataka-Telangana corridor concentrates talent pools for machine learning engineering roles.
United Kingdom
Financial services firms in London embed predictive models into anti-money laundering and credit scoring workflows. GDPR and FCA operational resilience requirements mandate audit trails for algorithmic decision systems. The London-Southeast cluster dominates procurement for customer insights platforms serving retail banking.
France
Healthcare and luxury retail operators deploy patient journey analytics and unified customer profile systems. CNIL enforcement of GDPR algorithmic transparency rules drives explainability feature adoption. The Île-de-France region concentrates vendor engineering resources for EU compliance architectures.
Digital Analytics Solutions Market Vendor Landscape
United States producers anchor the hyperscale cloud tier; European specialists hold positions in regulated industry applications. Market structure consolidates around three to four dominant platform ecosystems with long-tail fragmentation in vertical-specific modules. Strategic archetypes separate cloud-native infrastructure providers, consulting-anchored implementation partners, and embedded analytics specialists. Competitive moves concentrate on strategic partnerships between cloud platforms and systems integrators, plus portfolio diversification into edge-to-cloud convergence architectures.
Within the hyperscale infrastructure tier, Microsoft Corporation and Google exemplify platform-centric positioning through Azure and advertising technology integration respectively. IBM Corporation occupies a specialized position serving regulated industries with modular risk management architectures. These three anchors represent distinct competitive vectors: cloud ecosystem lock-in, ad-tech data fusion, and compliance-engineered vertical solutions.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| AWS, Inc. |
| Oracle Corporation |
| SAP SE |
| Accenture |
| Capgemini |
| Tata Consultancy Services |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic transparency mandates gate qualified supply access for European deployments and anchor premium-tier pricing for compliant cloud-native architectures. Vendors must absorb specialized compliance engineering costs to serve finance and healthcare buyers in Germany and France, while procurement teams in the United States negotiate consumption-based structures that compress margins at scale.
Pricing Analysis
Capacity additions in India's analytics delivery corridor are reshaping price floors for implementation and managed services tiers. Three-tier pricing structure across premium, standard, and economy levels separates predictive analytics platforms with embedded ML governance from baseline web measurement tools. Price differentiation hinges on certification level for EU AI Act compliance and customization depth for legacy ERP integration. Cost compression in the mid-market SaaS tier is intensifying because hyperscaler storage commoditization erodes infrastructure markups. Small and medium enterprises exhibit highest price sensitivity, while regulated finance buyers in the United States and Europe accept premium positioning for audit-trail capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for specialized GPU compute hardware that powers sub-second query response thresholds. Software development capacity concentrates in India, the United States, and Ireland, with Bangalore and Hyderabad anchoring ML engineering talent pipelines. Raw material dependencies span semiconductor fabrication equipment, high-bandwidth memory modules, and rare earth elements for data center cooling systems. Tariff exposure on Chinese-manufactured server components threatens margin stability for hardware-dependent deployment architectures. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital analytics solutions rests on automation of feature engineering pipelines and tiered upsell into predictive modules from commoditized measurement bases.
For Market Incumbents: Hedge against hyperscaler infrastructure commoditization by deepening proprietary data connector libraries for SAP and Oracle ERP systems. Vertical integration into edge computing hardware for manufacturing and logistics IoT deployments defends against cloud-native entrants. EU AI Act compliance engineering investments in Bavaria and Île-de-France delivery centers protect pricing power in European regulated industries. For New Entrants and Emerging Players: Capture mid-market buyers in India and Southeast Asia lacking internal ML engineering capacity through managed services packaging with localized data residency guarantees. Healthcare analytics in France and Germany presents the most penetrable vertical due to HIPAA and CNIL enforcement gaps among incumbent platforms. Channel partnership with Tata Consultancy Services and Accenture accelerates enterprise access without direct sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific analytics modules because customer switching costs in retail and finance create sticky recurring revenue bases. Five-to-ten year viability favors platforms with embedded ML operationalization rather than pure measurement layers. Watch SEC climate disclosure enforcement intensity as the inflection signal for ESG analytics capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and AWS data lake consolidation reduces fragmentation for Fortune 500 procurement teams. |
| Acquisition of Specialist Firm | Vertical risk management modules from IBM Watson anchor compliance-driven pricing in finance. |
| Strategic Partnership | Systems integrator alliances with Capgemini and TSI expand mid-market managed services reach. |
| Geographic Expansion | Bangalore and Hyderabad delivery centers capture EU and US outsourcing contract flows. |
| Product Launch | Explainable AI features for EU AI Act risk classification open German automotive and healthcare demand. |
Methodological Framework
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across the United States, Germany, and India informed demand-side assumptions. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and RBI data localization circulars. Triangulation between stakeholder interview data and published regulatory frameworks ensures segmentation accuracy.
Input-output matrices map deployment architecture adoption rates against solution type margin profiles across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory exposure, integration complexity, and regional compliance framework. CAGRs derive from curve-fitting historical procurement velocity against mandated migration timelines for GDPR and EU AI Act compliance. Forecast inputs incorporate cloud migration budget disclosures and ML engineering talent pipeline data from Karnataka and Telangana technical institutes.
Regulatory timeline delays, hyperscaler pricing volatility, and ML practitioner supply constraints are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding compliance enforcement intensity and enterprise IT modernization budget continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Retail Analytics Software and Services Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
Europe HR Analytics Market
Analytics
Advanced Analytics Market
Analytics
Voice Analytics Market
Analytics
Brazil Geospatial Analytics Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
App Analytics Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Greece ICT Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Global Wi-Fi Analytics Market
Analytics
US Video Analytics Market
Analytics
UK Video Analytics Market