
 Israel Geospatial Analytics Market | 2026-2036
Israel Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Geospatial Analytics Market Insights
Channel partnerships between defense contractors and civilian software distributors is rewriting how geospatial intelligence reaches non-military buyers in Israel. Rafael Advanced Defense Systems leverages its satellite command heritage to anchor premium positioning in dual-use analytics. Elbit Systems competes through integrated sensor-to-analytics pipelines that extend from airborne platforms to ground stations. ImageSat International dominates commercial imagery resale by controlling exclusive orbital access over Eastern Mediterranean targets.
Geospatial analytics encompasses the computational processing of location-referenced data through remote sensing capture, spatial database management, and algorithmic pattern recognition to generate actionable intelligence for asset tracking, territory monitoring, and predictive terrain modeling. The technology stack processes multispectral satellite feeds through artificial intelligence and machine learning pipelines that automate feature extraction from raster and vector datasets. Government end users command the largest procurement budgets though agriculture applications are expanding fastest as precision farming mandates from Israel's Water Authority drive sensor network deployment. Cloud-based solutions capture growing share as hybrid architectures lose favor among security-conscious defense clients requiring air-gapped on-premises systems.
Israel's National Cyber Directorate and the Israel Defense Forces C4I Directorate jointly regulate geospatial data classification, restricting foreign cloud hosting of sensitive territorial imagery while permitting commercial export of processed analytics. The Standards Institution of Israel enforces interoperability protocols that compel vendors to adopt national spatial reference systems compatible with NATO geodata frameworks. Stakeholders must monitor evolving export control rulings from the Israeli Ministry of Defense that could recategorize commercial satellite analytics as controlled defense articles.
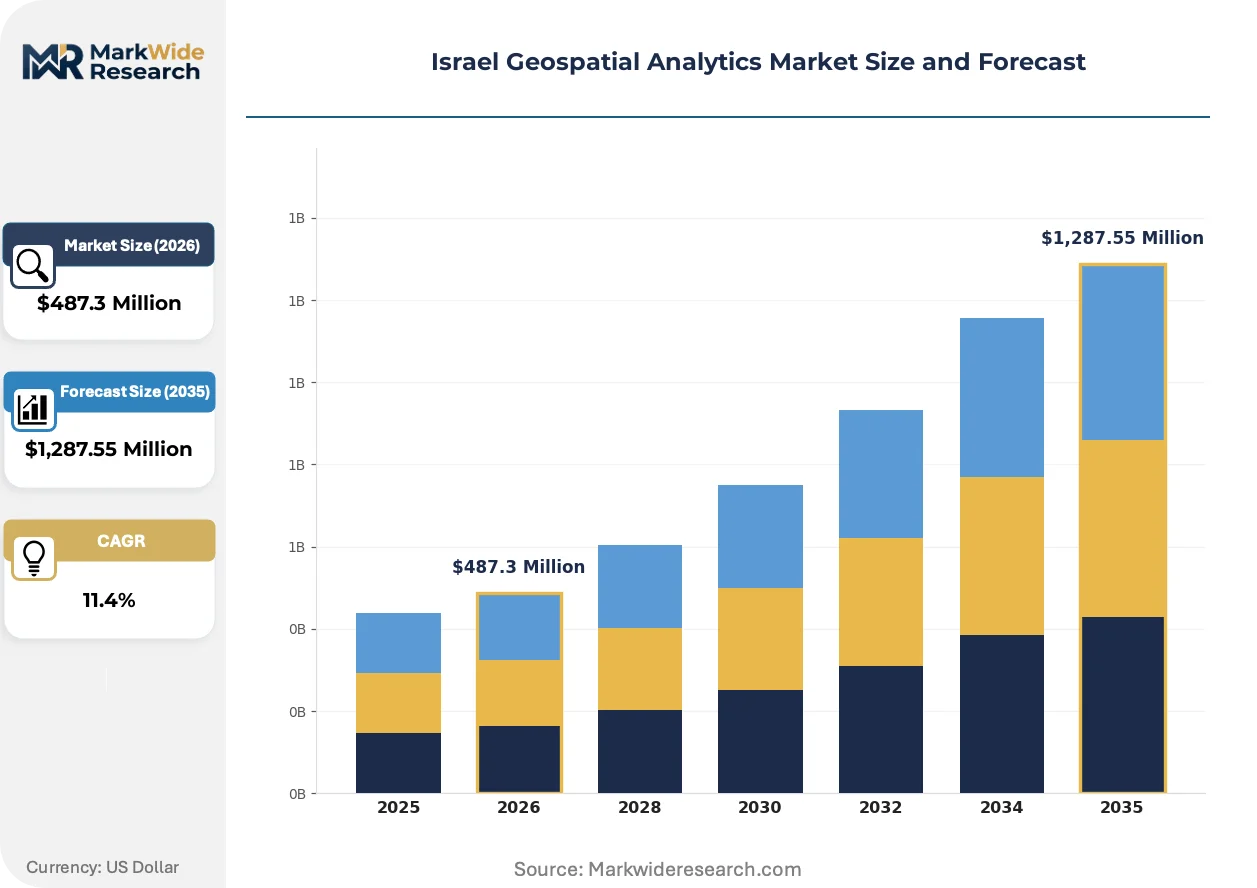
Market Dynamics
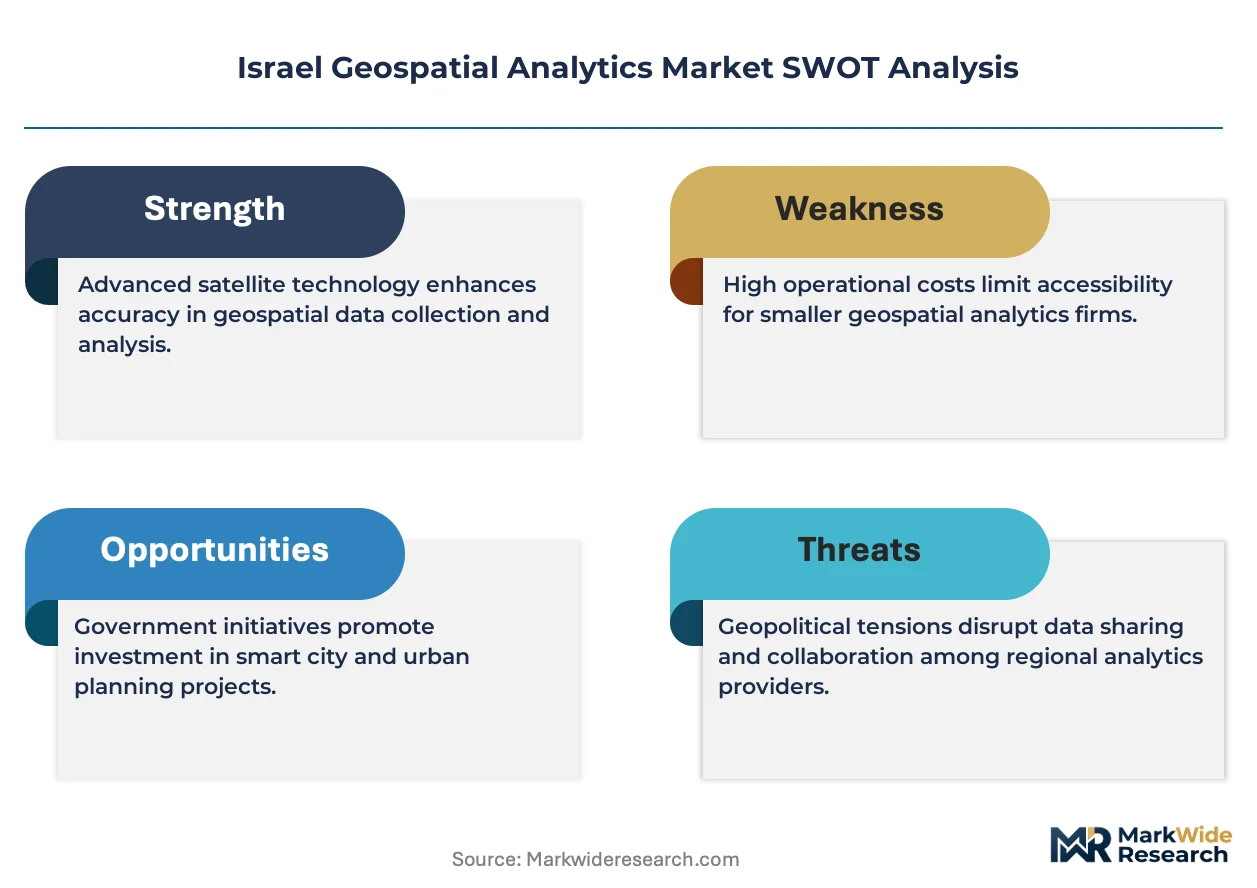
Israel's National Spatial Data Infrastructure policy mandates standardized geodata sharing across ministries, forcing vendors to retrofit legacy platforms for interoperability while defense clients demand air-gapped architectures that resist cloud migration.
Growth Catalysts
- Water Authority precision mandates:Israel's Water Authority now requires sensor network deployment for agricultural water monitoring, accelerating farm-level procurement of geospatial analytics platforms.
- Dual-use technology transfer:Military satellite command heritage flows into civilian applications through defense contractor partnerships, expanding addressable markets beyond traditional defense buyers.
- AI/ML pipeline automation:Artificial intelligence and machine learning now automate feature extraction from raster datasets, compressing analyst labor requirements for territory monitoring workflows.
Market Restraints
- Foreign cloud hosting prohibitions:Israel's National Cyber Directorate restricts sensitive territorial imagery on foreign servers, limiting vendor architecture options and raising infrastructure costs.
- Export control uncertainty:The Israeli Ministry of Defense may recategorize commercial satellite analytics as controlled defense articles, creating compliance friction for analytics exporters.
- Input concentration in orbital access:Exclusive control over Eastern Mediterranean imagery by single-source providers creates supply vulnerability for downstream analytics vendors.
Strategic Opportunities
- Negev Desert precision agriculture:Arid-zone farming expansion in Israel's southern districts creates demand for predictive terrain modeling and subsurface water mapping.
- NATO geodata framework alignment:Standards Institution of Israel interoperability protocols position domestic vendors for defense export contracts into European allied markets.
- Hybrid-to-air-gapped migration services:Security-conscious defense clients require on-premises system integration expertise, creating high-margin professional services revenue streams.
Industry Challenges
- Cleared personnel scarcity:Geospatial AI development requires engineers with security clearances, constraining talent pools for classified project staffing.
- Legacy sensor integration complexity:Municipal governments operate heterogeneous equipment fleets that resist standardized analytics platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Geospatial Analytics Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,287.55 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geographic Information System, Remote Sensing, Spatial Data Infrastructure, Location-Based Services End User: Government, Defense, Agriculture, Transportation Deployment: Cloud-Based Solutions, On-Premises Systems, Hybrid Systems, Open Source Platforms Technology: Artificial Intelligence, Machine Learning, Internet of Things, Big Data |
| Companies Covered | Esri Inc., Rafael Advanced Defense Systems, ImageSat International, Elbit Systems, Israel Aerospace Industries, Microsoft Corporation, Autodesk Inc., Bentley Systems Inc., SAS Institute Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Geospatial Analytics Market Trends and Innovations
Computational processing of location-referenced data is pivoting from batch analysis toward real-time streaming architectures, with artificial intelligence pipelines now operating at the edge of satellite downlink stations.
Multispectral satellite feeds processed through on-board AI accelerators are rendering obsolete ground-station preprocessing workflows that previously consumed hours between capture and actionable intelligence delivery. Defense agencies in Tel Aviv's technology corridor now demand sub-minute latency for territory monitoring applications. This compression eliminates competitive positioning for vendors lacking edge-computing architecture.
Israel's National Cyber Directorate and IDF C4I Directorate jointly regulate geospatial data classification, creating a dual-key approval system that extends procurement cycles for sensitive territorial imagery. Defense contractors must now navigate parallel compliance tracks for commercial and classified deployments. Municipal governments face lighter scrutiny but encounter capability gaps when scaling from pilot programs to enterprise sensor networks.
Subscription-based platform access is displacing perpetual license sales across municipal procurement departments, compressing upfront revenue recognition for analytics vendors. Tel Aviv metropolitan authorities now favor operational expenditure models that bundle sensor maintenance with software access. This shift pressures vendor cash flow management while rewarding providers with integrated hardware-software service capabilities.
Israel Geospatial Analytics Market Segmentation
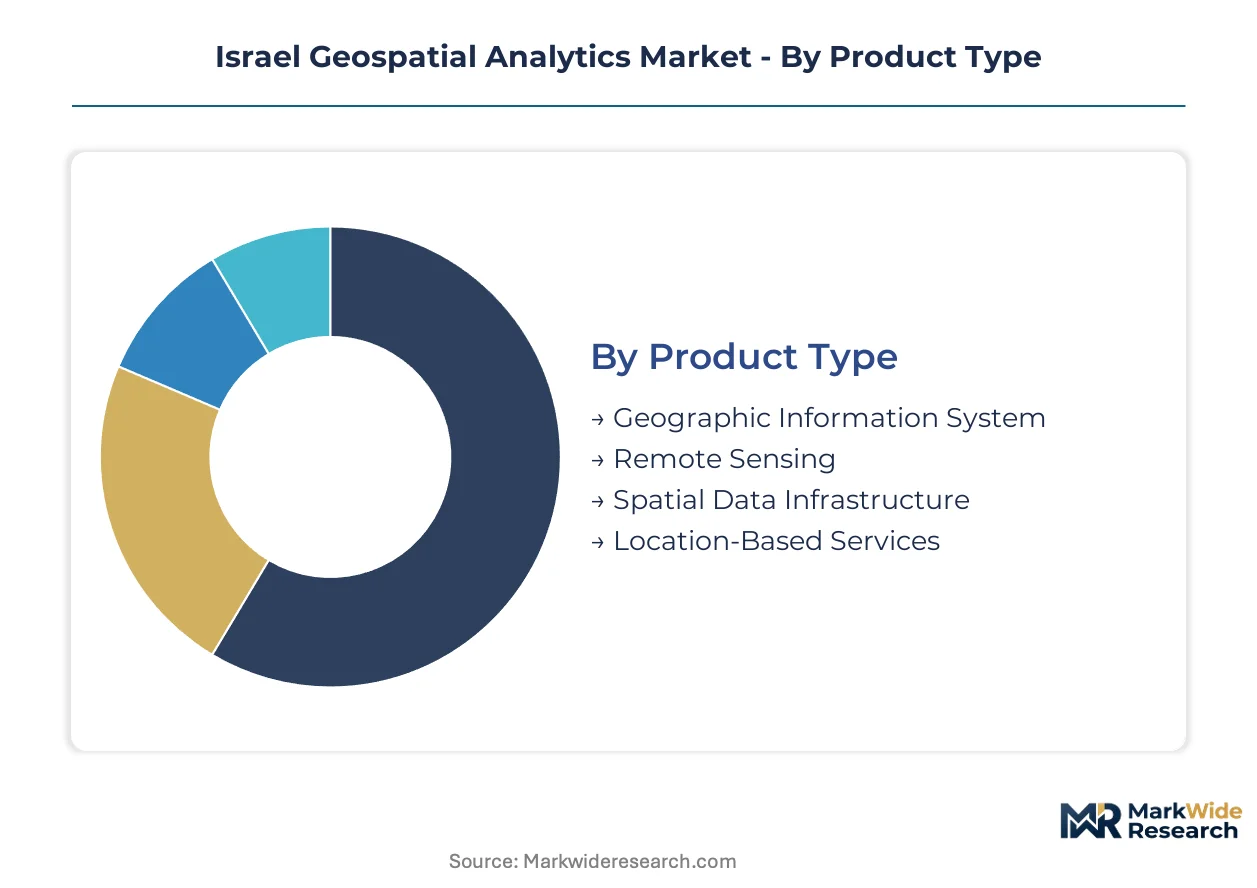
Geospatial analytics procurement patterns in Israel diverge sharply by segment cycle times, with defense contracts extending across multi-year development cycles while municipal deployments compress to quarterly refresh intervals. Understanding these velocity differentials enables vendors to align R&D pipelines with revenue recognition timing and capacity planning.
Product Type:
Remote Sensing platforms turn over fastest as orbital access agreements renegotiate annually, while Spatial Data Infrastructure investments stretch across decade-long national modernization programs.
- Geographic Information System:Core mapping and spatial analysis software layers process vector and raster datasets through standardized coordinate reference systems. Municipal governments in Tel Aviv's metropolitan corridor drive procurement as property tax assessment modernization mandates compel legacy system replacement.
- Remote Sensing:Satellite and aerial imagery capture systems deliver multispectral and synthetic aperture radar feeds for territory monitoring. Defense agencies command premium procurement budgets here, though agricultural drought monitoring applications are expanding most quickly under Water Authority precision mandates.
- Spatial Data Infrastructure:Federated geodata repositories enabling cross-ministry sharing under Israel's National Spatial Data Infrastructure policy.
- Location-Based Services:Real-time positioning APIs and navigation overlays for fleet management and emergency response dispatch.
Geographic Information System dominates installed base. Remote Sensing is where expansion concentrates.
End User:
Defense procurement operates at the highest cost tier with classified security requirements, while Agriculture sits at the volume frontier where sensor network standardization drives unit economics.
- Government:Civilian ministries and municipal authorities procuring territory planning, environmental monitoring, and infrastructure asset management platforms. The Standards Institution of Israel enforces interoperability protocols that compel vendors to adopt national spatial reference systems, extending procurement cycles but ensuring long-term contract lock-in.
- Defense:Israel Defense Forces and intelligence agencies requiring air-gapped architectures for sensitive territorial imagery. Israel's National Cyber Directorate and IDF C4I Directorate jointly regulate data classification, creating dual-key approval systems that restrict foreign cloud hosting and favor domestic system integrators.
- Agriculture:Precision farming operators deploying subsurface water mapping and predictive terrain modeling across Negev Desert expansion zones.
- Transportation:Logistics fleet operators and public transit authorities utilizing real-time route optimization and congestion analytics.
Defense commands highest contract values. Agriculture represents the steepest expansion trajectory as arid-zone farming mandates proliferate.
Deployment:
Cloud architectures mature fastest with monthly feature releases, while On-Premises Systems extend across generational procurement horizons given defense certification requirements.
- Cloud-Based Solutions:SaaS analytics platforms with elastic compute scaling for commercial imagery processing. Municipal governments favor operational expenditure models here, though the National Cyber Directorate restricts sensitive territorial imagery from foreign servers.
- On-Premises Systems:Air-gapped installations with dedicated hardware stacks for classified defense workloads. Security-conscious clients require integration expertise that generates high-margin professional services revenue.
- Hybrid Systems:Split architectures with sensitive preprocessing on-premises and non-classified analytics in cloud environments.
- Open Source Platforms:Community-developed geospatial libraries and self-hosted alternatives reducing license expenditure for budget-constrained agencies.
On-Premises Systems dominate classified installed base. Cloud-Based Solutions capture growing share among municipal buyers.
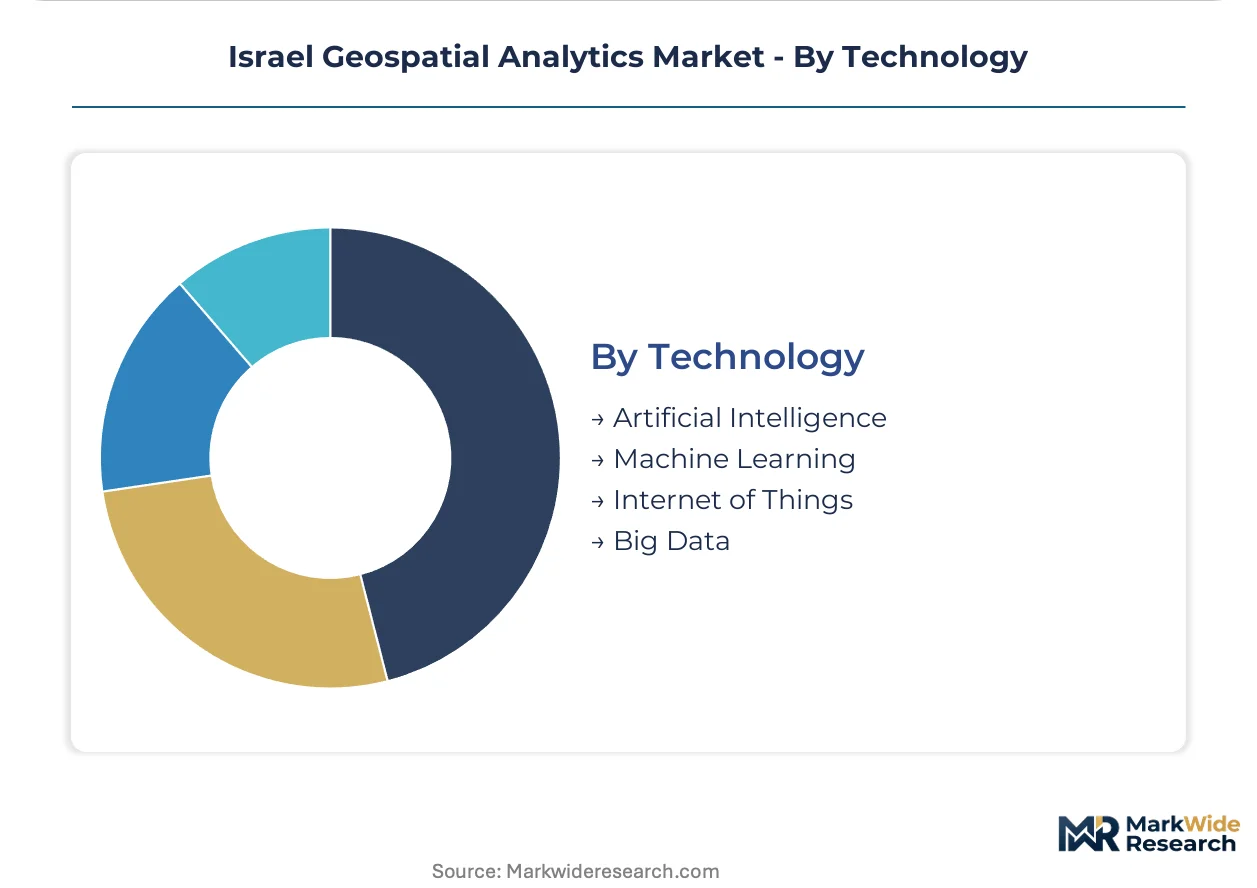
Technology:
Internet of Things sensors refresh on agricultural harvest cycles, while Big Data infrastructure investments span five-year depreciation schedules.
- Artificial Intelligence:Neural network pipelines automating feature extraction from satellite imagery at edge-computing nodes. Defense agencies now demand sub-minute latency for territory monitoring, eliminating vendors lacking real-time architecture.
- Machine Learning:Supervised classification algorithms training on historical spatial datasets for predictive terrain modeling. Agricultural water monitoring applications deploy these models across Negev sensor networks.
- Internet of Things:Ground-based sensor arrays collecting soil moisture, meteorological, and crop health telemetry for precision farming.
- Big Data:Distributed storage and processing frameworks handling petabyte-scale satellite imagery archives.
Machine Learning anchors current defense procurement. Artificial Intelligence is where vendor R&D investment concentrates for next-generation capability differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's National Spatial Data Infrastructure policy mandates standardized geodata sharing across ministries, creating procurement momentum in municipal governments while defense agencies drive premium-tier demand for air-gapped architectures. The analysis examines five sub-regional concentrations where geospatial analytics procurement diverges by end-use security requirements and infrastructure maturity.
Tel Aviv Metropolitan Area
Defense contractors and geospatial AI startups cluster along the technology corridor, feeding procurement from IDF C4I Directorate and intelligence agencies. The National Cyber Directorate restricts sensitive territorial imagery from foreign cloud servers, compelling vendors toward domestic system integrators. Tel Aviv municipal authorities favor subscription-based operational expenditure models bundling sensor maintenance with software access.
Negev Desert Districts
Arid-zone farming expansion generates demand for subsurface water mapping and predictive terrain modeling under Water Authority precision mandates. Agricultural sensor networks deploy across southern districts where drought monitoring applications expand fastest. The Israel Land Authority coordinates spatial data repositories enabling cross-ministry sharing for territory planning workflows.
Haifa Bay Industrial Zone
Port logistics operators and maritime surveillance agencies procure real-time positioning APIs for fleet management and emergency response dispatch. The Standards Institution of Israel enforces interoperability protocols compatible with NATO geodata frameworks, positioning domestic vendors for defense export contracts. Industrial equipment manufacturers integrate location-based services into supply chain tracking systems.
Jerusalem Government Quarter
Civilian ministries consolidate spatial database management for infrastructure asset monitoring and environmental compliance. The dual-key approval system between National Cyber Directorate and IDF C4I Directorate extends procurement cycles for sensitive territorial imagery. Municipal planning departments face capability gaps when scaling pilot sensor networks to enterprise deployment.
Galilee Northern Region
Border monitoring applications and precision agriculture coexist across mixed-use territories where security-conscious clients require hybrid-to-air-gapped migration expertise. Regional water utilities deploy Internet of Things sensor arrays for agricultural telemetry under national conservation mandates. Local governments operate heterogeneous equipment fleets resisting standardized analytics platform deployment.
Israel Geospatial Analytics Market Competitive Landscape
On the supply side, the industry is bifurcated between defense heritage contractors commanding premium positioning and commercial software distributors rewriting channel access for non-military buyers. Three strategic archetypes dominate: satellite command heritage players leveraging dual-use technology transfer, integrated sensor-to-analytics pipeline providers, and exclusive orbital access controllers. Competitive moves concentrate on strategic partnerships bridging defense and civilian procurement channels, plus portfolio diversification into precision agriculture applications.
Within the defense heritage tier, Rafael Advanced Defense Systems and Elbit Systems exemplify contrasting integration strategies, while ImageSat International anchors the orbital access control archetype. Microsoft Corporation and Autodesk Inc. represent commercial software distributors expanding through municipal procurement channels. Esri Inc. occupies a position bridging geospatial platform standardization with defense interoperability requirements. These players collectively illustrate how channel partnerships and dual-use technology flows are restructuring competitive positioning across Israeli government and agricultural end-use segments.
| Leading Market Players |
|---|
| Esri Inc. |
| Rafael Advanced Defense Systems |
| ImageSat International |
| Elbit Systems |
| Israel Aerospace Industries |
| Microsoft Corporation |
| Autodesk Inc. |
| Bentley Systems Inc. |
| SAS Institute Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in edge-computing hardware fabrication tightens vendor margins while simultaneously strengthening pricing power for satellite imagery providers with exclusive Eastern Mediterranean orbital access. Israel's National Cyber Directorate restrictions on foreign cloud hosting force domestic system integrators toward air-gapped architectures that carry premium installation and maintenance cost structures.
Pricing Analysis
Volume-discount tiering structures separate defense-grade air-gapped deployments from municipal SaaS subscriptions and agricultural sensor-network bundles. Price differentiation rests on security clearance requirements and NATO interoperability certification levels. Cost compression in municipal cloud tiers intensifies as subscription models displace perpetual licenses. Agricultural buyers exhibit highest price sensitivity due to thin commodity margins, while defense agencies prioritize capability over unit cost.
Supply Chain Analysis
Extended payment terms from defense contractors to component suppliers characterize working capital dynamics across the vendor base. Hardware concentrates in Israel, Taiwan, and the United States for AI accelerators and satellite ground station equipment. Software draws from open-source geospatial libraries and proprietary defense heritage codebases. Single-source vulnerability concentrates in Eastern Mediterranean imagery access controlled by exclusive orbital agreements. Distribution runs through defense contractor prime channels for classified workloads and civilian software distributors for municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's geospatial analytics sector sits in early-cycle expansion as Water Authority precision mandates penetrate agricultural sensor networks previously dependent on manual monitoring. Dual-use technology flows from military satellite command heritage accelerate civilian application development timelines.
For Market Incumbents: Entrench air-gapped architecture expertise through cleared personnel certification programs that constrain competitor staffing pools. Deepen backward integration into sensor manufacturing to capture margin from hardware-software bundles. Municipal procurement standardization around Israel's National Spatial Data Infrastructure protocols creates long-term contract lock-in for vendors with legacy system retrofit capabilities.
For New Entrants and Emerging Players: Establish a beachhead in Negev Desert precision agriculture where arid-zone farming expansion outpaces incumbent coverage. Agricultural water monitoring applications offer lowest competitive density and fastest procurement velocity. Go-to-market through Israel Land Authority territorial planning partnerships bypasses direct competition with defense heritage contractors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS platform providers serving Tel Aviv metropolitan authorities with bundled sensor maintenance contracts. Long-term viability favors vendors with dual-use technology transfer pipelines spanning defense and civilian end-use segments. Monitor Israeli Ministry of Defense export control rulings as inflection indicator for commercial analytics reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Architecture Investment | Sub-minute latency requirements from IDF C4I Directorate eliminate vendors lacking real-time processing capability. |
| NATO Interoperability Certification | Standards Institution of Israel protocols position domestic vendors for European allied defense export contracts. |
| Precision Agriculture Partnership | Water Authority mandates drive sensor network deployment across Negev Desert expansion zones. |
| Air-Gapped System Integration | National Cyber Directorate restrictions on foreign cloud hosting create high-margin professional services demand. |
| Dual-Use Technology Transfer | Military satellite command heritage flows into civilian applications through defense contractor channel partnerships. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, municipal IT directors, agricultural operations managers, and geospatial platform engineers and refined through secondary validation. Primary fieldwork combined structured interviews with Israeli government technology buyers and defense contractor program managers. Secondary sources encompassed Israel National Spatial Data Infrastructure policy documents, Standards Institution of Israel interoperability protocols, and IDF C4I Directorate procurement guidelines. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, end-user vertical, deployment architecture, and technology stack complexity. CAGRs derived from historical trajectory analysis adjusted for policy mandate acceleration and technology adoption S-curves. Forecast inputs incorporated Water Authority precision mandate implementation schedules and dual-use technology transfer pipeline velocity.
Sensitivities concentrate around Israeli Ministry of Defense export control recategorization rulings and National Cyber Directorate cloud hosting restriction evolution. Forecasts reflect documented assumptions regarding defense procurement cycle continuity and agricultural sensor network standardization timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Latin America Location Based Data Analytics Market
Analytics
Marketing Mix Optimization Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Patent Analytics Services Market
Analytics
Augmented Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Workforce Analytics Market
Analytics
Analytics of Things (Aot) Market
Analytics
Pandemic Analytics Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
India Geospatial Analytics Market
Analytics
Self Service Analytics Market
Analytics
Mobile App Attribution Tool Market
Analytics
Service Analytics Market
Analytics
Embedded Analytics Market