
 Global Wi-Fi Analytics Market | 2026-2036
Global Wi-Fi Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wi-Fi Analytics Market Intelligence
Enterprise-grade Wi-Fi analytics is rotating toward real-time location systems with sub-meter accuracy and predictive dwell-time modeling. Cisco Systems leverages its Meraki cloud infrastructure to anchor large-scale retail and hospitality deployments. Fortinet competes through integrated security analytics that unify wireless threat detection with network performance monitoring. Skyfii specializes in venue intelligence platforms that sustain recurring revenue through SaaS-based customer experience dashboards.
Wi-Fi analytics encompasses the capture, aggregation, and algorithmic interpretation of radio frequency signal data, probe requests, and connected device telemetry to derive spatial behavior patterns and network performance metrics. The technology operates through distributed access point arrays that measure signal strength variance, device association intervals, and bandwidth utilization to enable dynamic load balancing and footfall quantification. Cloud-based deployment leads solution delivery by reducing capital intensity for multi-site operators, while edge computing configurations are gaining traction in latency-sensitive environments such as transportation hubs and manufacturing floors. Predictive analytics commands premium pricing due to its integration with enterprise CRM and inventory systems, whereas security analytics represents the fastest-expanding solution category as zero-trust architectures extend into wireless access layers.
The Federal Communications Commission shapes spectrum allocation and power regulations that directly constrain sensor density and indoor positioning accuracy in the United States. The European Union's GDPR and the EU AI Act impose strict anonymization and algorithmic transparency mandates that vendors must embed at the firmware level to maintain market access. Stakeholders must monitor evolving national data-localization statutes and spectrum reallocation proceedings to anticipate compliance costs and competitive positioning shifts.
Market Dynamics
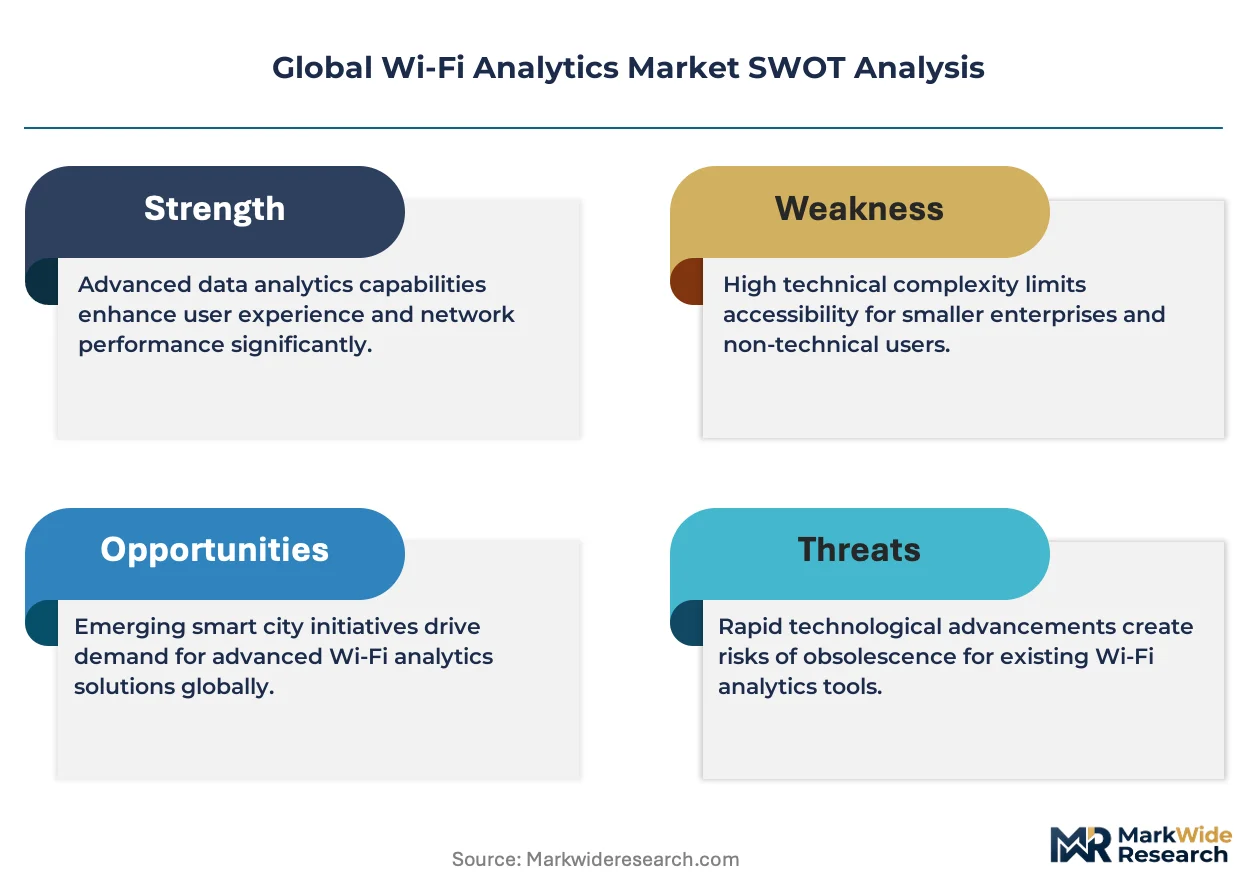
Enterprise WLAN refresh cycles are compressing from five-year to three-year intervals as predictive location intelligence becomes a baseline procurement requirement rather than a premium upgrade tier.
Growth Catalysts
- GDPR Article 25 Data Protection by Design:European retail chains now mandate privacy-preserving probe request anonymization at the firmware layer, expanding addressable market for compliant analytics vendors.
- Smart Venue Infrastructure:Airport operators in the United States deploy sub-meter RTLS for passenger flow optimization and gate congestion prediction.
- Wi-Fi 6E Spectrum Expansion:The FCC's 6 GHz band allocation enables denser access point arrays without co-channel interference, improving positioning accuracy thresholds.
Market Restraints
- Silicon Supply Concentration:Enterprise-grade Wi-Fi chipset fabrication concentrates in Taiwan and South Korea, creating vulnerability to geopolitical disruption or export control tightening.
- GDPR Fines and Liability Exposure:The EU AI Act's algorithmic transparency mandates impose compliance costs that squeeze margin structures for mid-tier analytics providers.
- 5G Private Network Substitution:Manufacturing facilities increasingly evaluate CBRS-based private cellular for indoor positioning, threatening Wi-Fi analytics' historical dominance in industrial environments.
Strategic Opportunities
- India Smart Cities Mission:Municipal transit authorities seek footfall analytics for crowd management at metro interchanges, creating first-mover advantage for vendors with localized data residency architectures.
- AI-Driven Predictive Maintenance Convergence:Integration of Wi-Fi telemetry with machine learning models for HVAC and lighting optimization opens building automation as an adjacent revenue pool.
- Subscription-Based Channel Pivot:Value-added resellers transition from perpetual license sales to recurring SaaS arrangements, improving customer lifetime value metrics and reducing churn.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:Deployment of sub-meter positioning requires specialized expertise in multipath mitigation and antenna calibration that outpaces current training pipeline output.
- Legacy WLAN Integration Complexity:Brownfield environments with heterogeneous access point vintages from Aruba, Cisco, and Ruckus create data normalization bottlenecks that prolong implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wi-Fi Analytics Market |
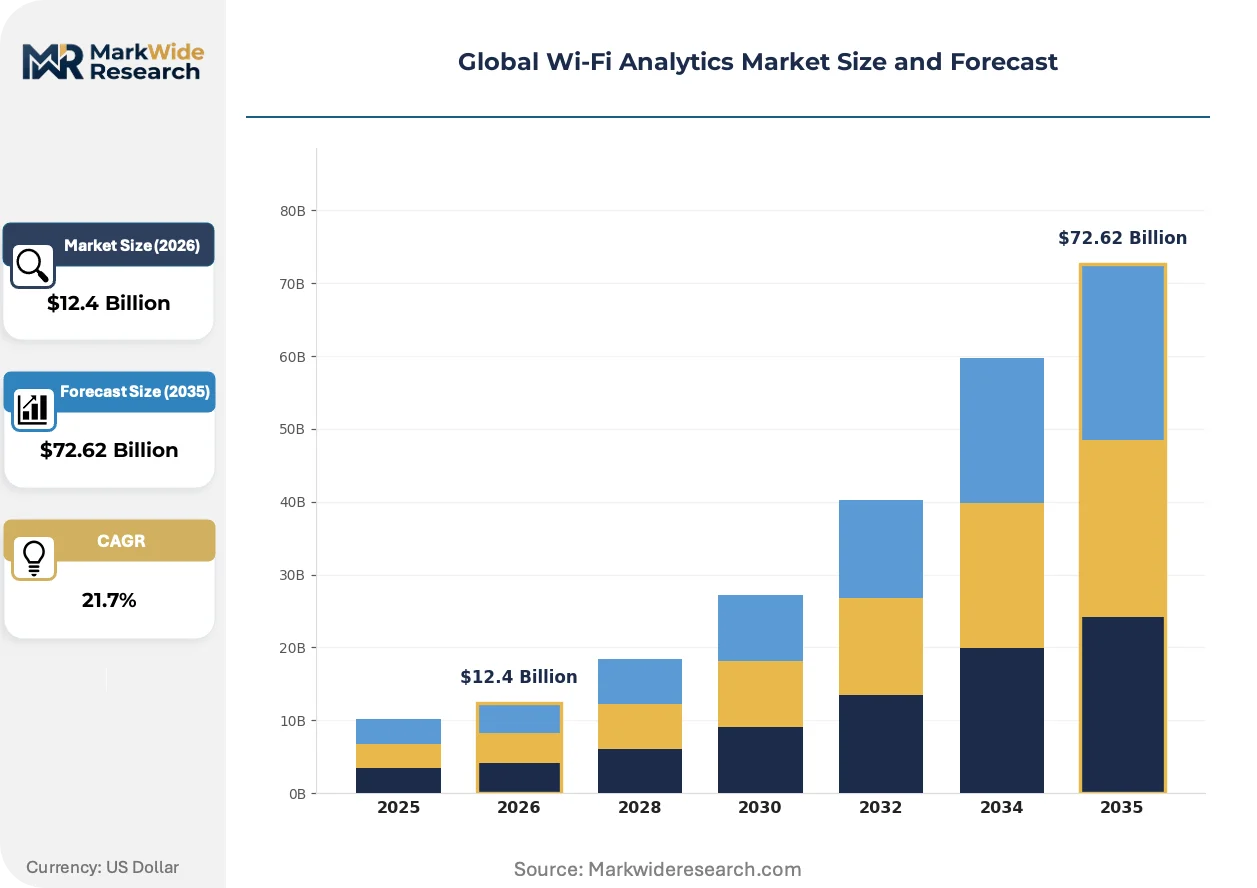
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $72.62 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Real-Time Analytics, Predictive Analytics, User Behavior Analysis, Traffic Management, Security Analytics Use Case: Customer Experience Enhancement, Network Optimization, Location Analytics, Marketing Campaigns, Asset Tracking End User Industry: Telecommunications Providers, Educational Institutions, Hospitality Chains, Retail Chains, Transportation Operators |
| Companies Covered | Cisco Systems, Inc., Cloud4Wi, Purple Wi-Fi, Fortinet, Inc., Hewlett Packard Enterprise, Skyfii, GoZone WiFi, Euclid, RetailNext, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wi-Fi Analytics Market Strategic Shifts & Innovations
Cloud-native architectures are displacing on-premise deployments as the default delivery mode, while edge inference capabilities advance to satisfy latency constraints in transportation and industrial settings.
Passpoint and OpenRoaming protocols are fragmenting captive portal authentication flows across venue types. Hospitality operators adopt seamless cellular-to-Wi-Fi handoff to reduce front-desk friction. This protocol fragmentation is compressing vendor differentiation around proprietary authentication layers and shifting competitive focus toward backend analytics depth.
The EU AI Act's risk-based classification system imposes documentation and audit requirements on behavioral analytics algorithms used for customer journey mapping. Vendors serving European retail must maintain technical files demonstrating bias mitigation in dwell-time prediction models. France's CNIL has issued specific guidance on MAC address hashing standards that exceeds baseline GDPR requirements, creating a compliance gradient across member states.
Buyer procurement patterns are consolidating around integrated platform evaluations rather than point-solution acquisitions. Large retail chains now require Wi-Fi analytics to demonstrate pre-built connectors to Salesforce, Shopify, and SAP Commerce Cloud before inclusion in RFP shortlists. This integration mandate is most pronounced in the United States, where unified commerce investments have advanced furthest among enterprise segments.
Global Wi-Fi Analytics Market Segmentation
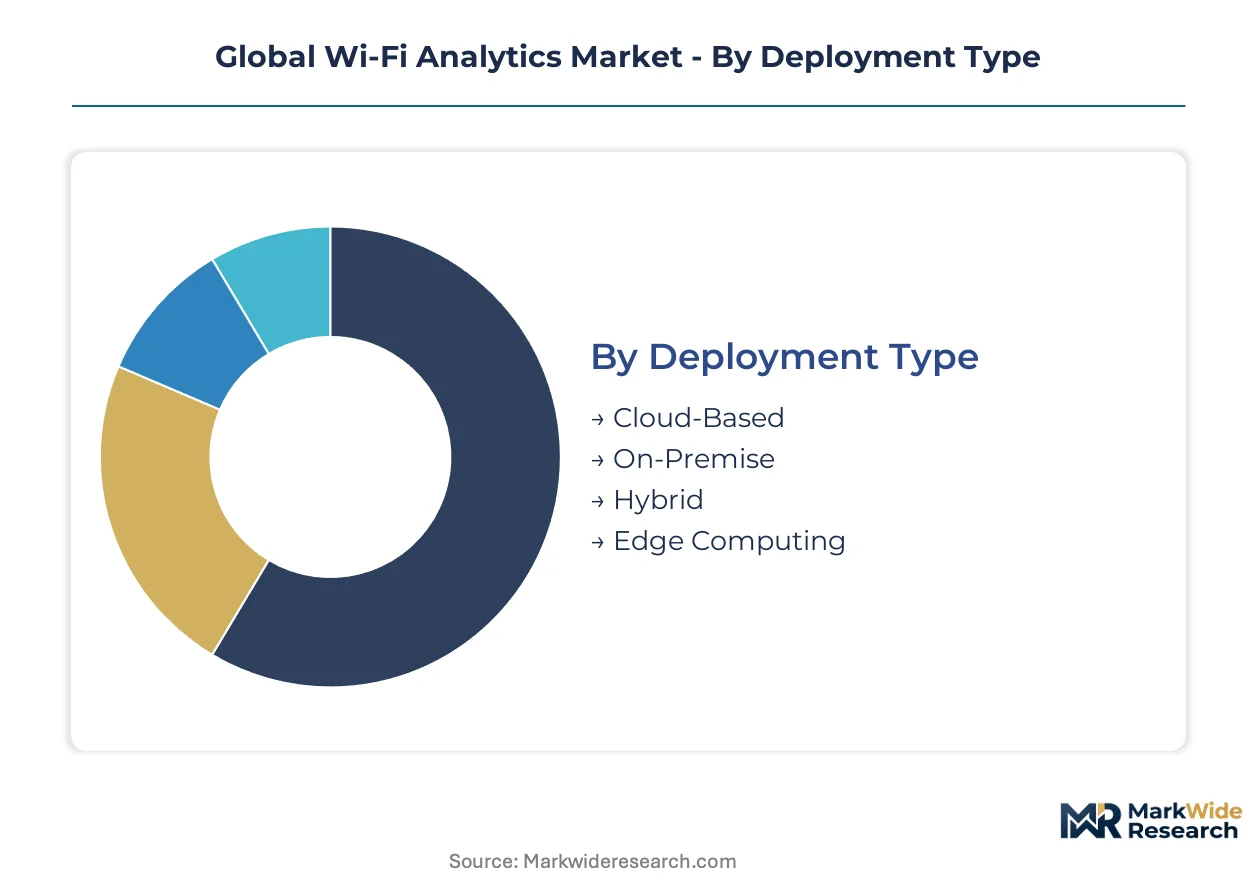
Wi-Fi analytics vendors structure product portfolios around four intersecting dimensions that determine pricing architecture and deployment complexity. Deployment type and solution offering dictate capital intensity and recurring revenue potential, while use case and end user industry define integration requirements and sales cycle length.
Deployment Type:
Cloud-based deployments dominate North American enterprise procurement, whereas edge computing configurations concentrate in European manufacturing and Asian transportation infrastructure.
- Cloud-Based:Multi-tenant SaaS architectures eliminate on-site server maintenance and enable centralized dashboard access across dispersed retail footprints. United States hospitality chains prioritize this model for rapid property onboarding without dedicated IT staff at each location. Cloud delivery commands subscription pricing that improves vendor cash flow predictability.
- On-Premise:Single-tenant installations retain raw telemetry within facility firewalls, satisfying data residency mandates from Germany's BSI and France's CNIL. Financial services and defense contractors in Switzerland mandate on-premise stacks despite higher total cost of ownership. Procurement cycles extend 18-24 months due to security clearance protocols.
- Hybrid:Split architectures process sensitive authentication data locally while pushing anonymized analytics to cloud dashboards. Australian healthcare networks and Canadian university systems favor this balance of compliance and scalability.
- Edge Computing:Millisecond-latency inference at access point level supports real-time passenger flow alerts in Singapore's Changi Airport and Dubai's metro interchanges. Deployment requires specialized radio frequency engineering talent that concentrates in South Korea and Taiwan.
Cloud-based holds the largest share; momentum sits with edge computing.
Solution Offering:
Solution pricing stratifies sharply: security analytics commands premium licensing due to zero-trust integration requirements, while traffic management functions approach commodity pricing.
- Real-Time Analytics:Sub-second dashboard updates enable immediate staff redeployment during congestion events. Large-format retailers in the United Kingdom deploy these capabilities for queue management during peak trading hours. FCC spectrum allocations for Wi-Fi 6E improve update frequency thresholds.
- Predictive Analytics:Machine learning models forecast dwell-time patterns and correlate footfall with inventory depletion rates. Integration with SAP Commerce Cloud and Salesforce Marketing Cloud separates premium vendors from point-solution providers. GDPR Article 22 restrictions on automated decision-making constrain algorithmic transparency requirements in EU deployments.
- User Behavior Analysis:Path tracing and zone heatmaps support merchandising decisions in French hypermarkets and Japanese department stores.
- Traffic Management:Dynamic load balancing across access point arrays prevents bandwidth saturation during convention center peak loads.
- Security Analytics:Wireless intrusion detection and rogue access point identification unify with Fortinet and Palo Alto Networks firewall ecosystems. Fastest-expanding category as NIST zero-trust architectures extend into wireless access layers.
Security analytics is climbing the fastest; real-time analytics retains the revenue base.
Use Case:
Customer-facing applications generate higher per-seat pricing than infrastructure optimization tools, though the latter deliver faster implementation timelines.
- Customer Experience Enhancement:Personalized captive portals and loyalty program integration reduce front-desk friction in Marriott and Hilton properties. Passpoint protocol adoption accelerates seamless cellular-to-Wi-Fi handoff. Deployment concentrates in United States and United Arab Emirates luxury hospitality.
- Network Optimization:Automated channel selection and transmit power adjustment minimize interference in dense urban deployments. Telecommunications providers in South Korea and Japan prioritize this use case for public Wi-Fi infrastructure.
- Location Analytics:Sub-meter positioning supports asset tracking in German automotive assembly plants.
- Marketing Campaigns:Proximity-triggered promotions and dwell-time-based retargeting integrate with Shopify and Klaviyo for mid-market retailers.
- Asset Tracking:RTLS for medical equipment and industrial tooling expands fastest in Indian hospital networks under the Smart Cities Mission.
Network optimization holds the largest share; asset tracking is gaining share fastest.
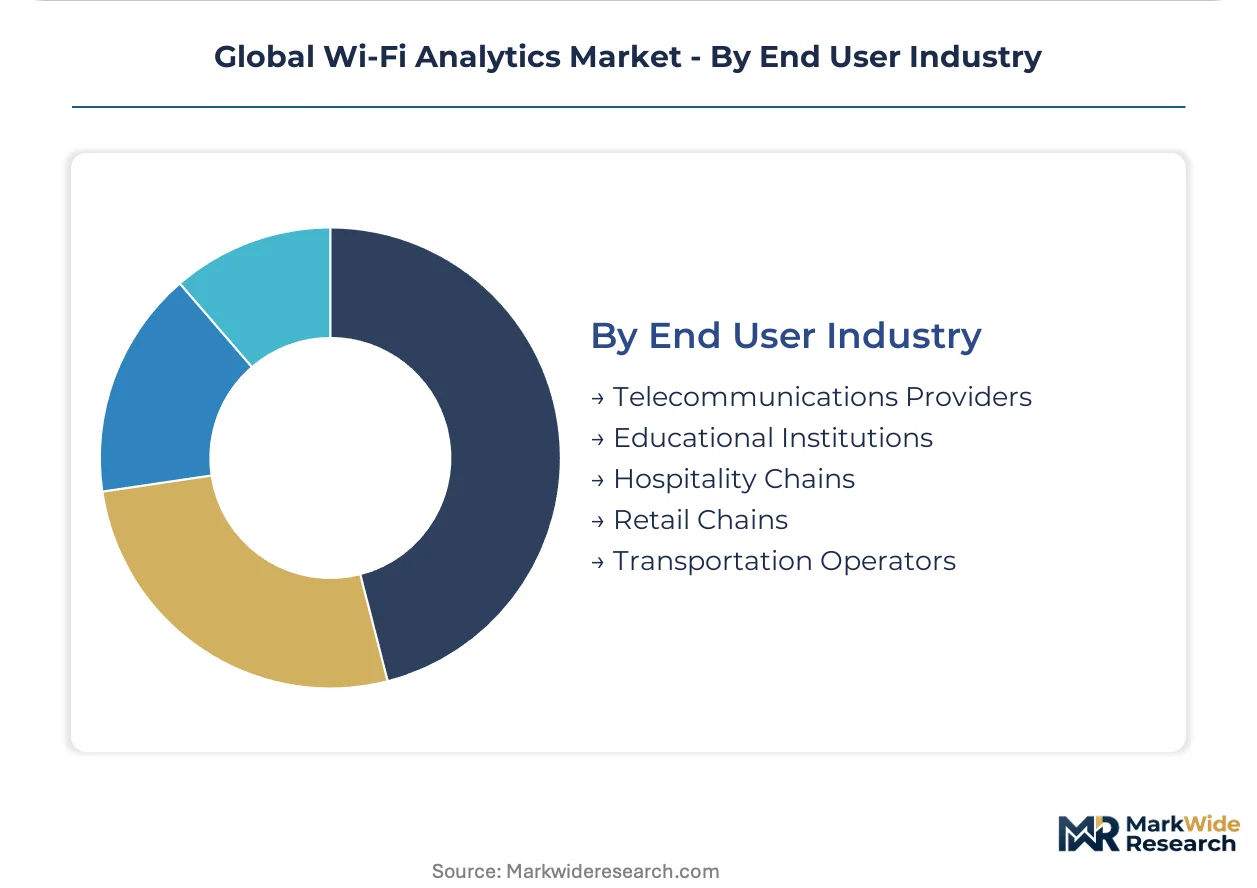
End User Industry:
Retail and hospitality procurement concentrates in North American headquarters, while transportation and education demand localizes to municipal and institutional budgets across fragmented geographies.
- Telecommunications Providers:Public Wi-Fi offload strategies and subscriber analytics platforms require carrier-grade scalability. Verizon and AT&T in the United States, plus SK Telecom in South Korea, drive standardization around OpenRoaming federation. Procurement evaluates billions of daily connection events.
- Educational Institutions:Campus-wide density planning and learning space utilization analytics support capital allocation decisions. Large university systems in California, Texas, and Ontario issue consolidated RFPs covering tens of thousands of access points.
- Hospitality Chains:Brand-consistent guest Wi-Fi and operational dashboards for franchise compliance dominate requirements. Marriott International and Accor standardize on Meraki and Aruba platforms.
- Retail Chains:Unified commerce integration and loss prevention correlation with video analytics shape vendor selection. Walmart and Target mandate pre-built SAP connectors.
- Transportation Operators:Passenger flow prediction and gate congestion management in Hartsfield-Jackson Atlanta and Heathrow Airport demand sub-meter accuracy.
Retail chains hold the largest share; transportation operators show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise-grade Wi-Fi chipset fabrication concentrates in Taiwan and South Korea, creating geographic vulnerability that shapes procurement strategies across end markets. The United States, Germany, Japan, India, and the United Arab Emirates represent distinct demand centers where regulatory frameworks and infrastructure investment cycles diverge sharply.
United States
FCC spectrum allocations for Wi-Fi 6E enable denser access point deployments without co-channel interference, improving sub-meter positioning accuracy for airport and retail applications. NIST zero-trust architecture mandates extend into wireless access layers, accelerating security analytics procurement. Atlanta's Hartsfield-Jackson International Airport deploys real-time passenger flow optimization systems.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria adopt Wi-Fi RTLS for automotive assembly plant asset tracking, integrating telemetry with predictive maintenance platforms. BSI data residency requirements and GDPR Article 25 mandates enforce privacy-preserving probe request anonymization at firmware level. Munich's Siemens AG campus serves as a reference deployment for edge-computing configurations.
Japan
METI smart city initiatives drive municipal transit authority investments in footfall analytics for Tokyo and Osaka metro interchanges. Public Wi-Fi infrastructure standardization around OpenRoaming federation protocols enables seamless cellular-to-Wi-Fi handoff. Nagoya's Chubu Centrair International Airport implements gate congestion prediction systems.
India
Smart Cities Mission funding channels toward municipal crowd management at Delhi, Mumbai, and Bangalore metro interchanges, creating demand for localized data residency architectures. TRAI public Wi-Fi offload regulations shape carrier-grade scalability requirements. Hyderabad's HITEC City technology cluster hosts vendor engineering centers serving South Asian deployments.
United Arab Emirates
Dubai's aviation authority mandates sub-meter RTLS accuracy for passenger flow optimization at Dubai International Airport, driving premium-tier solution procurement. MOHAP data localization guidance influences hybrid deployment architectures balancing cloud scalability with on-premise compliance. Abu Dhabi's Yas Island entertainment district deploys unified commerce integration for hospitality operators.
Global Wi-Fi Analytics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated networking incumbents competing against pure-play analytics specialists. The vendor base stratifies into three tiers: cloud-native SaaS platforms commanding recurring revenue premiums, security-integrated stacks bundling wireless threat detection, and point-solution providers facing margin compression from integration mandates. Dominant competitive moves include M&A activity consolidating authentication layer capabilities and strategic partnerships embedding analytics into unified commerce platforms.
Among integrated networking incumbents, Cisco Systems, Inc. and Fortinet, Inc. exemplify the security-integrated archetype, anchoring large-scale enterprise deployments through existing WLAN infrastructure relationships. Skyfii occupies a position within the pure-play SaaS tier, representing venue intelligence specialists that sustain recurring revenue through customer experience dashboards. Hewlett Packard Enterprise sits within the hybrid archetype, bridging on-premise hardware heritage with cloud-native delivery models.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Cloud4Wi |
| Purple Wi-Fi |
| Fortinet, Inc. |
| Hewlett Packard Enterprise |
| Skyfii |
| GoZone WiFi |
| Euclid |
| RetailNext |
| Others |
Cost & Logistics Intelligence
Long-term SaaS subscription contracts lock in both chipset supply allocation and predictable per-seat pricing for enterprise Wi-Fi analytics vendors serving multi-site retail chains. These arrangements tether cloud-native providers to Taiwan Semiconductor Manufacturing Company and Samsung Foundry wafer commitments while insulating buyers from spot-market volatility in enterprise-grade Wi-Fi 6E silicon.
Pricing Analysis
GDPR Article 25 dictates the pricing tier structure across European deployments, mandating firmware-level anonymization that separates privacy-preserving premium offerings from stripped-down economy tiers lacking probe-request masking. Three-tier pricing structure across premium, standard, and economy levels correlates with certification depth: premium bundles include EU AI Act algorithmic transparency documentation and CNIL-compliant MAC address hashing. Cost compression in the economy tier is intensifying because mid-market retailers in India and Southeast Asia prioritize basic footfall counting over predictive dwell-time modeling. Transportation operators in the United Arab Emirates and Singapore exhibit the lowest price sensitivity, accepting per-access-point premiums for sub-meter RTLS accuracy that manufacturing facilities routinely reject.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates risk for enterprise Wi-Fi chipset fabrication, where Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation anchor global supply alongside Samsung Foundry in South Korea. Raw material dependencies span gallium nitride substrates for 6 GHz power amplifiers, advanced packaging substrates from Japan's Ibiden and Shinko Electric, and rare earth elements for antenna calibration. Single-source vulnerability pervades the 7nm and 5nm node fabrication that enables edge-computing inference at access point level. Distribution runs through Aruba, Cisco, and Fortinet direct sales forces for enterprise accounts, with value-added resellers handling mid-market hospitality and retail procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wi-Fi analytics is approaching a platform-economics inflection where OpenRoaming federation protocols commoditize authentication layers and concentrate value in backend analytics engines interoperating with Salesforce, Shopify, and SAP Commerce Cloud ecosystems.
For Market Incumbents: Shield recurring revenue streams by embedding predictive maintenance modules into building automation partnerships with Siemens and Honeywell, neutralizing the threat of 5G private network substitution in manufacturing environments. Deepen firmware-level GDPR compliance moats through automated technical file generation for EU AI Act audits, raising switching costs for European retail chains. For New Entrants and Emerging Players: Anchor in India's Smart Cities Mission municipal transit deployments, where localized data residency architectures remain underpenetrated by established cloud-native vendors lacking Hyderabad engineering presence. Target asset tracking applications in German automotive assembly plants through edge-computing configurations that bypass the cloud subscription model dominating North American procurement. For Investors and Strategic Acquirers: Pure-play venue intelligence SaaS platforms with pre-built SAP Commerce Cloud connectors represent the most defensible acquisition archetype as unified commerce integration mandates consolidate buyer procurement around integrated platform evaluations. Monitor FCC 6 GHz spectrum reallocation proceedings as the critical inflection signal: expanded channel availability would accelerate sub-meter RTLS adoption and compress implementation timelines for transportation and retail segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built connectors to Salesforce and SAP Commerce Cloud now dominate RFP shortlists for retail chains. |
| Privacy-Preserving Architecture | Firmware-level probe request anonymization satisfies GDPR Article 25 and EU AI Act mandates for European deployments. |
| Edge Computing Deployment | Millisecond-latency inference at Changi Airport and Dubai Metro supports real-time passenger flow alerts. |
| Strategic Partnership | Building automation alliances with Siemens expand addressable market into HVAC and lighting optimization. |
| Acquisition of Specialist Firm | Authentication layer consolidation neutralizes Passpoint protocol fragmentation compressing vendor differentiation. |
Research Approach
The analysis maps cloud-native SaaS platforms, edge-computing configurations, security-integrated stacks, and on-premise installations, each validated through chief technology officers at retail chains, airport operations directors, municipal transit authority planners, and value-added reseller channel heads. Primary interviews with WLAN infrastructure procurement teams at Marriott, Target, and Hartsfield-Jackson Atlanta combined with secondary validation against FCC spectrum allocation dockets, ETSI OpenRoaming technical specifications, and BSI data residency guidance. SEC 10-K filings from Cisco and Fortinet, TRAI public Wi-Fi offload regulations, and EU AI Act implementation guidance from France's CNIL anchored bottom-up and top-down triangulation.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for Meraki cloud infrastructure expansion, carrier-grade Wi-Fi offload statistics from Verizon and AT&T, and Smart Cities Mission funding disbursement records from Indian municipal authorities. Segmentation dimensions modeled across deployment type, solution offering, use case, and end user industry incorporated regional regulatory cluster variations including GDPR Article 22 automated decision-making restrictions and NIST zero-trust architecture mandates. CAGRs derived from logistic diffusion curves fitted to enterprise WLAN refresh cycle compression patterns and Wi-Fi 6E chipset shipment trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained FCC 6 GHz spectrum availability and continued Taiwan-South Korea semiconductor fabrication access; material deviation through export control tightening or geopolitical disruption would warrant model refresh. Practitioners should keep alternative scenarios live as CBRS-based private 5G network evaluations proliferate in manufacturing facilities and EU AI Act enforcement gradients sharpen across member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Italy ICT Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Global Customer Experience Analytics Market
Analytics
Big Data Analytics in BFSI Market
Analytics
Global Operational Analytics Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Emotion Analytics Market
Analytics
India Big Data Analytics Market
Analytics
Global Recommendation Engine Market
Analytics
Sales Intelligence Market
Analytics
Video Analytics Market
Analytics
North America Location Analytics Market
Analytics
Big Data Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
App Analytics Market
Analytics
FMCG Spending on Analytics Market