
 Commodity Supply Chain Management Solution Market | 2026-2036
Commodity Supply Chain Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Commodity Supply Chain Management Solution Market Outlook
Market Dynamics
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring SaaS arrangements. SAP leverages deep ERP integration to anchor enterprise accounts across energy and agriculture verticals. Oracle competes through cloud infrastructure tie-ins that sustain subscription renewal rates. Manhattan Associates specializes in warehouse execution layers that dominate North American food commodity distribution networks.
Technology and Segmentation
Commodity supply chain management solutions encompass software platforms that integrate real-time price feeds, logistics tracking, and contract lifecycle management through API-connected modules. These systems process exchange-traded and over-the-counter commodity positions with sub-second latency for risk calculation and margin call automation. Inventory optimization leads product type segments as metals and grain traders prioritize working capital efficiency over demand forecasting maturity. Cloud-based deployment is accelerating fastest among mid-tier agricultural cooperatives seeking to avoid on-premise infrastructure capital.
Regulatory Environment
EU Green Deal due diligence rules and REACH chemical traceability standards shape platform requirements for European commodity traders documenting origin and processing history. The SEC climate disclosure framework and CFTC position limit reporting obligations extend compliance burdens to US-based energy and metals market participants. Stakeholders must monitor how divergent jurisdictional reporting timelines reshape platform architecture roadmaps and vendor certification priorities.
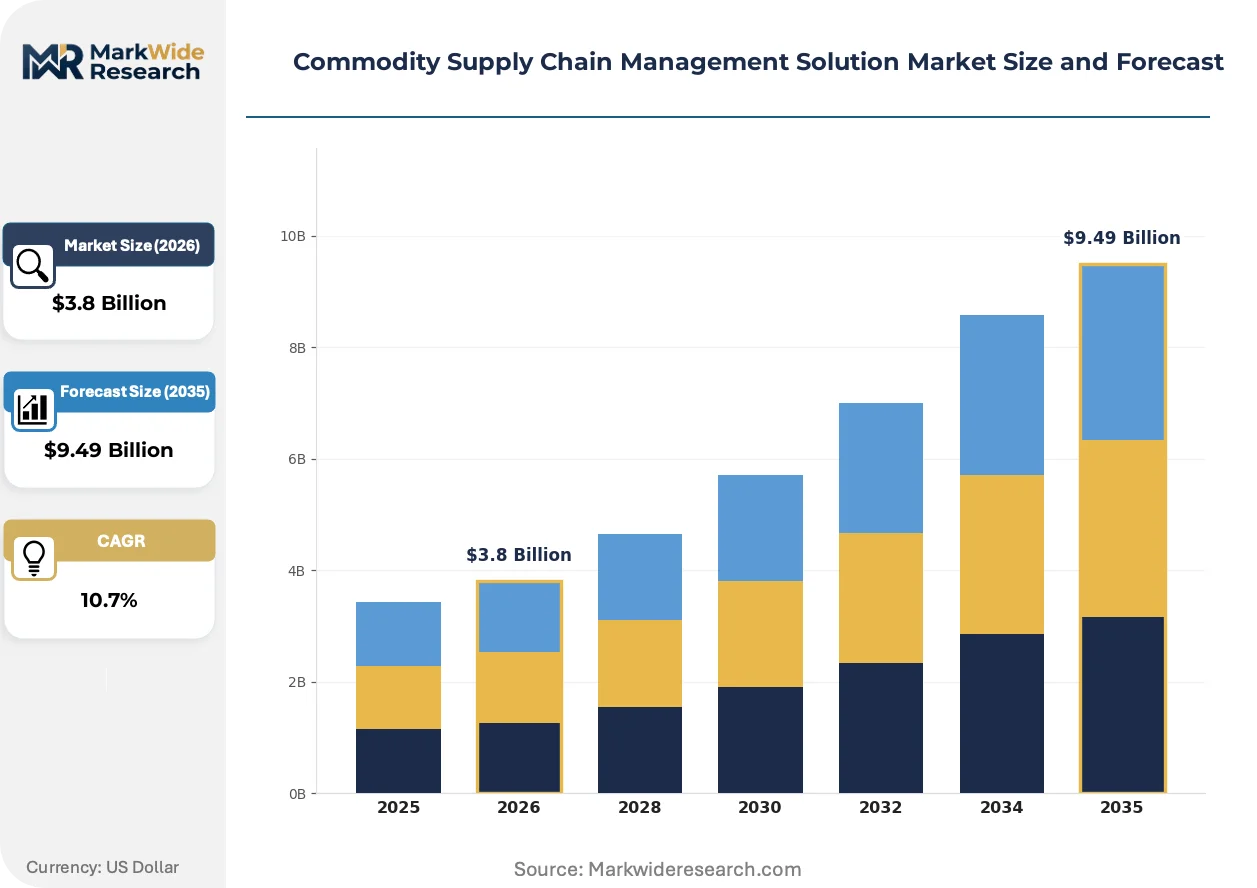
Market Dynamics
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring SaaS arrangements. Agricultural commodity traders in Brazil and energy majors in the US are accelerating cloud migration to manage price volatility and margin compression.
Growth Catalysts
- EU Green Deal due diligence:Mandatory origin documentation requirements are forcing European agricultural traders to adopt traceability modules. This regulatory pressure expands addressable market for compliance-integrated platforms.
- API-connected risk calculation:Real-time position monitoring with sub-second latency enables automated margin call management. Metals and grain traders deploy these capabilities to reduce working capital buffers.
- Brazilian soy export digitization:Agricultural cooperatives in Mato Grosso and Paraná are replacing spreadsheet-based procurement with cloud deployment to eliminate infrastructure capital expenditure.
Market Restraints
- Cloud infrastructure concentration:Mid-tier agricultural cooperatives face vendor lock-in risks with hyperscale providers. Migration costs constrain multi-cloud strategies for price-sensitive buyers.
- Legacy ERP integration complexity:On-premise warehouse management systems in North American food distribution networks resist API connectivity. Technical debt prolongs implementation timelines.
- REACH chemical traceability friction:European commodity traders face documentation gaps between processing history requirements and supplier data availability. Compliance gaps trigger audit exposure.
Strategic Opportunities
- Indian agricultural cooperative penetration:BIS standards alignment and DGFT trade documentation mandates create entry points for SaaS platforms. Digitization remains underdeveloped in Punjab and Haryana grain procurement.
- Blockchain-IoT convergence:Immutable origin records combined with sensor-based logistics tracking address EU Green Deal evidentiary requirements. Joint deployments reduce compliance labor intensity.
- SEC climate disclosure framework:US energy and metals market participants require emissions data integration into contract lifecycle management. Early platform certification captures compliance-driven replacement cycles.
Industry Challenges
- Sub-second latency engineering scarcity:Risk calculation module development demands specialized quantitative infrastructure talent. Agricultural platform vendors compete with fintech for limited developer pools.
- CFTC position limit reporting integration:Energy traders face fragmented data architecture between trading systems and regulatory submission portals. Manual reconciliation consumes operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commodity Supply Chain Management Solution Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.49 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Management, Risk Assessment, Inventory Optimization, Demand Forecasting End User: Agriculture, Manufacturing, Energy, Retail Technology: Blockchain, IoT, Artificial Intelligence, Big Data Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | SAP, Oracle, Infor, Manhattan Associates, E2open, Kinaxis, IBM, Descartes Systems Group, JDA Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commodity Supply Chain Management Solution Market Strategic Shifts
Commodity supply chain platforms are converging around modular API architectures that decouple risk engines from logistics tracking. This structural unbundling enables point-solution specialization while preserving data interoperability across trading workflows.
Real-time price feed integration is migrating from batch-file exchange protocols to streaming API connections. Agricultural cooperatives in Brazil and metals traders in London are adopting these interfaces to compress margin call notification delays from hours to milliseconds. The technology is compressing competitive differentiation around latency performance rather than feature breadth.
REACH chemical traceability standards are extending documentation requirements to secondary processing stages. European commodity traders must now capture transformation records through multi-tier supplier networks. Agricultural chemical inputs and refined metal products face the steepest compliance cost escalation.
Buyer concentration among multinational agricultural traders is compressing vendor negotiation cycles. Tier-one grain merchants now demand outcome-based platform pricing tied to working capital efficiency gains. Brazilian soy exporters and US ethanol processors are piloting these performance-linked arrangements.
Commodity Supply Chain Management Solution Market Segmentation
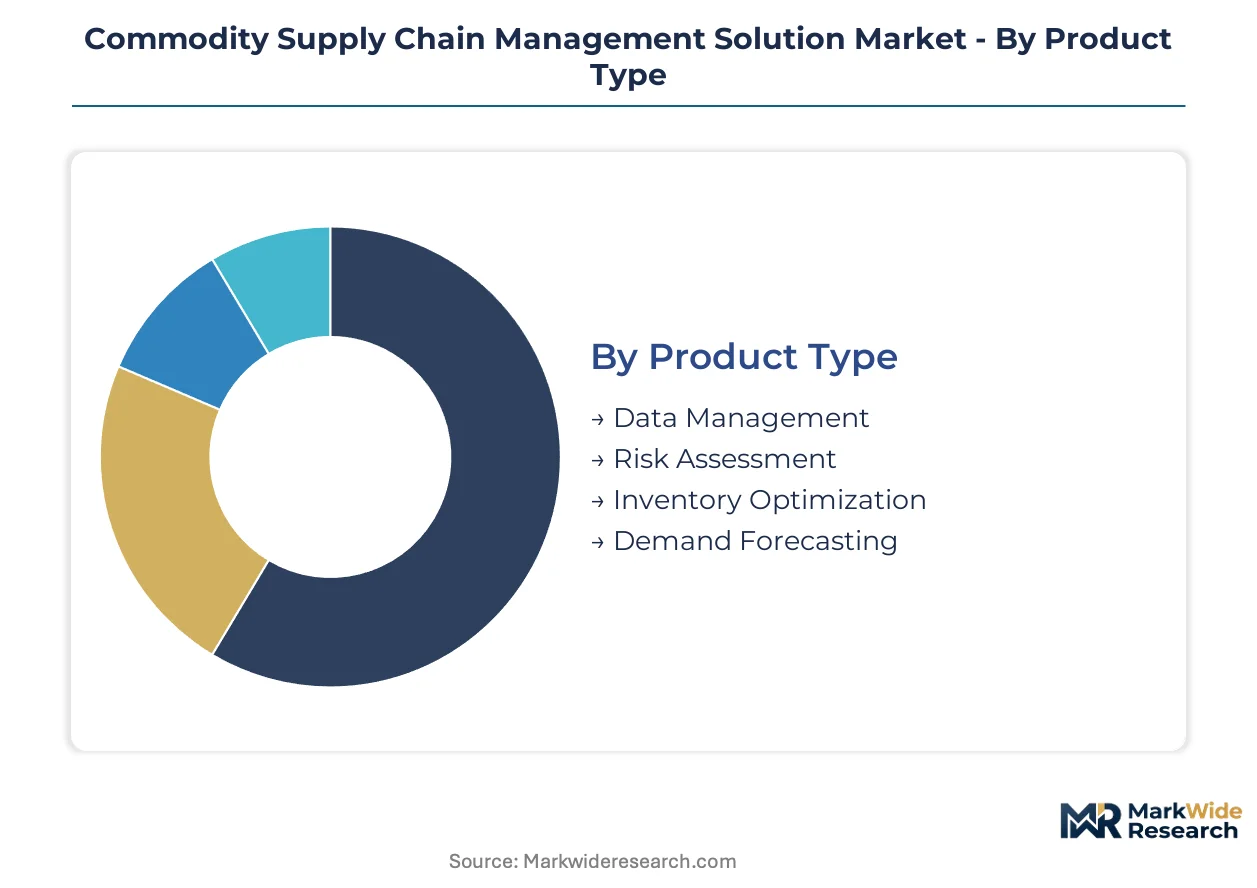
Commodity supply chain platforms segment across functional modules, user verticals, underlying technologies, and infrastructure models. These dimensions determine integration complexity, pricing architecture, and replacement cycle timing for vendors and buyers alike.
Product Type:
Inventory Optimization turns over fastest as working capital pressure forces quarterly module refreshes, while Demand Forecasting cycles slowest due to model validation timelines.
- Inventory Optimization:Working capital efficiency engines process real-time position data to minimize carrying costs and obsolescence risk. Metals traders in London and grain cooperatives in Brazil deploy these modules to compress cash conversion cycles. Agricultural commodity buyers facing margin compression prioritize this capability above all others.
- Risk Assessment:Quantitative engines calculate value-at-risk and margin requirements across exchange-traded and OTC positions. Energy majors in the US integrate these systems with CFTC reporting obligations to automate compliance submission. Sub-second latency requirements differentiate vendor performance tiers.
- Data Management:Master data platforms harmonize contract terms, counterparty profiles, and logistics records across fragmented source systems.
- Demand Forecasting:Predictive models project consumption patterns using weather, macroeconomic, and satellite imagery inputs.
Inventory Optimization dominates installed base. Risk Assessment is where expansion concentrates.
End User:
Agriculture and Energy represent opposite cost tiers — agricultural cooperatives demand per-seat pricing while energy majors absorb enterprise licenses.
- Agriculture:Crop and livestock traders manage harvest timing, storage logistics, and export documentation through integrated platforms. Brazilian soy exporters in Mato Grosso digitize procurement workflows to eliminate spreadsheet-based coordination. EU Green Deal traceability mandates drive compliance module adoption.
- Energy:Oil, gas, and power traders coordinate physical delivery with financial hedging across complex counterparty networks. US-based participants face SEC climate disclosure and CFTC position limit reporting that shapes platform requirements. Margin call automation reduces operational staffing intensity.
- Manufacturing:Industrial buyers manage raw material input streams and supplier quality certification.
- Retail:Grocery and consumer goods chains track agricultural provenance and sustainability credentials for consumer-facing claims.
Agriculture captures the broadest user base. Energy commands the highest contract values.
Technology:
IoT and Blockchain cluster around high-volume, high-documentation applications while AI and Big Data serve analytical intensity.
- IoT:Sensor networks track temperature, humidity, and location across grain silos, shipping containers, and pipeline infrastructure. Brazilian iron ore exporters deploy these systems to document chain-of-custody for European buyers. Real-time telemetry reduces spoilage claims and insurance premiums.
- Artificial Intelligence:Machine learning models optimize route selection, predict equipment failure, and flag anomalous trading patterns. Metals traders use pattern recognition to detect wash trading and market manipulation. Model explainability requirements shape vendor selection criteria.
- Blockchain:Distributed ledger architectures create immutable origin records for EU Green Deal compliance.
- Big Data:Lakehouse architectures consolidate historical price, weather, and satellite data for longitudinal analysis.
Big Data anchors legacy infrastructure. IoT is climbing the fastest as hardware costs decline.
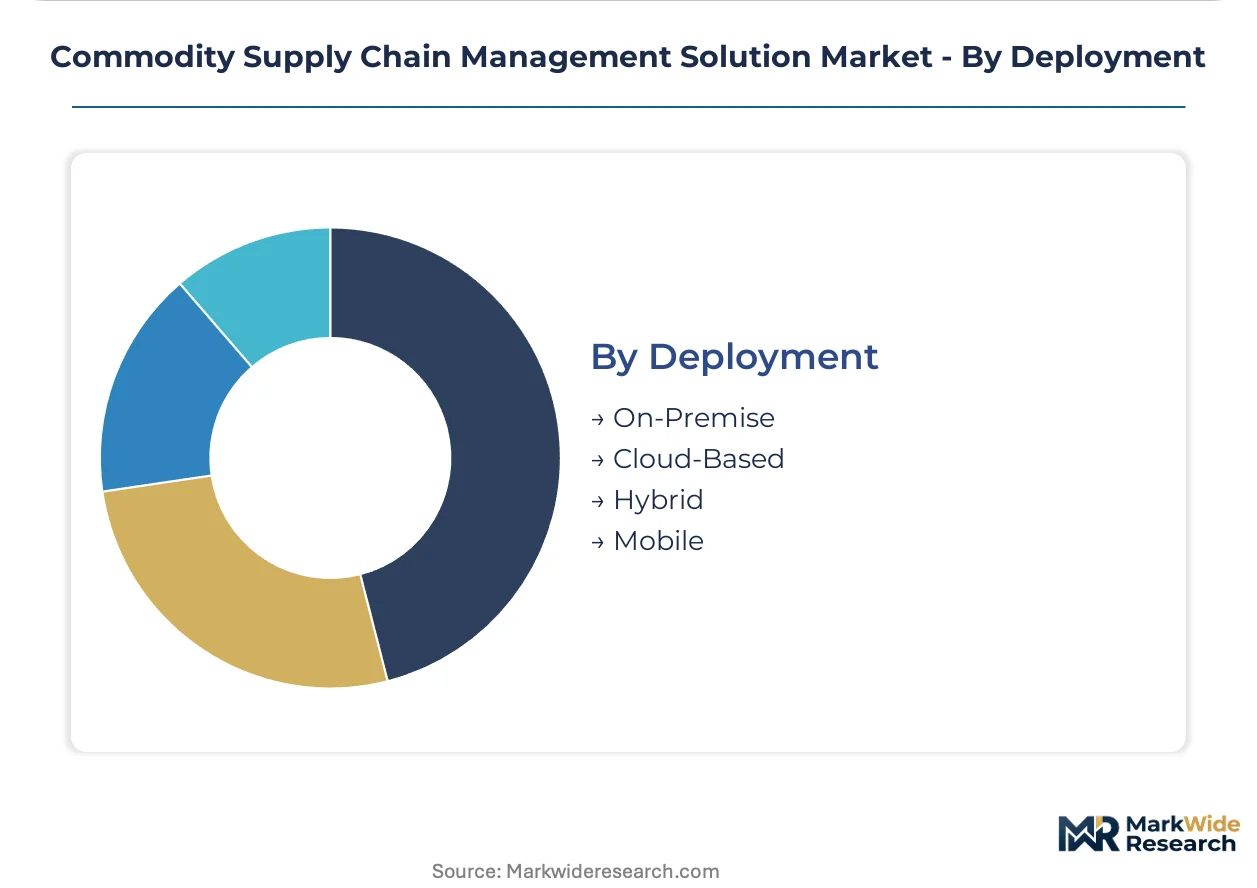
Deployment:
Cloud-Based and On-Premise represent a maturity split — mid-tier buyers skip to cloud while energy majors retain captive infrastructure.
- Cloud-Based:SaaS delivery eliminates capital expenditure and accelerates implementation for resource-constrained buyers. Agricultural cooperatives in Paraná adopt these models to avoid data center investments. Subscription pricing aligns vendor incentives with customer success outcomes.
- Hybrid:Split architectures retain sensitive trading data on-premise while pushing analytics workloads to cloud infrastructure. Energy traders with CFTC reporting obligations use this model to satisfy data residency requirements. Complexity increases integration and staffing costs.
- On-Premise:Captive infrastructure persists among entities with stringent security mandates or legacy system dependencies.
- Mobile:Field-accessible interfaces enable grain elevator operators and port inspectors to capture data at point of origin.
On-Premise retains the largest legacy footprint. Cloud-Based is gaining share fastest among new implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among agricultural cooperatives in Brazil and India contrasts sharply with enterprise license absorption by US energy majors, creating divergent deployment patterns across geographies. Cloud migration accelerates where capital constraints bite hardest. Regulatory fragmentation around traceability mandates reshapes vendor prioritization.
United States
Energy traders and agricultural conglomerates drive platform adoption for CFTC position limit reporting and margin call automation. SEC climate disclosure requirements pressure emissions data integration into contract lifecycle systems. Houston-based energy trading clusters and Chicago agricultural exchanges anchor domestic demand concentration.
Brazil
Soy exporters in Mato Grosso and iron ore operators digitize procurement workflows to eliminate spreadsheet-based coordination. ANVISA traceability protocols for agricultural chemical inputs expand compliance module requirements. Agricultural cooperatives in Paraná state lead cloud deployment adoption among mid-tier buyers.
Germany
Industrial commodity traders face REACH chemical traceability standards extending to secondary processing stages. EU Green Deal due diligence mandates reshape documentation requirements for origin verification. The Rhine-Ruhr logistics corridor concentrates platform deployment for metals and chemicals distribution.
India
BIS standards alignment and DGFT trade documentation mandates create entry points for SaaS platforms in underdeveloped grain procurement regions. Agricultural cooperatives in Punjab and Haryana states lag in digitization relative to southern manufacturing belts. Mumbai-based commodity exchanges drive risk calculation module demand.
China
Dual carbon goals and GB standards for supply chain transparency pressure state-owned energy and metals traders toward platform modernization. MIIT industrial internet initiatives accelerate IoT sensor deployment across port and pipeline infrastructure. Yangtze River Delta commodity trading hubs concentrate procurement digitization investment.
Commodity Supply Chain Management Solution Market Competitive Environment
Capability concentration sits with specialized warehouse execution and risk engine vendors; scale advantage sits with ERP-anchored conglomerates that bundle supply chain modules into enterprise contracts. The market structures around three tiers: horizontal platform giants with deep integration ecosystems, vertical specialists dominating specific commodity workflows, and mid-tier SaaS vendors capturing price-sensitive agricultural cooperatives. Dominant competitive moves include API unbundling to enable point-solution interoperability and outcome-based pricing pilots tied to working capital efficiency metrics.
Among ERP-anchored conglomerates, SAP and Oracle occupy positions exemplifying the bundled-platform archetype through deep enterprise system integration. Manhattan Associates represents the vertical specialist tier with concentrated presence in North American food distribution warehouse execution. Kinaxis sits within the supply chain planning specialist segment, illustrating how modular risk engines decouple from broader logistics platforms.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| Infor |
| Manhattan Associates |
| E2open |
| Kinaxis |
| IBM |
| Descartes Systems Group |
| JDA Software |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud infrastructure concentration in the United States anchors platform delivery costs, pushing margin pools toward recurring SaaS arrangements and compressing perpetual license premiums. Agricultural cooperatives in Brazil and India absorb subscription pricing while energy majors in the United States negotiate enterprise bundles anchored to working capital efficiency outcomes.
Pricing Analysis
After-sales service revenue and extended implementation support drive lifetime value for commodity supply chain vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and API throughput capacity. Pricing pressure stems from buyer consolidation among multinational grain merchants demanding outcome-based contracts tied to inventory turnover metrics. Agricultural cooperatives in Brazil exhibit highest price sensitivity while North American energy traders absorb premium tiers for sub-second latency guarantees.
Supply Chain Analysis
Supply-chain finance facilities and extended payment terms from hyperscale infrastructure providers ease cloud migration for capital-constrained buyers. Software development resources concentrate in the United States, India, and Germany. Platform architecture rests on API modules, real-time data feeds, and compliance certification layers. Single-source vulnerability sits with concentrated cloud infrastructure providers. Distribution runs through direct enterprise sales for energy majors and channel partners for agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among tier-one agricultural traders and energy majors, compressing vendor negotiation cycles and forcing outcome-based pricing pilots. This concentration fragments addressable market access for mid-tier SaaS vendors.
For Market Incumbents: Entrench API unbundling strategies to preserve interoperability moats against modular point-solution entrants. Deepen backward integration into quantitative risk engine development to capture scarce developer talent pools. Anchor enterprise accounts through ERP ecosystem lock-in while defending against cloud-native challengers with latency performance benchmarks. For New Entrants and Emerging Players: Establish a beachhead in Indian agricultural cooperatives where BIS standards alignment creates compliance-driven replacement cycles. Target Punjab and Haryana grain procurement networks with mobile-first deployment models. Pursue blockchain-IoT convergence as a differentiated go-to-market angle for EU Green Deal traceability mandates. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with concentrated warehouse execution or risk engine capabilities that ERP conglomerates will bundle through acquisition. Long-term viability hinges on regulatory certification depth rather than feature breadth. Watch CFTC position limit reporting timeline acceleration as an inflection signal for compliance-integrated platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| API Unbundling | Enables point-solution specialization while preserving data interoperability across trading workflows. |
| Cloud Infrastructure Partnership | Reduces capital expenditure barriers for Brazilian agricultural cooperatives migrating from spreadsheets. |
| Regulatory Certification Investment | Captures EU Green Deal and SEC climate disclosure compliance-driven replacement cycles. |
| Outcome-Based Pricing Pilots | Aligns vendor incentives with working capital efficiency gains demanded by multinational grain merchants. |
| Blockchain-IoT Convergence | Addresses REACH chemical traceability and EU origin documentation with immutable sensor-based records. |
Study Parameters
A spread of perspectives from commodity trading risk officers, agricultural cooperative procurement managers, cloud infrastructure procurement leads, and regulatory compliance directors converged on the working assumptions. Primary interview insights combined with secondary validation from SEC filings, CFTC regulatory notices, EU Green Deal implementation guidance, and Brazilian ANVISA traceability protocols. Bottom-up segment sizing and top-down macroeconomic cross-checks anchored the analytical framework.
Demand-supply balance modeling across the projection horizon captured deployment model preferences, vertical adoption patterns, integration complexity tiers, and regional regulatory cluster variations. CAGRs derived from segment-level growth rate reconciliation and historical technology adoption curve analysis. Forecast inputs incorporated API latency performance benchmarks and compliance module certification timelines.
Sensitivities concentrate around regulatory timeline acceleration, cloud infrastructure pricing volatility, and agricultural commodity margin compression cycles. Forecasts reflect documented assumptions about buyer consolidation trajectories and vendor competitive response patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Community Forum Market
Digital Solutions
Social Computing Market
Digital Solutions
Digital Twin Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
UAE ICT Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market