
 Europe Big Data and Business Analytics Market | 2026-2036
Europe Big Data and Business Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Big Data and Business Analytics Market Intelligence
Data science talent scarcity across the European Union is bifurcating vendor strategies between platform automation and managed services. SAP SE leverages its deep ERP integration to anchor analytics workloads inside existing enterprise workflows. Microsoft Corporation competes through Azure's hybrid cloud architecture, which sustains compliance with data residency requirements in Frankfurt and Amsterdam.
Europe Big Data and Business Analytics encompasses distributed data processing architectures, statistical modeling engines, and visualization layers that transform structured and unstructured information into operational intelligence. Cloud Computing deployments now dominate new capacity additions, while Hadoop-based infrastructure occupies a shrinking but stable niche for batch-heavy legacy workloads. Among End User segments, Healthcare and Manufacturing generate the fastest adoption curves as hospitals deploy predictive patient monitoring and factories integrate sensor streams for defect detection.
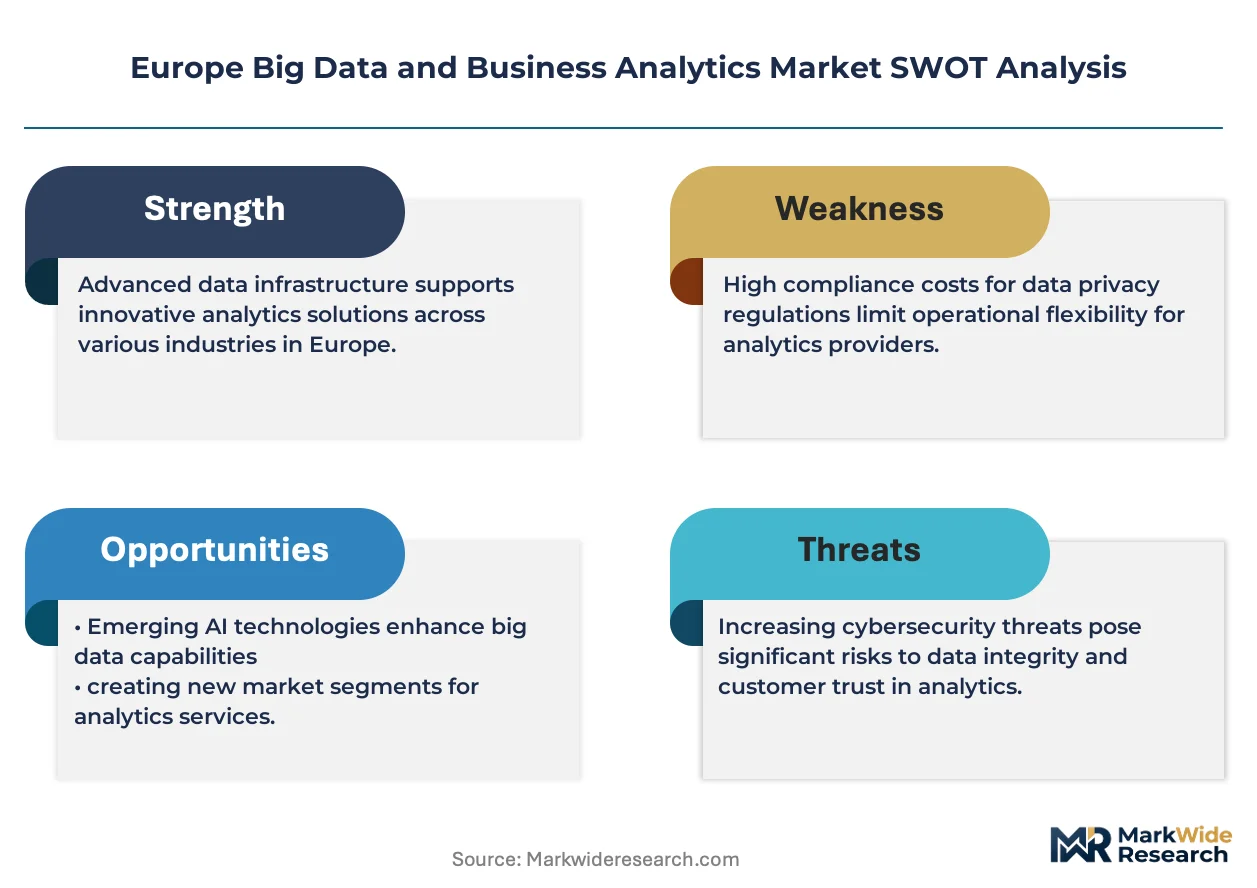
GDPR enforcement by national data protection authorities and the EU AI Act's risk-classification framework jointly elevate demand for auditable, explainable analytics pipelines. EMA guidelines on real-world evidence further shape pharmaceutical analytics procurement in the region. Stakeholders must weigh cloud sovereignty guarantees against the interoperability standards emerging from the European Data Governance Act.
Market Dynamics
GDPR enforcement and the EU AI Act's risk-classification mandates are forcing European enterprises to rebuild analytics pipelines around explainability and auditability rather than raw predictive power.
Growth Catalysts
- EU AI Act compliance deadlines:Enterprises across Germany, France, and the Netherlands are accelerating procurement of interpretable machine learning frameworks to meet prohibited-practice and high-risk system requirements.
- Automotive sensor fusion:German OEMs and tier-one suppliers deploy real-time streaming analytics for predictive maintenance and quality control, embedding analytics directly into manufacturing execution systems.
- Healthcare real-world evidence mandates:EMA guidelines on post-market surveillance push pharmaceutical firms toward continuous patient monitoring analytics, expanding demand for compliant data infrastructure.
Market Restraints
- Data residency compliance costs:Strict localization requirements under GDPR and national implementations force duplication of cloud infrastructure across Frankfurt, Amsterdam, and Dublin zones.
- Apache Hadoop legacy lock-in:Batch-processing architectures in established European banks and insurers resist migration to streaming-native platforms, constraining modernization budgets.
- Cloud vendor concentration:Hyperscaler dominance in IaaS layers creates dependency risk for mid-market enterprises seeking multi-cloud failover capabilities.
Strategic Opportunities
- Polish and Romanian nearshore delivery:Lower-cost EU member states with strong technical education pipelines offer expansion paths for analytics service delivery without third-country transfer complications.
- Edge-to-cloud federated learning:Convergence of 5G network slicing and differential privacy techniques enables predictive maintenance across distributed industrial sites without centralizing sensitive operational data.
- CSRD sustainability reporting mandates:The Corporate Sustainability Reporting Directive creates mandatory demand for carbon accounting analytics and supply chain emissions tracking across listed European companies.
Industry Challenges
- MLOps engineering scarcity:European universities produce insufficient practitioners capable of bridging data science experimentation with production-grade pipeline engineering at enterprise scale.
- Interoperability friction:The European Data Governance Act's emerging standards create uncertainty for vendors building cross-border data spaces, delaying product roadmap commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Big Data and Business Analytics Market |
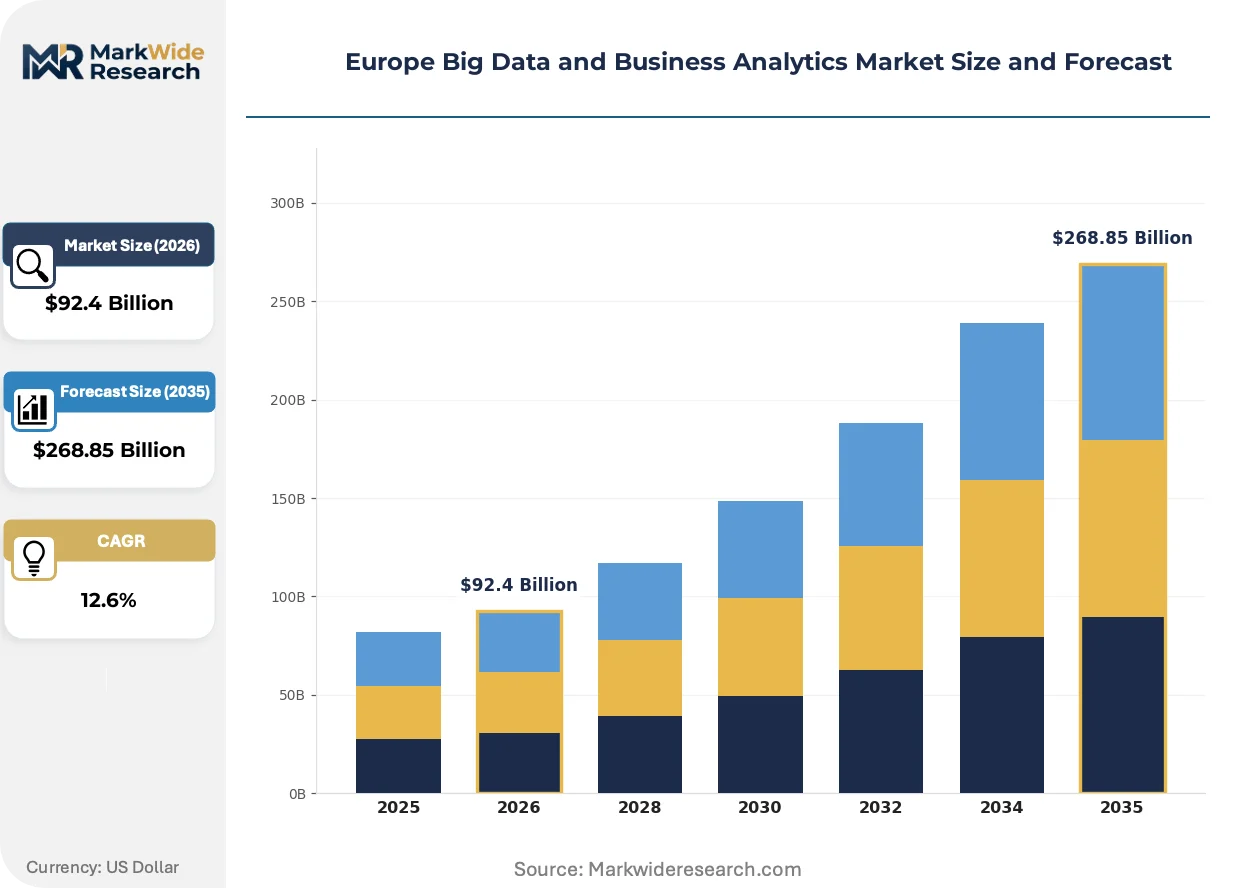
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $268.85 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
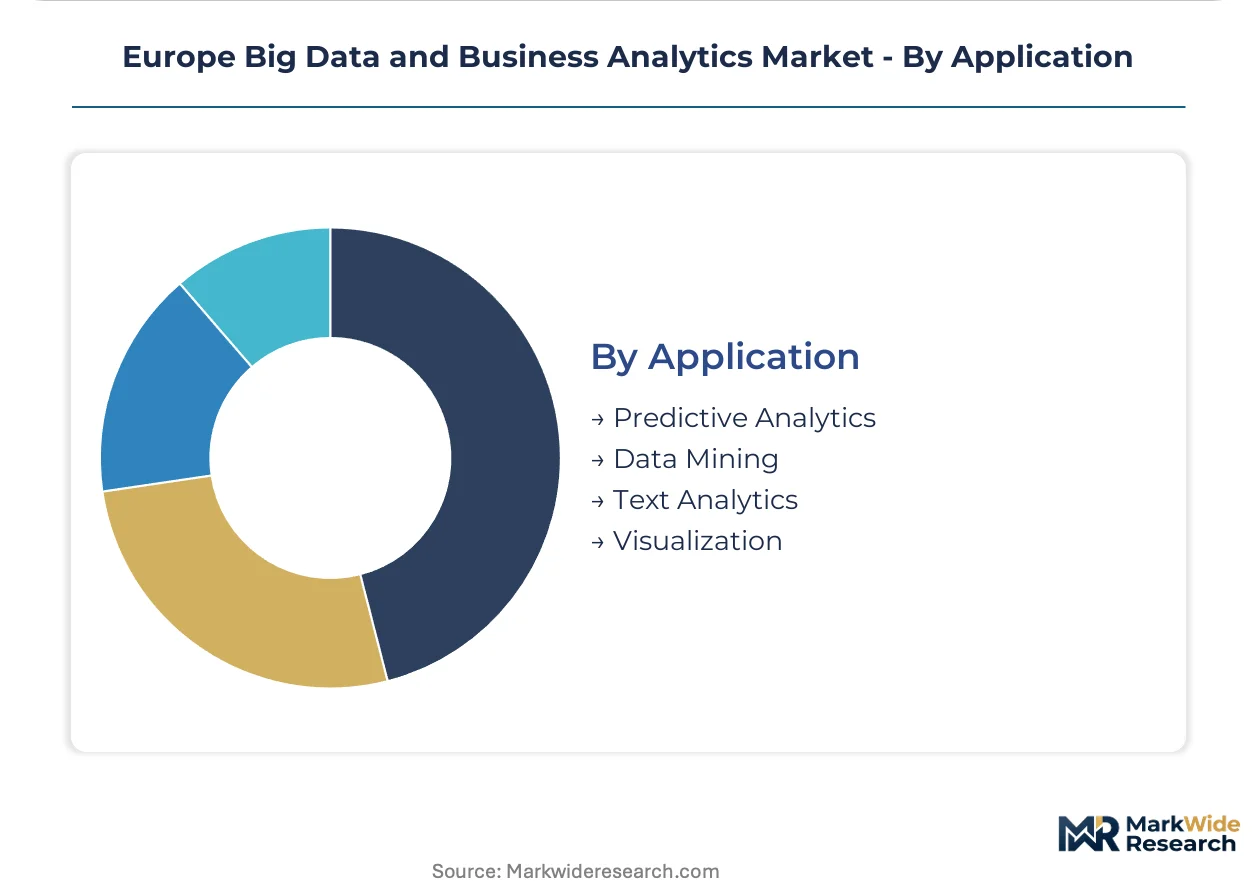
| Segmentation | Technology: Hadoop, NoSQL, Cloud Computing, Data Warehousing End User: Retail, Healthcare, Telecommunications, Manufacturing Deployment: On-Premises, Cloud, Hybrid, Managed Services Application: Predictive Analytics, Data Mining, Text Analytics, Visualization |
| Companies Covered | Amazon Web Services, IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Hewlett Packard Enterprise, SAS Institute, TIBCO Software, Teradata Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Big Data and Business Analytics Market Strategic Shifts & Innovations
European analytics markets are pivoting from centralized data lakes toward distributed architectures that preserve sovereignty while enabling cross-organizational collaboration. This structural reconfiguration touches infrastructure, compliance tooling, and procurement patterns simultaneously.
Embedded analytics is miniaturizing decision intelligence into operational software rather than standalone dashboards. Manufacturing ERP systems from SAP and specialized vendors now ship with native statistical engines. German automotive suppliers embed defect-prediction models directly into shop-floor HMIs, compressing the latency between signal detection and corrective action from hours to seconds.
The EU AI Act's prohibited-practices list and high-risk system obligations are reshaping vendor liability structures. Providers of credit-scoring, recruitment, and biometric identification analytics must now maintain technical documentation, human oversight protocols, and conformity assessments. French and Italian regulators have begun pre-market consultation processes, creating a compliance pathway that delays launch timelines but reduces retroactive enforcement risk.
Hospital procurement departments now bundle analytics subscriptions with electronic health record renewals rather than acquiring point solutions separately. This consolidation favors platforms with pre-certified GDPR compliance and EMA-aligned audit trails. Nordic hospital networks have pioneered this shift, with Central European health systems now following the procurement template.
Europe Big Data and Business Analytics Market Segmentation
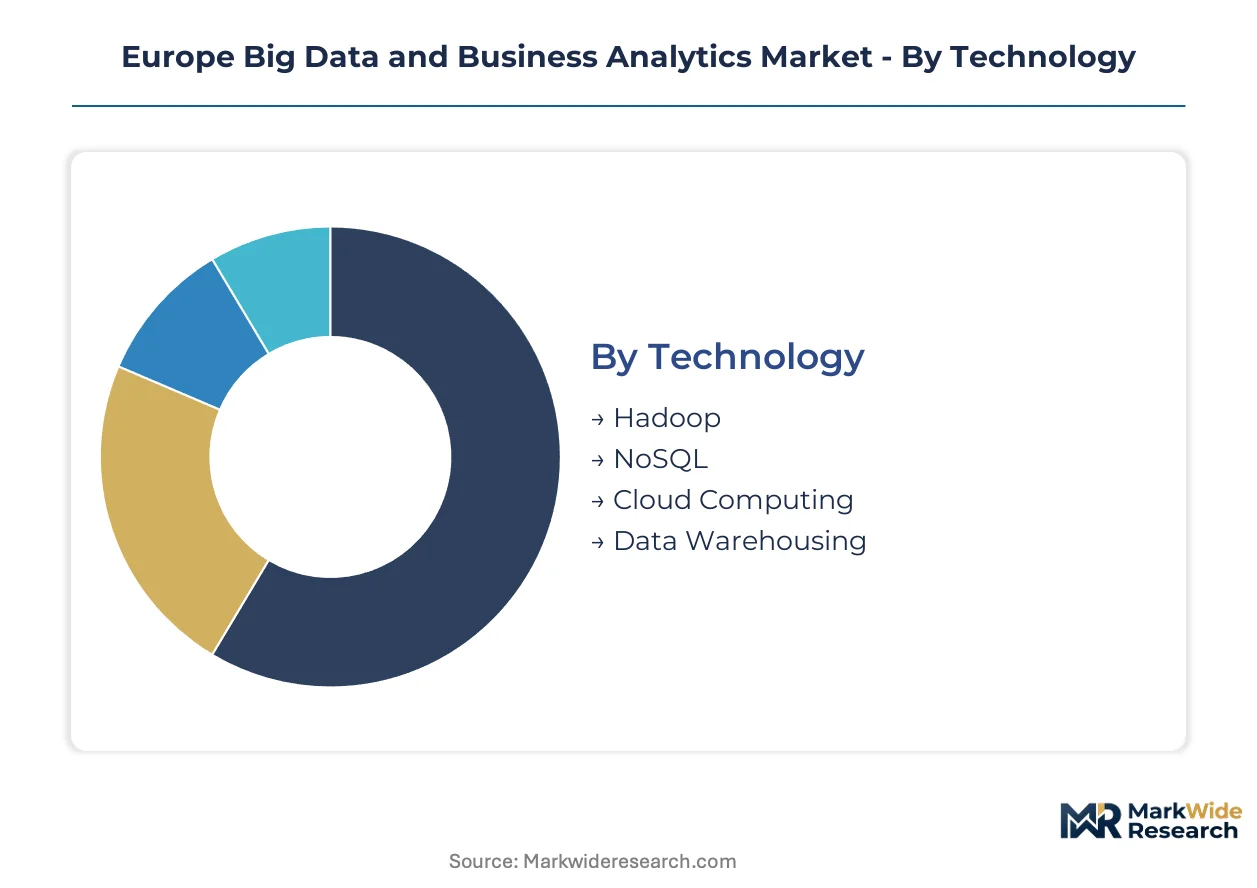
European enterprises navigate divergent compliance obligations across GDPR, EU AI Act, and national implementations, fragmenting procurement patterns by technology maturity and auditability requirements. Segmentation reveals where regulatory pressure reshapes infrastructure choices versus where operational efficiency drives adoption.
Technology:
GDPR data residency mandates and EU AI Act explainability requirements differentiate technology selection, with cloud architectures facing stricter sovereignty scrutiny than on-premise alternatives.
- Cloud Computing:Distributed architectures with region-locked data centers in Frankfurt, Amsterdam, and Dublin satisfy GDPR localization without sacrificing elasticity. German automotive OEMs and French pharmaceutical firms dominate private-cloud deployments, driven by EMA audit trail requirements and real-time manufacturing analytics needs.
- Hadoop:Batch-processing frameworks persist in established European banking and insurance infrastructure despite streaming-native alternatives. Legacy lock-in constrains migration budgets at institutions with decades of historical risk data formatted for MapReduce operations.
- NoSQL:Schema-flexible databases accommodate unstructured sensor streams from industrial IoT deployments.
- Data Warehousing:Centralized repositories serve regulatory reporting and consolidated business intelligence for mid-market enterprises.
Established volume favors Hadoop; emerging adoption favors Cloud Computing.
End User:
Customer type determines whether procurement prioritizes patient safety compliance, supply chain traceability, or consumer privacy protection.
- Healthcare:EMA guidelines on real-world evidence and post-market surveillance mandate continuous patient monitoring infrastructure. Nordic hospital networks bundle analytics with electronic health record renewals, requiring pre-certified GDPR compliance and auditable data lineage.
- Manufacturing:German OEMs and tier-one suppliers embed predictive maintenance models directly into manufacturing execution systems. Shop-floor HMIs compress defect detection-to-correction latency from hours to seconds, driven by automotive quality standards.
- Retail:Customer analytics faces GDPR consent-management complexity and prohibited-practice restrictions under EU AI Act.
- Telecommunications:Network operators leverage subscriber data for churn prediction within strict data retention limits.
Healthcare claims the steepest expansion trajectory; Manufacturing holds the deepest incumbent penetration.
Deployment:
Infrastructure location choices reflect trade-offs between operational control and regulatory audit burden.
- Hybrid:Split workloads allow sensitive data processing on-premise while bursting analytics compute to sovereign cloud regions. Dutch and Belgian enterprises favor this model for balancing GDPR compliance with cost optimization.
- Cloud:Fully outsourced infrastructure dominates new capacity additions among mid-market firms lacking dedicated security engineering.
- On-Premises:Air-gapped systems persist in defense and critical infrastructure sectors with national security classifications.
- Managed Services:Polish and Romanian delivery centers offer EU-based technical operations without third-country transfer complications.
Hybrid deployments gain share fastest; On-Premises contracts face renewal pressure.
Application:
Use case selection tracks whether decision latency requirements favor batch insight generation or real-time inference.
- Predictive Analytics:Machine learning models forecasting equipment failure, patient deterioration, or credit default require EU AI Act conformity assessments for high-risk system classification. French and Italian regulators have initiated pre-market consultation pathways.
- Visualization:Self-service dashboards democratize data access but must embed audit logging for GDPR accountability.
- Data Mining:Pattern discovery in historical datasets supports pharmaceutical research and fraud detection.
- Text Analytics:Natural language processing of clinical notes and customer communications faces consent and anonymization constraints.
Predictive Analytics climbs the fastest; Visualization retains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturers deploy real-time analytics for predictive maintenance at volumes unmatched elsewhere in Europe, while Nordic healthcare systems lead in bundling analytics with electronic health record renewals.
Germany
Bavarian automotive OEMs and Baden-Württemberg machinery producers drive private-cloud analytics deployment for shop-floor sensor fusion. The EU AI Act's high-risk system obligations force conformity assessments for predictive maintenance algorithms. Stuttgart-based tier-one suppliers embed defect-detection models directly into manufacturing execution systems, compressing response latency from hours to seconds.
France
Parisian banking consortia embed real-time risk analytics into core operations under ECB supervisory scrutiny. ANSM and CNIL pre-market consultation processes create compliance pathways that delay launch timelines but reduce retroactive enforcement risk. Île-de-France pharmaceutical clusters expand continuous patient monitoring infrastructure to satisfy EMA real-world evidence guidelines.
United Kingdom
London financial services firms navigate post-Brexit data transfer constraints while maintaining GDPR-equivalent standards. The Financial Conduct Authority's operational resilience requirements push cloud analytics procurement toward sovereign infrastructure. Scottish health boards pioneer federated learning architectures for clinical research without centralizing sensitive patient records.
Netherlands
Amsterdam data center zones attract GDPR-compliant cloud workloads from mid-market enterprises lacking dedicated security engineering. Dutch agritech clusters deploy edge-to-cloud analytics for precision farming across distributed greenhouse operations. Rotterdam logistics hubs integrate supply chain emissions tracking to satisfy CSRD sustainability reporting mandates.
Poland
Warsaw and Krakow delivery centers offer EU-based technical operations for analytics managed services without third-country transfer complications. Polish technical universities feed engineering pipelines that alleviate MLOps scarcity constraining enterprise-scale deployments. Silesian manufacturing zones adopt predictive analytics for industrial machinery retrofit programs.
Europe Big Data and Business Analytics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscalers and ERP-anchored platforms commanding infrastructure layers while niche vendors capture vertical-specific compliance tooling. The market structure reflects data residency requirements that reward established cloud presence over challenger innovation. Two strategic archetypes dominate: sovereign-cloud infrastructure providers and compliance-embedded analytics platforms. Competitive moves concentrate on geographic data center expansion and pre-certified regulatory compliance modules.
Within the integrated platform tier, Microsoft Corporation and SAP SE exemplify divergent anchoring strategies—Azure's hybrid architecture sustains Frankfurt and Amsterdam data residency, while SAP leverages ERP integration to embed analytics inside existing workflows. Amazon Web Services occupies a position as the scale-driven hyperscale alternative. Specialists in explainable machine learning frameworks include SAS Institute, which represents the vertical-specific compliance tooling archetype for regulated industries.
| Leading Market Players |
|---|
| Amazon Web Services |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Hewlett Packard Enterprise |
| SAS Institute |
| TIBCO Software |
| Teradata Corporation |
| Others |
Cost & Logistics Intelligence
GDPR certification tiers and EU AI Act conformity assessments gate both vendor qualification and price differentiation simultaneously, forcing mid-market buyers toward standardized SaaS bundles while enterprise procurement prioritizes sovereign-cloud premiums for audit-trail guarantees.
Pricing Analysis
Long-term enterprise licensing contracts dominate analytics procurement for German automotive OEMs and French pharmaceutical clusters, while spot consumption models gain traction among Dutch mid-market firms lacking dedicated compliance engineering. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with GDPR-plus-AI-Act bundled offerings commanding substantial premiums over baseline cloud subscriptions. Cost compression in the standard tier is intensifying because Polish and Romanian delivery centers are expanding managed services capacity without third-country transfer complications. Healthcare procurement committees exhibit highest price sensitivity due to bundled EHR renewal negotiations, whereas defense and critical infrastructure buyers prioritize air-gapped sovereignty over cost optimization.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for specialized hardware accelerators deployed in Frankfurt and Amsterdam data center zones, compressing margins for on-premise infrastructure vendors. Supply concentrates in Ireland, Germany, and the Netherlands for hyperscale cloud capacity, while specialized edge-computing hardware draws from Taiwan and South Korea. Raw material dependencies span NVIDIA GPUs, high-bandwidth memory modules, and precision cooling systems. Single-source vulnerability in AI accelerator supply creates procurement risk for real-time analytics deployments. Distribution runs through direct enterprise sales teams for large accounts and cloud marketplaces for mid-market self-service adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of MLOps engineers capable of bridging experimentation with production-grade pipelines constrains enterprise-scale deployments, creating asymmetric returns for vendors who solve the talent-to-technology translation gap.
For Market Incumbents: Fortify competitive moats by embedding explainable analytics modules directly into existing ERP workflows, leveraging deep integration to resist displacement by standalone AI platforms. Accelerate certification pre-clearance with French ANSM and Italian regulators to reduce retroactive enforcement exposure. Prioritize sovereign-cloud capacity expansion in Warsaw and Krakow to capture nearshore delivery demand without GDPR transfer complications. For New Entrants and Emerging Players: CE marking fast-track for medical-device-adjacent analytics creates entry pathway into Nordic hospital networks bundling solutions with EHR renewals. Target Polish manufacturing zones adopting predictive maintenance for industrial machinery retrofit programs, where incumbent penetration remains shallow. Pursue federated learning architectures for clinical research as differentiated go-to-market angle, addressing Scottish health board demand for decentralized patient data analysis. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed analytics consultancies holding GDPR-specialist talent pools but lacking platform scalability. Five-to-ten year viability hinges on regulatory compliance automation rather than raw algorithmic performance. Monitor EMA real-world evidence guideline enforcement intensity as inflection indicator for pharmaceutical analytics infrastructure spend.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics engines into SAP ERP workflows captures manufacturing execution system demand in Baden-Württemberg. |
| Geographic Expansion | Warsaw and Krakow delivery centers exploit EU technical education pipelines without third-country transfer constraints. |
| Regulatory Pre-Certification | ANSM and CNIL consultation pathways reduce retroactive enforcement risk for high-risk system deployments. |
| Strategic Partnership | Hospital system alliances in Nordic networks consolidate procurement through bundled EHR-analytics subscriptions. |
| Acquisition of Specialist Firm | Explainable ML frameworks from SAS Institute archetype address EU AI Act technical documentation mandates. |
Research Approach
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners and secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory submission databases anchors the qualitative findings. Bottom-up triangulation across deployment model, organization size, vertical integration complexity, and regional adoption pattern segments converges with top-down macroeconomic sensitivity checks. The analysis draws from enterprise software purchasing patterns and cloud infrastructure spend disclosures.
Sensitivity analysis around GDPR enforcement intensity and EU AI Act implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, end-user industry, deployment location, and application latency requirements. CAGRs derive from installed base evolution and new capacity addition trajectories, with cloud-native platform substitution rates and legacy Hadoop migration constraints as industry-specific forecast inputs.
Underlying assumptions cover sustained regulatory enforcement consistency and cloud sovereignty guarantee durability, with deviation risk concentrated in European Data Governance Act interoperability standard delays and hyperscaler market concentration policy interventions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Contact Center Intelligence Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Europe Retail Analytics Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Content Analytics Software Market
Analytics
North America HR Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Content Analytics and Search Software Market
Analytics
UK Geospatial Analytics Market
Analytics
Capacity Management Analytics Market
Analytics
UK Video Analytics Market
Analytics
Manufacturing Analytics Market
Analytics
Service Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Advanced Analytics Market