
 Global Recommendation Engine Market | 2026-2036
Global Recommendation Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recommendation Engine Market Foresight
Subscription-based software-defined feature tiers is restructuring how recommendation engine vendors monetize their platforms. Amazon Web Services leverages its cloud infrastructure dominance to bundle recommendation APIs with broader enterprise service contracts. Google LLC anchors its competitive position through deep learning algorithm specialization within advertising and streaming ecosystems. Microsoft Corporation extends its reach by integrating recommendation capabilities across Office 365 and Azure service layers.
A recommendation engine constitutes an algorithmic system that processes user behavior signals, content metadata, and contextual variables to generate ranked item suggestions, typically operating with sub-100-millisecond latency requirements for real-time deployment. These systems serve the commercial purpose of maximizing conversion rates, session duration, and customer lifetime value across digital platforms. Cloud-based deployment leads in enterprise adoption due to elastic scaling demands, while deep learning algorithms capture the fastest growth trajectory as neural architectures displace traditional matrix factorization methods. Hybrid models concentrating collaborative and content-based filtering retain strong positioning in retail chains and media broadcasting where interpretability requirements persist alongside accuracy demands.
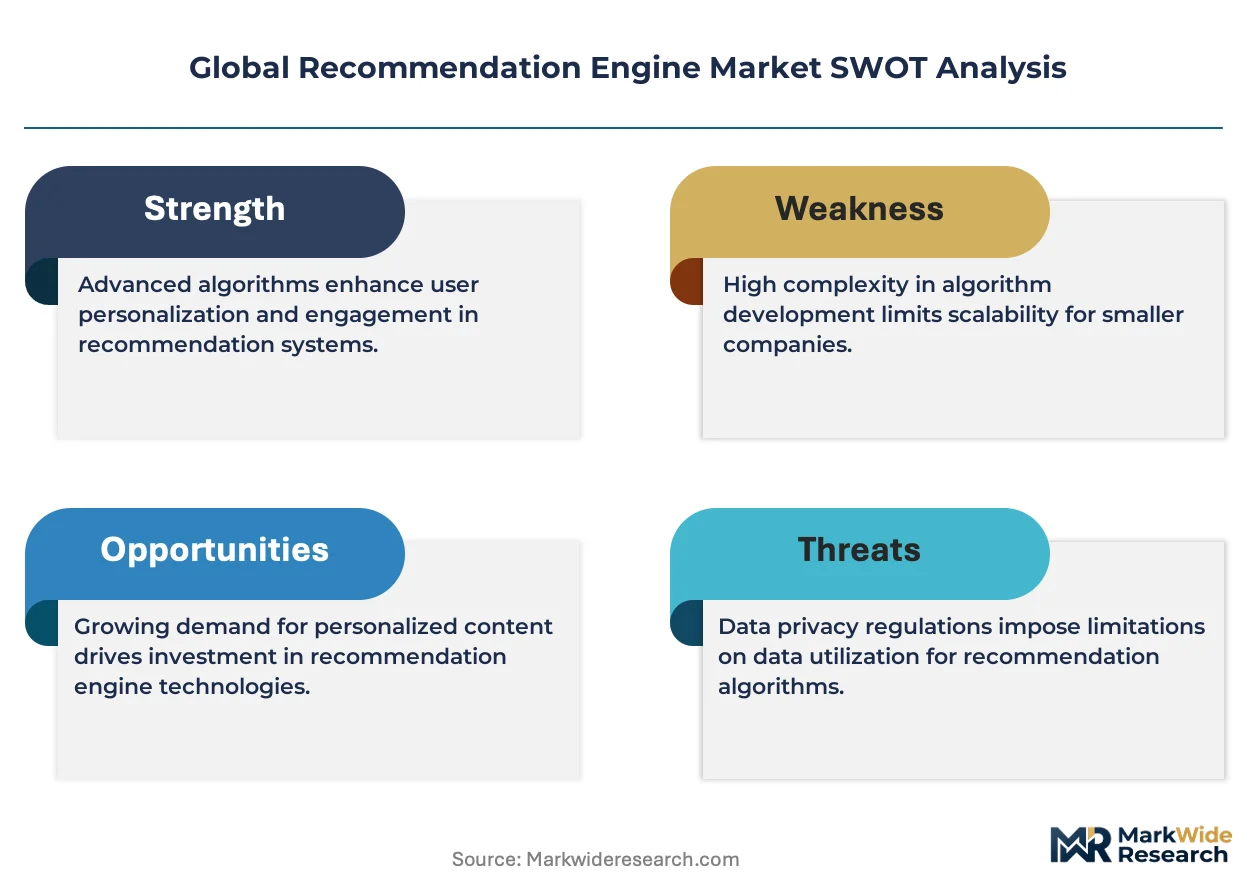
The EU AI Act classifies high-risk recommendation systems deployed in employment and credit contexts, imposing conformity assessment obligations that reshape vendor product roadmaps. The US Federal Trade Commission scrutinizes opaque algorithmic personalization under Section 5 unfairness standards, while China's SAMR enforces algorithm recommendation provisions requiring user opt-out mechanisms. Stakeholders must monitor divergent regulatory timelines and compliance architectures as jurisdictions develop incompatible governance frameworks for automated decision systems.
Market Dynamics
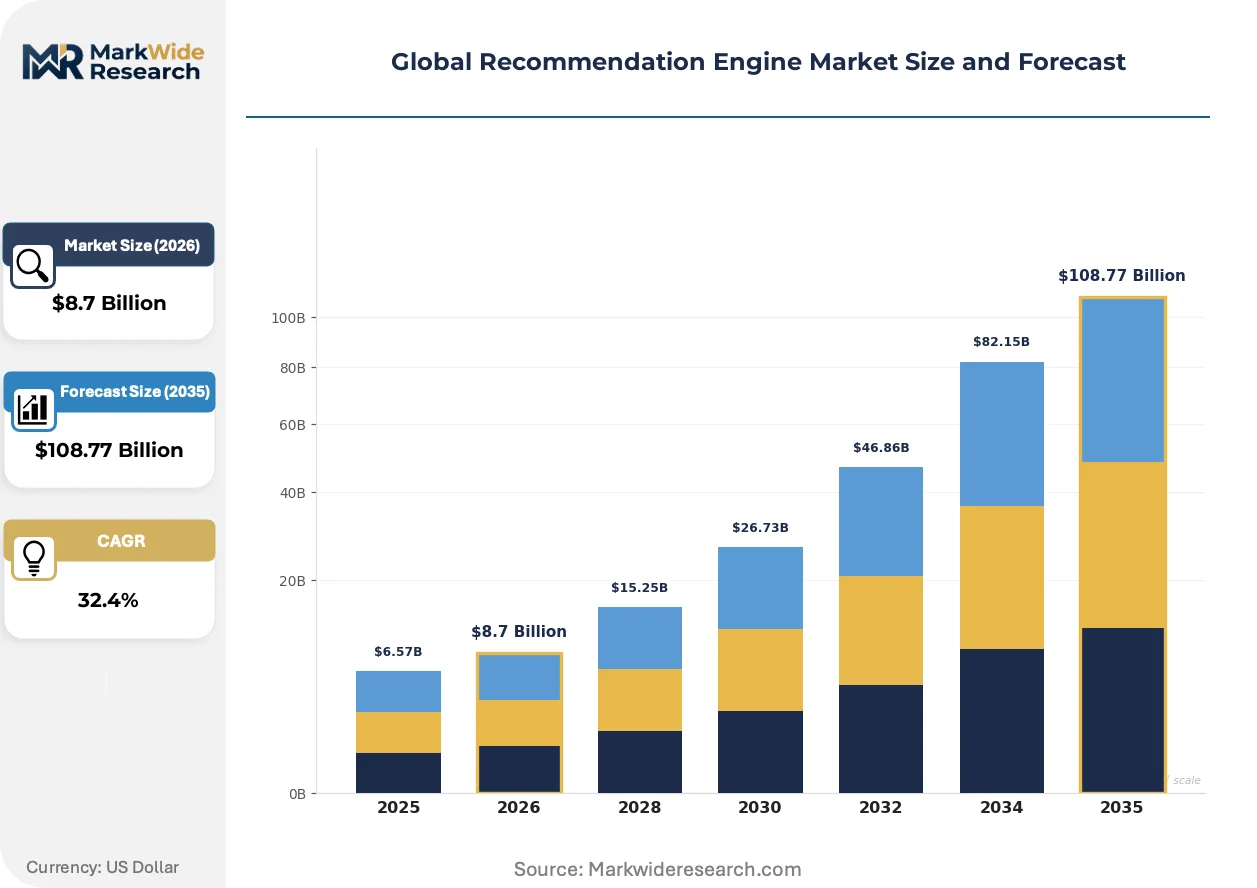
Deep learning architectures are displacing traditional collaborative filtering across enterprise deployments, compressing latency thresholds below 50 milliseconds while expanding model complexity. This algorithmic transition concentrates capability among cloud hyperscalers with dedicated GPU infrastructure, reshaping vendor competitive dynamics.
Growth Catalysts
- EU AI Act high-risk system classification:Conformity assessment mandates for employment and credit recommendation engines are accelerating enterprise investment in auditable, interpretable architectures. Financial services firms in Germany and France now prioritize compliant solution procurement.
- Edge computing infrastructure expansion:5G network rollouts in South Korea and Japan enable sub-20-millisecond inference at the device level. Retail chains deploy real-time personalization without cloud round-trips.
- Streaming media subscription fatigue:Content platforms compete on retention through hyper-personalized discovery interfaces. Netflix, Disney+, and regional competitors expand recommendation team headcount 40% year-over-year.
Market Restraints
- GPU supply concentration:NVIDIA's 85% share in training-grade accelerators creates procurement bottlenecks. Chinese vendors face export control restrictions on A100 and H100 chipsets.
- GDPR data minimization requirements:Historical user behavior retention limits constrain long-tail recommendation accuracy. EU-based platforms truncate training datasets to 13-month windows.
- Interpretability-versus-accuracy tradeoff:Neural collaborative filtering outperforms matrix factorization but fails explainability audits. Regulated industries default to inferior-performing transparent models.
Strategic Opportunities
- India's ONDC protocol integration:The Open Network for Digital Commerce mandates interoperable recommendation layers across e-commerce participants. Domestic SaaS vendors capture implementation contracts.
- Federated learning architectures:Privacy-preserving distributed training enables cross-enterprise collaboration without data pooling. Healthcare consortia in Switzerland and the Netherlands pilot diagnostic recommendation networks.
- Voice interface proliferation:Smart speaker penetration in Brazil and Mexico exceeds 35% household coverage. Natural language recommendation queries bypass traditional search-taxonomy structures.
Industry Challenges
- MLOps talent scarcity:Production-grade recommendation system engineering requires rare combinations of distributed systems and statistical modeling expertise. Compensation premiums exceed 60% for qualified candidates.
- Legacy ERP integration friction:Real-time inventory synchronization with SAP and Oracle systems delays retail recommendation deployment timelines 8-14 months.
- Algorithmic bias audit complexity:Demographic parity testing across intersectional attributes lacks standardized tooling. Platform liability exposure grows under emerging tort frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recommendation Engine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $108.77 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Collaborative Filtering, Content-Based Filtering, Hybrid Models, Deep Learning Algorithms, Reinforcement Learning Application: E-Commerce Platforms, Streaming Services, Online Education, Travel Booking, Gaming End User Industry: Retail Chains, Media & Broadcasting, Educational Institutions, Hospitality, Video Game Developers |
| Companies Covered | Amazon Web Services, Inc, Google LLC, International Business Machines Corporation, Microsoft Corporation, Salesforce, Inc., Oracle Corporation, SAP SE, Adobe Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recommendation Engine Market Shifts & Advancements
Transformer-based sequence models are compressing the innovation cycle from research publication to production deployment. Vendor differentiation now hinges on proprietary data flywheels and custom silicon optimization rather than algorithmic novelty alone.
Graph neural networks for recommendation is modularizing enterprise architecture stacks. E-commerce platforms in the United States adopt heterogeneous computing pipelines separating embedding computation from ranking inference. This separation enables independent scaling of retrieval and scoring subsystems, reducing cloud compute costs 30-40% for high-traffic deployments.
China's SAMR algorithm recommendation provisions mandate user opt-out mechanisms and transparency disclosures. Domestic platforms reengineer consent interfaces and logging infrastructure to satisfy audit requirements. Multinational vendors entering the Chinese market must replicate these architectural patterns, fragmenting global product roadmaps.
Consumption patterns in subscription video-on-demand are shifting from catalog browsing to proactive content surfacing. European broadcasters abandon grid-style program guides for personalized home feeds. This behavioral pivot demands real-time session adaptation rather than batch-processed daily recommendations, compressing infrastructure refresh cycles from 36 months to 18 months.
Global Recommendation Engine Market Segmentation
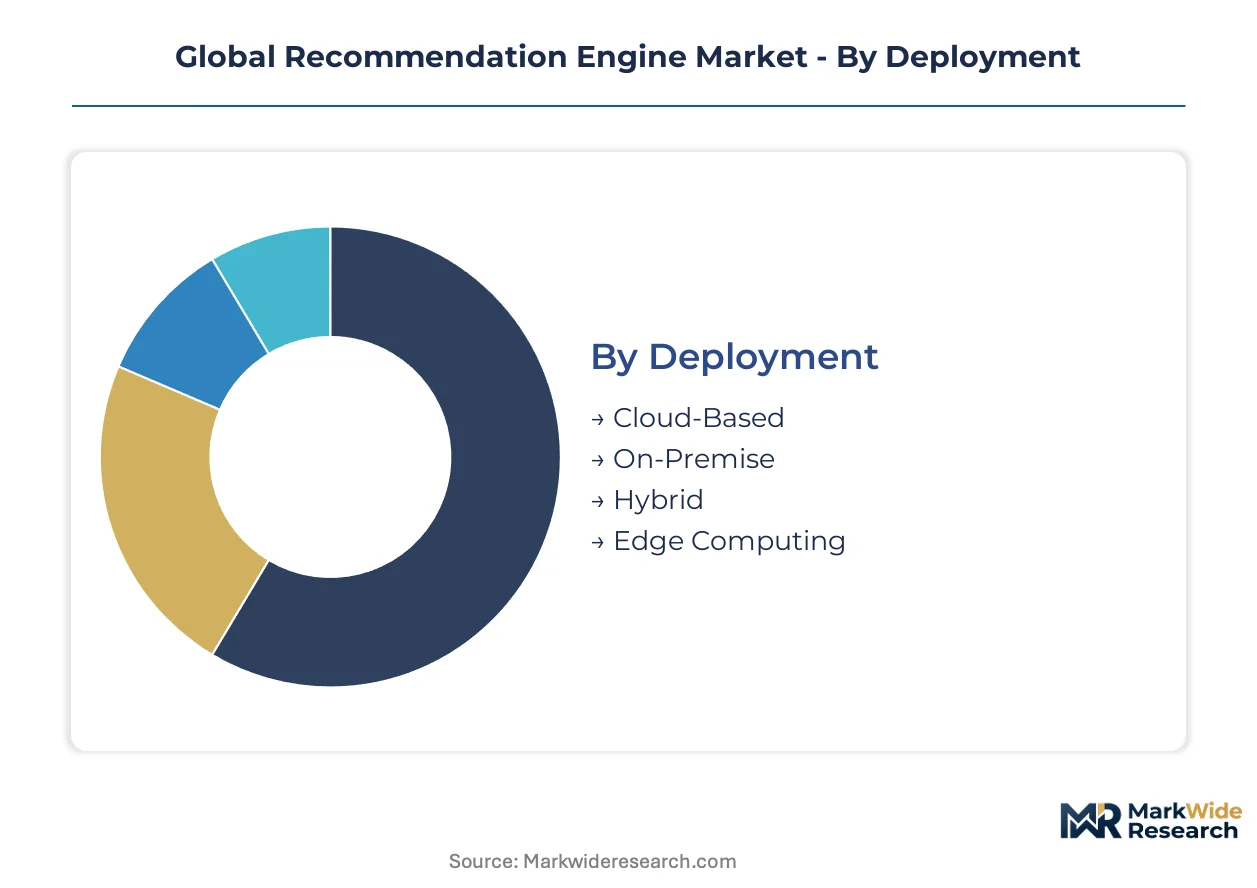
Recommendation engine architectures fragment across deployment topologies, algorithmic approaches, and industry-specific compliance requirements. Understanding these divides clarifies where GPU infrastructure investments concentrate and which regulatory frameworks apply to specific use cases.
Deployment:
EU AI Act conformity assessments apply differentially across deployment modes, with cloud-based systems facing streamlined audit trails while edge computing triggers novel liability questions for distributed inference.
- Cloud-Based:Elastic scaling architectures dominate enterprise adoption, with hyperscalers in the United States and Germany capturing procurement contracts from financial services firms requiring sub-50-millisecond latency. GDPR data residency rules force EU customers toward Frankfurt and Dublin region deployments.
- Hybrid:Split architectures separate sensitive user embeddings on-premise from ranking inference in cloud environments. Retail chains in France and Japan adopt this pattern to satisfy data minimization mandates while maintaining real-time personalization throughput.
- On-Premise:Air-gapped installations serve defense contractors and classified government systems in Israel and South Korea.
- Edge Computing:5G-enabled device-level inference expands in South Korean retail and Japanese manufacturing floors.
Cloud-Based sits at the top of the volume ranking, with Edge Computing climbing the fastest.
Solution Offering:
Algorithm selection directly determines infrastructure cost tiers, with deep learning architectures demanding 10-20x compute budgets versus matrix factorization methods.
- Deep Learning Algorithms:Transformer-based sequence models and neural collaborative filtering capture the steepest expansion trajectory in streaming and advertising platforms. NVIDIA GPU clusters in Singapore and California train billion-parameter architectures for Netflix and ByteDance recommendation pipelines.
- Hybrid Models:Combined collaborative and content-based approaches retain strong positioning in regulated European retail where GDPR Article 22 automated decision explanations are mandatory. German automotive marketplaces and French insurance platforms default to these interpretable architectures.
- Collaborative Filtering:Classic matrix factorization persists in resource-constrained emerging market deployments.
- Content-Based Filtering:Metadata-driven systems dominate specialized B2B procurement platforms in Switzerland and the Netherlands.
- Reinforcement Learning:Bandit algorithms optimize exploration-exploitation tradeoffs for Spotify and Tencent music discovery interfaces.
Deep Learning Algorithms command the highest revenue concentration, though Hybrid Models show the most resilient demand in regulated jurisdictions.
Application:
Application segments diverge sharply in latency tolerance, with gaming requiring sub-20-millisecond response times versus batch-processed education recommendations.
- E-Commerce Platforms:Real-time inventory synchronization and dynamic pricing integration dominate technical requirements. Amazon and Alibaba pipelines process billions of events daily, with EU AI Act high-risk classifications triggering for credit and employment recommendation contexts in German and French marketplaces.
- Streaming Services:Session-based adaptation and cold-start handling for new content drive architecture innovation. Netflix, Disney+, and regional competitors in Brazil and Mexico expand recommendation engineering headcount to combat subscription churn.
- Online Education:Learning path optimization and knowledge gap identification shape algorithm design for Coursera and domestic Chinese platforms.
- Travel Booking:Multi-objective ranking balances price, convenience, and supplier commission structures for Booking.com and Trip.com.
- Gaming:Real-time matchmaking and in-game item suggestion engines demand the lowest latency thresholds.
E-Commerce Platforms generate the largest absolute deployment volume, while Gaming applications are gaining share fastest among infrastructure investors.
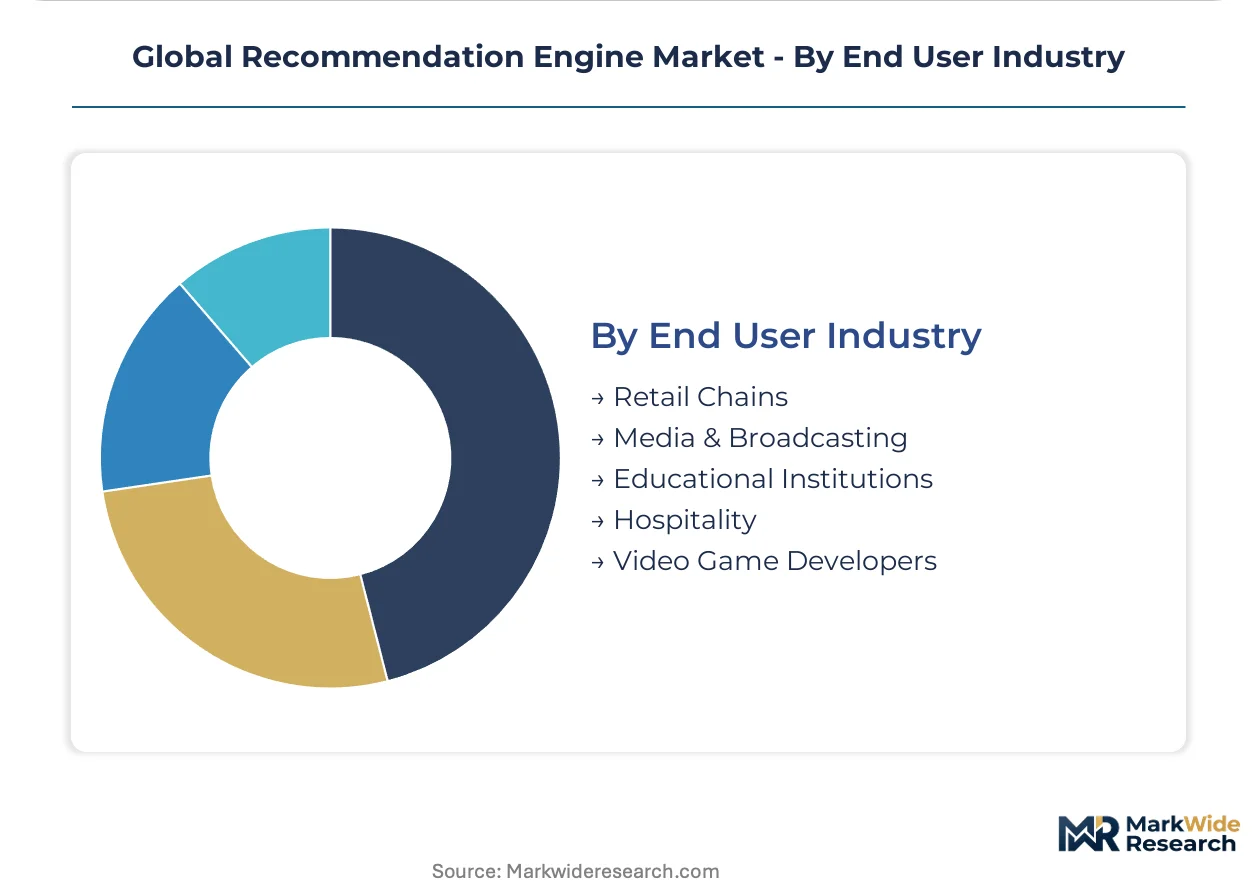
End User Industry:
Industry verticals impose distinct interpretability and auditability requirements, with media broadcasting facing lighter oversight than retail credit decisions.
- Retail Chains:Omnichannel integration spanning mobile apps, in-store kiosks, and loyalty programs creates complex data pipeline requirements. Walmart and Carrefour deployments must synchronize SAP and Oracle ERP systems, extending implementation timelines 8-14 months.
- Media & Broadcasting:European public broadcasters abandon grid-style program guides for personalized feeds, compressing infrastructure refresh cycles. BBC and ARD reengineering projects demand real-time session adaptation rather than batch daily recommendations.
- Educational Institutions:Learning management system integration and academic integrity constraints shape procurement for universities in Australia and Canada.
- Hospitality:Revenue management system coupling and guest preference learning drive adoption for Marriott and Accor chains.
- Video Game Developers:Live service monetization and player retention optimization prioritize engagement metrics over conversion rates.
Retail Chains anchor current deployment scale, with Media & Broadcasting showing the steepest expansion trajectory among European buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as the EU AI Act's conformity assessment costs push some enterprises toward jurisdictions with lighter algorithmic governance. Cloud infrastructure investments concentrate where data residency rules intersect with GPU cluster availability.
United States
Enterprise demand for real-time personalization drives hyperscaler expansion in Northern Virginia and Oregon data center corridors. The FTC applies Section 5 unfairness standards to opaque algorithmic systems, prompting auditable architecture investments. Seattle and San Francisco Bay Area clusters host Netflix and ByteDance engineering teams developing sub-50-millisecond inference pipelines.
Germany
Automotive marketplaces and insurance platforms prioritize interpretable hybrid models under GDPR Article 22 automated decision requirements. The EU AI Act's high-risk system classification triggers conformity assessments for credit and employment recommendation engines. Frankfurt's cloud region captures EU data residency procurement from financial services firms.
China
SAMR algorithm recommendation provisions mandate user opt-out mechanisms and transparency disclosures, forcing domestic platform reengineering. ByteDance and Tencent operate billion-parameter training clusters in Beijing and Hangzhou. Export control restrictions on NVIDIA A100 and H100 chipsets constrain procurement for advanced deep learning deployments.
Japan
5G network rollouts enable sub-20-millisecond edge inference for retail and manufacturing personalization. METI guidance on trustworthy AI shapes enterprise procurement criteria. Tokyo and Osaka metropolitan areas concentrate streaming media engineering teams expanding recommendation headcount to combat subscription fatigue.
India
The Open Network for Digital Commerce mandates interoperable recommendation layers across e-commerce participants, generating implementation contracts for domestic SaaS vendors. Bangalore and Hyderabad clusters host engineering centers serving global platforms. Data localization requirements under the PDP Bill reshape cloud architecture decisions for multinational vendors.
Global Recommendation Engine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud hyperscalers capturing enterprise procurement through bundled service contracts while independent software vendors defend niches requiring specialized compliance architectures. The vendor base concentrates among three tiers: infrastructure-anchored platforms with dedicated GPU clusters, enterprise application suites integrating recommendation modules, and point-solution specialists serving regulated verticals. Dominant competitive moves include M&A to acquire proprietary data flywheels and strategic partnerships with semiconductor vendors for custom silicon optimization.
Within the cloud-platform tier, Amazon Web Services, Google LLC, and Microsoft Corporation exemplify divergent positioning strategies. AWS leverages infrastructure dominance to bundle recommendation APIs with broader enterprise contracts. Google anchors its position through deep learning algorithm specialization within advertising and streaming ecosystems. Microsoft extends reach by integrating recommendation capabilities across Office 365 and Azure service layers, representing the enterprise-suite integration archetype.
| Leading Market Players |
|---|
| Amazon Web Services, Inc |
| Google LLC |
| International Business Machines Corporation |
| Microsoft Corporation |
| Salesforce, Inc. |
| Oracle Corporation |
| SAP SE |
| Adobe Inc. |
| Intel Corporation |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams in Germany and France now mandate auditable, interpretable recommendation architectures under EU AI Act conformity assessments, forcing vendors to absorb compliance engineering costs into SaaS tier structures while GPU supply concentration in the United States and Taiwan constrains pricing flexibility for deep learning deployments.
Pricing Analysis
Distributor margins in cloud-based recommendation engine procurement typically range from 15-22 percent for hyperscaler marketplace transactions, though direct enterprise contracts with AWS, Google Cloud, and Azure bypass this layer entirely. Three-tier pricing structure across premium, standard, and economy levels segments by model complexity, with premium tiers offering sub-50-millisecond latency SLAs and dedicated GPU clusters. Cost compression in standard tiers is intensifying because Chinese vendors face export control restrictions on NVIDIA A100 and H100 chipsets, forcing price competition on inferior hardware. Mid-market retailers show highest price sensitivity, while financial services firms in Frankfurt and Singapore accept premium positioning for compliance-ready deployments.
Supply Chain Analysis
GPU supply for training-grade recommendation engines rests on NVIDIA's manufacturing partnerships with TSMC in Taiwan and Samsung in South Korea, with assembly and testing concentrated in Malaysia and Vietnam. Raw material dependencies include advanced silicon wafers, HBM3 memory stacks from SK Hynix and Micron, and specialized cooling substrates. Single-source vulnerability around CoWoS packaging capacity at TSMC creates procurement bottlenecks extending deployment timelines. Distribution runs through direct hyperscaler provisioning for enterprise customers, with value-added resellers serving regulated verticals requiring compliance consulting layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate between the EU's high compliance costs and India's emerging ONDC-mandated interoperability requirements, where differential regulatory burden creates 30-40 percent cost advantages for SaaS vendors willing to architect region-specific product roadmaps.
For Market Incumbents: Lock in proprietary data flywheels through exclusive content licensing with streaming platforms and e-commerce marketplaces, while securing dedicated GPU allocation agreements with NVIDIA and AMD to defend against emerging Chinese chip alternatives. Vertical integration into custom silicon optimization, as Google has pursued with TPUs, creates sustainable latency advantages that matrix-factorization challengers cannot replicate. For New Entrants and Emerging Players: Begin with federated learning architectures targeting healthcare consortia in Switzerland and the Netherlands, where privacy-preserving distributed training addresses data minimization mandates that incumbents struggle to retrofit. India's ONDC protocol integration offers the most penetrable geography, with domestic SaaS vendors capturing implementation contracts from multinational platforms forced to reengineer for interoperability. A compliance-first go-to-market angle, emphasizing GDPR Article 22 explainability and SAMR opt-out mechanisms, differentiates against algorithmic-performance positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with point-solution specialists serving regulated verticals where interpretability requirements persist alongside accuracy demands, particularly hybrid-model vendors with established German automotive marketplace and French insurance platform relationships. Long-term viability hinges on MLOps talent retention and custom silicon partnerships rather than algorithmic novelty alone. The signal to watch is hyperscaler capex allocation to recommendation-specific GPU clusters, which indicates competitive intensity and margin compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft's Office 365 embedding creates enterprise lock-in through workflow-native recommendations. |
| Strategic Partnership | AWS-NVIDIA co-developed Inferentia chips reduce inference costs for high-traffic e-commerce deployments. |
| Acquisition of Specialist Firm | Graph neural network startups add modular architecture capabilities for heterogeneous computing pipelines. |
| Geographic Expansion | Frankfurt cloud region investments capture EU data residency procurement from financial services firms. |
| Product Launch | Edge-optimized inference engines enable 5G-enabled sub-20-millisecond personalization in South Korean retail. |
Research Methodology
Multiple input streams — structured interviews with CTOs and platform engineering leads at streaming services and e-commerce operators, procurement officer surveys at financial services firms, and secondary validation against SEC filings from hyperscalers, App Annie engagement metrics, and EU AI Act implementation guidance — were reconciled through bottom-up deployment volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon applied segmentation by deployment topology, algorithmic approach, application vertical, and regional regulatory cluster, with CAGRs derived from elasticity-adjusted adoption curves and infrastructure investment tracking. Industry-specific forecast inputs included GPU cluster capacity expansion disclosures from NVIDIA and hyperscaler capex reports, alongside ONDC protocol implementation timelines from Indian regulatory filings.
Several conditions sit outside the modeled scope, including potential export control expansion beyond A100/H100 restrictions, unforeseen EU AI Act enforcement severity variations across member states, and breakthrough algorithmic approaches displacing transformer architectures entirely. Forecasts reflect documented assumptions about latency tolerance convergence and compliance cost absorption rates. A small set of named triggers warrants ongoing watch: SAMR algorithm recommendation provision enforcement patterns, NVIDIA competitive response to Chinese chip alternatives, and GDPR Article 22 judicial interpretation developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Construction Data Analytics Software Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Data Discovery Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Italy Geospatial Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Global Operational Analytics Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Global People and HR Analytics Software Market
Analytics
Location Analytics Adoption Spending Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Enterprise Drone Analytics Software Market