
 Global Customer Analytics Market | 2026-2036
Global Customer Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Analytics Market Foresight
Subscription-based SaaS financing is reconfiguring competitive entry barriers in customer analytics, enabling mid-sized vendors to access enterprise-grade infrastructure without heavy capital deployment. Salesforce leverages its integrated CRM-to-analytics pipeline to sustain recurring revenue density among Fortune 500 accounts. SAP SE anchors its position through deep ERP connectivity that feeds native customer data models. Teradata Corporation specializes in high-volume on-premises deployments where data sovereignty requirements dominate procurement decisions.
Customer analytics encompasses the systematic extraction, processing, and modeling of behavioral, transactional, and demographic data to generate actionable intelligence about buyer preferences, lifetime value trajectories, and propensity scores. Platforms typically ingest structured and unstructured data streams through API connectors, apply machine learning algorithms for pattern recognition, and output segmentations or predictions that inform pricing, promotion, and retention strategies. Predictive analytics commands the largest revenue share as enterprises prioritize churn prevention and demand forecasting, while prescriptive analytics represents the fastest-expanding category as optimization engines mature. Cloud-based deployment dominates new installations, though hybrid architectures retain strong traction among financial services firms managing sensitive transaction records under strict residency rules.
The EU AI Act imposes risk-classification requirements on automated decision-making systems, compelling vendors to document algorithmic transparency and human oversight protocols for European deployments. The SEC's escalating disclosure mandates around consumer data monetization practices in the United States are tightening governance standards for publicly traded analytics buyers. Stakeholders must monitor how divergent regulatory timelines across jurisdictions reshape product roadmaps and localization investments.
Market Dynamics
Real-time data infrastructure investments are compressing deployment cycles and forcing vendors to rearchitect platforms for sub-second latency requirements.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must document algorithmic transparency for automated decision systems, creating mandatory upgrade cycles for legacy analytics stacks.
- Cloud-native API architectures:Financial services firms in Singapore and Switzerland are replacing batch-processing systems with streaming data pipelines to enable instant personalization.
- Churn prevention prioritization:Telecommunications carriers now allocate majority of analytics budgets to predictive retention models, pulling investment from descriptive reporting tools.
Market Restraints
- Data residency enforcement:Brazil's LGPD and Saudi Arabia's PDPL require local server presence, fragmenting vendor infrastructure and raising operational overhead.
- Specialized talent scarcity:Machine learning operations engineers command premium compensation in London, San Francisco, and Bangalore, constraining mid-market vendor expansion.
- GPU compute cost volatility:Training large customer propensity models depends on NVIDIA hardware availability, exposing buyers to supply chain concentration risk.
Strategic Opportunities
- Prescriptive analytics white space:Optimization engines for dynamic pricing remain underdeployed in German automotive retail and Japanese e-commerce.
- 5G-enabled edge processing:Convergence of low-latency networks with on-device inference opens real-time personalization for physical retail environments in South Korea.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates create demand for customer carbon-footprint analytics tied to purchase behavior.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle systems hold decades of customer transaction data in incompatible schemas, delaying cloud migration timelines.
- Model interpretability standards:Financial regulators in New York and Frankfurt now require explainable AI documentation, forcing engineering teams to abandon black-box algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Analytics Market |
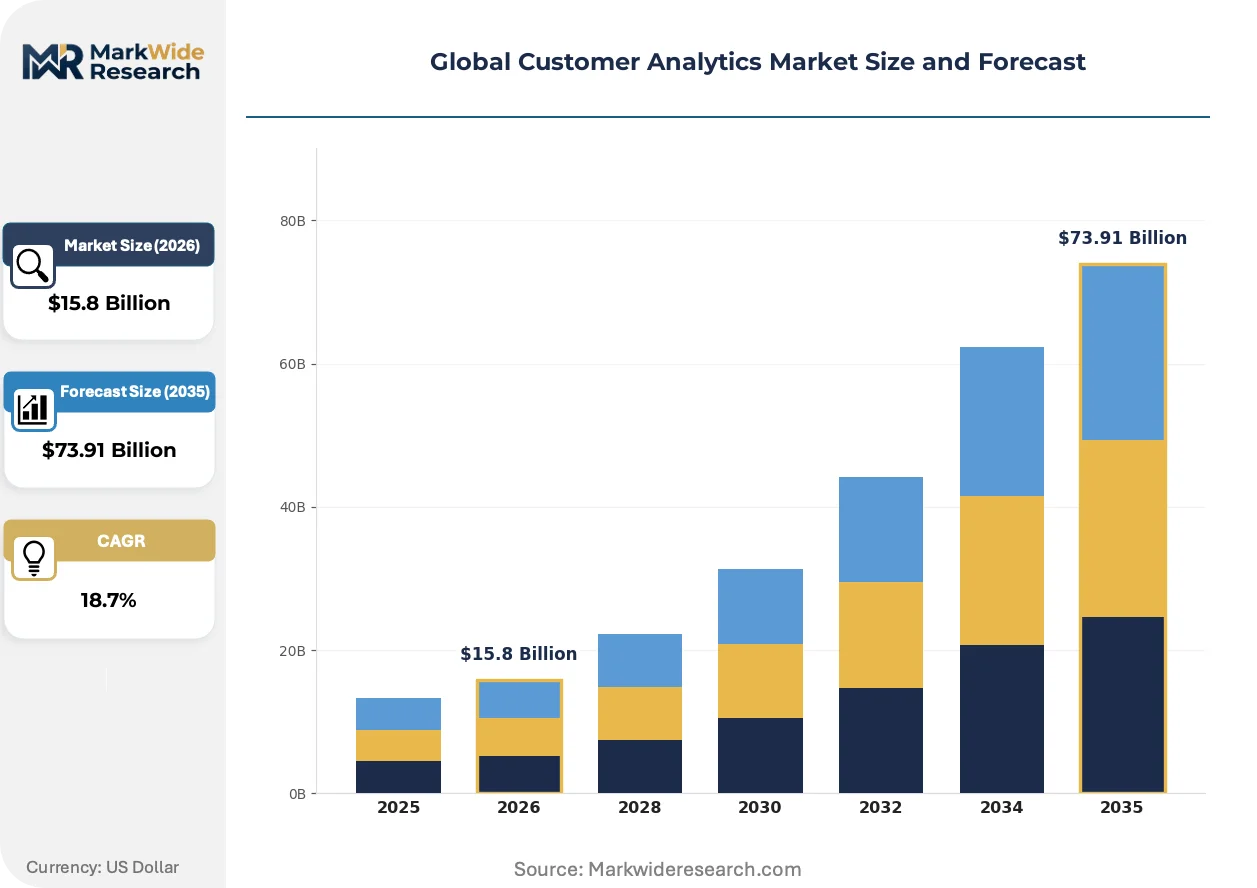
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $73.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Descriptive Analytics, Prescriptive Analytics, Diagnostic Analytics, Real-time Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Edge Deployment, Hosted Services Application: Customer Retention, Market Basket Analysis, Campaign Management, Churn Prediction, Customer Segmentation End User Industry: Telecommunications, E-commerce Platforms, Financial Services, Travel Agencies, Consumer Electronics |
| Companies Covered | Salesforce, Adobe, SAS Institute, IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Google, Teradata Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Analytics Market Shifts & Advancements
Customer analytics platforms are converging around streaming-first architectures that collapse the gap between data ingestion and actionable insight generation.
Federated learning architectures is hybridizing privacy-preserving computation with distributed model training. Retail banking consortia in Canada and Australia are deploying this approach to pool behavioral insights without centralizing sensitive transaction records. The technique compresses compliance overhead while preserving predictive accuracy across institutional boundaries.
GDPR Article 22 enforcement is tightening documentation requirements for fully automated credit decisions and insurance pricing. Vendors must now embed human-in-the-loop interfaces as default configurations for European deployments. Financial services procurement teams in France and Italy are rewriting RFP criteria to mandate algorithmic audit trails.
Outcome-based engagement models are displacing seat-license subscriptions in enterprise sales cycles. Analytics buyers in the United States now demand contracts tied to measurable revenue uplift or churn reduction rather than software access fees. This shift concentrates vendor risk in performance guarantees and accelerates consolidation toward platforms with proven vertical expertise.
Global Customer Analytics Market Segmentation
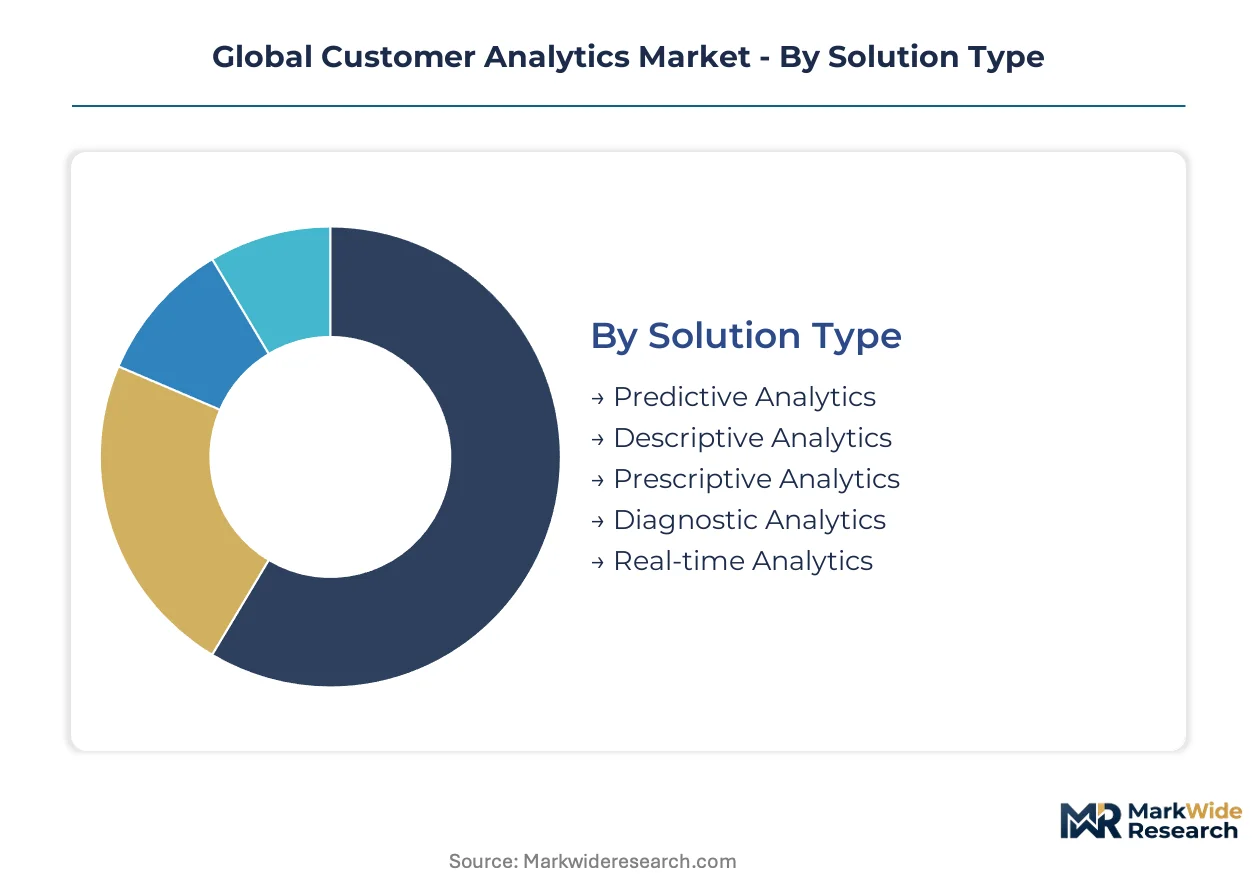
Customer analytics platforms fragment across solution architectures, infrastructure models, and industry-specific use cases. Buyers prioritize segments matching their data maturity, latency requirements, and regulatory exposure.
Solution Type:
Predictive and prescriptive engines dominate enterprise procurement as organizations shift from historical reporting to forward-looking intelligence.
- Predictive Analytics:Machine learning models forecast customer lifetime value, purchase propensity, and churn probability using behavioral and transactional signals. Telecommunications carriers in the United States and Germany allocate majority analytics budgets to predictive retention systems, prioritizing churn prevention over descriptive dashboards.
- Prescriptive Analytics:Optimization engines recommend specific actions—dynamic pricing adjustments, personalized promotions, or retention interventions—based on simulated outcomes. German automotive retail and Japanese e-commerce platforms represent underpenetrated demand pockets where prescriptive deployment remains nascent.
- Descriptive Analytics:Retrospective reporting and visualization tools aggregate historical customer data into segment profiles and performance dashboards.
- Diagnostic Analytics:Root-cause analysis modules isolate factors driving customer behavior shifts, supporting troubleshooting and process improvement.
- Real-time Analytics:Sub-second processing pipelines enable instant personalization and triggered interventions across digital touchpoints.
Established volume favors predictive analytics; emerging adoption favors prescriptive analytics.
Deployment Model:
Infrastructure choices reflect data sovereignty requirements, latency constraints, and capital deployment preferences across regulated and unregulated sectors.
- Cloud-Based:Scalable, API-native platforms eliminate capital expenditure and accelerate time-to-value through managed infrastructure. Singaporean and Swiss financial services firms are replacing batch systems with streaming cloud pipelines to enable instant personalization.
- On-Premises:Dedicated hardware installations maintain physical control over sensitive customer records. Saudi Arabia's PDPL and Brazil's LGPD mandate local server presence, preserving on-premises demand among compliance-heavy organizations.
- Hybrid Cloud:Split architectures process anonymized data in public cloud while retaining personally identifiable information in private infrastructure.
- Edge Deployment:On-device inference at retail locations and mobile endpoints reduces round-trip latency for physical environment personalization.
- Hosted Services:Managed private cloud offerings combine vendor-operated infrastructure with single-tenant isolation.
Cloud-based deployments capture the steepest expansion trajectory; hybrid architectures retain strongest traction among financial services firms.
Application:
Use-case prioritization follows industry-specific pain points, with retention and churn prevention commanding disproportionate investment.
- Churn Prediction:Models identify at-risk customers before defection, triggering proactive retention interventions. Telecommunications carriers now redirect majority analytics spending from descriptive tools toward predictive retention models.
- Customer Retention:Comprehensive programs combine predictive scoring with automated engagement workflows to sustain subscriber and buyer relationships.
- Customer Segmentation:Clustering algorithms group buyers by behavioral, demographic, and value-based attributes for targeted treatment.
- Campaign Management:Orchestration platforms coordinate multi-channel marketing execution based on analytics-driven audience selection.
- Market Basket Analysis:Association rule mining reveals product affinities to inform cross-selling, store layout, and bundle pricing.
Churn prediction applications concentrate telecommunications spending; customer segmentation tools expand fastest across e-commerce platforms.
End User Industry:
Vertical-specific requirements shape platform selection, with financial services and telecommunications driving the most stringent compliance and latency demands.
- Financial Services:Banks, insurers, and wealth managers deploy analytics for credit risk, fraud detection, and personalized product recommendations. EU AI Act risk-classification requirements and GDPR Article 22 enforcement compel algorithmic transparency documentation and human-in-the-loop interfaces for European deployments.
- Telecommunications:Carriers leverage subscriber data for churn prevention, network optimization, and targeted service upselling.
- E-commerce Platforms:Online retailers prioritize real-time personalization, dynamic pricing, and recommendation engines.
- Consumer Electronics:Device manufacturers analyze usage patterns to inform product development and subscription service design.
- Travel Agencies:Booking platforms apply analytics to pricing optimization, demand forecasting, and personalized itinerary suggestions.
Financial services anchor compliance-driven procurement; e-commerce platforms are gaining share fastest through cloud-native personalization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States vendors extract pricing premiums through real-time infrastructure dominance, while German competitors absorb compliance costs from EU AI Act documentation mandates without equivalent margin recovery.
United States
Enterprise buyers in New York and San Francisco prioritize sub-second latency personalization engines, driving cloud-native API investments. SEC disclosure mandates on consumer data monetization tighten governance standards for publicly traded analytics purchasers. The Greater Boston cluster hosts specialized MLOps engineering talent pools that command premium compensation.
Germany
Automotive retailers in Bavaria and Baden-Württemberg underdeploy prescriptive optimization engines, creating white space for dynamic pricing solutions. EU AI Act risk-classification requirements force algorithmic transparency documentation for automated credit decisions. Frankfurt financial services procurement teams now mandate human-in-the-loop interfaces as default RFP criteria.
United Kingdom
London-based machine learning operations engineers command salary premiums that constrain mid-market vendor expansion. GDPR Article 22 enforcement tightens documentation requirements for fully automated insurance pricing systems. The Manchester-Leeds corridor concentrates legacy ERP integration projects delaying cloud migration timelines.
Singapore
Financial services firms replace batch-processing systems with streaming data pipelines to enable instant personalization. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria for banking analytics deployments. The one-north technology cluster anchors ASEAN regional headquarters for cloud-native platform providers.
Brazil
LGPD data residency requirements mandate local server presence, fragmenting vendor infrastructure and raising operational overhead. São Paulo-based telecommunications carriers redirect majority analytics spending toward predictive retention models. The Rio de Janeiro metropolitan area concentrates consumer-facing deployment of churn prevention systems.
Global Customer Analytics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream feeding algorithmic modules into broader workflows. The vendor base concentrates around three strategic archetypes: cloud-native SaaS providers with CRM-to-analytics pipelines, ERP-anchored incumbents leveraging native data connectivity, and on-premises specialists serving sovereignty-sensitive deployments. Dominant competitive moves include outcome-based contract structures displacing seat-license subscriptions and federated learning consortiums pooling behavioral insights without centralizing sensitive records.
Within the integrated platform tier, Salesforce and SAP SE exemplify divergent anchoring strategies, while Teradata Corporation occupies a position serving high-volume on-premises requirements. Salesforce represents the CRM-native archetype leveraging recurring revenue density among enterprise accounts. SAP SE anchors the ERP-connected segment through deep system integration feeding customer data models. Teradata Corporation exemplifies the sovereignty-focused specialist where data residency requirements dominate procurement decisions.
| Leading Market Players |
|---|
| Salesforce |
| Adobe |
| SAS Institute |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Teradata Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in European cloud infrastructure is compressing vendor margins and forcing tiered pricing differentiation between latency-optimized deployments and standard SaaS offerings. GPU availability constraints in United States data centers are accelerating cost pass-through mechanisms while Singaporean financial services buyers absorb premium pricing for sub-second personalization engines.
Pricing Analysis
The customization-premium spread separates configured-to-order deployments with dedicated infrastructure from multi-tenant standard subscriptions. Subscription-based SaaS tiers dominate enterprise procurement, with price differentiation anchored in data residency certification levels and vertical integration depth. Pricing pressure stems from outcome-based contract structures displacing seat-license models, compressing vendor risk into performance guarantees. Mid-market telecommunications carriers exhibit highest price sensitivity, while Fortune 500 financial services firms prioritize latency guarantees over cost optimization.
Supply Chain Analysis
Upstream feedstock for customer analytics platforms centers on NVIDIA GPU clusters, cloud hyperscaler compute capacity, and specialized MLOps engineering talent pools. Supply concentrates in United States data center regions, Singapore financial technology corridors, and Frankfurt cloud zones serving EU compliance requirements. Raw material dependencies include high-bandwidth memory modules, specialized inference accelerators, and proprietary training datasets. Single-source vulnerability runs through NVIDIA hardware availability, exposing buyers to supply chain concentration risk. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Customer Analytics Market sits in early-cycle expansion as prescriptive analytics penetration remains below predictive deployment rates across German automotive retail and Japanese e-commerce platforms. Federated learning consortiums in Canada and Australia demonstrate viable pathways for privacy-preserving growth without centralized data infrastructure.
For Market Incumbents: Pre-empt margin erosion from outcome-based contracting by deepening vertical integration into MLOps tooling and edge deployment hardware. Anchor retention through ERP-native data connectivity that feeds customer models, while absorbing compliance costs from EU AI Act documentation mandates without equivalent pricing recovery. Defend against cloud-native SaaS challengers by embedding human-in-the-loop interfaces as default configurations for European financial services procurement.
For New Entrants and Emerging Players: Pursue prescriptive analytics white space in German automotive retail and Japanese e-commerce where optimization engines remain underdeployed. Target telecommunications churn prevention budgets redirecting from descriptive reporting tools toward predictive retention models. Enter through API-native architectures that collapse deployment cycles for real-time personalization requirements in Singaporean financial services.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical-specialization play because outcome-based engagement models concentrate vendor risk in proven domain expertise rather than horizontal platform scale. Acquisition targets should demonstrate federated learning deployment experience or deep ERP integration capabilities with SAP and Oracle systems. Watch for inflection signals in 5G-enabled edge processing adoption across South Korean physical retail environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Consortium Formation | Enables Canadian and Australian retail banking consortia to pool behavioral insights without centralizing sensitive transaction records. |
| Human-in-the-Loop Interface Deployment | Satisfies GDPR Article 22 enforcement requirements for fully automated credit decisions in French and Italian financial services. |
| Streaming-First Architecture Migration | Replaces batch-processing systems with sub-second latency pipelines for instant personalization in Singaporean wealth management. |
| Outcome-Based Contract Structuring | Aligns vendor compensation with measurable churn reduction or revenue uplift in United States telecommunications procurement. |
| Edge Processing Capability Buildout | Captures 5G-enabled real-time personalization opportunities in South Korean physical retail environments. |
Research Methodology
Operator-level perspectives from chief data officers, MLOps engineering leads, financial services procurement managers, and telecommunications analytics directors anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory documentation. Bottom-up segment sizing triangulated with top-down market boundary checks across deployment models, solution architectures, and vertical adoption patterns.
Scenario-bracketing framed the analytical approach across the analysis window, with sensitivity testing around regulatory timeline divergence and GPU supply constraints. Segmentation dimensions modeled include solution type, deployment architecture, end-user industry, and regional compliance cluster. CAGRs derived from fitted growth curves incorporating cloud infrastructure investment trajectories, EU AI Act implementation schedules, and telecommunications carrier budget reallocation patterns.
Macroeconomic conditions sit as an overlay; deviation in enterprise software spending cycles or cloud hyperscaler capacity expansion would shift the trajectory. Forecasts incorporate assumptions around regulatory enforcement intensity and federated learning technical maturation. Cross-checking against hyperscaler earnings call commentary on analytics workload growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Latin America Big Data Analytics Market
Analytics
Global Streaming Analytics Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Data Mining Tools Market
Analytics
APAC Retail Analytics Market
Analytics
Self Service Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Video Analytics Market
Analytics
In-Memory Analytics Tools Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Embedded Analytics Market
Analytics
Text Analytics Market
Analytics
Load (ETL) Market