
 Europe HR Analytics Market | 2026-2036
Europe HR Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HR Analytics Market Insights
Healthcare recruitment is consolidating its position as the fastest-growing end-use vertical for HR analytics platforms across Europe. SAP SE leverages deep ERP integration to anchor enterprise deployments in German manufacturing clusters. Workday Inc competes through cloud-native architecture designed for multi-country payroll harmonization. Oracle Corporation sustains momentum via embedded AI capabilities that span talent acquisition through retention analytics.
HR analytics encompasses the systematic application of statistical modeling, machine learning algorithms, and workforce data visualization to optimize human capital decisions across planning, acquisition, development, and retention functions. Cloud-based deployment models now dominate new implementations as GDPR-compliant data residency architectures mature across EU member states. Predictive analytics represents the fastest-expanding solution category as organizations shift from retrospective reporting to forward-looking attrition and performance forecasting. Workforce analytics for SMBs lags enterprise adoption but presents concentrated margin pools due to underserved pricing tiers and lighter competitive density.
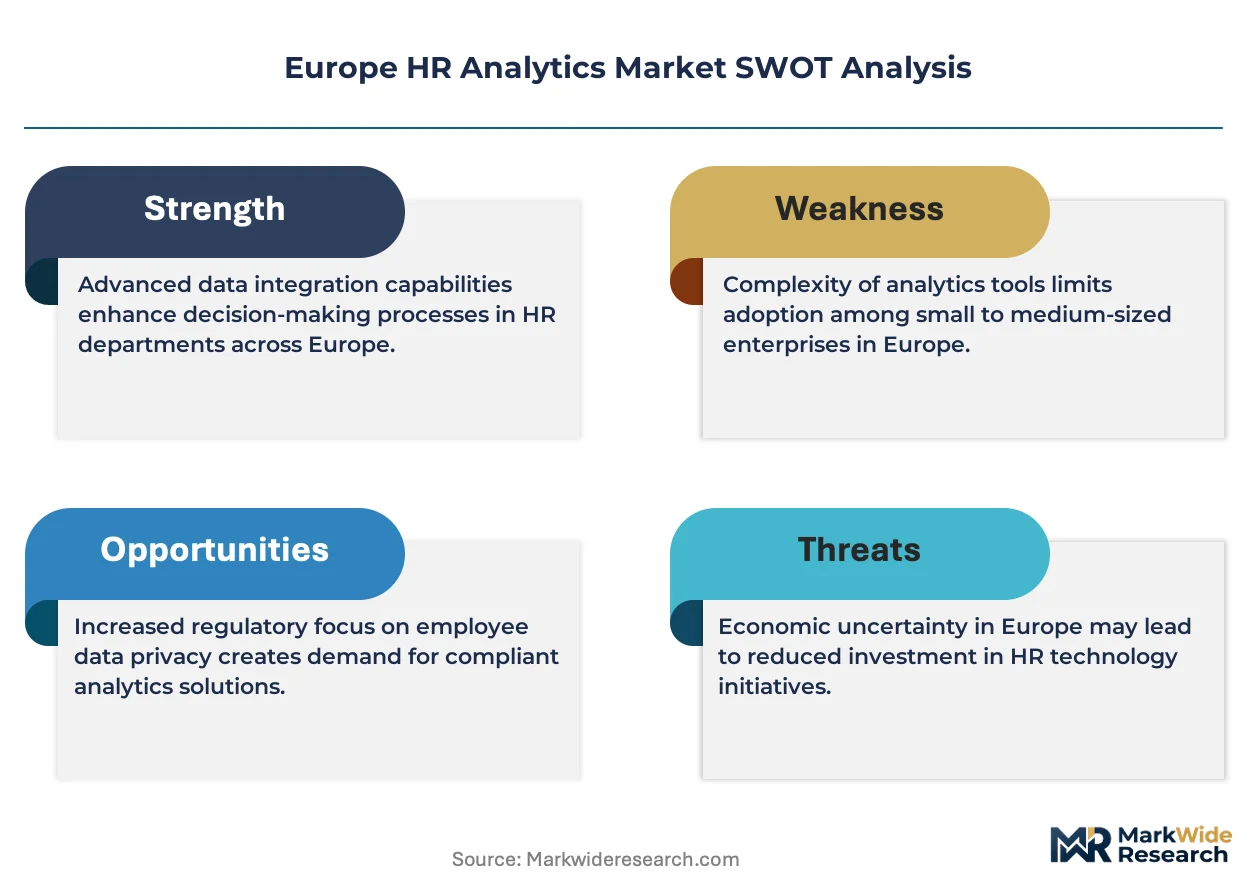
The EU AI Act and GDPR jointly constrain algorithmic transparency requirements for automated hiring tools, compelling vendors to invest in explainable AI documentation and bias audit trails. EMA-aligned healthcare employers face supplementary workforce compliance layers tied to credential verification and continuing education tracking. France's CNIL and Germany's federal data protection authorities actively enforce cross-border data transfer limitations that shape cloud architecture decisions. Stakeholders must monitor evolving national implementations of the EU AI Act as enforcement timelines and penalty structures crystallize across member states.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are compressing vendor compliance timelines while simultaneously opening procurement budgets for explainable AI tooling across financial services and healthcare employers.
Growth Catalysts
- GDPR-compliant cloud architectures:Maturing data residency frameworks across EU member states are removing procurement friction for cross-border workforce analytics deployments.
- Healthcare credential verification mandates:EMA-aligned employers face expanding workforce compliance requirements tied to continuing education tracking and professional certification validation.
- Predictive attrition modeling:Machine learning applications for forward-looking performance forecasting are displacing retrospective HR reporting systems in German manufacturing clusters.
Market Restraints
- Cross-border data transfer limitations:France's CNIL and Germany's federal data protection authorities enforce strict territorial restrictions that fragment cloud architecture standardization.
- Algorithmic audit documentation costs:Explainable AI trail requirements under the EU AI Act impose fixed compliance burdens that disproportionately constrain mid-market vendor margins.
- Legacy system integration complexity:SAP-dominated ERP environments in Central European industrial centers create path dependency that slows cloud-native platform displacement.
Strategic Opportunities
- Underpenetrated SMB pricing tiers:Workforce analytics for small and medium businesses presents concentrated margin pools due to lighter competitive density across Spain and Italy.
- Multi-country payroll harmonization:Cloud-native architectures capable of spanning diverse national labor codes are capturing procurement attention from pan-European employers.
- EMA workforce compliance layers:Supplementary credential verification requirements for healthcare employers create specialized module demand distinct from generic HR platforms.
Industry Challenges
- Explainable AI talent scarcity:Technical specialists capable of building bias audit trails and algorithmic documentation systems command premium compensation that compresses vendor operating margins.
- Legacy ERP integration timelines:SAP SE's deep manufacturing cluster penetration forces multi-year migration cycles that delay cloud analytics revenue recognition for competing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HR Analytics Market |
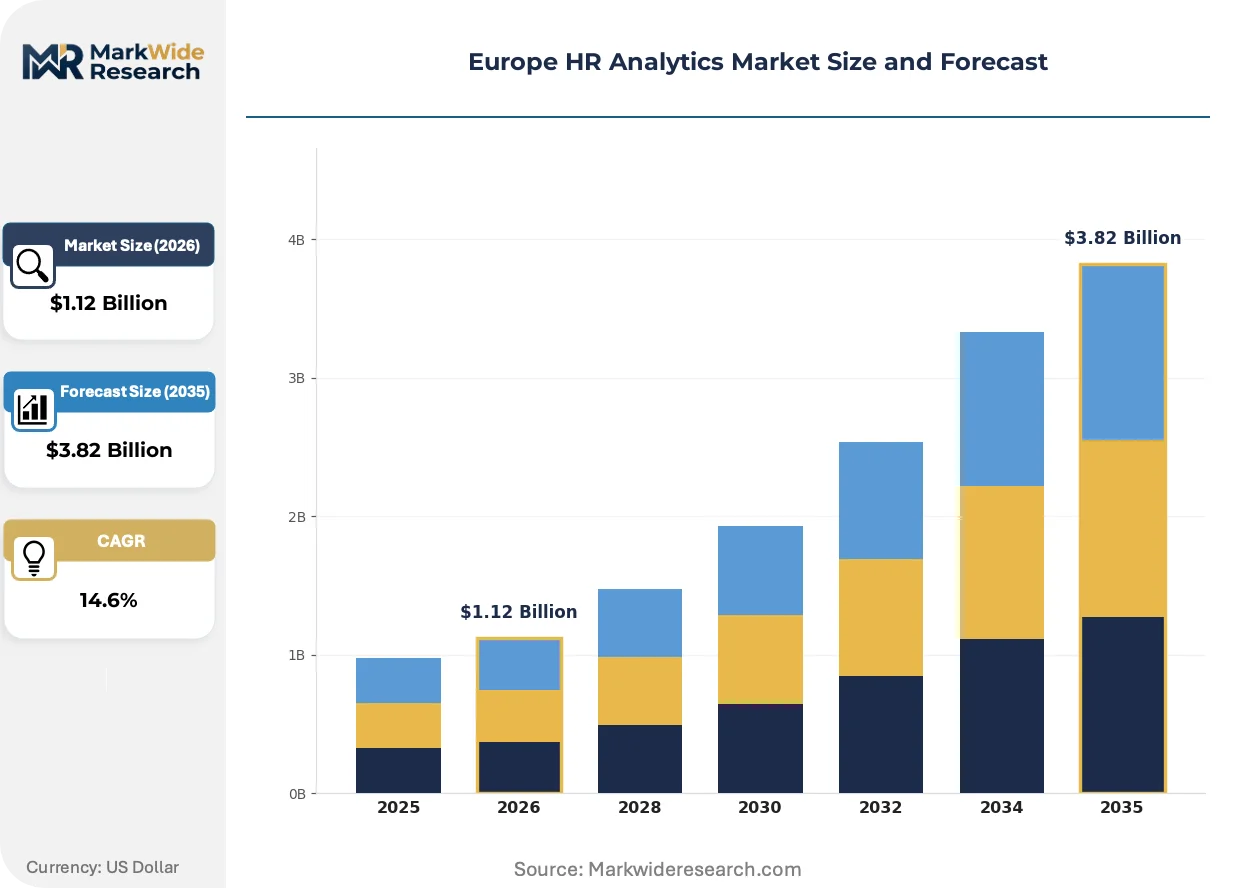
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Workforce Analytics Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Enterprises, Small & Medium Businesses, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Retail, Manufacturing, Information Technology |
| Companies Covered | Talentsoft SA, Cezanne HR Ltd, SAP SE, Workday Inc, Oracle Corporation, CEGID, Crunchr, UKG, MHR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HR Analytics Market Trends and Innovations
Workforce data infrastructure is pivoting from retrospective reporting toward predictive decision systems, with regulatory compliance and cross-border data architecture serving as the primary innovation vectors.
Embedded AI capabilities spanning talent acquisition through retention analytics are unifying previously siloed HR functions into continuous workforce intelligence pipelines. Large financial services employers in Frankfurt and London are deploying these integrated platforms at accelerated procurement cycles. The structural consequence is compressing vendor competitive differentiation toward explainability documentation rather than raw algorithmic performance.
The EU AI Act's enforcement timelines are crystallizing algorithmic transparency requirements for automated hiring and promotion tools across member states. Vendors must now invest in bias audit infrastructure and decision-documentation systems to maintain procurement eligibility. Healthcare and banking segments face the most immediate compliance pressure given their exposure to high-stakes employment decisions.
Buyer procurement patterns are rotating toward outcome-based workforce planning contracts that tie vendor compensation to measurable retention or performance improvements. This displaces traditional seat-based SaaS licensing in competitive RFP processes. The shift is most visible in United Kingdom financial services, where procurement teams possess mature vendor management capabilities to structure complex performance agreements.
Europe HR Analytics Market Segmentation
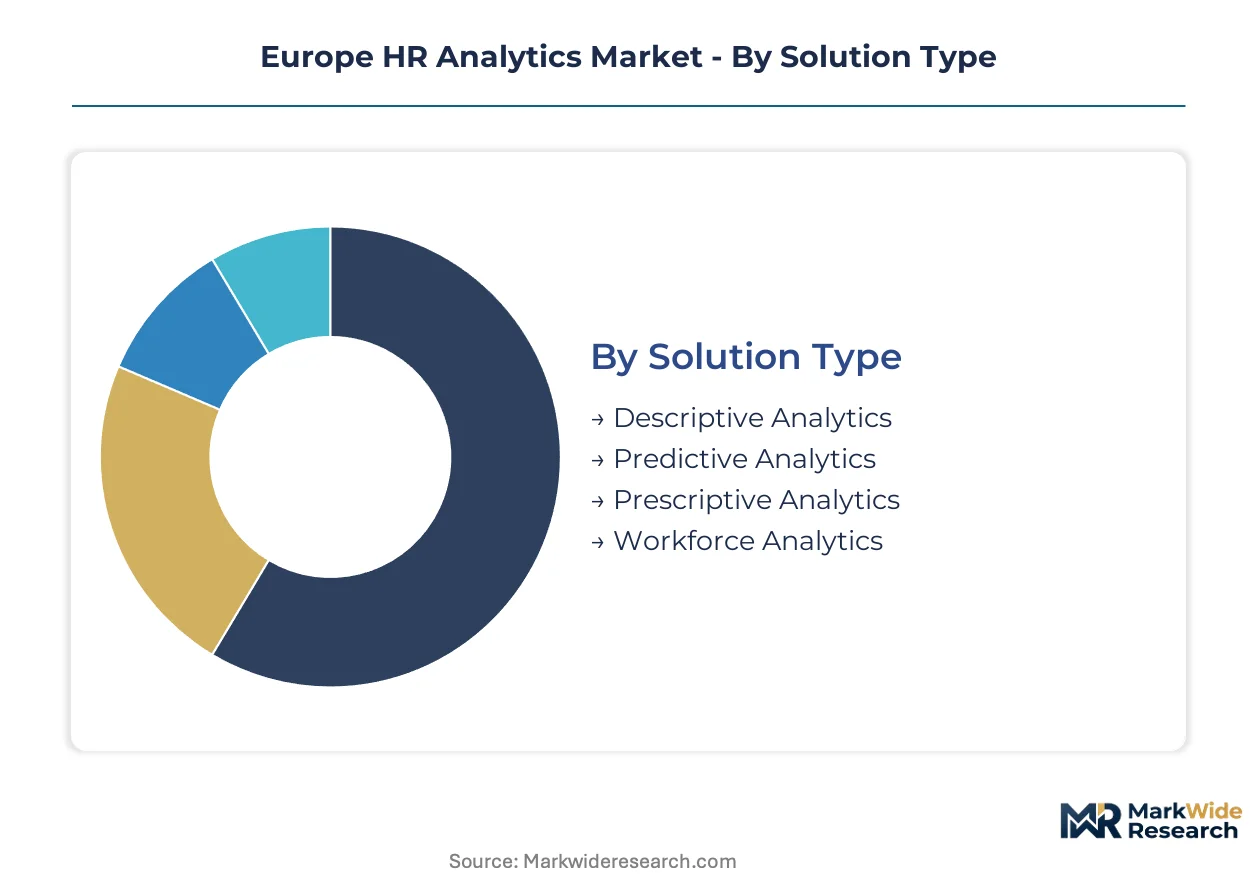
Segmentation in the Europe HR Analytics Market reveals how regulatory pressure and infrastructure maturity reshape procurement priorities across solution architectures and buyer profiles. Understanding these divides illuminates where compliance investments concentrate and where cloud-native platforms displace legacy systems.
Solution Type:
Supply concentration in predictive capabilities has intensified as vendors race to meet EU AI Act documentation requirements for algorithmic decision systems.
- Predictive Analytics:Machine learning models forecast attrition, performance trajectories, and workforce gaps before they materialize. German manufacturing clusters and United Kingdom financial services drive demand as predictive hiring tools displace retrospective reporting dashboards.
- Workforce Analytics:Integrated platforms unify talent acquisition, development, and retention data into continuous intelligence pipelines. Healthcare employers across France and the Netherlands adopt these systems to satisfy EMA-aligned credential verification mandates.
- Descriptive Analytics:Retrospective dashboards and standardized reporting tools remain entrenched in public sector deployments with limited modernization budgets.
- Prescriptive Analytics:Optimization engines recommending specific interventions for workforce planning currently serve niche applications in complex multinational payroll harmonization scenarios.
Predictive Analytics absorbs the bulk of installed capacity; Workforce Analytics is expanding most quickly.
Deployment Model:
Cost tier stratification separates enterprise buyers with compliance-driven architecture investments from mid-market purchasers prioritizing speed-to-deployment over customization depth.
- Cloud-Based:GDPR-compliant data residency frameworks now mature across EU member states, removing procurement friction for cross-border workforce analytics. France's CNIL and Germany's federal data protection authorities actively enforce territorial restrictions that shape vendor cloud architecture decisions.
- SaaS:Subscription delivery models dominate new implementations among mid-market employers seeking rapid deployment without capital expenditure. Spain and Italy present concentrated margin pools due to lighter competitive density in this tier.
- Hybrid:Mixed architectures preserve sensitive workforce data on-premise while leveraging cloud analytics for non-regulated functions.
- On-Premise:Legacy installations persist in Central European industrial centers where SAP-dominated ERP environments create path dependency slowing displacement.
Cloud-Based deployments capture the majority of new procurement spend; SaaS is climbing the fastest among mid-market buyers.
End User:
Customer type segmentation exposes a structural divide between enterprise buyers with mature vendor management capabilities and underserved SMB pricing tiers.
- Enterprises:Large employers structure outcome-based workforce planning contracts tying vendor compensation to measurable retention improvements. United Kingdom financial services procurement teams lead this shift away from seat-based SaaS licensing.
- Small & Medium Businesses:Underserved pricing tiers across Southern Europe present concentrated margin pools as lighter competitive density leaves room for specialized entrants.
- Government Agencies:Public sector procurement cycles emphasize standardized reporting compliance over predictive capabilities.
- Educational Institutions:University and research employer demand concentrates in workforce planning for specialized research talent pipelines.
Enterprises command the deepest installed base; Small & Medium Businesses are gaining share fastest as cloud-native platforms lower entry barriers.
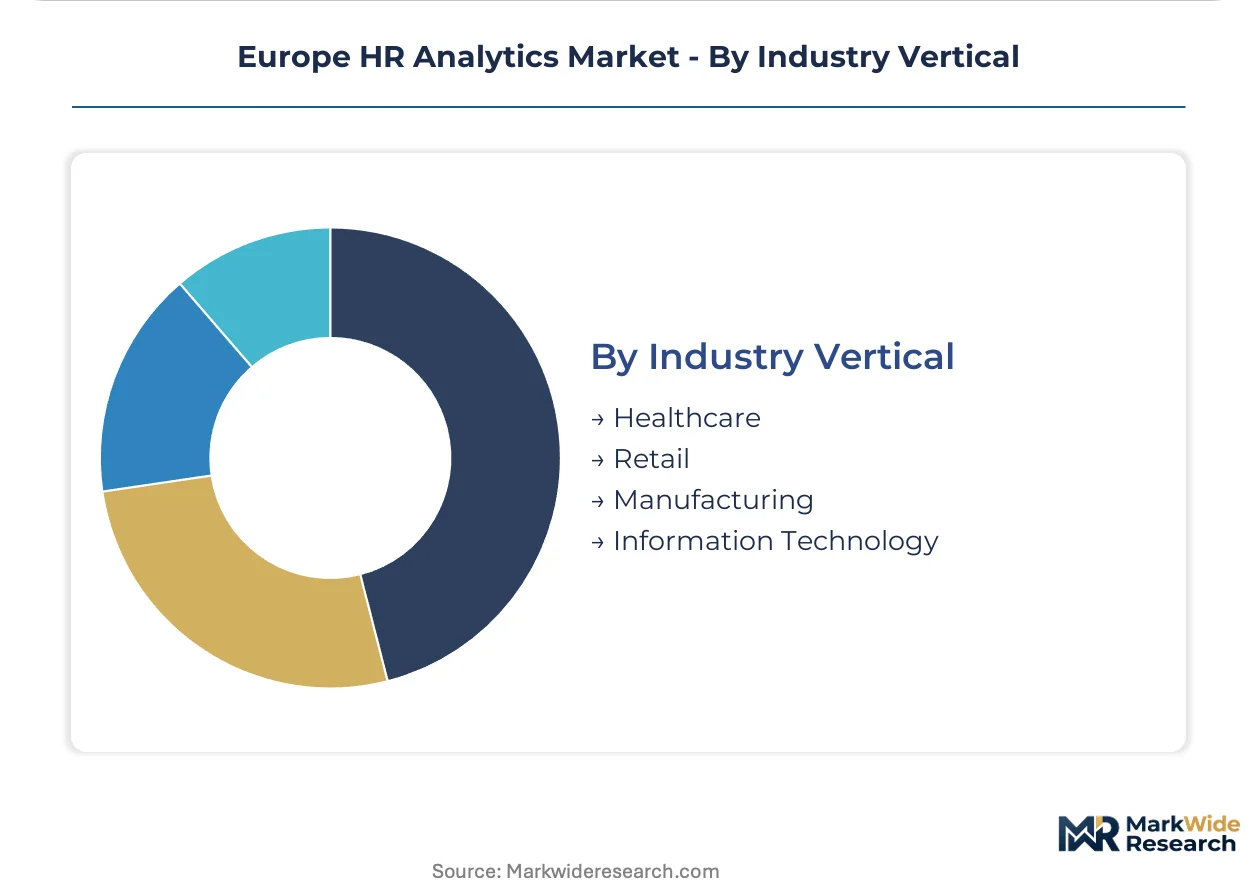
Industry Vertical:
Application-driven segmentation tracks how sector-specific compliance layers reshape platform requirements beyond generic HR functionality.
- Healthcare:EMA-aligned employers face expanding workforce compliance requirements tied to continuing education tracking and professional certification validation. Healthcare recruitment is consolidating its position as the fastest-growing end-use vertical for HR analytics platforms across Europe.
- Financial Services:Banking institutions in Frankfurt and London deploy predictive workforce planning tools at accelerated procurement cycles. The EU AI Act's algorithmic transparency mandates compress vendor compliance timelines while opening budgets for explainable AI tooling.
- Manufacturing:German industrial clusters leverage deep ERP integration for enterprise workforce analytics deployments.
- Retail:Seasonal workforce volatility drives demand for flexible analytics platforms capable of rapid scaling.
Healthcare absorbs the bulk of specialized compliance-driven investment; Financial Services is expanding most quickly on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of HR analytics platforms concentrates in software engineering hubs across Germany, the United Kingdom, and France, while consumption spreads across manufacturing clusters in Central Europe and financial services centers in Western Europe. The EU AI Act and GDPR create uniform compliance baselines, yet national data protection authorities enforce divergent territorial restrictions that reshape cloud architecture decisions.
Germany
German manufacturing clusters in Bavaria and Baden-Württemberg drive enterprise demand for predictive workforce planning tools integrated with SAP-dominated ERP environments. The Federal Data Protection Authority enforces strict cross-border data transfer limitations that compel vendors to maintain EU-based data residency architectures. Stuttgart's automotive sector and Munich's industrial technology corridor anchor the deepest installed base of workforce analytics platforms in Europe.
United Kingdom
London's financial services procurement teams structure outcome-based workforce planning contracts that tie vendor compensation to measurable retention improvements. The UK Information Commissioner's Office maintains GDPR-aligned enforcement post-Brexit, preserving algorithmic transparency requirements for automated hiring tools. The City of London and Canary Wharf banking clusters deploy integrated talent acquisition-to-retention analytics at accelerated procurement cycles.
France
Healthcare employers across Île-de-France and Auvergne-Rhône-Alpes adopt workforce analytics platforms to satisfy EMA-aligned credential verification mandates for continuing education tracking. The CNIL actively enforces territorial data restrictions that fragment standardization for pan-European cloud deployments. Paris-based pharmaceutical and hospital networks represent the fastest-growing vertical for specialized compliance-driven HR analytics modules.
Netherlands
Amsterdam and Rotterdam serve as data hub locations where vendors establish GDPR-compliant cloud infrastructure to serve cross-border workforce analytics deployments. The Dutch Data Protection Authority coordinates with EU counterparts on algorithmic transparency enforcement timelines. The Randstad's concentration of European headquarters for multinational employers generates concentrated demand for multi-country payroll harmonization capabilities.
Spain
Small and medium businesses across Madrid and Catalonia present concentrated margin pools for cloud-native HR analytics platforms due to lighter competitive density in underserved pricing tiers. The Spanish Data Protection Agency implements EU AI Act requirements with phased enforcement timelines extending through mid-decade. Barcelona's growing technology sector and Madrid's services economy drive SMB adoption of subscription-based workforce analytics solutions.
Europe HR Analytics Market Competitive Landscape
Top-tier vendors anchor enterprise deployments through deep ERP integration, while mid-market specialists compete on rapid cloud-native deployment speed. The vendor base stratifies across three tiers: enterprise platforms with embedded AI capabilities, regional specialists in compliance-driven verticals, and SaaS-native entrants targeting SMB pricing gaps. Strategic archetypes include ERP-anchored incumbents, vertical compliance specialists, and cloud-native disruptors. Dominant competitive moves center on explainable AI documentation investments and multi-country payroll harmonization partnerships.
Within the ERP-anchored tier, SAP SE leverages manufacturing cluster penetration to defend enterprise positions, while Workday Inc and Oracle Corporation occupy cloud-native positions emphasizing multi-country payroll capabilities. These three exemplify divergent architectural approaches to the same compliance-constrained demand environment, with each representing a distinct path to procurement eligibility under EU AI Act transparency mandates.
| Leading Market Players |
|---|
| Talentsoft SA |
| Cezanne HR Ltd |
| SAP SE |
| Workday Inc |
| Oracle Corporation |
| CEGID |
| Crunchr |
| UKG |
| MHR |
| Others |
Pricing and Supply Chain Analysis
Explainable AI talent scarcity in Berlin, Frankfurt, and London widens pricing-tier spreads as vendors absorb premium compensation costs for compliance specialists while competing for mid-market buyers in Southern Europe. Labor-cost differentials between algorithmic audit talent hubs and SMB sales territories compress margins at the economy tier while sustaining premium pricing for enterprise explainability modules.
Pricing Analysis
Margin tightening in the SaaS mid-market reflects compressed procurement budgets as Spanish and Italian SMBs prioritize rapid deployment over customization depth. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and explainable AI documentation depth. Cost-down pressure on standard-tier subscriptions accelerates because explainable AI talent scarcity inflates vendor operating costs disproportionately. Government agencies and public sector buyers exhibit highest price sensitivity due to fixed modernization budgets, while United Kingdom financial services procurement teams demonstrate lowest sensitivity given outcome-based contract structures.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from German manufacturing clusters and London banking centers, while partner networks serve mid-market dispersion across Madrid and Barcelona. Software engineering and cloud infrastructure supply concentrates in Germany, the United Kingdom, and the Netherlands. Raw material dependencies include GPU compute capacity, GDPR-compliant data residency architectures, and specialized machine learning frameworks. Single-source vulnerability in explainable AI talent pipelines threatens delivery timelines for EU AI Act compliance documentation. Distribution runs through SAP-anchored system integrators in Central Europe and cloud-native implementation partners in Western financial centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance timelines are forcing consolidation as mid-market vendors lacking explainable AI documentation infrastructure face procurement exclusion. Weaker players without bias audit capabilities will exit or be absorbed by enterprise platforms with embedded compliance layers.
For Market Incumbents: Anchor enterprise positions through deep ERP integration partnerships with SAP-dominated manufacturing clusters in Bavaria and Baden-Württemberg. Invest in explainable AI documentation infrastructure to defend against cloud-native challengers targeting procurement eligibility under EU AI Act mandates. Prioritize multi-country payroll harmonization capabilities to capture pan-European employer demand from Amsterdam and Rotterdam headquarters concentrations. For New Entrants and Emerging Players: Regional system integrators in underserved Southern Europe present the most penetrable channel for SaaS-native workforce analytics platforms. Target SMB pricing tiers across Spain and Italy where lighter competitive density leaves room for rapid deployment value propositions. Structure subscription delivery models emphasizing speed-to-value over customization depth to differentiate from ERP-anchored incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with vertical compliance specialists given EMA-aligned healthcare workforce mandates expanding module demand beyond generic HR functionality. Long-term viability favors platforms with embedded explainable AI infrastructure capable of serving both banking and healthcare segments through unified compliance layers. Monitor CNIL and German federal data protection authority enforcement patterns as inflection indicators for cloud architecture investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Documentation Investment | Bias audit trail capabilities secure procurement eligibility under EU AI Act mandates for Frankfurt banking clients. |
| Multi-Country Payroll Harmonization | Cloud-native architectures spanning diverse national labor codes capture demand from Randstad multinational headquarters. |
| EMA Compliance Module Development | Specialized credential verification layers differentiate platforms for Paris pharmaceutical and hospital network buyers. |
| GDPR-Compliant Data Residency Expansion | EU-based cloud infrastructure satisfies CNIL and German federal data protection authority territorial enforcement requirements. |
| SMB Channel Partner Network Buildout | Regional implementation partnerships in Madrid and Barcelona unlock concentrated margin pools in underserved pricing tiers. |
Research Methodology
Independent corroboration across vendor product documentation, regulatory filing analysis, and procurement database review underwrites the qualitative findings in this study. Primary interviews with HR technology executives, compliance officers at EMA-aligned healthcare employers, procurement leads at United Kingdom financial services firms, and cloud architecture specialists informed demand-side validation. Secondary sources include EU AI Act implementation guidance, GDPR enforcement decisions from CNIL and German federal data protection authorities, and workforce analytics platform technical specifications. Bottom-up deployment estimates triangulate against top-down market sizing from enterprise software spending analysis.
Rate-of-change decomposition across solution type, deployment model, end user, and industry vertical dimensions structures the analytical framework. Segmentation modeling incorporates predictive analytics adoption curves, cloud migration patterns, SMB penetration rates, and healthcare compliance module attach rates throughout the forecast period. CAGRs derive from regression analysis against historical enterprise software spending elasticity and regulatory compliance investment cycles. Forecast inputs include EU AI Act enforcement timeline assumptions and cross-border data transfer restriction evolution patterns.
Caveats apply where accelerated EU AI Act enforcement or divergent national implementation interpretations could materially shift the outlook. Forecasts reflect assumptions regarding cloud infrastructure maturity and explainable AI talent pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Learning Analytics Solution Market
Analytics
Europe Location Analytics Market
Analytics
Global Development Analytics Tools Market
Analytics
Patent Analytics Market
Analytics
Investigative Analytics Market
Analytics
Global Web Analytics Software Market
Analytics
Location Analytics Adoption Spending Market
Analytics
Sweden ICT Market
Analytics
Pandemic Analytics Market
Analytics
Social Business Intelligence Market
Analytics
Global Talent Intelligence Software Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Big Data Analytics in Retail Market
Analytics
Advanced Analytics Market