
 Embedded Software and Tools Market | 2026-2036
Embedded Software and Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Software and Tools Market Analysis
Automotive OEMs is bifurcating the Embedded Software and Tools Market away from traditional tier-one suppliers as vehicle architectures shift to zonal computing and software-defined platforms. Texas Instruments anchors its position through deep vertical integration into automotive microcontrollers and real-time processing silicon. NXP Semiconductors competes by sustaining broad R&D intensity across secure vehicle networking and domain controller solutions. Siemens EDA differentiates through model-based design toolchains that dominate safety-critical development workflows.
Embedded software and tools encompass integrated development environments, debuggers, real-time operating systems, middleware, and firmware frameworks that compile, verify, and deploy code onto resource-constrained microcontrollers and processors with deterministic timing requirements. These toolchains enable functional control across automotive ECUs, industrial PLCs, medical infusion pumps, and consumer IoT endpoints where hardware-software co-design determines system reliability. The debugging tools segment captures premium margins as multicore SoC complexity escalates trace and profiling requirements. Real-time operating systems lead in revenue scale due to their non-negotiable role in automotive and industrial safety loops. Model-based design is expanding fastest among segments as OEMs auto-generate production code from MATLAB and Simulink architectures to compress validation cycles.
ISO 26262 functional safety standards, UNECE WP.29 cybersecurity regulations, and EU AI Act risk classifications are reshaping toolchain certification requirements across European automotive development centers. The FDA's software as a medical device framework and IEC 62304 standards impose parallel compliance burdens on embedded tools serving North American healthcare equipment manufacturers. Stakeholders must monitor how regulatory divergence between jurisdictions fragments toolchain certification paths and forces redundant qualification investments.
Market Dynamics
Zonal E/E architectures are collapsing distributed ECU networks into centralized compute clusters, forcing embedded toolchains to support multicore debugging across heterogeneous processor arrays with deterministic latency guarantees.
Growth Catalysts
- ISO 26262 functional safety mandates:Automotive OEMs in Germany must certify toolchain components to ASIL-D levels, creating captive demand for qualified debuggers and static analysis suites.
- Software-defined vehicle platforms:Domain controller consolidation requires real-time operating systems that orchestrate sensor fusion, powertrain, and infotainment workloads on shared silicon.
- Industrial IoT deployment waves:Manufacturing facilities across Japan are retrofitting PLC networks with embedded Linux gateways, expanding addressable market for cross-compilation toolchains.
Market Restraints
- Silicon supply concentration:Automotive-grade microcontroller fabrication concentrates in Taiwan and South Korea, exposing tool vendors to foundry allocation volatility that delays reference platform availability.
- Certification cost escalation:FDA IEC 62304 qualification for medical device toolchains requires 18-24 month validation cycles that freeze feature roadmaps and inflate R&D overhead.
- Open-source substitution pressure:GCC and LLVM compiler ecosystems erode commercial IDE pricing power in cost-sensitive consumer electronics segments.
Strategic Opportunities
- India PLI scheme for automotive electronics:Tier-one suppliers establishing captive engineering centers in Pune and Chennai require localized toolchain support and training infrastructure.
- RISC-V architecture migration:Convergence of open instruction set adoption with custom silicon design tools creates white space for compiler and debugger vendors serving fabless automotive chip startups.
- EU AI Act risk classification:Embedded inference engines in autonomous systems face mandatory conformity assessment, opening certification service revenue streams adjacent to core tooling.
Industry Challenges
- Multicore trace expertise scarcity:SoC complexity exceeding 16 cores demands engineers proficient in Aurora protocol configuration and timestamp correlation across clock domains.
- Legacy AUTOSAR integration friction:Classic platform codebases resist migration to adaptive stacks, forcing tool vendors to maintain parallel toolchain branches with diverging qualification matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Software and Tools Market |
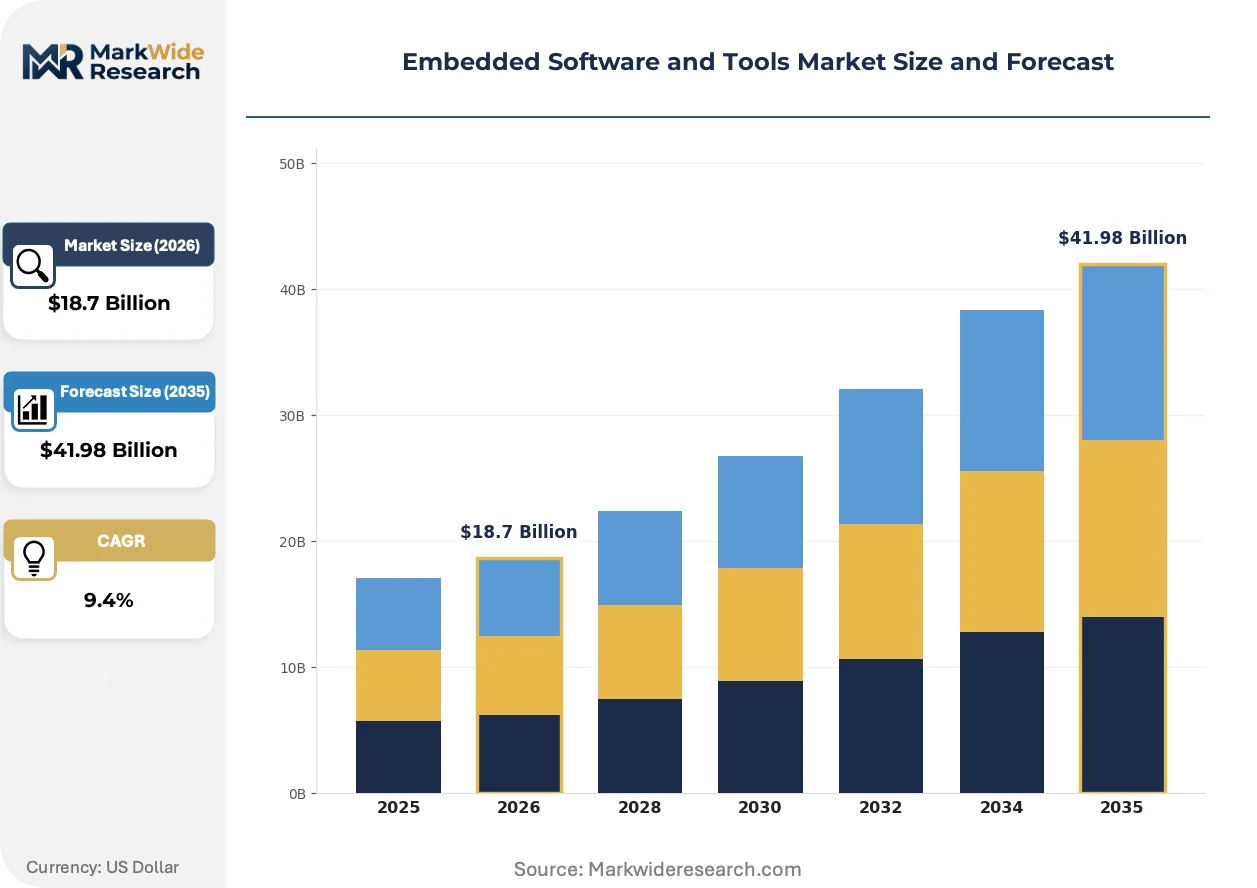
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Development Environment, Debugging Tools, Operating System, Middleware Application: Consumer Electronics, Automotive Systems, Industrial Automation, Medical Devices End User: OEMs, Software Developers, System Integrators, Research Institutions Technology: Real-Time Operating Systems, Firmware, APIs, Model-Based Design |
| Companies Covered | Texas Instruments, NXP Semiconductors, Cadence Design Systems, IAR Systems, Siemens EDA, ANSYS, STMicroelectronics, Wind River, Vector Informatik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Software and Tools Market Emerging Trajectories
Cloud-native development environments are displacing on-premise toolchains as distributed engineering teams demand centralized build farms and shared hardware-in-the-loop resources accessible through browser interfaces.
Model-based design is fragmenting traditional hand-coding workflows across automotive safety-critical development. Engineers at BMW and Bosch auto-generate production C code from MATLAB Stateflow diagrams, compressing unit test cycles while embedding formal verification proofs directly into generated artifacts. This shift compresses demand for conventional debugger licenses in favor of integrated simulation-verification bundles.
UNECE WP.29 cybersecurity regulations are mandating software bill of materials traceability across vehicle lifecycles. Type approval authorities in Germany and France now require embedded toolchains to generate cryptographically signed binary manifests that map every compiled module to its source revision and compiler version. Suppliers are retrofitting legacy build systems with SBOM generation plugins to maintain homologation eligibility.
Buyer concentration among automotive OEMs is forcing tool vendors into direct enterprise licensing negotiations that bypass traditional distribution channels. Volkswagen Group and Stellantis have consolidated procurement through centralized software engineering centers in Wolfsburg and Turin, extracting volume commitments that reshape vendor pricing structures away from per-seat models toward capped enterprise subscriptions.
Embedded Software and Tools Market Segmentation
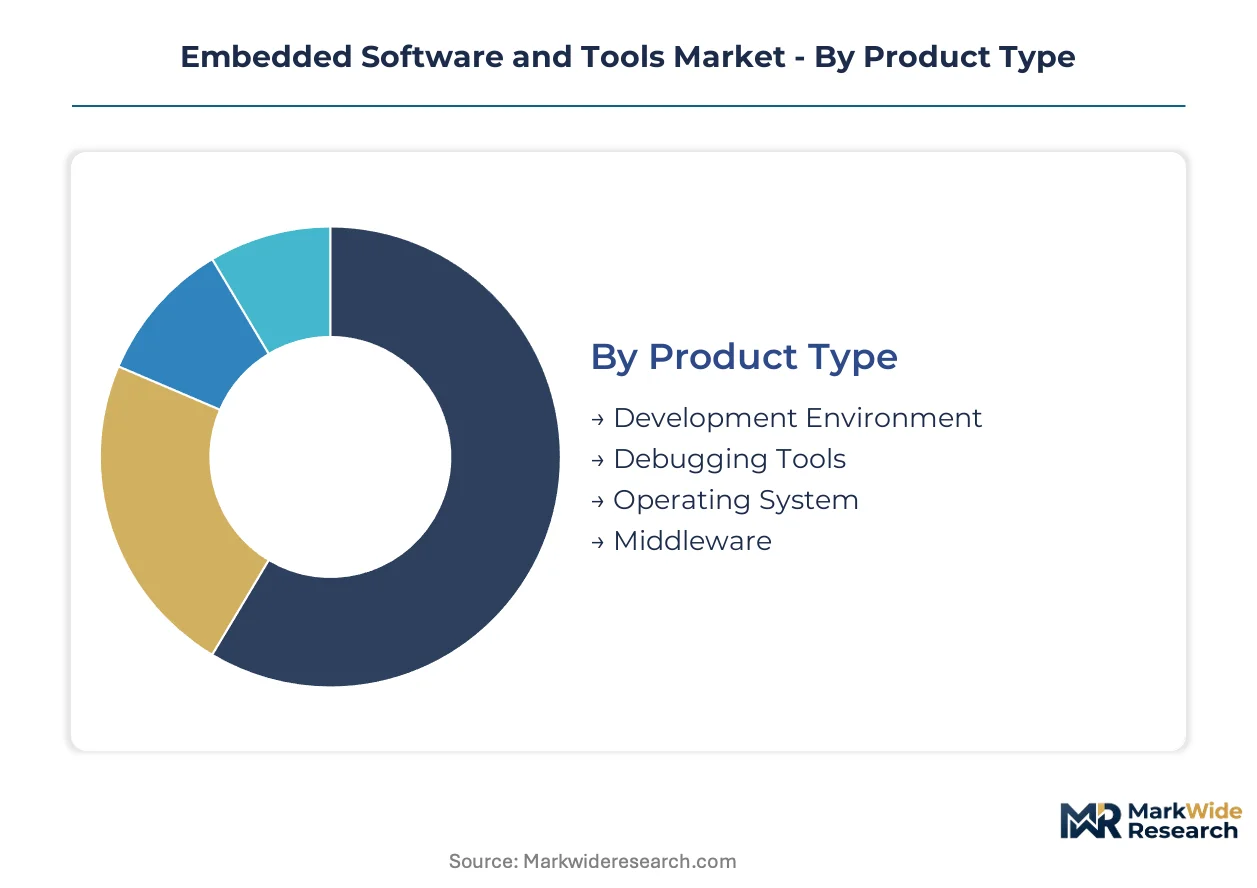
Segmentation in embedded software and tools reflects divergent compliance burdens across automotive, medical, and industrial verticals. Procurement patterns split between safety-critical toolchains requiring ISO 26262 qualification and cost-optimized environments serving consumer electronics. Understanding these divides exposes where vendors can extract premium pricing versus where open-source substitution threatens margins.
Product Type:
Development environments concentrate engineering investment in Germany and Japan where automotive OEMs maintain captive toolchain teams. Debugging tools and middleware show stronger export orientation toward India and Eastern European contract development centers.
- Development Environment:Integrated toolchains combining compilers, linkers, and project management interfaces dominate R&D expenditure at Volkswagen and Bosch engineering centers. German automotive clusters demand these suites certified to ASIL-D under ISO 26262, creating captive domestic demand that resists offshore migration.
- Debugging Tools:Multicore trace and profiling solutions capture premium margins as SoC complexity exceeds 16 cores. Japanese industrial automation vendors in Yokohama and Nagoya drive export demand for Aurora protocol configuration and timestamp correlation across heterogeneous processor arrays.
- Operating System:Real-time kernels with deterministic scheduling anchor safety loops in automotive powertrain and medical infusion pumps.
- Middleware:Communication stacks and protocol translators bridge legacy AUTOSAR Classic with adaptive platforms.
Operating systems command the established base. The steepest expansion runs through debugging tools.
Application:
Cost tier stratification separates medically certified toolchains from consumer electronics segments where GCC and LLVM erode commercial pricing power.
- Automotive Systems:Domain controller consolidation and zonal E/E architectures force toolchains to orchestrate sensor fusion, powertrain, and infotainment workloads on shared silicon. BMW and Stellantis procurement centers in Wolfsburg and Turin extract enterprise-wide licensing commitments that reshape vendor pricing structures.
- Medical Devices:FDA IEC 62304 qualification requirements impose 18-24 month validation cycles that freeze feature roadmaps and inflate R&D overhead. North American healthcare equipment manufacturers absorb these costs through reimbursed device pricing, insulating tool vendors from open-source pressure.
- Consumer Electronics:Cost-sensitive smartphone and wearable manufacturers favor zero-license-fee compiler ecosystems.
- Industrial Automation:Manufacturing facilities across Japan retrofit PLC networks with embedded Linux gateways.
Automotive systems anchor volume procurement. Medical devices sustain the highest margin tier.
End User:
Customer type determines contract structure, with OEMs forcing direct enterprise negotiations while research institutions sustain per-seat academic licensing.
- OEMs:Volkswagen Group and Stellantis have consolidated procurement through centralized software engineering centers, extracting volume commitments that shift pricing away from per-seat models toward capped enterprise subscriptions. These buyers demand SBOM traceability and cryptographically signed binary manifests for UNECE WP.29 homologation.
- Software Developers:Independent contractors and specialized firms serve mid-tier automotive suppliers with project-based toolchain deployments.
- System Integrators:Tier-one suppliers establishing captive engineering centers in Pune and Chennai under India's PLI scheme require localized toolchain support and training infrastructure.
- Research Institutions:University labs and government research centers in Munich and Tokyo drive early adoption of RISC-V architectures and experimental model-based design workflows.
OEMs dominate contract value. Research institutions pilot the steepest technology transitions.
Technology:
Maturity gradients separate established real-time kernels from emerging model-based design workflows that compress validation cycles.
- Model-Based Design:Engineers at BMW and Bosch auto-generate production C code from MATLAB Stateflow diagrams, embedding formal verification proofs directly into generated artifacts. This shift compresses demand for conventional debugger licenses in favor of integrated simulation-verification bundles.
- Real-Time Operating Systems:Deterministic kernels with sub-microsecond interrupt latency remain non-negotiable in automotive safety loops and industrial motion control. These systems anchor the revenue base across German and Japanese manufacturing clusters.
- Firmware:Low-level hardware abstraction layers require tight coupling to specific microcontroller reference platforms.
- APIs:Standardized interfaces for sensor integration and cloud connectivity gain traction in IoT gateway deployments.
Real-time operating systems command the established base. Model-based design climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne rail corridor and Rhine-Ruhr industrial belt underwrite Germany's embedded tooling dominance. Dense automotive engineering clusters in Stuttgart, Munich, and Wolfsburg generate concentrated demand for ISO 26262-qualified toolchains.
Germany
Volkswagen Group and BMW operate captive software engineering centers in Wolfsburg and Munich that procure enterprise-wide debugger licenses. KBA enforces UNECE WP.29 cybersecurity homologation requirements that mandate cryptographically signed binary manifests. Stuttgart anchors Europe's largest embedded engineering cluster, where Bosch and Continental maintain parallel toolchain teams for Classic and Adaptive AUTOSAR platforms.
United States
FDA's software as a medical device framework drives IEC 62304-qualified toolchain procurement from Boston and Minneapolis medical device manufacturers. NHTSA safety standards and emerging autonomous vehicle guidelines reshape automotive embedded requirements. Austin and Detroit engineering centers concentrate demand for multicore trace solutions as zonal E/E architectures consolidate compute.
Japan
METI industrial digitization programs accelerate embedded Linux gateway deployment across Yokohama and Nagoya manufacturing facilities. JIS standards govern functional safety toolchains serving Toyota and Honda powertrain divisions. Nagoya's Chubu region hosts specialized Aurora protocol expertise for industrial motion control debugging.
India
PLI scheme incentives attract tier-one automotive suppliers establishing captive engineering centers in Pune and Chennai. BIS automotive electronics standards create localized certification requirements for toolchain vendors. Bangalore's semiconductor design ecosystem generates demand for RISC-V compiler and debugger support services.
South Korea
MFDS medical device regulations parallel FDA frameworks, insulating qualified toolchain margins in Seoul healthcare equipment clusters. Hyundai and Kia centralize embedded procurement through Pangyo software engineering hubs. Samsung's foundry partnerships in Hwaseong influence reference platform availability for automotive microcontroller toolchains.
Embedded Software and Tools Market Vendor Landscape
Concentration sits with semiconductor-integrated tool vendors and specialized automotive software houses. The vendor base splits between consolidated semiconductor majors bundling toolchains with silicon and fragmented independent tool vendors serving certification-intensive verticals. Two strategic archetypes dominate: silicon-integrated platform vendors leveraging hardware-software co-design relationships, and independent safety-critical specialists monetizing qualification depth. Competitive moves center on enterprise licensing consolidation and cloud-native development environment migration.
Within the semiconductor-integrated tier, Texas Instruments and NXP Semiconductors exemplify platform bundling strategies. Siemens EDA occupies a distinct position among model-based design specialists serving German automotive qualification requirements. These three anchors represent divergent approaches to monetizing embedded tooling—silicon-tied distribution, automotive safety depth, and design automation integration.
| Leading Market Players |
|---|
| Texas Instruments |
| NXP Semiconductors |
| Cadence Design Systems |
| IAR Systems |
| Siemens EDA |
| ANSYS |
| STMicroelectronics |
| Wind River |
| Vector Informatik |
| Others |
Supply Flow & Price Mechanics
Foundry utilization rates above 90 percent at TSMC and Samsung Foundry concentrate automotive-grade microcontroller supply in Taiwan and South Korea, creating asymmetric pricing power that elevates price floors for ISO 26262-qualified toolchains while compressing margins in consumer-grade segments.
Pricing Analysis
Enterprise-volume discounting separates ASIL-D certified suites from standard development licenses. Volkswagen Group and Stellantis procurement centers extract capped subscription commitments that reshape vendor structures away from per-seat models. Pricing pressure stems from GCC and LLVM compiler ecosystems eroding commercial IDE pricing power in cost-sensitive consumer electronics segments. Medical device manufacturers absorbing FDA IEC 62304 qualification costs show lowest price sensitivity; smartphone OEMs exhibit highest.
Supply Chain Analysis
Strategic stockpiling of reference platforms dominates automotive toolchain procurement as foundry allocation volatility threatens development timelines. Silicon supply concentrates in Taiwan and South Korea, with automotive-grade microcontroller fabrication drawing from advanced node capacity. Single-source vulnerability at leading foundries exposes tool vendors to allocation disruptions. Distribution runs through direct enterprise licensing negotiations that bypass traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded tooling sits in early-cycle expansion as zonal E/E architectures and software-defined vehicle platforms drive replacement demand for multicore debugging and model-based design workflows.
For Market Incumbents: Consolidate certification depth by acquiring static analysis specialists with existing ASIL-D qualification matrices. Expand captive training infrastructure in Pune and Chennai to serve tier-one suppliers under India's PLI scheme. Open-source compiler pressure in consumer electronics demands defensive bundling with silicon reference platforms.
For New Entrants and Emerging Players: Cloud-native development environment gaps expose white space where incumbents under-serve distributed engineering teams. Target mid-tier automotive suppliers in Eastern European contract development centers with browser-accessible build farm solutions. Lead with SBOM generation plugins for UNECE WP.29 homologation compliance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among model-based design specialists with automotive OEM direct relationships. Five-to-ten year viability favors vendors with embedded formal verification capabilities and adaptive AUTOSAR migration toolchains. Watch RISC-V architecture adoption rates as inflection indicator for compiler and debugger demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Development Platform Launch | Centralized build farms serve Volkswagen and Stellantis distributed engineering centers. |
| ISO 26262 ASIL-D Certification Investment | Qualification matrices unlock procurement at BMW and Bosch engineering clusters. |
| RISC-V Compiler and Debugger Development | Open instruction set adoption creates demand from Bangalore fabless chip startups. |
| SBOM Generation Plugin Integration | Cryptographic binary manifests satisfy KBA and French type approval requirements. |
| India PLI Scheme Training Infrastructure | Localized support centers capture tier-one supplier captive engineering demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, automotive production databases, and regulatory submission records. Interviews with embedded software engineering directors, Tier 1 supplier procurement leads, and semiconductor platform managers informed demand-side validation. Bottom-up triangulation across product type, application, and technology segments was cross-checked against top-down macroeconomic indicators.
Segmentation dimensions modeled include product type, application vertical, end-user category, and technology maturity across the projection horizon. CAGRs were derived from regression analysis of historical adoption curves and forward penetration assumptions. Key inputs incorporated zonal E/E architecture transition timelines and UNECE WP.29 homologation rollout schedules.
Forecasts assume regulatory continuity in EU automotive homologation and FDA medical device frameworks; material policy shifts would require re-modeling. Automotive semiconductor supply constraints and open-source compiler ecosystem maturation represent primary revision triggers. Revision becomes warranted when RISC-V architecture penetration in automotive exceeds threshold adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Mainframe Software Market
Software & Services
Statistics Software Market
Software & Services
Global Presentation Software Market
Software & Services
MES Software Market
Software & Services
Optical Design Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Telecom Billing Software Market
Software & Services
Online Lottery Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
HCS Software and Services Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Compensation Software Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Survey and Feedback Management Software Market