
 Pipettes and Accessories Market | 2026-2036
Pipettes and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Pipettes and Accessories Market Analytics
The capital-intensity divergence between automated and manual product portfolios is reorganizing competitive hierarchies in laboratory liquid handling. Eppendorf AG leverages its German manufacturing base to sustain premium positioning in electronic pipettes. Thermo Fisher Scientific anchors North American supply through extensive direct sales infrastructure.
Pipettes and accessories comprise precision volumetric instruments—typically glass or polymer barrels with piston-driven air displacement mechanisms calibrated to ISO 8655 standards—used for quantitative liquid transfer in analytical and preparative workflows. Electronic pipettes with programmable step sequences command margin premiums over manual variants as throughput demands intensify. Academic institutions represent a mature volume pool, while pharmaceutical labs concentrate growth in multichannel configurations for high-density screening applications.
FDA quality system regulations and ISO 8655 calibration protocols shape instrument validation requirements across clinical and drug development settings. The EPA's good laboratory practice standards extend traceability demands to environmental testing workflows. Stakeholders must monitor evolving MDR requirements in Europe and assess certification burdens against regional production strategies.
Market Dynamics
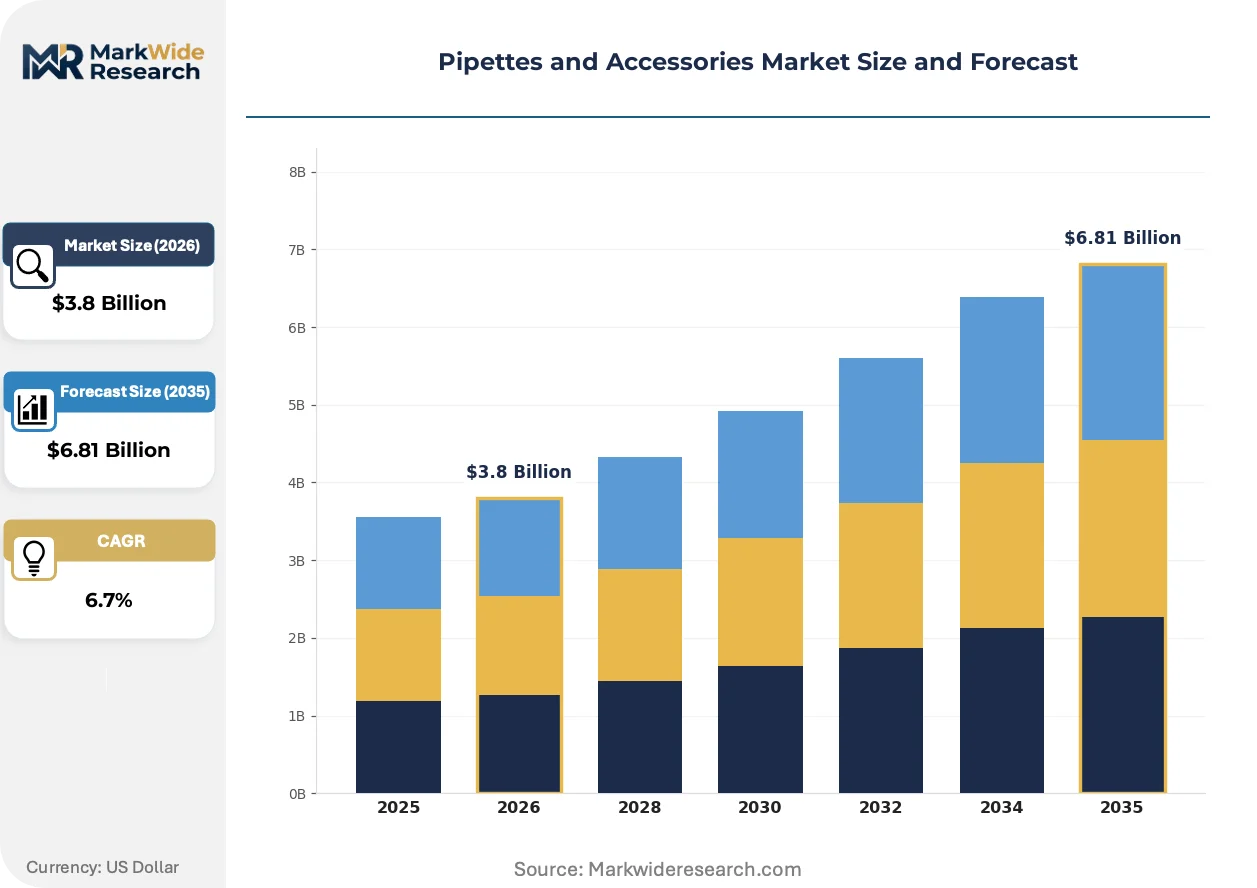
The transition from manual to electronic pipetting systems is compressing replacement cycles and elevating calibration service revenues as laboratories pursue ISO 8655 traceability for regulated workflows.
Growth Catalysts
- High-throughput screening expansion:Pharmaceutical R&D facilities in the United States are deploying multichannel electronic pipettes to accelerate compound library processing. FDA quality system regulations mandate documented liquid handling precision for IND-enabling studies.
- ISO 8655 calibration mandates:Clinical diagnostic laboratories across Germany and Switzerland now require annual third-party piston verification. This generates recurring service revenue streams for instrument distributors.
- Polymer barrel adoption:Academic institutions in Japan are shifting from borosilicate glass to autoclavable polymer constructions. METI-supported standardization initiatives have accelerated JIS-compliant material qualification.
Market Restraints
- Premium electronic pricing:Single-channel electronic pipettes command three-to-four-fold cost multiples over manual variants. Capital procurement freezes at mid-tier research institutes in France constrain upgrade velocity.
- Tip supply concentration:Polypropylene filter-tip production clusters in southern China create geographic vulnerability. ANSM import documentation requirements for sterile consumables extend lead times for European buyers.
- Air displacement limitations:Volatile organic solvent handling demands positive-displacement systems. Many legacy workflows remain tethered to manual glass syringes for chlorinated compound aliquoting.
Strategic Opportunities
- Brazilian diagnostic expansion:ANVISA's updated IVD quality regulations are compelling public health laboratories toward calibrated electronic systems. Underpenetration in São Paulo state research corridors offers first-mover positioning.
- CRISPR workflow integration:Gene editing protocols require sub-microliter precision for guide RNA assembly. Convergence of electronic pipetting with LIMS connectivity enables automated traceability for cell therapy manufacturing.
- Refurbishment channel development:Certified pre-owned electronic pipette programs are capturing price-sensitive segments. Direct-to-laboratory ecommerce platforms in India bypass traditional distributor markups for BIS-certified accessories.
Industry Challenges
- Metrology technician scarcity:ISO 17025-accredited calibration laboratories face recruitment gaps for piston-based volumetric verification. Competency gaps in gravimetric testing methods extend service turnaround times.
- Legacy LIMS integration:Electronic pipette data export protocols often conflict with established laboratory information management systems. Middleware development demands divert R&D resources from core ergonomic improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipettes and Accessories Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pipettes, Electronic Pipettes, Multichannel Pipettes, Pipette Tips End User: Pharmaceutical Labs, Academic Institutions, Research Organizations, Clinical Laboratories Application: Drug Development, Quality Control, Laboratory Testing, Scientific Research Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Eppendorf AG, Thermo Fisher Scientific Inc, Gilson Inc, Sartorius AG, BRAND GMBH + Co KG, Hamilton Company, Corning Incorporated, INTEGRA Biosciences AG, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipettes and Accessories Market Evolving Landscape
Digital connectivity and materials science advances are redefining liquid handling instrumentation. Laboratories now expect seamless data capture alongside mechanical reliability.
Bluetooth-enabled electronic pipettes are supplanting standalone units in regulated environments. These instruments transmit volume, user ID, and timestamp data directly to centralized quality systems. Pharmaceutical QC labs in Switzerland and Massachusetts are mandating such connectivity for GMP compliance, compressing demand for non-networked legacy models.
Europe's MDR recalibration requirements for clinical devices are extending traceability obligations to point-of-care testing workflows. Manufacturers must now provide documented measurement uncertainty calculations for every pipette channel. German hospital networks are consolidating procurement around suppliers offering integrated calibration management portals.
Subscription-based service contracts are displacing transactional accessory purchases. Large academic medical centers in California and Texas now bundle tip consumption, preventive maintenance, and compliance documentation into single annual agreements. This shift concentrates vendor relationships and raises switching costs for established supply partnerships.
Pipettes and Accessories Market Segmentation
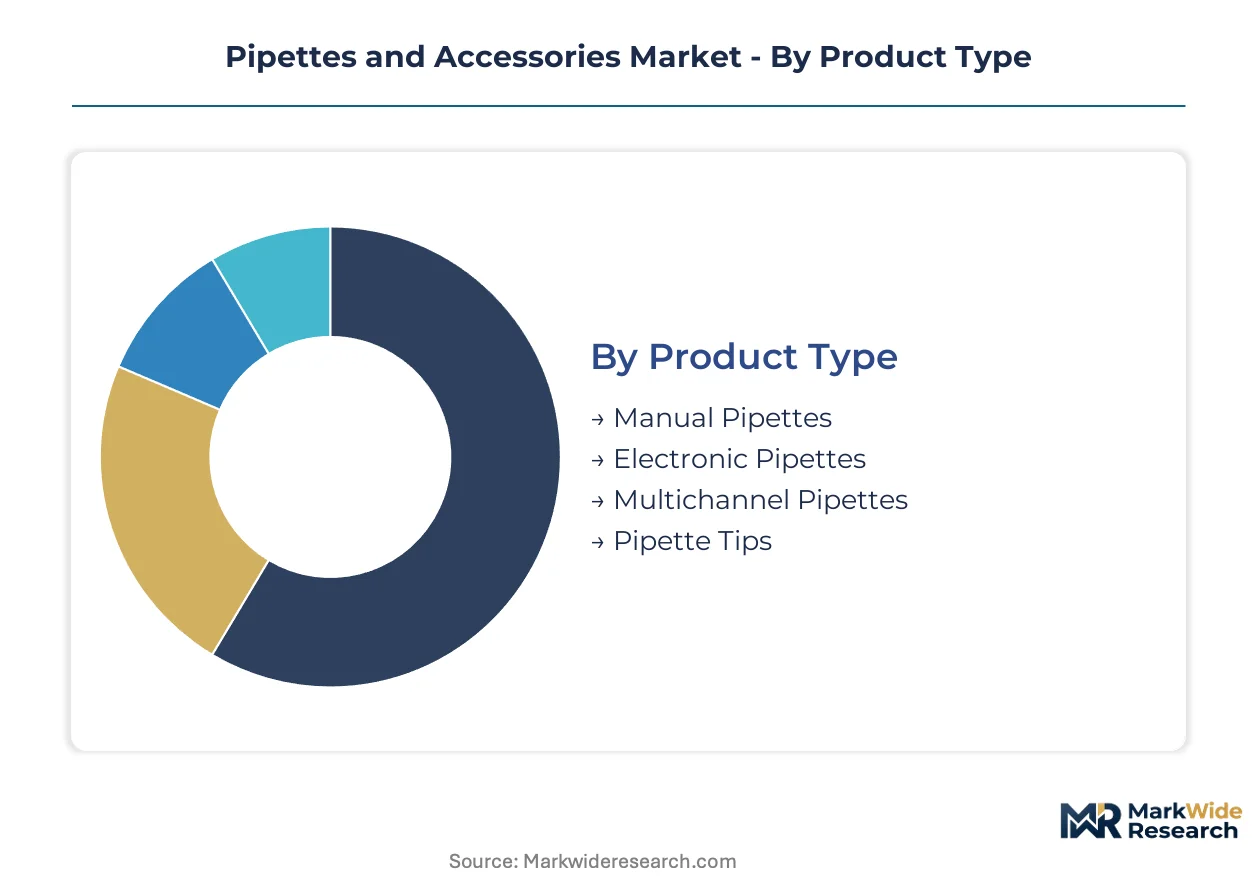
Segmentation in pipettes and accessories reveals divergent technology lifecycles and procurement patterns. Product type stratification shows electronic systems displacing manual instruments in regulated settings, while end-user concentration shapes service bundling strategies across pharmaceutical and academic channels.
Product Type:
Substitution pressure from electronic systems is most acute against manual variants in high-throughput environments, while polymer consumables face material competition from sustainable alternatives.
- Manual Pipettes:Spring-loaded piston mechanisms with fixed or adjustable volume ranges dominate introductory laboratory training. Academic institutions in Japan sustain volume through METI-funded equipment refresh programs despite electronic encroachment in research settings.
- Electronic Pipettes:Stepper motor-driven systems with programmable aspiration-dispense sequences and user ID logging command premium positioning. Pharmaceutical labs in Switzerland now mandate Bluetooth-enabled units for GMP traceability, compressing replacement cycles to three-year intervals.
- Multichannel Pipettes:Simultaneous 8- to 384-channel liquid transfer for microplate formats.
- Pipette Tips:Polypropylene consumables with filter barriers or low-retention coatings.
Pipette Tips anchors the volume base while Electronic Pipettes gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive pharmaceutical procurement from grant-dependent academic purchasing, with divergent service expectations.
- Pharmaceutical Labs:IND-enabling and QC workflows demand ISO 8655-compliant calibration documentation. FDA quality system regulations drive annual third-party verification contracts, concentrating vendor relationships around integrated service providers.
- Academic Institutions:Budget constraints favor manual systems and bulk tip purchasing. German university consortia now negotiate framework agreements pooling procurement across multiple institutions to extract volume discounts.
- Research Organizations:Contract research and government laboratory settings with mixed funding profiles.
- Clinical Laboratories:Diagnostic testing facilities with point-of-care and central lab configurations.
Academic Institutions anchors the volume base while Pharmaceutical Labs climbs the fastest.
Application:
Margin concentration varies sharply across workflow stages, with late-stage manufacturing quality control commanding service premiums over early discovery.
- Drug Development:Lead optimization through scale-up synthesis requires multichannel precision for compound library management. Massachusetts biotech clusters deploy electronic systems with LIMS integration to satisfy FDA IND documentation requirements.
- Quality Control:Release testing and stability studies mandate measurement uncertainty calculations. Swissmedic inspections of contract manufacturers now require pipette-specific calibration certificates traceable to national standards.
- Laboratory Testing:Environmental, food safety, and industrial analysis workflows.
- Scientific Research:Basic biology and chemistry investigations with flexible methodology requirements.
Scientific Research anchors the volume base while Drug Development expands most quickly.
Distribution Channel:
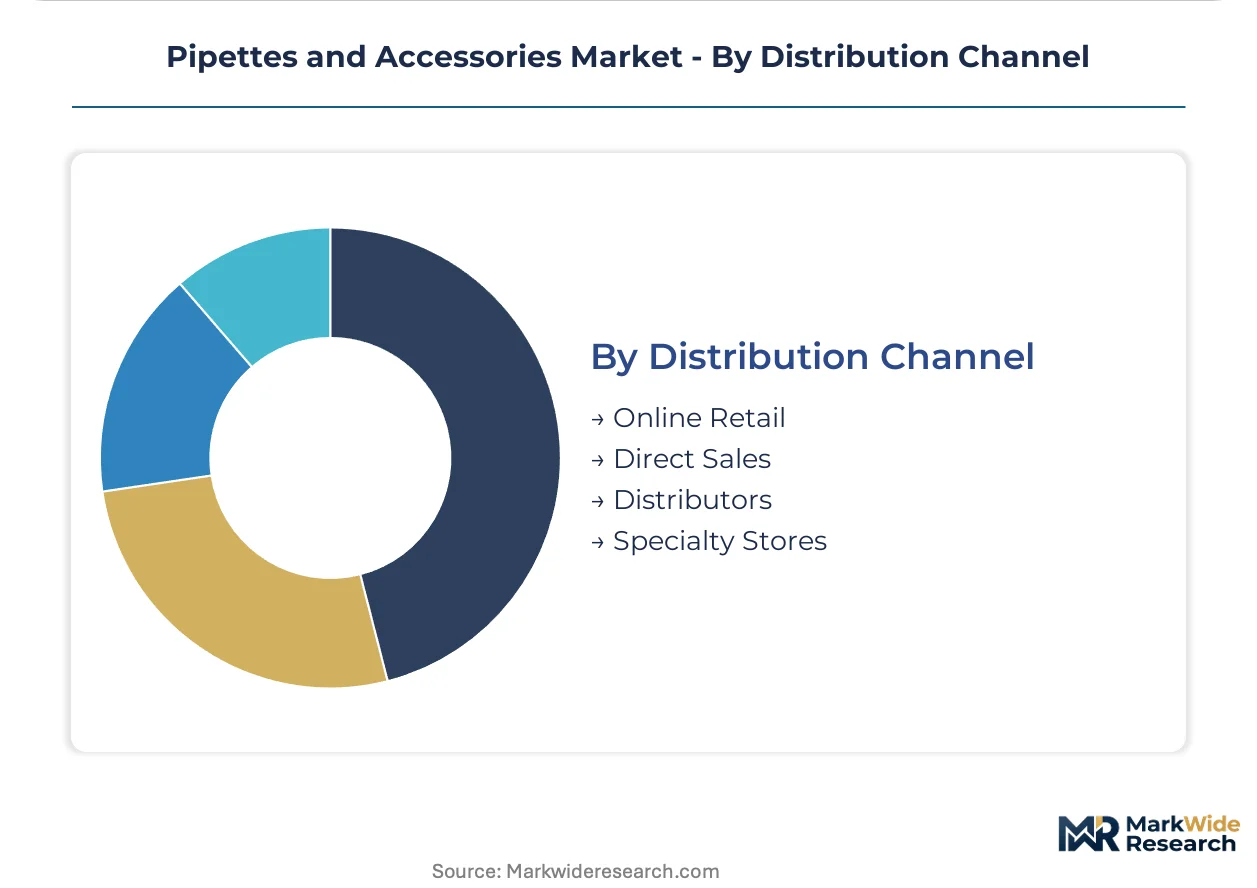
Geography shapes channel viability, with direct sales infrastructure proving essential for electronic system deployment in regulated markets.
- Online Retail:Ecommerce platforms capture price-sensitive tip replenishment and entry-level manual instrument sales. Indian B2B marketplaces now bypass distributor markups for BIS-certified accessories, compressing regional margin structures.
- Direct Sales:Field application scientists demonstrate electronic system operation and negotiate service contracts. Thermo Fisher's North American direct infrastructure anchors pharmaceutical procurement relationships through co-located technical support.
- Distributors:Regional inventory and logistics intermediaries serving mid-tier accounts.
- Specialty Stores:Local laboratory supply retailers with immediate availability for urgent replenishment.
Distributors anchors the volume base while Direct Sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical laboratories in the United States deploy multichannel electronic systems for high-throughput screening, while German academic consortia favor manual instruments under pooled procurement frameworks. This consumption-mix differential reflects divergent funding structures and regulatory maturity across developed markets.
United States
Massachusetts biotech clusters and California academic medical centers drive electronic pipette adoption for IND-enabling studies. FDA quality system regulations mandate documented liquid handling precision, compressing replacement cycles to three-year intervals. Greater Boston pharmaceutical corridors now require Bluetooth-enabled units for GMP traceability.
Germany
University consortia negotiate framework agreements pooling procurement across multiple institutions to extract volume discounts on manual systems. METI-equivalent standardization initiatives through DIN accelerate polymer barrel qualification for autoclavable constructions. Baden-Württemberg precision engineering clusters supply piston components to domestic instrument manufacturers.
Switzerland
Contract manufacturers face Swissmedic inspections requiring pipette-specific calibration certificates traceable to national standards. Basel pharmaceutical headquarters mandate integrated calibration management portals from suppliers. Geneva diagnostic laboratories concentrate demand for electronic systems with LIMS connectivity.
Japan
METI-funded equipment refresh programs sustain manual pipette volumes at academic institutions despite electronic encroachment in research settings. JIS-compliant material qualification accelerates polymer barrel adoption over borosilicate glass. Tokyo-Yokohama biotech corridors deploy multichannel configurations for compound library processing.
Brazil
ANVISA's updated IVD quality regulations compel public health laboratories toward calibrated electronic systems. São Paulo state research corridors remain underpenetrated, offering first-mover positioning for integrated service providers. Southern tip supply chain vulnerabilities for polypropylene filter-tips extend lead times for sterile consumables.
Pipettes and Accessories Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in laboratory liquid handling instrumentation. The upper tier commands premium positioning through direct sales infrastructure and bundled service contracts, while mid-tier specialists compete on ergonomic design or niche application focus. Three archetypes dominate: diversified life science conglomerates with extensive field application networks; precision engineering specialists with captive manufacturing of piston and barrel components; and consumables-focused suppliers leveraging high-volume tip production. Competitive moves concentrate on backward integration into polymer molding capacity and geographic expansion of ISO 17025-accredited calibration laboratories.
Among German-origin precision instrument manufacturers, Eppendorf AG and Sartorius AG exemplify the engineering-specialist archetype with strong domestic manufacturing footprints. Thermo Fisher Scientific Inc represents the diversified conglomerate model, anchoring North American pharmaceutical procurement through extensive direct sales infrastructure. These three occupy positions across the premium-to-mid-tier spectrum, with each sitting within distinct strategic vectors of the competitive map.
| Leading Market Players |
|---|
| Eppendorf AG |
| Thermo Fisher Scientific Inc |
| Gilson Inc |
| Sartorius AG |
| BRAND GMBH + Co KG |
| Hamilton Company |
| Corning Incorporated |
| INTEGRA Biosciences AG |
| Mettler Toledo |
| Others |
Value Network & Pricing Analysis
Polymer barrel substitution for borosilicate glass is simultaneously relocating manufacturing footprints from German precision engineering clusters to Chinese polymer molding centers and compressing per-unit production economics by two-thirds, forcing incumbents to recalibrate premium positioning strategies around calibration service bundling rather than instrument hardware margins.
Pricing Analysis
Long-term service contracts now dominate pharmaceutical procurement, displacing transactional instrument sales as FDA quality system regulations mandate annual ISO 8655 calibration verification. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled electronic systems with LIMS integration from manual variants and refurbished certified-preowned units. Cost compression in the mid-tier manual segment is intensifying because Indian B2B ecommerce platforms bypass traditional distributor markups for BIS-certified accessories. Academic institutions exhibit highest price sensitivity due to grant-dependent funding cycles, while pharmaceutical QC labs demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Strait of Malacca transit vulnerability for polypropylene resin shipments from Middle Eastern petrochemical complexes to southern Chinese molding facilities creates geographic chokepoint exposure for filter-tip production. Manufacturing concentrates in China for polymer consumables, Germany for precision piston components, and Switzerland for electronic calibration systems. Raw material dependencies include medical-grade polypropylene, rare-earth magnets for stepper motors, and borosilicate glass tubing. Single-source vulnerability in southern Chinese filter-tip production clusters generates supply disruption risk for European buyers facing ANSM import documentation delays. Distribution runs through direct sales infrastructure for electronic systems in regulated markets, with ecommerce platforms capturing price-sensitive consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic pipetting connectivity mandates from FDA and Swissmedic are accelerating a technological inflection that compresses replacement cycles and elevates recurring service revenues, creating high-growth disruption dynamics for stakeholders across the value chain.
For Market Incumbents: Shield installed base relationships by embedding calibration management portals that lock pharmaceutical customers into multi-year service contracts, while deepening backward integration into polymer molding capacity to offset Chinese supply concentration risks. ISO 17025-accredited laboratory scarcity represents the critical capability bottleneck to defend through targeted technician training investments. For New Entrants and Emerging Players: Lead with refurbishment channel development in price-sensitive Indian academic markets, where direct-to-laboratory ecommerce platforms bypass entrenched distributor networks. São Paulo state research corridors in Brazil offer the most penetrable geography given ANVISA regulatory upgrades compelling electronic system adoption against limited incumbent service infrastructure. For Investors and Strategic Acquirers: MDR recalibration requirements for clinical devices reshape the acquisition landscape toward calibration service providers with ISO 17025 accreditation and existing pharmaceutical relationships. Five-to-ten year viability favors precision engineering specialists with captive piston manufacturing and integrated software development capabilities. The signal to watch is consolidation velocity among mid-tier distributors as subscription-based service contracts concentrate vendor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Portal Development | Integrated ISO 8655 documentation platforms lock pharmaceutical customers into recurring revenue streams. |
| Backward Integration into Polymer Molding | Captive medical-grade polypropylene production reduces dependency on southern Chinese filter-tip clusters. |
| Bluetooth-Enabled System Launch | FDA GMP traceability mandates in Massachusetts biotech corridors compress demand for non-networked legacy units. |
| Refurbishment Channel Establishment | Certified pre-owned electronic programs capture price-sensitive segments in Indian B2B ecommerce marketplaces. |
| ISO 17025 Laboratory Expansion | Accredited calibration capacity addresses metrology technician scarcity extending Swiss pharmaceutical service turnaround times. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laboratory directors, procurement managers at pharmaceutical companies, biomedical engineers, and calibration service technicians; and secondary validation against FDA 483 inspection observations, ISO 8655 technical documentation, ANVISA regulatory filings, and trade flow data for polymer consumables. Bottom-up triangulation against top-down market sizing ensured segmentation coherence across product type, end user, and application dimensions.
Across the analysis window, the analytical framework modeled volume and value trajectories through disaggregation by electronic versus manual technology tiers, pharmaceutical versus academic end-user concentration, and drug development versus quality control application intensity. CAGRs were synthesized from replacement cycle compression dynamics, regulatory mandate adoption curves, and regional laboratory construction pipelines. Industry-specific forecast inputs included METI-funded equipment refresh program allocations and ANVISA IVD quality regulation implementation timelines.
Underlying assumptions cover sustained FDA quality system enforcement intensity and polymer resin supply stability, with deviation risk concentrated in China-US trade policy shifts affecting filter-tip import logistics and European MDR recalibration timeline extensions. Practitioners should keep alternative scenarios live as ISO 17025 laboratory capacity expansion and Bluetooth connectivity standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Global Laboratory Glassware Washers Market