
 Electronic Clutch Actuators Market | 2026-2036
Electronic Clutch Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Clutch Actuators Market Intelligence
Mechatronics engineering talent is reorganizing competitive dynamics across the electronic clutch actuator supply base. Continental leverages deep in-house electromechanical expertise to dominate integrated powertrain modules. Robert Bosch GmbH anchors its position through sensor fusion capabilities that tighten clutch engagement precision. ZF Friedrichshafen specializes in heavy-duty actuator variants for commercial vehicle torque demands.
Electronic clutch actuators are electromechanical devices that replace traditional mechanical or hydraulic clutch linkage systems, typically incorporating DC motors, position sensors, and gear reduction mechanisms to transmit calibrated force to clutch release bearings. They enable automated manual transmissions and dual-clutch systems to execute sub-200-millisecond gear changes while eliminating pedal effort. Electric actuators now lead product type dynamics as thermal efficiency targets push hydraulic fluid out of transmission architectures. Passenger vehicle applications command the largest volume base, though electric vehicle variants represent the fastest-growing application segment as EV makers adopt multi-speed gearboxes for performance trims.
NHTSA crashworthiness standards and EPA fuel economy mandates in the United States compel actuator designs that reduce driveline losses below mechanical benchmarks. EMA and REACH frameworks in Europe restrict hazardous substances in motor windings and sensor coatings, reshaping supplier qualification protocols. Stakeholders must monitor how cybersecurity regulations for connected powertrain components rewrite firmware validation requirements before committing to next-generation platform designs.
Market Dynamics
Transmission electrification is compressing development cycles for electronic clutch actuators as automakers eliminate mechanical linkages from powertrain architectures. Tier-1 suppliers now compete on electromechanical integration speed rather than component cost alone.
Growth Catalysts
- EPA fuel economy mandates:NHTSA crashworthiness standards compel actuator designs that cut driveline losses below mechanical benchmarks, forcing OEMs toward electrified clutch control systems.
- Electric vehicle multi-speed gearboxes:Performance-oriented EV platforms require precision clutch engagement for torque management, expanding actuator demand beyond traditional internal combustion applications.
- REACH substance restrictions:ECHA frameworks on hazardous materials in motor windings and sensor coatings are accelerating supplier qualification for compliant electromechanical architectures.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese supply chains compress margins for DC motor manufacturers serving actuator OEMs.
- Precision manufacturing concentration:Miniaturized gear reduction mechanisms depend on machining ecosystems clustered in southern Germany and Japan's Aichi Prefecture, creating single-source vulnerabilities.
- Hydraulic actuator installed base:Existing dual-clutch transmission lines in European assembly plants carry sunk costs that slow full electrification transitions.
Strategic Opportunities
- Commercial vehicle torque segments:Heavy-duty actuators for long-haul trucking remain underpenetrated by electronic solutions, offering white space for suppliers with thermal management expertise.
- Sensor fusion integration:Convergence of position feedback systems with predictive clutch wear algorithms enables outcome-based maintenance contracts for fleet operators.
- EU Green Deal industrial funding:Battery-electric platform subsidies in Germany and France are channeling capital toward domestic actuator production capacity.
Industry Challenges
- Mechatronics talent scarcity:Electromechanical system design expertise concentrates at Continental, Bosch, and ZF, constraining second-tier supplier technical staffing.
- Cybersecurity firmware validation:Connected powertrain components face evolving UN ECE R155 requirements that extend development timelines before platform commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Clutch Actuators Market |
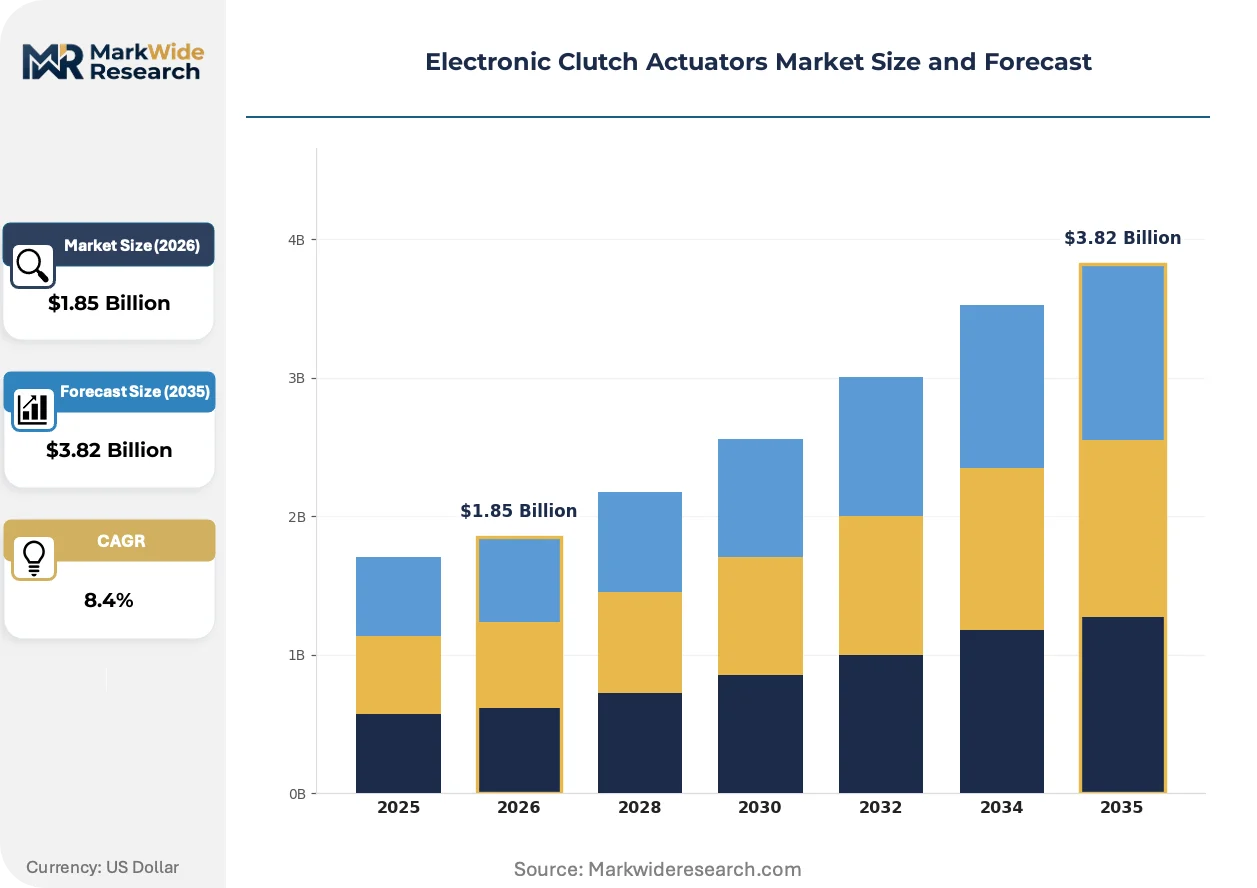
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Electric Actuators, Pneumatic Actuators, Mechanical Actuators Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Microcontroller-Based, Sensor-Based, Bluetooth Enabled, Wireless Communication |
| Companies Covered | Continental, Robert Bosch GmbH, ZF Friedrichshafen, DENSO Corporation, Infineon Technologies, WABCO, Magneti Marelli, Delphi Automotive, Allison Transmission, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Clutch Actuators Market Strategic Shifts & Innovations
Actuator architecture is pivoting from hydraulic fluid power toward solid-state electromechanical control. Three concurrent developments are compressing legacy supply positions while opening new technical frontiers for integrated powertrain modules.
Brushless DC motor technology with integrated position sensing is supplanting brushed motor designs in next-generation clutch actuators. Tier-1 suppliers in Germany and Japan are adopting these architectures for 2027 platform launches. The shift is compressing supplier qualification cycles from 36 months toward 18-month validation windows.
REACH substance restrictions on hexavalent chromium and certain phthalates in sensor coatings are forcing reformulation of motor winding insulation and connector housings. European suppliers face the steepest compliance timelines. Japanese actuator manufacturers are responding by qualifying alternative polymer compounds ahead of 2026 enforcement phases.
Fleet procurement departments now specify total cost of ownership metrics rather than unit pricing for clutch actuator contracts. Direct sourcing relationships between commercial vehicle OEMs and actuator specialists are displacing traditional distribution channels. This pattern is most visible in North American heavy-duty truck manufacturing, where vertical integration into powertrain assembly is accelerating.
Electronic Clutch Actuators Market Segmentation
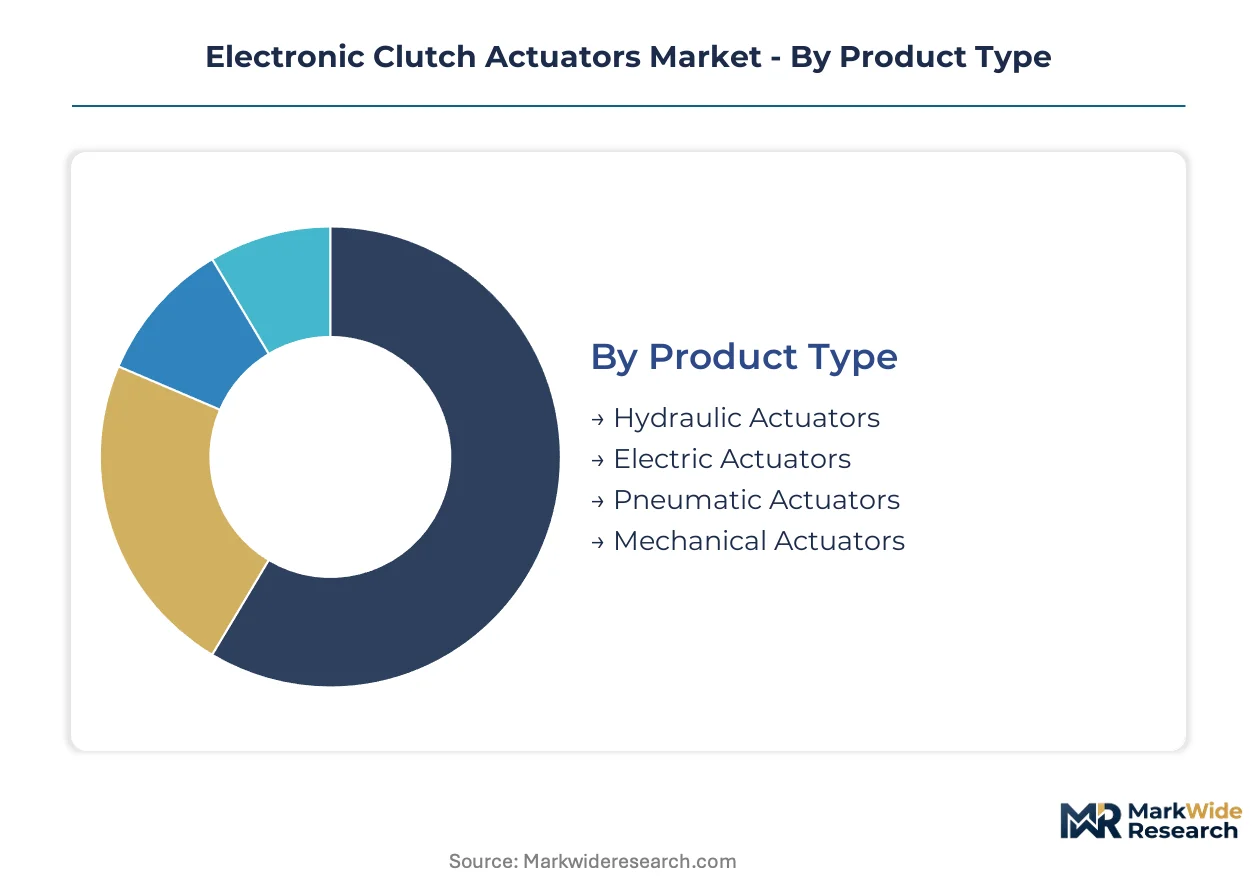
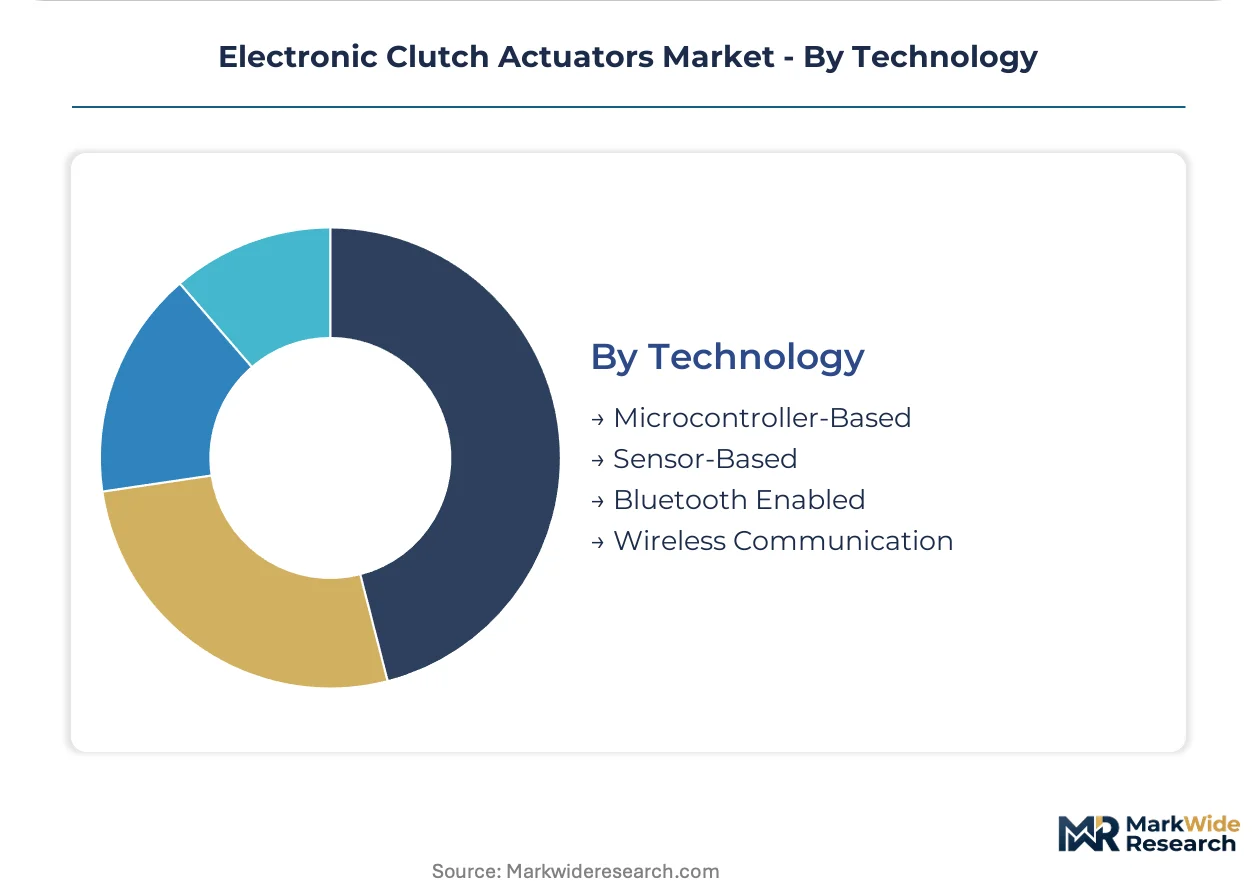
Electronic clutch actuator segmentation reveals how powertrain electrification is fragmenting demand across competing technical architectures. Each dimension—product type, application, end user, and technology—carries distinct regulatory pressures and margin structures that reshape supplier positioning.
Product Type:
REACH substance restrictions and EPA fuel economy mandates are bifurcating actuator procurement between hydraulic legacy systems and solid-state electric alternatives.
- Hydraulic Actuators:Fluid-powered systems utilizing pressurized mineral oil to transmit clutch engagement force through slave cylinders and release bearings. Established dual-clutch transmission lines in German and Spanish assembly plants carry sunk tooling costs that slow full electrification transitions despite thermal efficiency penalties.
- Electric Actuators:DC motor-driven electromechanical units with integrated position sensors and planetary gear reduction. Demand concentrates in Germany and Japan where precision machining ecosystems support miniaturized torque transmission components for automated manual transmissions.
- Pneumatic Actuators:Compressed-air systems limited to heavy-duty commercial vehicle segments with existing air brake infrastructure.
- Mechanical Actuators:Cable or linkage-based systems retaining niche presence in cost-sensitive motorcycle and emerging market applications.
Established volume favors hydraulic architectures; emerging adoption favors electric variants.
Application:
Cost tier differentiation separates mass-market passenger deployments from specialized commercial and electric vehicle requirements.
- Passenger Vehicles:High-volume automated manual and dual-clutch transmission applications demanding sub-200-millisecond shift precision. European OEMs in Germany and France specify integrated actuator-transmission modules that compress supplier margins through single-source contracting.
- Electric Vehicles:Multi-speed gearbox actuators for performance-oriented battery-electric platforms requiring torque-managed clutch engagement. Japanese and Chinese EV manufacturers are expanding procurement fastest as drivetrain architectures diversify beyond single-speed reduction.
- Commercial Vehicles:Heavy-duty actuators for long-haul trucking with thermal management requirements exceeding passenger specifications.
- Motorcycles:Compact actuators for automated manual transmissions in premium displacement segments.
Passenger applications dominate unit economics; electric vehicle demand is climbing the fastest.
End User:
Customer type determines whether procurement emphasizes unit cost, system integration speed, or aftermarket service density.
- OEMs:Vehicle manufacturers specifying integrated powertrain modules with 18-month platform validation cycles. German and Japanese OEMs are consolidating supplier bases toward electromechanical specialists with in-house mechatronics engineering.
- Tier-1 Suppliers:Transmission system integrators procuring actuator subassemblies for modular powertrain packaging. These intermediaries face margin compression as OEMs pursue backward integration into clutch control electronics.
- Aftermarket Providers:Independent distributors serving replacement demand for hydraulic actuator wear components in European vehicle parc.
- Vehicle Assemblers:Contract manufacturers and kit builders sourcing actuators for limited-production or regional vehicle programs.
Direct OEM relationships command premium positioning; aftermarket channels stabilize revenue through replacement cycles.
Technology:
Maturity gradients separate proven microcontroller architectures from connected-vehicle interfaces subject to evolving cybersecurity validation.
- Microcontroller-Based:Embedded control systems with deterministic response timing for safety-critical clutch engagement. These architectures dominate current production volumes but face firmware recertification costs under UN ECE R155 cybersecurity mandates.
- Sensor-Based:Position feedback systems with predictive wear algorithms enabling outcome-based maintenance contracts. Fleet operators in North American heavy-duty trucking are specifying these capabilities for total cost of ownership optimization.
- Bluetooth Enabled:Short-range wireless interfaces for diagnostic access and parameter configuration during assembly line calibration.
- Wireless Communication:Cellular or satellite-connected actuators supporting over-the-air updates and remote fleet monitoring.
Microcontroller foundations anchor current production; sensor fusion architectures are gaining share fastest through fleet procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, Japan, and China deploy electronic clutch actuators across fundamentally different powertrain strategies. German OEMs integrate actuators into dual-clutch systems for thermal efficiency. Japanese manufacturers prioritize miniaturized precision for hybrid architectures. Chinese EV platforms are adopting multi-speed gearboxes that demand torque-managed clutch engagement.
Germany
Automated manual transmission production for premium passenger vehicles drives actuator procurement volumes. The EU Green Deal industrial funding channels capital toward domestic electromechanical component manufacturing. Stuttgart and Munich host precision machining ecosystems where suppliers miniaturize gear reduction mechanisms for 2027 platform launches.
Japan
Hybrid powertrain diversification and performance EV multi-speed gearboxes expand actuator demand beyond traditional applications. METI carbon neutrality roadmaps accelerate transmission electrification timelines. Aichi Prefecture's manufacturing corridor concentrates brushless DC motor qualification programs for integrated clutch control modules.
China
Battery-electric vehicle platforms with multi-speed reduction systems are creating new actuator specifications for torque management. MIIT new energy vehicle mandates push automakers toward electrified transmission architectures. Shenzhen and Shanghai house the fastest-growing procurement programs for solid-state clutch control systems.
United States
Commercial vehicle fleet operators specify total cost of ownership metrics for heavy-duty clutch actuator contracts. NHTSA crashworthiness standards and EPA fuel economy mandates compel designs that cut driveline losses below mechanical benchmarks. Michigan and Ohio assembly plants are consolidating supplier bases toward electromechanical specialists with domestic engineering presence.
South Korea
Domestic OEMs are backward integrating into clutch control electronics for hybrid and electric platforms. The national automotive regulator enforces cybersecurity validation timelines under UN ECE R155 frameworks. Seoul Capital Area engineering centers are compressing platform validation cycles from 36 months toward 18-month windows.
Electronic Clutch Actuators Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the electronic clutch actuator supply base. Continental, Robert Bosch GmbH, and ZF Friedrichshafen anchor the upper tier through captive mechatronics engineering and sensor fusion capabilities. Mid-scale specialists compete on thermal management expertise for commercial vehicle segments or miniaturization speed for passenger applications. Dominant competitive moves include backward integration into clutch control firmware and geographic expansion through EU Green Deal-funded production capacity.
Within the integrated tier, Continental exemplifies the electromechanical systems archetype through deep in-house engineering consolidation. Robert Bosch GmbH anchors sensor fusion positioning that tightens engagement precision across powertrain modules. ZF Friedrichshafen occupies the heavy-duty specialization vector for commercial vehicle torque demands. These three firms represent distinct competitive postures: full-system integration, precision feedback control, and thermal-rated mechanical design.
| Leading Market Players |
|---|
| Continental |
| Robert Bosch GmbH |
| ZF Friedrichshafen |
| DENSO Corporation |
| Infineon Technologies |
| WABCO |
| Magneti Marelli |
| Delphi Automotive |
| Allison Transmission |
| Others |
Cost & Logistics Intelligence
Brushless DC motor substitution for brushed designs simultaneously shifts procurement geography toward German and Japanese precision machining clusters while compressing supplier margins through accelerated 18-month validation cycles. This technical transition rewards Tier-1 suppliers with captive electromechanical engineering while squeezing second-tier competitors dependent on outsourced motor sourcing.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement for 2027 platform launches, with pricing stratifying across premium integrated modules, standard subassemblies, and economy retrofit kits. Price differentiation hinges on REACH compliance certification and thermal management performance tier. Cost compression in economy hydraulic replacement segments is intensifying because Chinese rare earth magnet volatility feeds into DC motor input costs. Fleet operators in North American heavy-duty trucking exhibit lowest price sensitivity due to total cost of ownership contracting, while aftermarket distributors face highest sensitivity on unit replacement economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Japanese OEMs, though rare earth magnet exposure is forcing strategic stockpiling of neodymium and dysprosium by motor manufacturers. Geographic supply concentration centers on Germany, Japan, and China for precision gear reduction mechanisms, brushless DC motors, and position sensor subassemblies. Raw material dependencies rest on rare earth magnets, high-grade polymer compounds for REACH-compliant housings, and precision-machined planetary gears. Single-source vulnerability in southern Germany and Aichi Prefecture machining ecosystems creates structural risk. Distribution runs through direct OEM relationships displacing traditional Tier-1 intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic clutch actuators are approaching a platform-economics inflection where powertrain electrification standardization will consolidate winners around integrated firmware-hardware ecosystems. Interoperability between sensor fusion algorithms and predictive maintenance platforms is reshaping competitive moats.
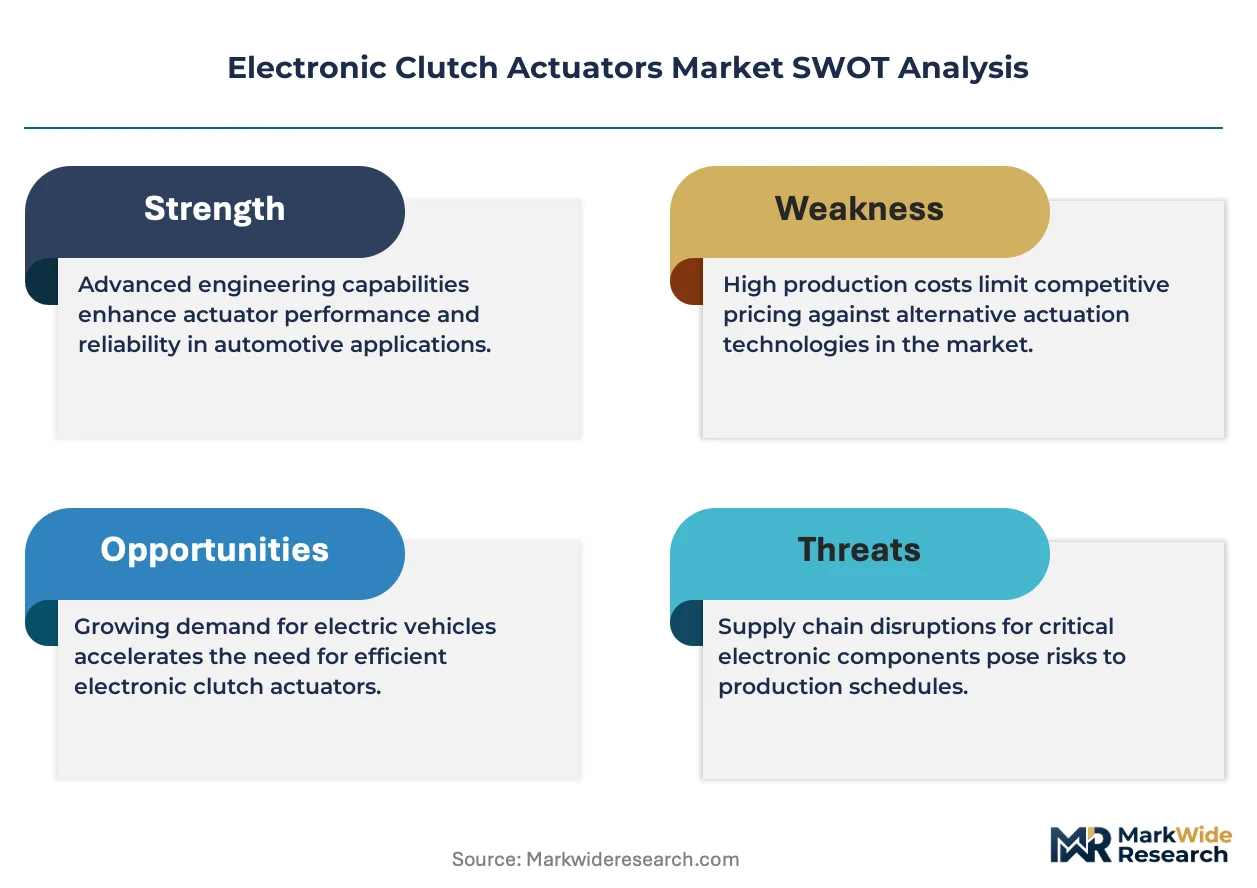
For Market Incumbents: Compound sensor fusion capabilities with predictive clutch wear algorithms to lock in fleet operator outcome-based contracts. Deepen backward integration into brushless DC motor production to offset rare earth cost volatility. Prioritize firmware cybersecurity certification under UN ECE R155 ahead of regulatory enforcement windows to defend against emerging electromechanical specialists.
For New Entrants and Emerging Players: Fleet telematics integration gaps in commercial vehicle segments offer white-space entry where incumbents under-serve long-haul thermal management requirements. Target North American heavy-duty trucking procurement departments with direct sensor-enabled actuator sourcing bypassing traditional distribution. Pursue EU Green Deal-funded production capacity in France or Germany to qualify for domestic OEM preference programs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding REACH-compliant polymer formulation IP. Five-to-ten year viability hinges on actuator firmware differentiation rather than mechanical commodity positioning. Acquisition target archetype: mid-scale thermal management specialists with commercial vehicle validation history. Watch for MIIT enforcement tightening on multi-speed EV gearbox specifications as inflection signal for Chinese demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Integration | Eliminates rare earth exposure while meeting EPA thermal efficiency mandates for 2027 platforms. |
| Sensor Fusion Platform Development | Enables predictive maintenance contracts with North American fleet operators seeking total cost optimization. |
| EU Green Deal Production Expansion | Qualifies suppliers for German and French OEM domestic content preferences in battery-electric platforms. |
| Cybersecurity Firmware Certification | Accelerates UN ECE R155 compliance ahead of connected powertrain regulatory enforcement phases. |
| Commercial Vehicle Thermal Specialization | Captures underpenetrated long-haul trucking segments with actuator designs exceeding passenger-duty specifications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 transmission system integrators, commercial vehicle fleet procurement directors, and precision machining subcontractor operations managers. Secondary validation drew from NHTSA crashworthiness filings, EPA fuel economy compliance databases, ECHA REACH substance restriction updates, and vehicle production registration data. Bottom-up actuator unit demand modeling was triangulated against top-down powertrain electrification spend projections.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, application, vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs were derived from regression analysis of historical platform adoption curves and forward projection of regulatory compliance timelines. Industry-specific inputs included MIIT new energy vehicle mandate enforcement schedules and EU Green Deal industrial funding disbursement patterns.
Forecasts assume regulatory continuity in EPA, NHTSA, ECHA, and MIIT regimes; material policy shifts on emissions standards or rare earth export controls would require re-modeling. Supply chain disruption scenarios from geopolitical friction or precision manufacturing cluster concentration risk are sensitivity-tested but not base-case assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automotive Axle Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Headliners Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market