
 Automotive Metal Timing Chain Market | 2026-2036
Automotive Metal Timing Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Metal Timing Chain Market Analysis
Market Context with Strategic Players
Precision metallurgy talent scarcity is redrawing competitive boundaries across the Automotive Metal Timing Chain Market. BorgWarner Inc. leverages its integrated manufacturing footprint to secure long-term OEM contracts for dual-row architectures. Schaeffler AG anchors European supply through captive steel-processing capabilities and in-house heat-treatment operations. Tsubakimoto Chain Co. dominates Asian tier-1 sourcing relationships with proprietary silent-chain surface-finishing techniques.
Technical Definition and Structural Segments
An automotive metal timing chain is a roller or silent chain assembly that synchronizes crankshaft and camshaft rotation, typically fabricated from case-hardened alloy steel with pitch tolerances below 0.05 millimeters to maintain valve timing accuracy under cyclic thermal load. Its primary purpose is to transmit rotational power with minimal stretch across engine operating cycles, replacing belt-driven systems in high-mileage and high-temperature applications. Silent chains command premium positioning among passenger vehicle OEMs due to reduced acoustic signatures and extended service intervals, while roller chains sustain aftermarket volume through lower unit costs and broader mechanic familiarity. Alloy steel formulations represent the fastest-expanding material category as manufacturers balance fatigue resistance against weight reduction targets for downsized turbocharged engines.
Regulatory Frame and Forward-Looking Close
EPA fuel-economy mandates, Euro 7 emission limits, and China's MIIT dual carbon goals collectively tighten permissible engine-efficiency tolerances, forcing chain suppliers to validate micron-grade wear performance under standardized test protocols. NHTSA durability requirements and REACH substance restrictions further constrain lubricant chemistry and surface-coating selections available to manufacturers. Stakeholders must monitor how evolving particulate-emission rules for gasoline direct-injection engines reshape cam-phasing hardware specifications and corresponding chain-load profiles.
Market Dynamics
Hybrid powertrain proliferation is compressing development cycles for precision-engineered timing chains as OEMs redesign valve-train architectures to accommodate dual-mode combustion strategies.
Growth Catalysts
- Euro 7 Emission Limits:Stringent NOx and particulate caps force engine calibrations demanding tighter valve timing tolerances. Chain suppliers validate sub-micron wear rates under accelerated thermal cycling.
- Alloy Steel Formulations:Advanced case-hardening processes enable thinner link plates without fatigue degradation. Downsized turbocharged engines adopt these chains for weight-critical applications.
- Germany:Dense clustering of vehicle assemblers and captive steel-processing infrastructure anchors continental procurement volumes for silent-chain architectures.
Market Restraints
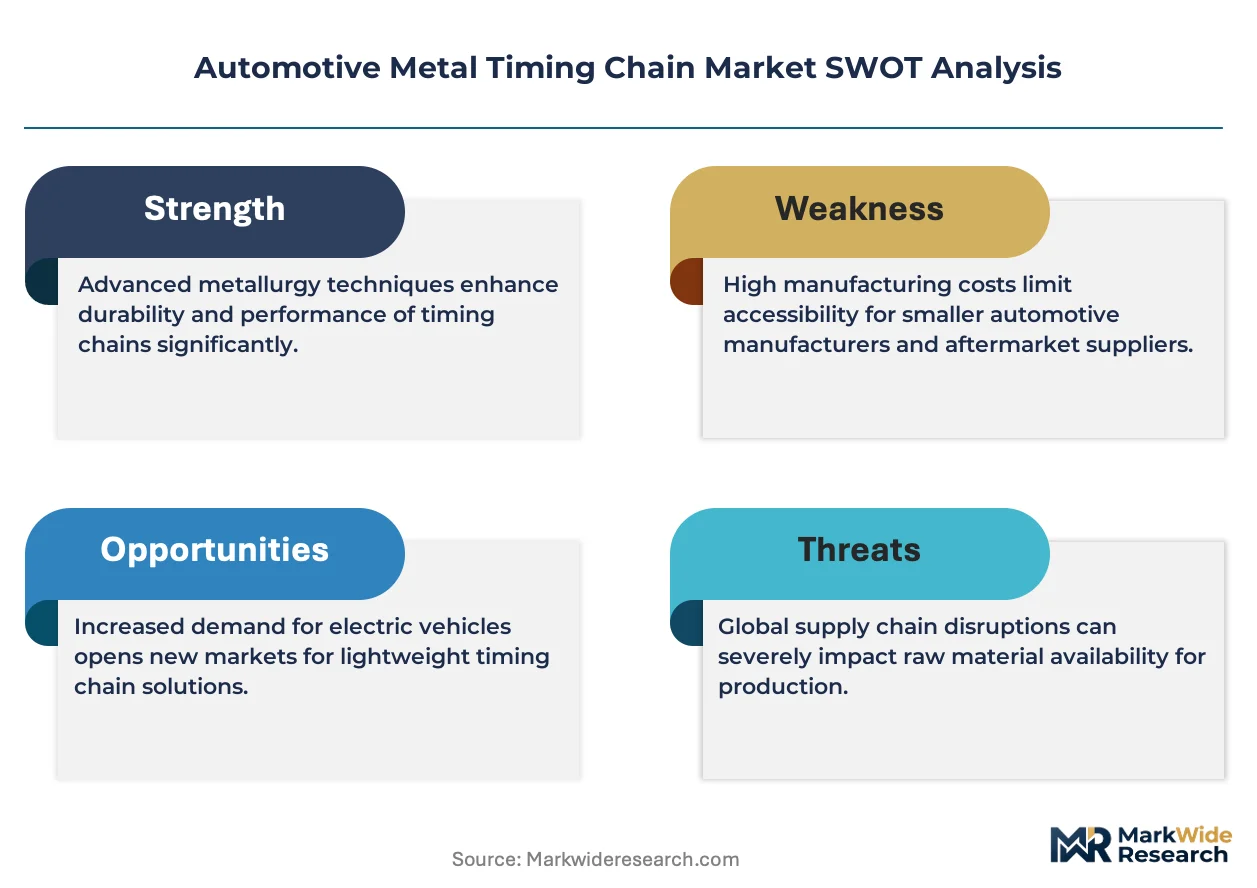
- Specialized Heat-Treatment Capacity:Controlled atmosphere carburizing furnaces require capital intensity that constrains supplier expansion. Equipment lead times exceed eighteen months.
- REACH Substance Restrictions:Lubricant chemistry limitations eliminate certain anti-wear additives. Surface-coating selections narrow to compliant alternatives with unproven field durability.
- Belt-Drive Substitution:Low-cost synchronous belts retain share in cost-sensitive vehicle segments. Timing belts require no lubrication and offer quieter operation at equivalent service intervals.
Strategic Opportunities
- India:Domestic vehicle production scales under PLI scheme incentives. Localized chain manufacturing escapes import duty exposure while serving Maruti Suzuki and Tata Motors assembly plants.
- Cam-Phasing Hardware Convergence:Variable valve timing actuators integrate directly with chain tensioner modules. Combined subassemblies reduce OEM assembly complexity and warranty exposure.
- Direct-to-Workshop Distribution:Authorized service networks bypass traditional tier-2 distributors. Digital catalog systems enable VIN-specific chain kit matching with same-day fulfillment.
Industry Challenges
- Precision Metallurgy Talent Scarcity:Case-hardening process engineers with automotive chain experience command premium compensation. University programs lack specialized curricula in this niche.
- Multi-Protocol Certification Timelines:Simultaneous EPA, Euro 7, and MIIT validation requires redundant test cell capacity. Divergent wear-test protocols extend qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Metal Timing Chain Market |
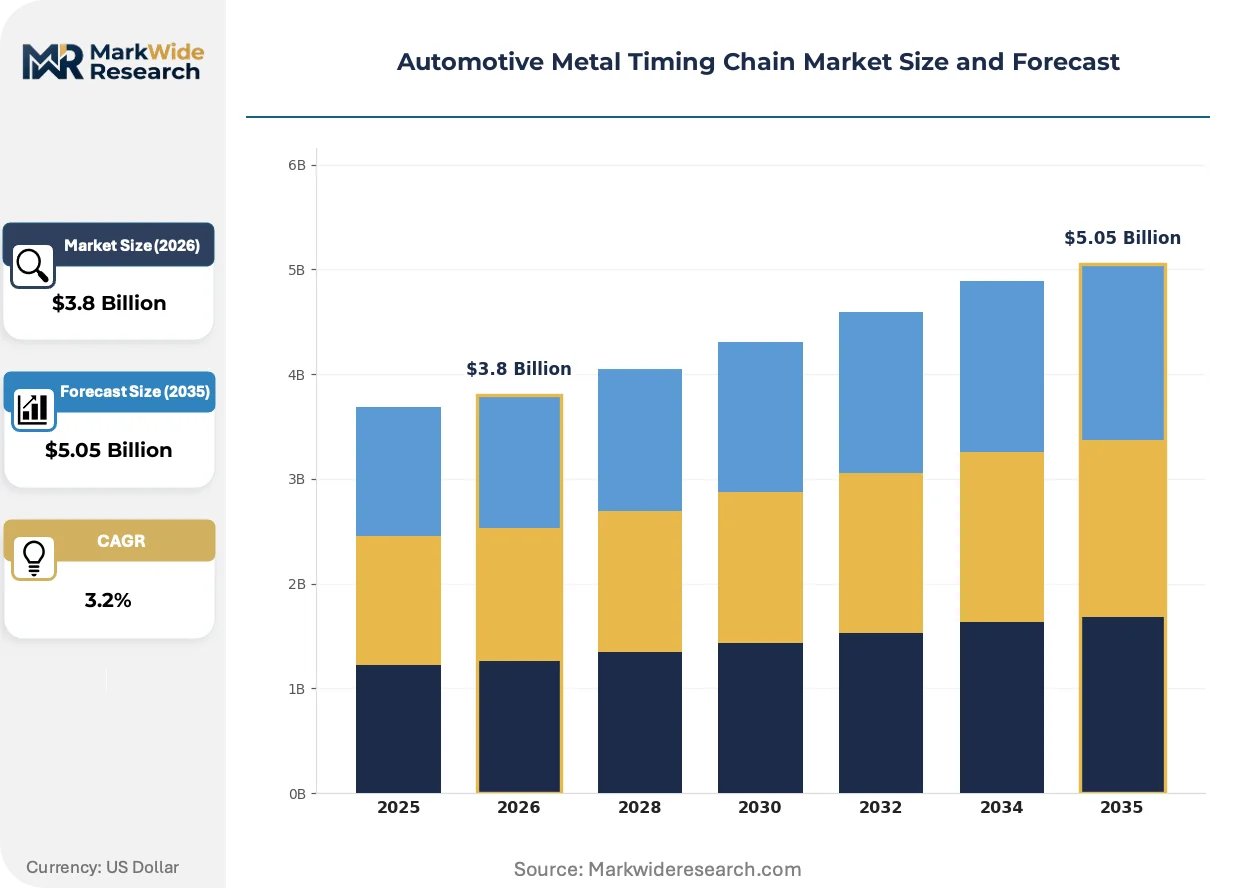
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-row Timing Chains, Dual-row Timing Chains, Roller Chains, Silent Chains Material: Steel, Alloy Steel, Stainless Steel, Nylon End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Industrial Engines |
| Companies Covered | BorgWarner Inc., Schaeffler AG, Continental AG, Iwis Motorsysteme GmbH & Co. KG, Tsubakimoto Chain Co., Aisin Corporation, MAHLE GmbH, Daido Metal Co. Ltd., Dayco IP Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Metal Timing Chain Market Emerging Trajectories
Silent-chain surface finishing is fragmenting established supplier hierarchies as proprietary treatments differentiate acoustic performance. Material science advances now dominate competitive positioning.
Diamond-like carbon coatings are fragmenting conventional phosphate-based surface treatments. These films reduce friction coefficients by forty percent under boundary lubrication conditions. Premium passenger vehicle OEMs specify DLC-treated silent chains for hybrid applications where engine restart noise must be minimized. The technology compresses supplier margins as coating equipment amortization accelerates.
EPA Corporate Average Fuel Economy standards tighten permissible engine-efficiency tolerances through model year 2032. Chain suppliers must document micron-grade wear degradation under standardized duty cycles. Gasoline direct-injection architectures face heightened scrutiny for particulate emissions, reshaping cam-phasing hardware specifications and corresponding chain-load profiles. US-based engineering teams prioritize test-protocol alignment with NHTSA durability requirements.
Consolidated tier-1 procurement is displacing fragmented multi-sourcing for critical powertrain components. Major vehicle assemblers reduce approved vendor lists from six suppliers to two qualified partners per platform. Long-term capacity reservation contracts replace spot-volume purchasing. This concentration is most visible in Germany, where Schaeffler and Iwis anchor exclusive supply relationships with domestic premium manufacturers.
Automotive Metal Timing Chain Market Segmentation
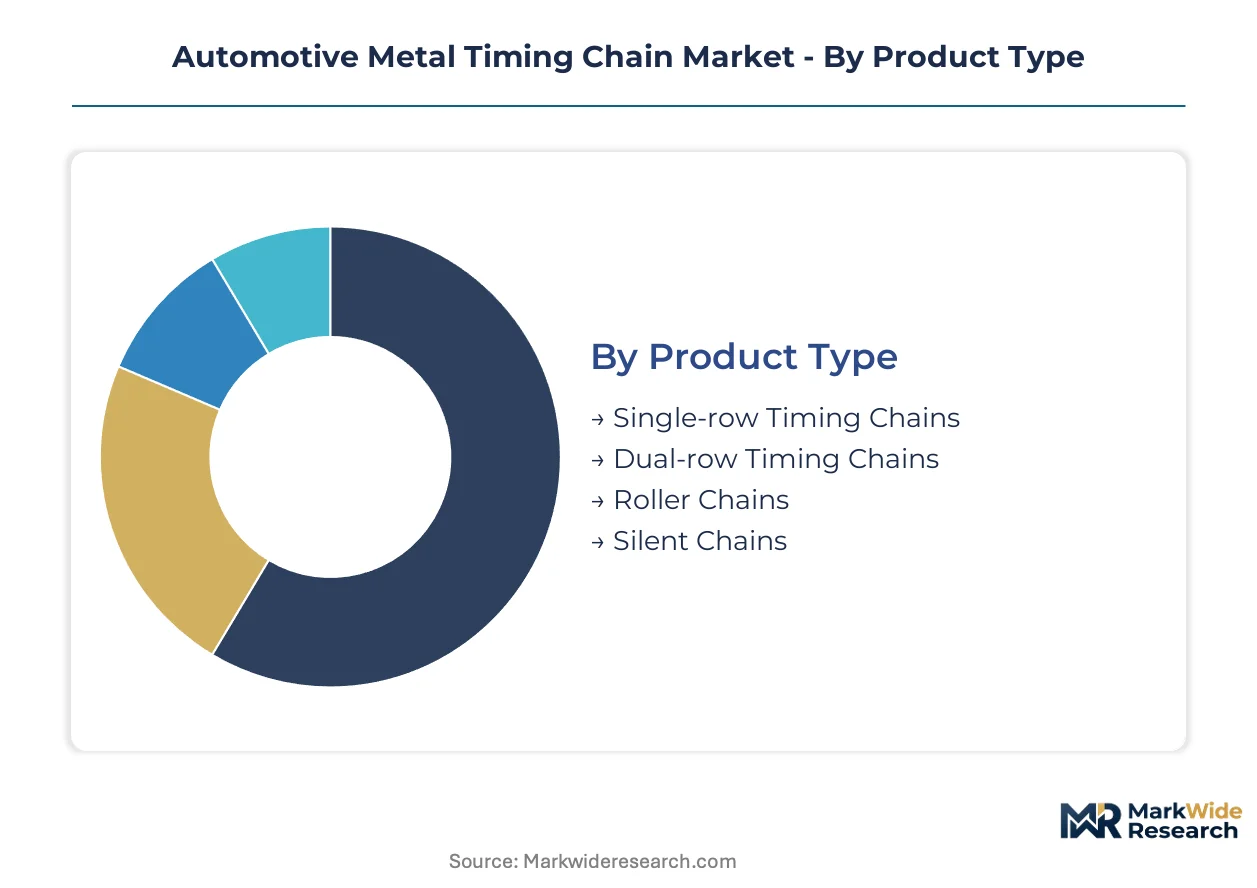
Chain architecture selection directly determines compliance margins under divergent emissions regimes. Product type, material grade, and end-user channel each impose distinct certification burdens and margin structures across supplier portfolios.
Product Type:
Euro 7 particulate caps and EPA fuel-economy mandates differentiate chain architectures by valve-timing precision requirements. Silent chains face stricter acoustic validation for hybrid restart sequences; roller chains confront durability thresholds for commercial mileage accumulation.
- Single-row Timing Chains:Compact link-plate assemblies serve inline three-cylinder and four-cylinder engines where packaging constraints dominate. Downsized turbocharged powertrains in Germany and Japan concentrate procurement for these architectures as OEMs pursue CO2 reduction targets.
- Dual-row Timing Chains:Parallel chain strands distribute tensile loads across V6 and V8 crankshaft sprockets. High-displacement hybrid applications in the United States specify these designs to manage torque spikes during electric-to-combustion mode transitions.
- Roller Chains:Cylindrical bushings reduce friction in aftermarket replacement cycles. Mechanic familiarity sustains volume across independent repair networks in cost-sensitive vehicle segments.
- Silent Chains:Toothed link plates engage sprockets with minimal impact noise. Premium passenger vehicle OEMs specify these for cabin acoustic targets under NHTSA and KBA homologation protocols.
Established volume favors roller chains; emerging adoption favors silent chains.
Material:
Cost tier stratification separates commodity steel from engineered alloy formulations. Heat-treatment intensity and case-hardening depth determine fatigue performance under cyclic thermal loading.
- Alloy Steel:Chromium-molybdenum blends enable thinner cross-sections without tensile degradation. Downsized turbocharged engines specify these chains to meet weight-reduction targets under EPA Corporate Average Fuel Economy standards.
- Steel:Plain carbon grades anchor aftermarket price competition. Volume production in India serves domestic vehicle assembly under PLI scheme localization requirements.
- Stainless Steel:Corrosion resistance extends service intervals in marine and high-humidity applications. Niche demand concentrates in coastal European markets with aggressive road-salt exposure.
- Nylon:Composite link plates reduce mass in auxiliary drive applications. Experimental adoption faces REACH substance scrutiny for polymer stabilizer chemistry.
Procurement volume concentrates in steel; technology investment flows to alloy steel.
End User:
Channel structure dictates warranty exposure and technical support obligations. OEM direct relationships require embedded engineering teams; aftermarket channels demand inventory velocity.
- OEMs:Original equipment manufacturers specify chains at platform design inception. Long-term capacity reservation contracts with Schaeffler AG and Tsubakimoto Chain Co. lock in volume through model-cycle durations.
- Tier-1 Suppliers:Integrated powertrain module producers consolidate chain procurement with cam-phasing hardware. Combined subassembly shipments reduce OEM line-side complexity.
- Vehicle Assemblers:Final assembly plants in Germany and the United States manage just-in-sequence chain kit deliveries. VIN-specific matching systems eliminate misassembly risk.
- Aftermarket Providers:Distributors and service networks stock replacement chains for high-mileage vehicles. Digital catalog platforms enable same-day fulfillment to authorized workshops.
Revenue concentration sits with OEMs; margin expansion favors aftermarket channels.
Application:
Engine operating cycles differentiate load profiles and lubrication regimes. Passenger vehicle refinement targets contrast with commercial vehicle durability requirements.
- Passenger Vehicles:Silent-chain architectures dominate acoustic-sensitive applications. Hybrid powertrain proliferation in Japan and South Korea drives specification for engine restart noise suppression.
- Commercial Vehicles:Dual-row roller chains withstand extended duty cycles under variable load. EPA and Euro 7 durability validation extends to 500,000-kilometer equivalent testing.
- Motorcycles:Compact single-row designs balance weight against tensile strength. High-revving sportbike engines in Italy and Japan specify specialized heat-treatment protocols.
- Industrial Engines:Stationary power generation and agricultural machinery adopt automotive-derived chain geometries. REACH lubricant restrictions constrain aftermarket chemistry selection for these non-road applications.
Unit volume leadership belongs to passenger vehicles; steepest expansion trajectory appears in commercial vehicle electrification hybrids.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel-economy mandates through model year 2032 anchor North American procurement intensity. Euro 7 emission caps and China's MIIT dual carbon goals reshape sourcing patterns across three additional manufacturing clusters.
United States
Hybrid powertrain proliferation at Detroit Three assembly plants drives dual-row timing chain procurement for V6 torque management. NHTSA durability protocols mandate 150,000-mile equivalent validation testing. Michigan and Ohio production corridors concentrate just-in-sequence deliveries to final assembly plants.
Germany
Premium vehicle OEMs in Stuttgart and Munich specify silent-chain architectures for cabin acoustic compliance. KBA homologation requirements enforce sub-micron wear validation under accelerated thermal cycling. Bavaria and Baden-Württemberg host captive steel-processing infrastructure for Schaeffler AG and Iwis Motorsysteme.
China
Domestic vehicle production scaling under MIIT dual carbon targets compresses development cycles for downsized turbocharged engines. GB standards for engine efficiency tighten valve-timing tolerances. Yangtze River Delta manufacturing corridors concentrate tier-1 sourcing relationships with local vehicle assemblers.
Japan
Hybrid restart noise suppression requirements from Toyota and Honda drive silent-chain specification for passenger vehicle platforms. METI energy efficiency guidelines prioritize weight-reduction targets for powertrain components. Aichi Prefecture and Kanto manufacturing belts anchor precision metallurgy talent pools.
India
Maruti Suzuki and Tata Motors assembly expansion under PLI scheme incentives attracts localized chain manufacturing investment. BIS automotive component standards harmonize with Euro 6-equivalent emission thresholds. Gujarat and Tamil Nadu industrial corridors concentrate domestic steel processing for cost-sensitive vehicle segments.
Automotive Metal Timing Chain Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the supplier base. Consolidated tier-1 procurement relationships favor integrated manufacturers with captive metallurgy capabilities. Three archetypes dominate: integrated European specialists with in-house heat-treatment, Asian scale producers with surface-finishing expertise, and diversified powertrain conglomerates with module-integration capabilities. Capacity reservation contracts and backward integration into alloy steel processing represent the dominant competitive moves.
Within the integrated European specialist tier, Schaeffler AG and Iwis Motorsysteme GmbH & Co. KG exemplify manufacturers with captive steel-processing infrastructure. Tsubakimoto Chain Co. occupies a position among Asian fabricators emphasizing proprietary silent-chain finishing techniques. These three companies represent distinct geographic and capability anchors across the competitive structure.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Schaeffler AG |
| Continental AG |
| Iwis Motorsysteme GmbH & Co. KG |
| Tsubakimoto Chain Co. |
| Aisin Corporation |
| MAHLE GmbH |
| Daido Metal Co. Ltd. |
| Dayco IP Holdings LLC |
| Others |
Supply Flow & Price Mechanics
Eighteen-month equipment lead times for controlled atmosphere carburizing furnaces concentrate supplier pricing power among German and Japanese manufacturers with captive heat-treatment infrastructure. OEMs absorb premium positioning for silent-chain architectures while aftermarket channels face cost compression from belt-drive substitution threats.
Pricing Analysis
German silent-chain quotations command substantial premiums over Indian roller-chain equivalents due to KBA homologation overhead and embedded engineering support. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale commitments. Cost compression in the aftermarket tier is intensifying because belt-drive systems require no lubrication and offer equivalent service intervals. Independent repair networks exhibit highest price sensitivity; premium OEM direct procurement shows lowest.
Supply Chain Analysis
Just-in-sequence delivery dominates OEM relationships while tier-2 distributors maintain strategic safety stock for aftermarket fulfillment. Supply concentrates in Germany, China, and Japan through Schaeffler AG, Tsubakimoto Chain Co., and domestic Yangtze River Delta fabricators. Production draws from chromium-molybdenum alloy steel, case-hardening equipment, and REACH-compliant lubricant chemistry. Single-source vulnerability persists in specialized heat-treatment furnace manufacturing. Distribution runs through tier-1 module integrators to final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against synchronous belt systems that eliminate lubrication requirements and noise penalties. Incumbents must navigate belt-drive share retention in cost-sensitive vehicle segments.
For Market Incumbents: Fortify captive steel-processing capabilities to defend margin position against integrated powertrain conglomerates. Backward integration into alloy steel refining secures supply continuity under REACH substance restrictions. Prioritize DLC coating equipment amortization to maintain acoustic performance differentiation against belt-drive alternatives.
For New Entrants and Emerging Players: Lead with cam-phasing hardware convergence opportunities in India's PLI scheme corridors. Localized manufacturing for Maruti Suzuki and Tata Motors assembly plants escapes import duty exposure. Target direct-to-workshop distribution bypassing traditional tier-2 channels.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tier-1 procurement concentration reduces approved vendor lists from six suppliers to two qualified partners per platform. Acquire mid-cap specialists with in-house heat-treatment and EPA-Euro 7 dual certification. Watch for Euro 7 particulate-emission rule finalization as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Contracts | Long-term volume commitments with BMW and Mercedes-Benz secure utilization rates. |
| Backward Integration into Alloy Steel | Captive chromium-molybdenum processing eliminates raw material price volatility exposure. |
| DLC Coating Equipment Deployment | Diamond-like carbon films reduce friction coefficients for hybrid restart noise compliance. |
| Cam-Phasing Module Integration | Combined tensioner-actuator subassemblies reduce OEM line-side complexity. |
| India PLI Localization | Gujarat manufacturing serves Maruti Suzuki under domestic content requirements. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, tier-1 powertrain procurement, aftermarket distribution, and precision metallurgy equipment manufacturing. Primary interviews with Schaeffler AG and Tsubakimoto Chain Co. commercial executives validated volume assumptions. Secondary sources included EPA fuel-economy filings, KBA homologation databases, MIIT dual carbon policy documents, and IHS Markit vehicle production data. Bottom-up chain demand modeling triangulated against top-down powertrain production forecasts.
Across the analysis window, projections integrated product type segmentation by architecture, material grade stratification, and end-user channel structure. CAGRs derived from platform-level content-per-vehicle trajectories and regional powertrain mix shifts. Hybrid powertrain proliferation rates and Euro 7 emission compliance timelines served as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside EPA-Euro 7 regulatory convergence or belt-drive substitution acceleration would require recalibration. Forecasts reflect assumptions around alloy steel availability and REACH lubricant chemistry continuity. Revision becomes warranted when heat-treatment equipment lead times exceed twenty-four months or when China MIIT standards diverge from Euro 7 benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Buffers Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Advanced Automotive Materials Market