
 Electrodeionization (EDI) Technology Market | 2026-2036
Electrodeionization (EDI) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Electrodeionization (EDI) Technology Market Foresight
North American membrane module producers is expanding fabrication lines to serve power sector and microelectronics clients. Veolia leverages integrated water service contracts across multiple industrial sites. Evoqua Water Technologies sustains technology leadership through concentrated R&D in high-flow stack architectures. DuPont anchors membrane chemistry supply with proprietary ion-selective polymer formulations.
Electrodeionization (EDI) technology combines ion exchange resins with electrodialysis membranes to remove dissolved ions from water without chemical regeneration, typically achieving resistivity above 16 megohm-centimeter for ultrapure water applications. The process uses direct current to drive ions through alternating cation and anion exchange membranes while resin beds continuously regenerate, eliminating acid and caustic handling associated with mixed-bed deionization. Electrodeionization Stack configurations dominate capital deployment due to their modular scalability and direct integration into ultrapure water trains. Ion Exchange Membranes command differentiated margin pools where fluoropolymer chemistry and thin-film casting precision create supply bottlenecks. Capacitive Deionization occupies a narrower niche in brackish water pre-treatment where energy efficiency trumps ultimate purity requirements.
The EPA enforces Maximum Achievable Control Technology standards for boiler feedwater in power generation, while China's MEE administers GB 8978 wastewater discharge limits that indirectly mandate higher upstream purification performance. ISO 9001 and semiconductor industry specifications from SEMI further constrain membrane selection and system validation protocols for electronics-grade water. Stakeholders must weigh resin lifespan optimization against membrane replacement cycles as total cost of ownership becomes the decisive procurement criterion.
Market Dynamics
The EDI technology market pivots on tightening ionic purity mandates from semiconductor fabs and power utilities, where resin-membrane stack reliability now determines facility uptime economics rather than capital cost alone.
Growth Catalysts
- Semiconductor Water Purity Mandates:Taiwan and South Korea foundries require resistivity above 16 megohm-centimeter for sub-7nm chip production, positioning EDI as the non-regenerable final polishing stage in ultrapure water trains.
- EPA Maximum Achievable Control Technology:US power generators face boiler feedwater conductivity limits that legacy mixed-bed deionization cannot meet without hazardous chemical handling, accelerating EDI retrofit cycles.
- Fluoropolymer Thin-Film Casting Advances:Precision ion-selective membrane manufacturing is compressing stack footprint while maintaining throughput, enabling modular expansion in space-constrained electronics corridors.
Market Restraints
- Perfluorinated Membrane Supply Concentration:Ion exchange membrane production clusters with specialty fluoropolymer compounders, creating single-source vulnerability for high-purity stack assemblies.
- Resin Lifespan Degradation in High-Silica Feed:Colloidal silica fouling accelerates anion resin exhaustion in surface water-dependent facilities, forcing unplanned maintenance windows.
- Capacitive Deionization Energy Efficiency:CDI systems capture brackish water pre-treatment applications where 16 megohm-centimeter purity is unnecessary, narrowing EDI's addressable volume in lower-grade industrial segments.
Strategic Opportunities
- India Pharmaceutical Purification Gap:CDSCO sterile manufacturing guidelines for active pharmaceutical ingredients create demand for validated EDI skids in underpenetrated formulation corridors around Hyderabad and Ahmedabad.
- Green Hydrogen Electrolyzer Feedwater:PEM electrolyzer stacks require sub-1 ppb ionic contamination for catalyst longevity, opening adjacent demand from renewable hydrogen project developers.
- China Dual Carbon Wastewater Reuse:MEE circular economy mandates for zero liquid discharge factories position EDI as the polishing stage for reclaimed process water in chemical and textile clusters.
Industry Challenges
- SEMI F104 Certification Timelines:Semiconductor-grade water system validation requires 12-18 months of particle and TOC monitoring, compressing equipment vendor cash conversion cycles.
- Legacy Mixed-Bed Infrastructure Interoperability:Chemical regeneration facilities resist full EDI replacement due to sunk caustic handling infrastructure, forcing hybrid system complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrodeionization (EDI) Technology Market |
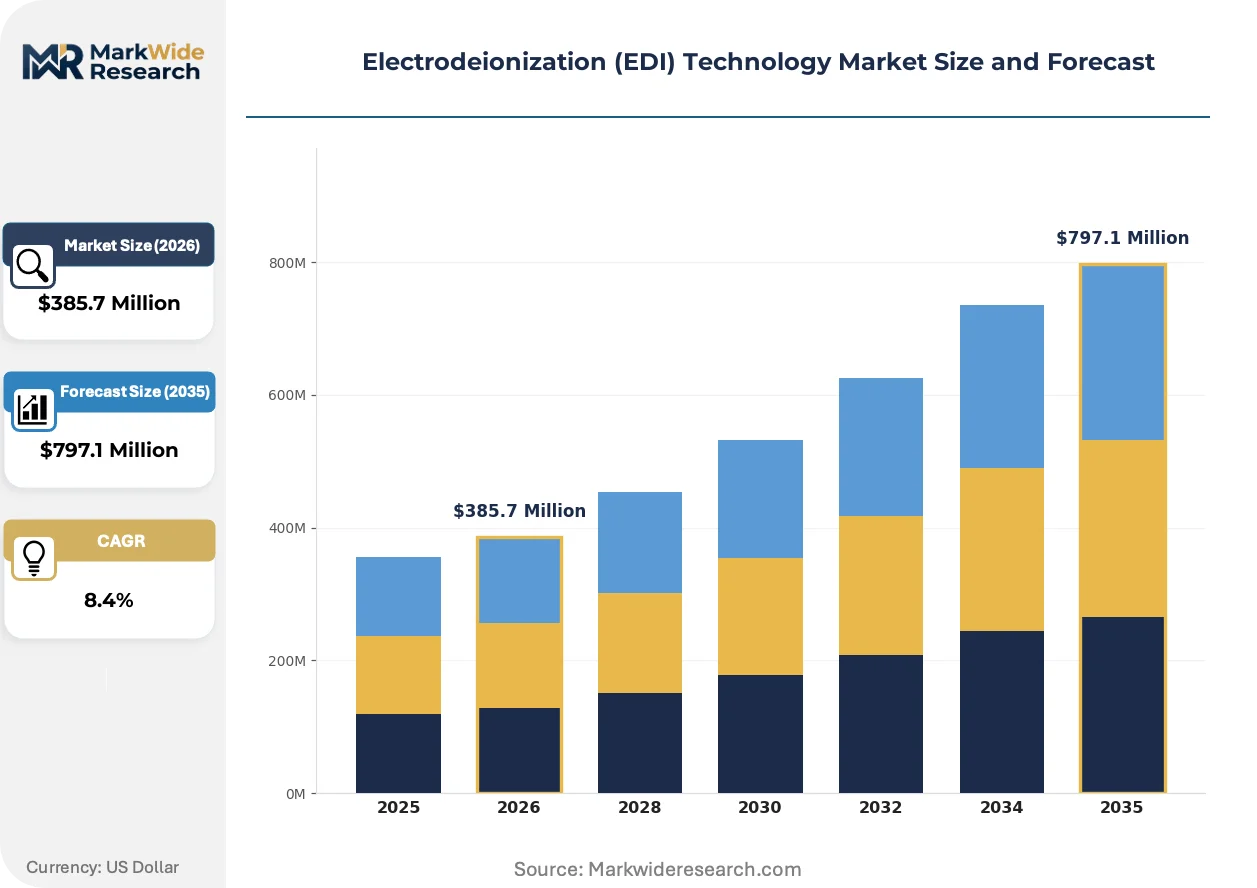
| Market Size in 2026 | $385.7 Million |
| Market Size in 2035 | $797.1 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Deionization, Electrodeionization Stack, Ion Exchange Membranes, Control Systems Application: Power Generation, Electronics Manufacturing, Pharmaceuticals, Water Treatment End User: Utilities, Semiconductor Industry, Chemical Plants, Laboratories Service Type: Consulting, System Integration, Maintenance, Technical Support |
| Companies Covered | Veolia, Evoqua Water Technologies, DuPont, SUEZ, Ovivo, Aquatech International, Kurita Water Industries, Lenntech, SnowPure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrodeionization (EDI) Technology Market Shifts & Advancements
Stack architecture evolution and resin chemistry refinement are compressing footprint requirements while expanding EDI's addressable purity range beyond traditional electronics applications.
High-flow stack architectures with optimized resin packing densities are decentralizing ultrapure water production from centralized utility buildings to point-of-use stations within cleanroom sub-fabs. Semiconductor facility designers in Hsinchu and Pyeongtaek are specifying distributed EDI skids to reduce loop length and contamination risk. This topology shift is compressing traditional central utility plant capital allocations while elevating modular equipment procurement.
China's GB 8978 wastewater discharge amendments are tightening total dissolved solids limits for industrial effluent, indirectly mandating higher upstream purification performance from chemical and textile processors. The MEE enforcement wave is accelerating membrane replacement cycles in facilities previously compliant under older thresholds. Electronics-grade water system vendors are adapting semiconductor-validated stack designs for these adjacent industrial verticals.
Power sector procurement patterns favor integrated service contracts bundling EDI stack maintenance with membrane replacement and resin regeneration logistics. US utilities under FERC reliability pressures are outsourcing water chemistry management to specialized operators rather than maintaining in-house expertise. This service model rotation is most visible in Texas and California independent power producer fleets where operational flexibility outweighs capital ownership preferences.
Electrodeionization (EDI) Technology Market Segmentation
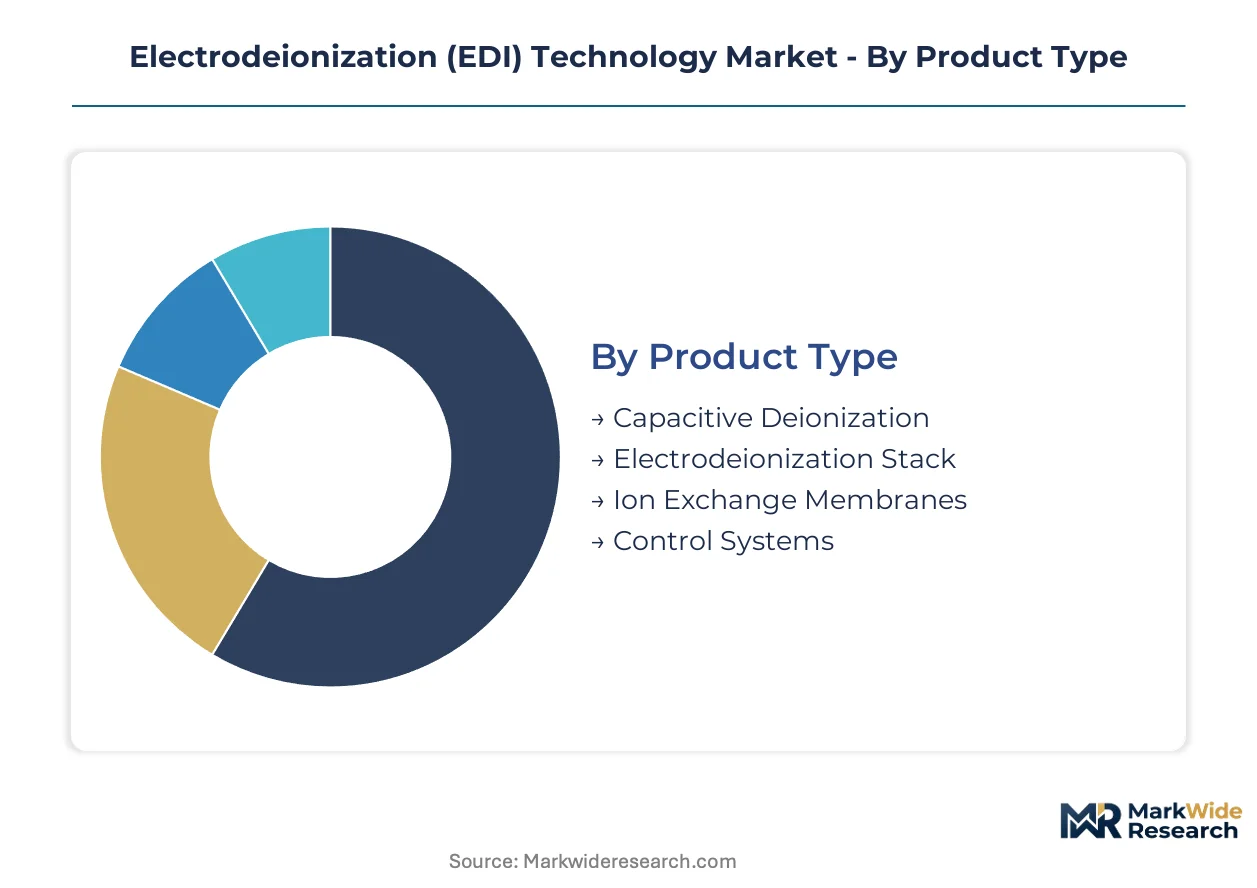
EDI technology segmentation reveals how resin-membrane stack configurations concentrate capital deployment while adjacent product categories capture differentiated margin pools. Understanding these divides exposes where fluoropolymer chemistry bottlenecks and modular scalability advantages reshape competitive positioning across ultrapure water value chains.
Product Type:
Supply concentration in ion-selective membrane manufacturing creates tiered competitive dynamics where fluoropolymer compounders command pricing power over stack assemblers.
- Electrodeionization Stack:Modular assemblies combine alternating cation and anion exchange membranes with resin beds in direct-current-driven configurations. Semiconductor fabs in Taiwan and South Korea specify these for sub-7nm chip production where resistivity must exceed 16 megohm-centimeter. Stack reliability now determines facility uptime economics rather than capital cost alone.
- Ion Exchange Membranes:Thin-film fluoropolymer castings with precision ion-selective functionality create supply bottlenecks where specialty chemistry and casting precision differentiate margin capture. DuPont anchors this segment with proprietary polymer formulations that constrain independent stack producer sourcing options.
- Capacitive Deionization:Energy-efficient electrosorption systems target brackish water pre-treatment where ultimate purity requirements remain below electronics-grade thresholds.
- Control Systems:Automated monitoring and DC power regulation modules enable remote diagnostics and predictive maintenance in distributed ultrapure water installations.
Today's leader: Electrodeionization Stack. Tomorrow's challenger: Ion Exchange Membranes.
Application:
Cost tier stratification separates capital-intensive electronics-grade installations from operational-expense-driven power sector retrofit cycles.
- Electronics Manufacturing:Taiwan and South Korea foundries deploy EDI as the non-regenerable final polishing stage in ultrapure water trains where sub-7nm lithography demands sub-ppb ionic contamination. Distributed skid topologies in Hsinchu and Pyeongtaek compress loop length and contamination risk.
- Power Generation:US utilities under FERC reliability pressures outsource water chemistry management through integrated service contracts bundling stack maintenance with membrane replacement logistics.
- Pharmaceuticals:CDSCO sterile manufacturing guidelines for active pharmaceutical ingredients drive validated EDI skid demand in underpenetrated Indian formulation corridors.
- Water Treatment:China's MEE circular economy mandates for zero liquid discharge factories position EDI polishing for reclaimed process water in chemical and textile clusters.
Electronics Manufacturing commands premium pricing. Power Generation offers volume scale.
End User:
Customer type diversity spans regulated utilities, specification-driven semiconductor procurement, and research-grade laboratory demand with divergent validation protocols.
- Semiconductor Industry:Foundry capacity additions in East Asian electronics corridors outpace other regions, with SEMI F104 certification timelines requiring 12-18 months of particle and TOC monitoring that compress vendor cash conversion cycles.
- Utilities:Texas and California independent power producer fleets favor operational flexibility over capital ownership, accelerating outsourced water chemistry management.
- Chemical Plants:China's GB 8978 wastewater discharge amendments tighten total dissolved solids limits, indirectly mandating higher upstream purification performance.
- Laboratories:Research and analytical facilities require validated ultrapure water systems with documented traceability for regulatory compliance.
Semiconductor Industry sets purity benchmarks. Utilities provide recurring revenue stability.
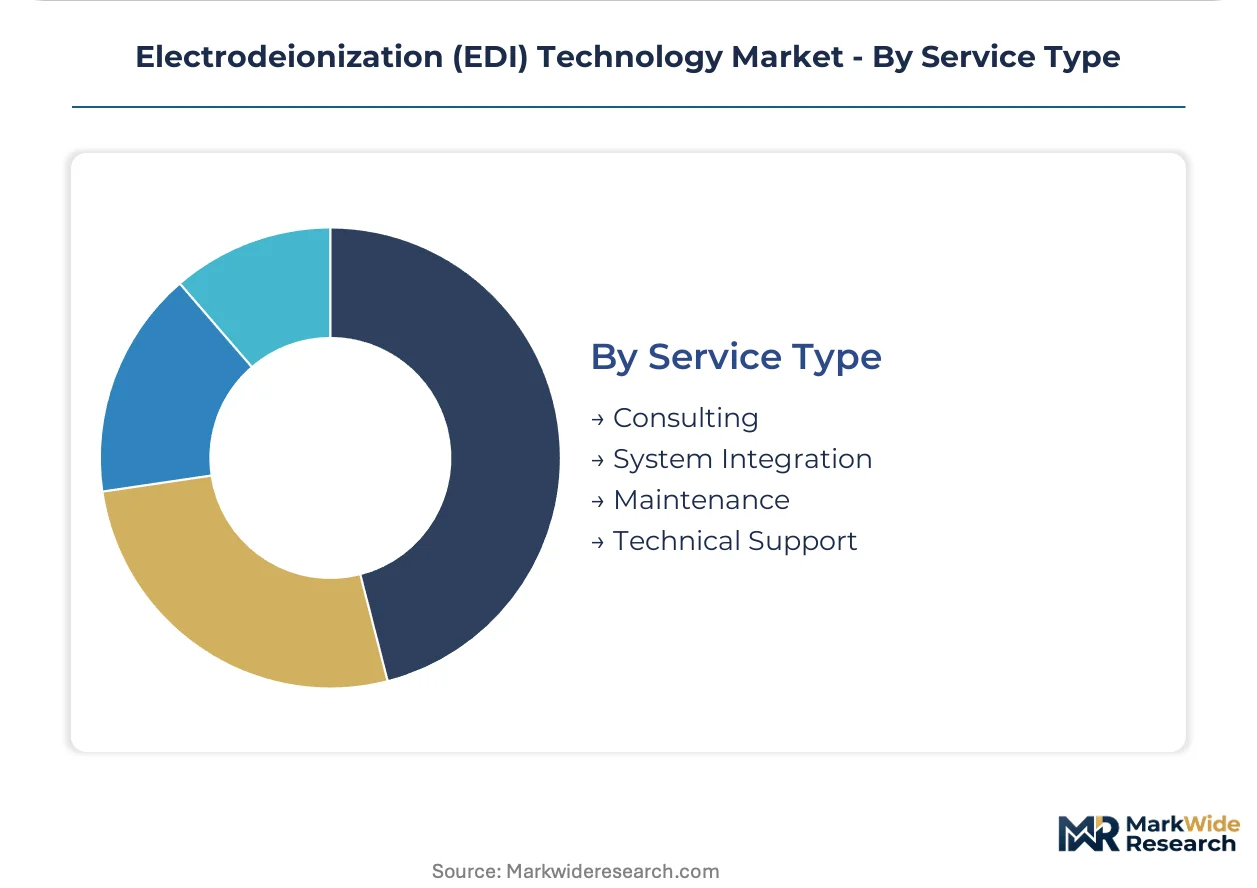
Service Type:
Margin accrual shifts downstream as power sector procurement patterns favor bundled service contracts over equipment-only transactions.
- System Integration:Turnkey design-build contracts for ultrapure water trains incorporate EDI as the final polishing stage with guaranteed performance specifications.
- Maintenance:Scheduled resin replacement and membrane cleaning protocols optimize total cost of ownership against unplanned downtime.
- Technical Support:Remote diagnostics and on-site troubleshooting reduce mean time to repair in continuous-production environments.
- Consulting:Feedwater analysis and process optimization studies identify colloidal silica fouling risks before resin degradation accelerates.
System Integration captures project margin. Maintenance secures recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are reshaping EDI equipment sourcing patterns, with semiconductor fabs migrating ultrapure water investments toward jurisdictions offering streamlined permitting and concentrated supplier ecosystems. Foundry operators weigh EPA enforcement intensity against China's MEE circular economy mandates when siting new capacity.
United States
Texas and California independent power producer fleets drive EDI retrofit demand as FERC reliability pressures force boiler feedwater conductivity compliance. The EPA's Maximum Achievable Control Technology standards accelerate chemical regeneration phaseouts. Austin and Dallas-Fort Worth utility clusters now specify integrated service contracts bundling stack maintenance with membrane replacement logistics.
China
Zero liquid discharge mandates from the MEE position EDI as the polishing stage for reclaimed process water in chemical and textile clusters. The country's dual carbon goals tighten wastewater discharge limits under GB 8978 amendments. Yangtze River Delta manufacturing corridors around Shanghai and Suzhou are upgrading membrane replacement cycles to meet revised total dissolved solids thresholds.
Taiwan
Hsinchu Science Park foundries deploy distributed EDI skids to compress ultrapure water loop length for sub-7nm chip production. SEMI F104 certification timelines require 12-18 months of particle monitoring that compress vendor cash conversion cycles. Taichung and Tainan fab expansions are scaling modular stack architectures for point-of-use purification stations.
South Korea
Pyeongtaek and Yongin semiconductor complexes specify EDI as the non-regenerable final polishing stage where resistivity must exceed 16 megohm-centimeter. The MFDS pharmaceutical water guidelines create adjacent demand for validated skids in biologics manufacturing. Busan-Ulsan industrial zones are adapting electronics-grade stack designs for chemical processor upgrades.
India
Hyderabad and Ahmedabad formulation corridors face CDSCO sterile manufacturing guidelines for active pharmaceutical ingredients that drive validated EDI skid procurement. The country's PLI scheme for specialty chemicals indirectly elevates upstream purification performance requirements. Gujarat's Dahej and Mundra industrial zones are specifying semiconductor-validated membrane configurations for API production.
Electrodeionization (EDI) Technology Market Competitive Landscape
North American membrane module producers anchor one tier; East Asian water treatment specialists hold integrated service capabilities. The vendor base stratifies across fluoropolymer chemistry suppliers, stack assemblers, and bundled service operators. Three archetypes dominate: integrated water service contractors, membrane chemistry compounders, and modular equipment fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure resin-membrane supply continuity.
Among France-based integrated operators, Veolia and SUEZ occupy positions exemplifying the service-contract archetype. DuPont anchors membrane chemistry supply with proprietary ion-selective polymer formulations that constrain independent stack producer sourcing options. Evoqua Water Technologies sits within the North American modular equipment tier, representing concentrated R&D investment in high-flow stack architectures.
| Leading Market Players |
|---|
| Veolia |
| Evoqua Water Technologies |
| DuPont |
| SUEZ |
| Ovivo |
| Aquatech International |
| Kurita Water Industries |
| Lenntech |
| SnowPure |
| Others |
Supply & Pricing Matrix
Fluoropolymer resin costs cascade through ion exchange membrane fabrication into tiered stack pricing, with perfluorinated chemistry concentration in North American and Japanese compounders creating margin compression for independent EDI assemblers sourcing thin-film castings.
Pricing Analysis
Distributor margins on ion exchange membranes compress final stack pricing by 15-25 points before OEM delivery. Three-tier pricing structure across semiconductor-validated, industrial-grade, and power-utility specifications reflects certification burden divergence. Cost compression in standard industrial tiers is intensifying because Chinese membrane entrants are undercutting legacy fluoropolymer suppliers. Power utilities exhibit highest price sensitivity due to FERC rate-case pressures, while semiconductor fabs accept premiums for SEMI F104 traceability.
Supply Chain Analysis
Specialized polymer chemist availability constrains membrane casting expansion in North Carolina and Texas manufacturing corridors. Supply concentrates with DuPont in the United States, AGC in Japan, and emerging Chinese fluoropolymer compounders. Raw material sourcing draws from perfluorinated monomer feedstocks, precision coating substrates, and high-purity ion exchange functionalization agents. Single-source vulnerability pervades sub-50-micron thin-film production. Distribution runs through direct OEM contracts for semiconductor fabs and regional water treatment distributors for power sector retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as semiconductor node shrinkage and power sector decarbonization create inexorable ultrapure water demand expansion with high customer switching costs.
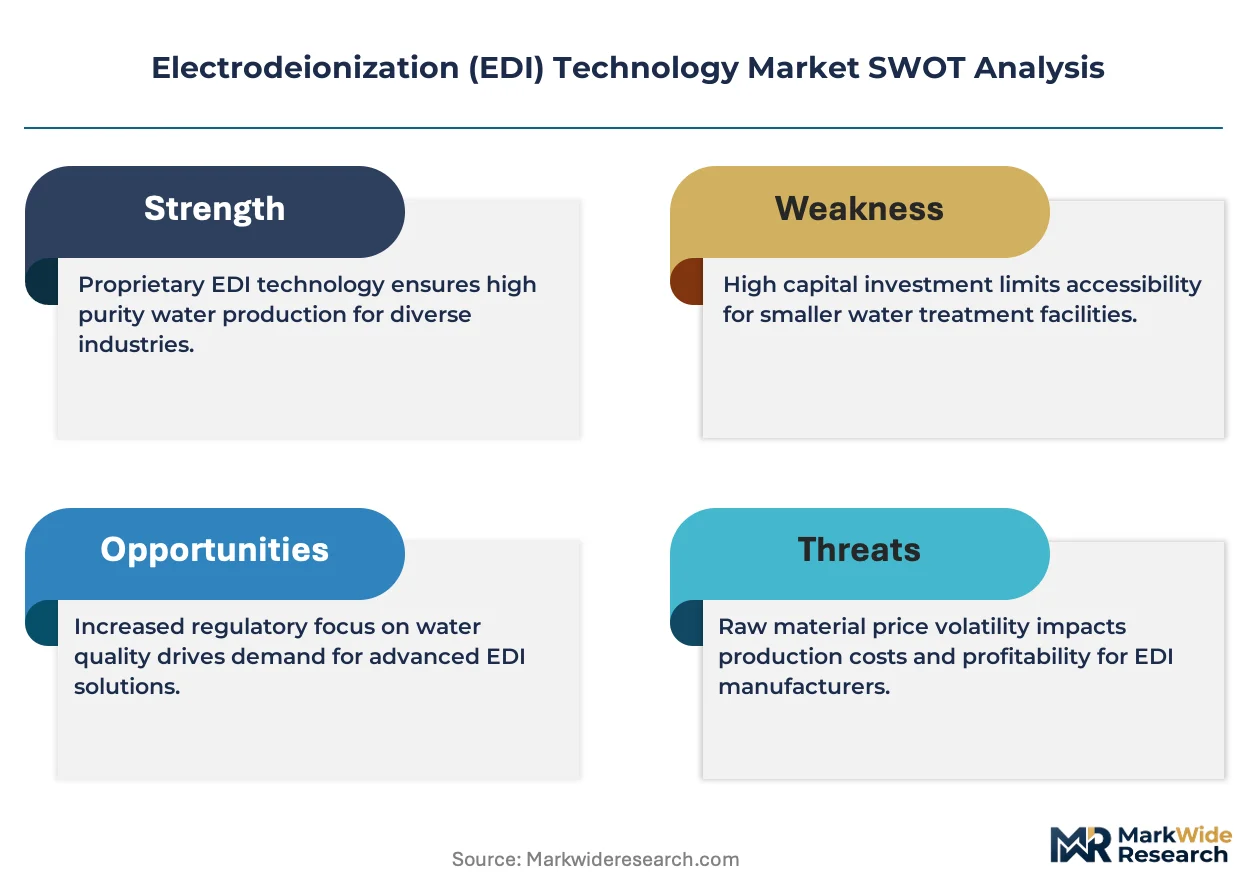
For Market Incumbents: Hedge membrane supply exposure through backward integration into fluoropolymer casting or long-term offtake agreements with AGC and Chemours. Defend service contract renewals by embedding predictive maintenance algorithms that raise switching costs for Texas and California IPP fleets facing FERC reliability mandates. For New Entrants and Emerging Players: Enter via validated EDI skid supply for Indian pharmaceutical corridors around Hyderabad, where CDSCO enforcement creates procurement urgency without entrenched incumbent relationships. Target green hydrogen electrolyzer developers requiring sub-1 ppb feedwater specifications, leveraging PEM stack OEM partnerships as channel anchor. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane chemistry scarcity meets fragmented stack assembly capacity. Position for 5-10 year holding periods around fluoropolymer compounders with captive resin formulations. Watch SEMI F104 certification timeline compression as inflection signal for semiconductor equipment vendor stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Casting | Captures membrane margin pools and secures supply continuity for stack assemblers. |
| SEMI F104 Certification Fast-Track Program | Compresses 12-18 month validation timelines to capture Taiwan and South Korea fab expansion windows. |
| Green Hydrogen Electrolyzer Partnership | Positions EDI skids for PEM feedwater demand from renewable hydrogen project developers. |
| India Pharmaceutical Corridor Expansion | Addresses CDSCO-mandated sterile water gaps in underpenetrated API manufacturing zones. |
| Integrated Service Contract Bundling | Locks in recurring revenue from FERC-pressured US power utilities outsourcing water chemistry management. |
Research Methodology
Multiple input streams — plant engineer interviews, procurement lead surveys, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary conversations with ultrapure water system designers, semiconductor fab facilities managers, power utility chemistry officers, and EDI stack maintenance supervisors informed operational parameters. Secondary validation drew from EPA MACT enforcement records, China's MEE GB 8978 amendment filings, SEMI technical standards, and FERC reliability compliance disclosures. Bottom-up unit economics and top-down sectoral spend patterns were triangulated to anchor projections.
Historical capacity deployment patterns were cross-referenced against panel input from equipment vendors and membrane suppliers to build the analytical framework. Segmentation modeling spanned product architecture, end-use industry, purity tier, and regional regulatory cluster across the analysis window. CAGRs were derived from slope consensus across input streams rather than single-source extrapolation. Forecast inputs incorporated foundry buildout timelines, power sector retrofit cycles, and pharmaceutical regulatory enforcement intensity.
Inputs from semiconductor capital expenditure disclosures and utility procurement databases were available through the study window; gaps in real-time resin degradation rate data introduce uncertainty bands around maintenance revenue projections. Forecasts reflect documented assumptions regarding EPA and MEE enforcement continuity. Material deviation in foundry construction delays or fluoropolymer supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market