
 United States Water Treatment Chemicals Market | 2026-2036
United States Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Water Treatment Chemicals Market Analytics
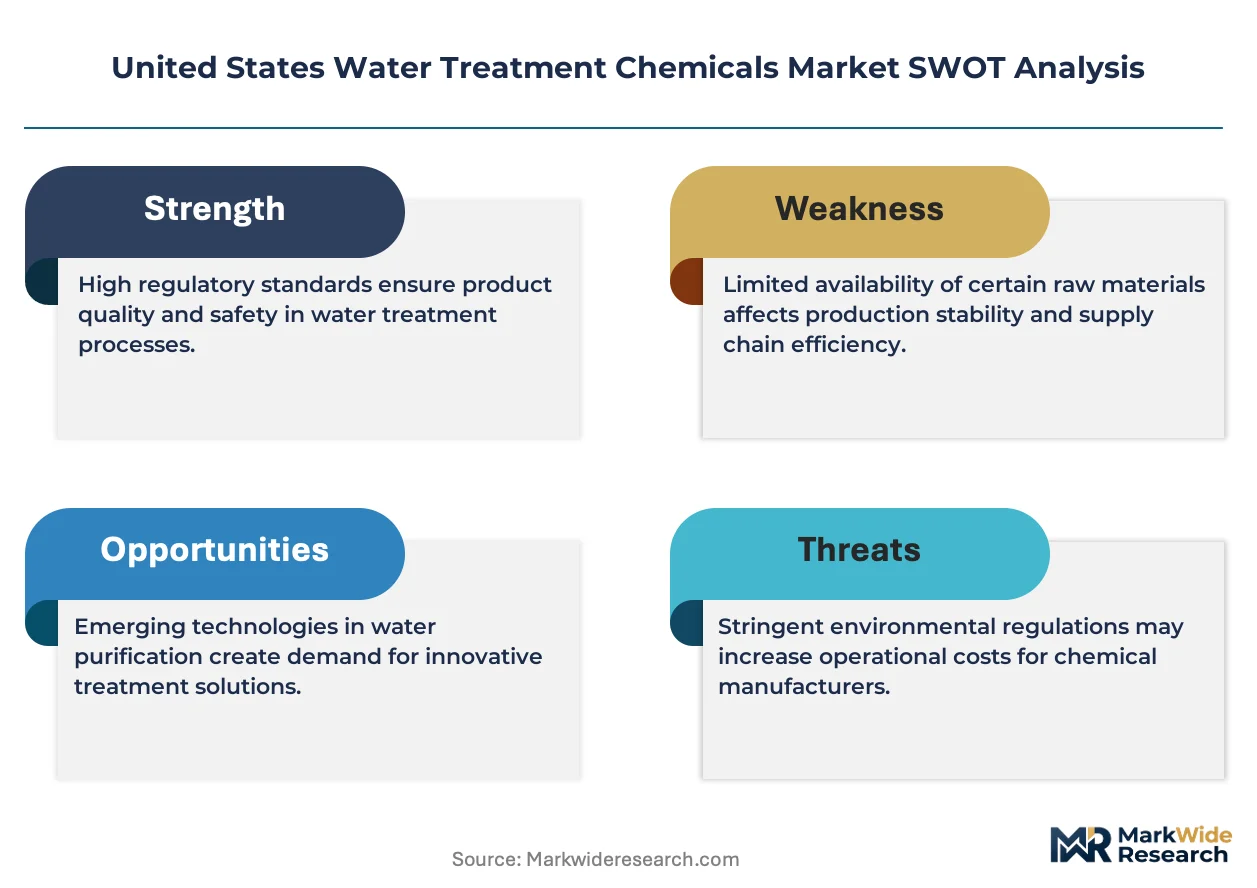
Advanced NSF/ANSI 60 certification tiers are rotating procurement specifications upward across municipal water systems. Ecolab leverages its on-site service model to anchor premium pricing in cooling water treatment. Solenis competes through specialized antiscalant formulations for reverse osmosis plants. Kemira sustains its position in coagulant supply through backward integration into aluminum sulfate production.
Water treatment chemicals encompass formulated additives including coagulants, flocculants, corrosion inhibitors, and biocides designed to remove contaminants, control microbial growth, and protect infrastructure in potable and process water systems. These formulations typically operate within specified pH ranges and dosing concentrations measured in parts per million to achieve regulatory compliance and operational efficiency. Biocides and corrosion inhibitors command the strongest margin pools due to technical complexity and performance-critical applications in power generation and chemical processing. Coagulants occupy the largest volume position driven by universal deployment in drinking water and wastewater clarification. On-site treatment delivery modes are gaining traction among industrial end users seeking to reduce chemical handling risks and transportation costs.
EPA Safe Drinking Water Act amendments and OSHA Process Safety Management standards shape product registration, handling protocols, and facility compliance investments across the value chain. NSF/ANSI 60 certification requirements filter market access for drinking water additives, creating qualification barriers for unverified suppliers. Stakeholders must monitor emerging EPA limits on per- and polyfluoroalkyl substances and assess reformulation exposure across fluorinated biocide and antiscalant portfolios.
Market Dynamics
EPA Stage 2 Disinfectants and Disinfection Byproducts Rule compliance deadlines are forcing municipal systems to accelerate advanced oxidation process deployments. This regulatory pressure concentrates procurement around certified suppliers capable of meeting tightened contaminant limits.
Growth Catalysts
- Advanced Oxidation Process Mandates:EPA Stage 2 DBP Rule deadlines in the Great Lakes region are expanding AOP capacity investments. Municipalities require specialized oxidant formulations to meet bromate and haloacetic acid limits.
- Membrane Bioreactor Retrofits:Texas and California wastewater facilities are concentrating biocide and antiscalant demand around large-volume framework contracts. These retrofits create recurring chemical consumption tied to membrane performance guarantees.
- NSF/ANSI 60 Tier Upgrades:Advanced certification tiers are rotating procurement specifications upward across municipal water systems. Higher-tier products command specification lock-in for multi-year supply agreements.
Market Restraints
- Aluminum Sulfate Supply Concentration:Coagulant production depends on captive bauxite processing and sulfuric acid supply chains concentrated in Gulf Coast chemical corridors. Input cost volatility transmits directly to municipal bid pricing.
- Fluorinated Compound Regulatory Exposure:Emerging EPA limits on per- and polyfluoroalkyl substances threaten reformulation requirements across fluorinated biocide and antiscalant portfolios. Suppliers face portfolio stranded-asset risk.
- PFAS Analytical Detection Limits:Method 533 and Method 537.1 detection thresholds at parts-per-trillion levels are disqualifying legacy chemistries from approved product lists before replacement formulations achieve NSF/ANSI 60 certification.
Strategic Opportunities
- On-Site Generation Systems:Electrochlorination and ozone generation equipment at industrial sites reduces bulk hypochlorite transportation and storage liability. Chemical suppliers can anchor recurring revenue through equipment-service bundling.
- Cooling Water Treatment Services:Power generation and petrochemical facilities are outsourcing chemical feed control and monitoring to specialty service providers. Performance-based contracts align supplier incentives with water reuse targets.
- Reverse Osmosis Antiscalant Specialization:High-recovery desalination and produced water treatment applications require polymer formulations tailored to specific silica and sulfate chemistries. Technical differentiation protects margin pools.
Industry Challenges
- NSF/ANSI 60 Certification Timelines:Third-party toxicological review and extraction testing cycles extend 18-24 months for novel chemistries. Product development pipelines misalign with regulatory deadline urgency.
- Legacy SCADA Integration:Automated chemical dosing systems require interoperability with decades-old municipal control infrastructure. Retrofit complexity delays smart monitoring adoption.
- Specialized Field Technician Scarcity:On-site service models depend on certified water treatment operators with cross-training in automation and analytical instrumentation. Talent gaps constrain service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Water Treatment Chemicals Market |
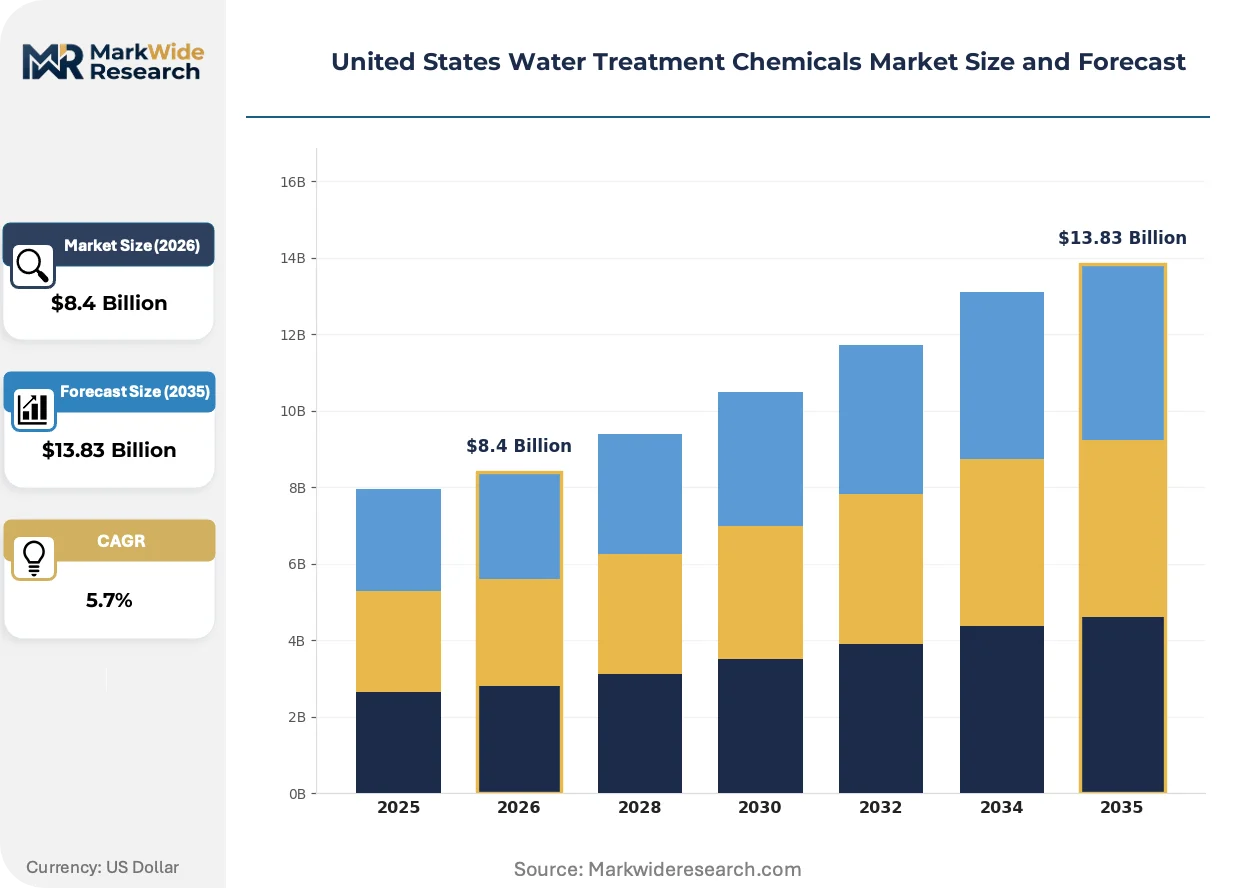
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Corrosion Inhibitors, Biocides Application: Drinking Water Treatment, Wastewater Treatment, Industrial Water Treatment, Cooling Water Treatment End User: Municipalities, Power Plants, Manufacturing, Chemical Plants Delivery Mode: Bulk Supply, Liquid Drums, Bags, On-site Treatment |
| Companies Covered | Ecolab, Solenis, Kemira, Veolia, BASF, ChemTreat, Kurita, SNF, Dow, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Water Treatment Chemicals Market Evolving Landscape
Electrochemical generation technologies and predictive dosing algorithms are compressing traditional bulk chemical distribution models. Regulatory detection limits continue tightening, forcing continuous formulation innovation.
Electrochlorination systems producing sodium hypochlorite on-site from salt and electricity are displacing bulk delivered hypochlorite and calcium hypochlorite tablets in large municipal applications. Arizona and Nevada water authorities have adopted this technology for remote well sites. The shift is displacing tanker truck logistics networks and quarterly delivery scheduling with continuous distributed production.
EPA's pending PFAS National Primary Drinking Water Regulation establishes maximum contaminant levels for six per- and polyfluoroalkyl substances. Water systems must install treatment or switch source water by compliance deadlines. Activated carbon and ion exchange resin demand is accelerating in Michigan, North Carolina, and Colorado contamination hotspots.
Industrial buyers are consolidating chemical procurement through integrated water management contracts. Petrochemical complexes in Texas and Louisiana now specify single-source accountability for treatment chemicals, monitoring equipment, and regulatory reporting. This bundling is displacing multi-vendor purchasing arrangements and spot-buying patterns.
United States Water Treatment Chemicals Market Segmentation
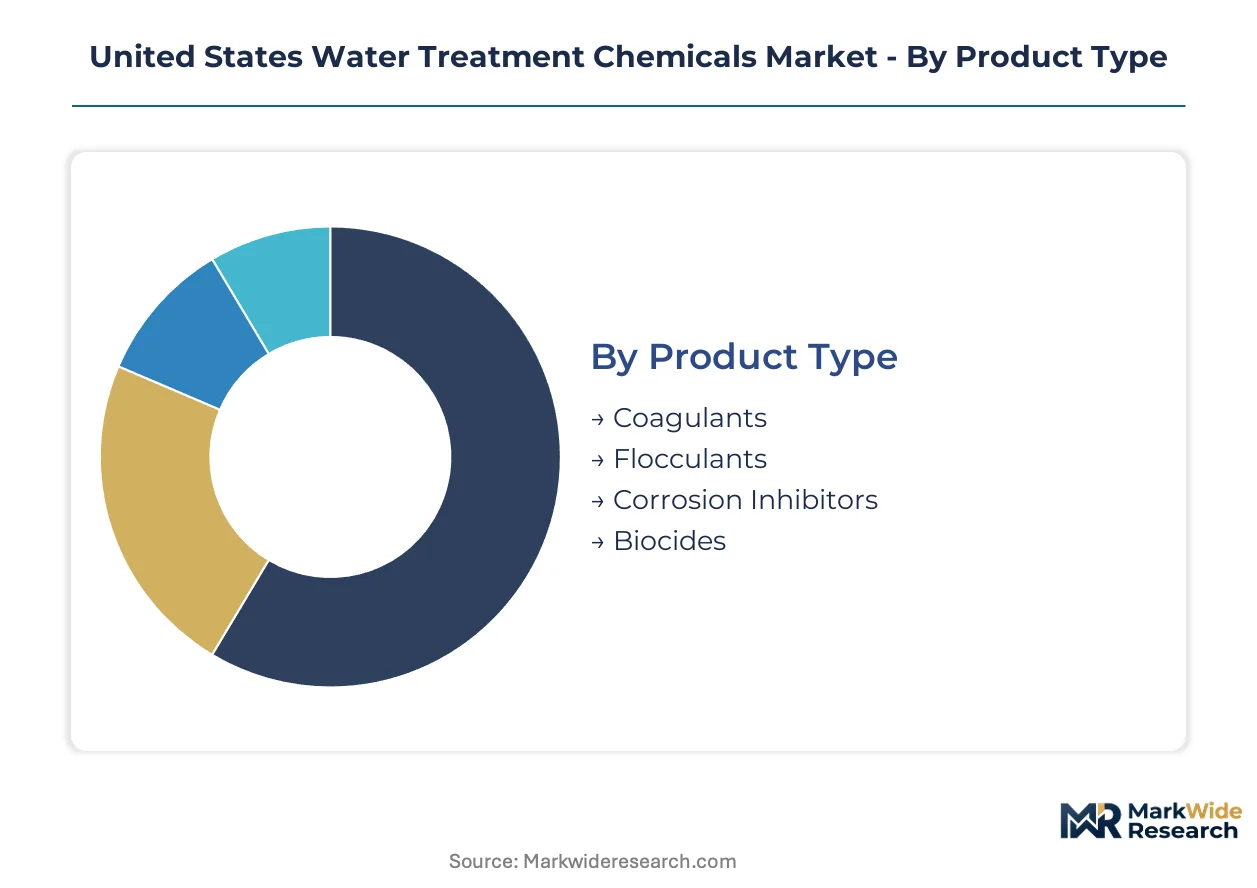
Substitution dynamics vary sharply across the United States Water Treatment Chemicals Market. Electrochemical generation and membrane technologies are displacing bulk chemical consumption in select segments while reinforcing demand concentration in others.
Product Type:
Biocides face the strongest substitution pressure from on-site electrochlorination systems, while coagulants remain insulated due to raw material integration barriers.
- Biocides:Oxidizing and non-oxidizing formulations control microbial growth in cooling towers and membrane systems. Power plants in Texas and Louisiana drive procurement concentration around performance guarantees for Legionella prevention.
- Coagulants:Aluminum sulfate and ferric chloride formulations remove suspended solids through charge neutralization. Municipalities across the Great Lakes region anchor demand as EPA Stage 2 DBP Rule compliance tightens clarification requirements.
- Corrosion Inhibitors:Phosphonate and polymer-based chemistries protect metal infrastructure in recirculating systems.
- Flocculants:Polyacrylamide polymers aggregate destabilized particles for sedimentation or flotation removal.
Coagulants anchor the volume base while biocides gain share at the steepest rate.
Application:
Margin concentration follows technical complexity gradients, with cooling water treatment commanding premium pricing against commoditized drinking water applications.
- Cooling Water Treatment:Scale inhibition, corrosion control, and microbial management in recirculating systems. Petrochemical complexes along the Gulf Coast outsource integrated chemical feed control to specialty service providers under performance contracts.
- Industrial Water Treatment:Process water conditioning for manufacturing and chemical production. California semiconductor fabs drive ultrapure water specification intensity for antiscalant and ion exchange resin demand.
- Drinking Water Treatment:Coagulation, disinfection, and contaminant removal for potable supply.
- Wastewater Treatment:Clarification, nutrient removal, and effluent polishing for discharge compliance.
Drinking water treatment anchors the volume base while cooling water treatment gains share at the steepest rate.
End User:
Procurement consolidation patterns diverge sharply between municipal framework contracts and industrial integrated service agreements.
- Power Plants:Cooling tower chemistry and boiler water treatment for thermal generation facilities. Arizona and Nevada utilities are adopting electrochlorination for remote well sites, displacing bulk hypochlorite logistics.
- Municipalities:Drinking water and wastewater treatment for public systems. Michigan, North Carolina, and Colorado contamination hotspots are accelerating activated carbon and ion exchange resin demand for PFAS removal.
- Chemical Plants:Process water conditioning and effluent treatment for specialty chemical production.
- Manufacturing:General industrial water treatment across diverse production facilities.
Municipalities anchor the volume base while power plants gain share at the steepest rate.
Delivery Mode:
Supply chain configuration determines cost structure differentiation, with bulk supply facing margin compression against value-added on-site service models.
- On-site Treatment:Electrochlorination and ozone generation equipment producing oxidants at point of use. Ecolab leverages this model to anchor premium pricing through equipment-service bundling and continuous monitoring.
- Bulk Supply:Tanker truck and railcar delivery of concentrated liquid chemicals. Gulf Coast bauxite processing corridors concentrate aluminum sulfate production, transmitting input cost volatility directly to municipal bid pricing.
- Liquid Drums:Intermediate-volume packaging for industrial maintenance and small municipal systems.
- Bags:Dry chemical packaging for flocculants and powdered coagulants in remote or low-volume applications.
Bulk supply anchors the volume base while on-site treatment gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast chemical corridors concentrate aluminum sulfate production through captive bauxite processing and sulfuric acid supply chains. This geographic concentration transmits input cost volatility directly into municipal bid pricing across the country.
Texas
Petrochemical complexes along the Houston Ship Channel outsource integrated chemical feed control to specialty service providers under performance contracts. EPA Stage 2 DBP Rule compliance pressures concentrate procurement around certified suppliers capable of meeting tightened contaminant limits. Membrane bioreactor retrofits in Dallas-Fort Worth and San Antonio wastewater facilities drive recurring biocide and antiscalant consumption.
California
Semiconductor fabs in Silicon Valley and San Diego drive ultrapure water specification intensity for antiscalant and ion exchange resin demand. The State Water Resources Control Board enforces stringent discharge limits that accelerate advanced oxidation process deployments. Los Angeles and San Francisco Bay Area municipalities rotate procurement specifications upward around advanced NSF/ANSI 60 certification tiers.
Michigan
Great Lakes region municipalities expand advanced oxidation process capacity to meet EPA Stage 2 Disinfectants and Disinfection Byproducts Rule compliance. PFAS contamination hotspots around Grand Rapids and Detroit accelerate activated carbon and ion exchange resin demand. The Michigan Department of Environment, Great Lakes, and Energy enforces analytical detection thresholds that disqualify legacy chemistries from approved product lists.
Arizona
Water authorities adopt electrochlorination systems for remote well sites, displacing bulk hypochlorite logistics networks and quarterly delivery scheduling. Arizona Department of Environmental Quality regulations concentrate procurement around on-site generation equipment capable of continuous distributed production. Phoenix and Tucson utilities anchor demand for cooling water treatment chemicals in power generation applications.
North Carolina
Research Triangle Park chemical processing facilities drive corrosion inhibitor and scale control formulation demand. Cape Fear River watershed PFAS contamination accelerates treatment infrastructure investment under EPA pending National Primary Drinking Water Regulation deadlines. Charlotte and Raleigh municipal systems install activated carbon and ion exchange capacity to meet compliance timelines.
United States Water Treatment Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States Water Treatment Chemicals Market. Specialty service providers anchor premium pricing through equipment-service bundling and continuous monitoring capabilities, while bulk chemical suppliers compete on input cost integration and logistics scale. Three archetypes dominate: integrated water management contractors, backward-integrated coagulant producers, and focused antiscalant formulators. Competitive moves concentrate on strategic partnerships for on-site generation equipment deployment and portfolio diversification away from fluorinated compound exposure.
Among North American-headquartered operators, Ecolab exemplifies the integrated service archetype through equipment-service bundling models. Solenis and Kemira occupy positions as specialty formulation providers, with Kemira representing backward-integrated coagulant supply through in-house aluminum sulfate production. These three anchors demonstrate how competitive positioning splits between service-intensive and manufacturing-intensive value capture models.
| Leading Market Players |
|---|
| Ecolab |
| Solenis |
| Kemira |
| Veolia |
| BASF |
| ChemTreat |
| Kurita |
| SNF |
| Dow |
| Others |
Value Network & Pricing Analysis
Electrochlorination system adoption across Arizona and Nevada water authorities simultaneously compresses bulk hypochlorite logistics networks and redistributes pricing power toward equipment-service bundling providers. This substitution dynamic severs traditional tanker truck scheduling economics while anchoring premium capture at the point of distributed production.
Pricing Analysis
EPA Stage 2 Disinfectants and Disinfection Byproducts Rule dictates the pricing tier structure across municipal procurement frameworks. Three-tier pricing stratifies across NSF/ANSI 60 advanced certification, standard compliance, and economy grades. Certification tier and volume scale anchor price differentiation. Cost compression in economy-grade coagulants is intensifying because Gulf Coast bauxite processing transmits sulfuric acid volatility directly into municipal bid pricing. Industrial integrated service agreements show lowest price sensitivity while small municipal systems bid on specification compliance alone.
Supply Chain Analysis
Gulf Coast chemical corridors anchor aluminum sulfate production through captive bauxite processing and sulfuric acid supply chains. Raw material sourcing draws from Gulf Coast petrochemical infrastructure, domestic bauxite refining, and imported alumina feedstocks. Single-source vulnerability concentrates in sulfuric acid supply corridors exposed to hurricane disruption. Distribution runs through tanker truck and railcar networks for bulk liquids, with electrochlorination equipment bypassing traditional chemical logistics entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as EPA PFAS National Primary Drinking Water Regulation deadlines force infrastructure replacement cycles across municipal systems. Capital deployment timing favors positions aligned with compliance-driven procurement windows.
For Market Incumbents: Consolidate backward integration into aluminum sulfate production to defend against Gulf Coast input cost volatility. Lock multi-year framework contracts with Great Lakes municipalities facing EPA Stage 2 DBP Rule deadlines. Certification investment in advanced NSF/ANSI 60 tiers creates specification lock-in against commodity competitors. For New Entrants and Emerging Players: Anchor in electrochlorination equipment-service bundling for remote well sites across Arizona and Nevada. White-space concentration sits with PFAS treatment media deployment in Michigan and North Carolina contamination hotspots. Go-to-market leverage rests on rapid NSF/ANSI 60 certification pathways for novel non-fluorinated antiscalant formulations. For Investors and Strategic Acquirers: EPA's pending PFAS National Primary Drinking Water Regulation reshapes the acquisition landscape toward treatment media specialists and on-site generation equipment providers. Five-to-ten-year viability favors targets with regulatory compliance technology rather than commodity chemical exposure. Watch EPA Method 533 and Method 537.1 detection threshold enforcement as the signal for portfolio stranded-asset risk in fluorinated chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sulfate | Gulf Coast captive bauxite processing insulates Kemira against sulfuric acid price volatility. |
| NSF/ANSI 60 Advanced Tier Certification | Advanced certification locks Ecolab into multi-year municipal supply agreements. |
| Electrochlorination Equipment Bundling | On-site generation displaces bulk hypochlorite logistics for Arizona remote well sites. |
| PFAS Treatment Media Deployment | Activated carbon and ion exchange demand accelerates in Michigan contamination hotspots. |
| Non-Fluorinated Antiscalant Development | Novel polymer formulations avoid EPA stranded-asset risk in reverse osmosis applications. |
Research Methodology
A spread of perspectives from municipal water treatment plant managers, industrial procurement leads at petrochemical complexes, specialty chemical R&D directors, and distribution channel partners converged on the working assumptions. Secondary validation drew from EPA enforcement databases, SEC 10-K filings, American Chemistry Council reports, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and delivery mode segments.
Segmentation dimensions modeled include product chemistry class, end-use facility type, certification tier, and regional regulatory cluster. Value projections across the analysis window applied category-specific growth trajectories derived from historical procurement patterns and compliance deadline phasing. Forecast inputs incorporated membrane bioreactor retrofit timelines and PFAS treatment infrastructure deployment schedules.
Material uncertainties — EPA regulatory timeline acceleration, PFAS analytical method revisions, and electrochlorination technology cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about municipal capital budget continuity and industrial outsourcing propensity. Recalibration cycles align with material shifts in EPA enforcement priorities and detection limit announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Drinking Water Adsorbents Market