
 Asia-Pacific Membrane Water Treatment Chemicals Market | 2026-2036
Asia-Pacific Membrane Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Membrane Water Treatment Chemicals Market Outlook
Aftermarket chemical dosing and membrane preservation revenue is fragmenting as plant operators shift from bulk procurement to performance-based service contracts. Kurita Water Industries Ltd anchors its position through captive formulation labs in Japan and China that customize antiscalant blends for local feedwater chemistries. Dow competes by extending its polymer science expertise into fouling-resistant pretreatment chemistries aligned with reverse osmosis module warranties. Ecolab, Inc. differentiates through integrated digital monitoring platforms that tie chemical consumption directly to membrane flux recovery rates.
Membrane water treatment chemicals comprise functional additives—coagulants, flocculants, antiscalants, and disinfectants—engineered to protect polyamide and cellulose acetate membranes from scaling, biofouling, and oxidative degradation, typically dosed at 0.5–10 ppm depending on feedwater total dissolved solids and membrane pore classification. Their primary purpose is sustaining design flux rates and extending membrane replacement intervals in pressure-driven separation systems. Antiscalants command the deepest margin pools among product types because phosphonate and polyacrylate formulations require precise inhibition-index calibration against silica, calcium sulfate, and barium strontium saturation. Reverse osmosis dominates technology-linked chemical demand due to its prevalence in seawater desalination and boiler feed preparation, though ultrafiltration pretreatment chemicals are gaining traction as hybrid membrane trains reduce downstream fouling loads.
MEE discharge standards in China and BIS drinking water specifications in India compel formulators to phase out acutely toxic biocides and document biodegradability profiles under OECD testing protocols. Australia's TGA-aligned state water authorities enforce chemical registration for membrane contact in potable applications, creating compliance barriers for uncertified imports. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national chemical inventories to avoid reformulation costs that erode contract profitability.
Market Dynamics
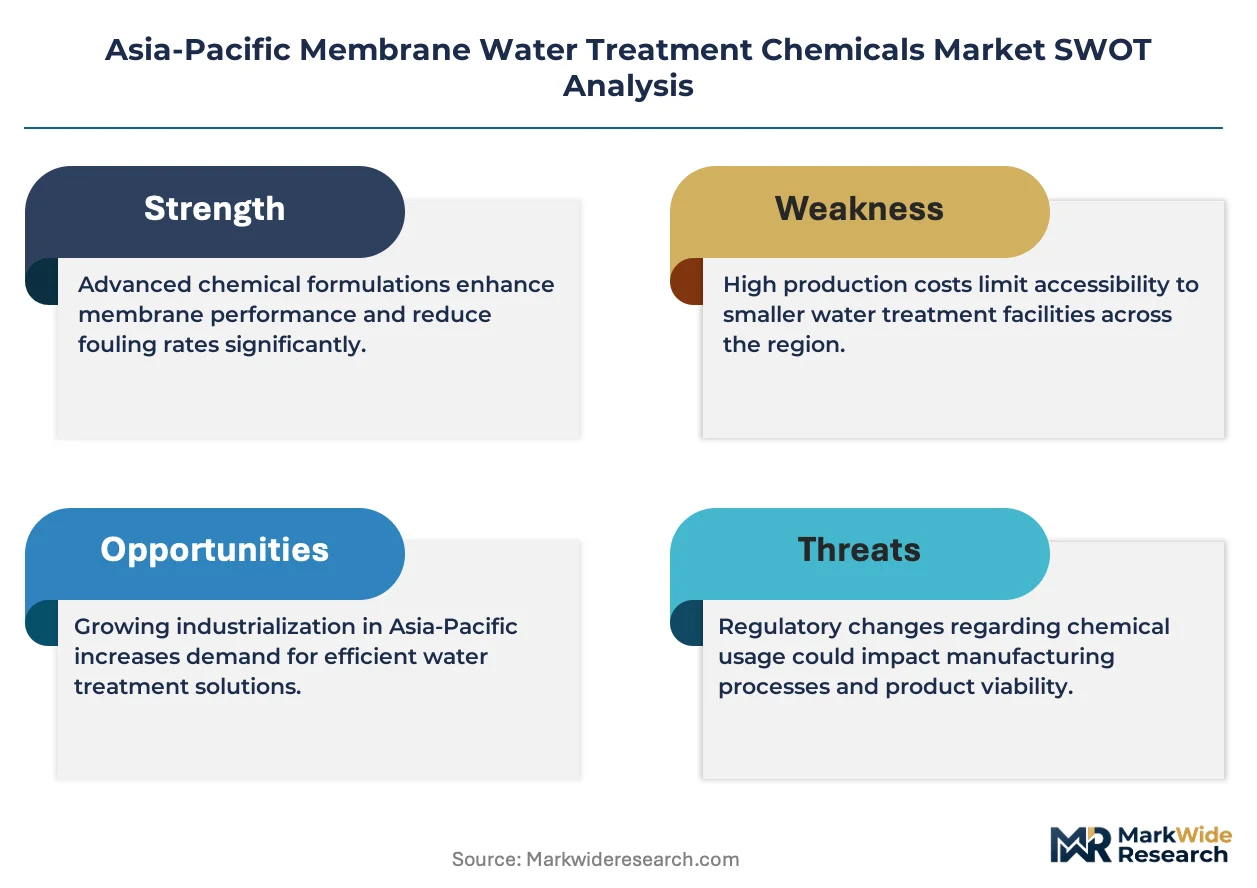
China's MEE discharge standards and dual carbon goals are forcing formulators to abandon phosphonate-heavy antiscalants in favor of biodegradable polymeric alternatives, restructuring procurement priorities across semiconductor fabs and municipal desalination plants.
Growth Catalysts
- Semiconductor cluster expansion:Eastern Chinese provinces are constructing membrane-intensive ultrapure water systems for advanced node fabrication, driving concentrated chemical demand from Shanghai to Hefei.
- MEE discharge mandates:Stricter effluent standards under China's Ministry of Ecology and Environment are accelerating substitution toward biodegradable antiscalants and low-phosphorus formulations.
- Seawater reverse osmosis buildout:Southeast Asian utilities in Vietnam and Indonesia are expanding membrane-based desalination capacity to address freshwater scarcity in coastal manufacturing zones.
Market Restraints
- Phosphonate supply concentration:Specialty phosphonate precursors for high-performance antiscalants concentrate among Japanese and German chemical suppliers, exposing formulators to freight and currency volatility.
- Biodegradability testing costs:OECD 301B and 306 protocols required for MEE compliance add six-to-twelve-month certification timelines that delay new product commercialization.
- Membrane warranty restrictions:Polyamide thin-film composite manufacturers impose approved-chemical lists that limit substitution flexibility and lock in incumbent formulations.
Strategic Opportunities
- India BIS drinking water alignment:India's Bureau of Indian Standards is tightening potable water specifications, creating first-mover advantage for certified biocide and disinfectant suppliers in membrane-based municipal systems.
- Hybrid membrane train integration:Ultrafiltration pretreatment chemicals are gaining traction as combined UF-RO configurations reduce downstream fouling loads and extend chemical dosing intervals.
- Performance-based service contracts:Plant operators across Australia and Singapore are abandoning bulk chemical procurement in favor of flux-guarantee agreements that tie supplier revenue to membrane recovery rates.
Industry Challenges
- Feedwater chemistry specialization:Antiscalant formulators must maintain captive laboratories in Japan, China, and Australia to calibrate inhibition indices against local silica, barium, and strontium saturation profiles.
- TGA-aligned registration fragmentation:Australia's Therapeutic Goods Administration and state water authorities enforce non-harmonized chemical registration requirements that multiply compliance costs for imported formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Membrane Water Treatment Chemicals Market |
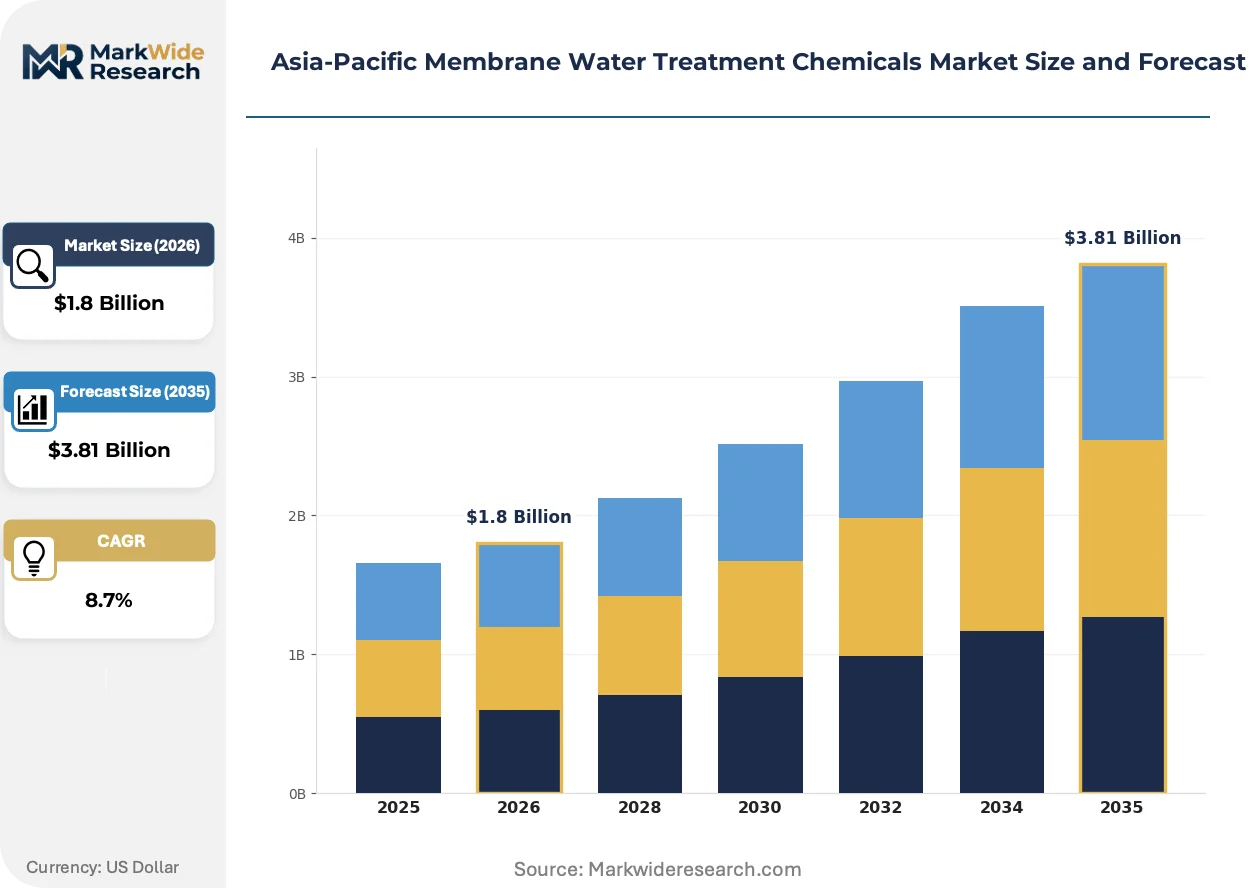
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Antiscalants, Disinfectants Application: Desalination, Wastewater Treatment, Industrial Processes, Drinking Water Treatment End User: Municipal, Industrial, Commercial, Residential Technology: Reverse Osmosis, Nanofiltration, Ultrafiltration, Microfiltration |
| Companies Covered | Kurita Water Industries Ltd, Ecolab, Inc., Dow, Toray Industries, Inc., Kemira Oyj, Suez, Solenis, Nalco Water, Veolia Water Solutions & Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Membrane Water Treatment Chemicals Market Strategic Shifts
Digital dosing platforms and predictive membrane health analytics are compressing the traditional separation between chemical supply and system operation, redefining how antiscalant and biocide vendors capture value.
Polymer-derived fouling-resistant pretreatment chemistries are advancing rapid adoption among power plant operators in Japan and South Korea who face strict thermal discharge limits. These formulations reduce organic fouling rates on reverse osmosis membranes by half compared to conventional coagulants. The technology is virtualizing the boundary between chemical treatment and membrane module warranties, as Dow and regional suppliers bundle dosing protocols directly into OEM service agreements.
REACH-aligned biodegradability documentation is penetrating Asia-Pacific procurement specifications even where EU jurisdiction does not apply. MEE in China and Australia's state water authorities now reference OECD 301 testing protocols for membrane-contact chemicals in potable applications. Formulators without existing registration dossiers face exclusion from tenders in Shanghai, Guangdong, and New South Wales as authorities harmonize toward EU chemical safety benchmarks.
Plant engineering divisions are consolidating chemical vendor relationships from three-to-five suppliers per site to single-source performance contracts with integrated monitoring platforms. Ecolab and Kurita are displacing smaller regional blenders in Singapore and Taiwan by guaranteeing membrane flux recovery rates through sensor-driven dosing optimization. This consolidation is most visible in semiconductor fabs where ultrapure water system uptime directly ties to wafer yield economics.
Asia-Pacific Membrane Water Treatment Chemicals Market Segmentation
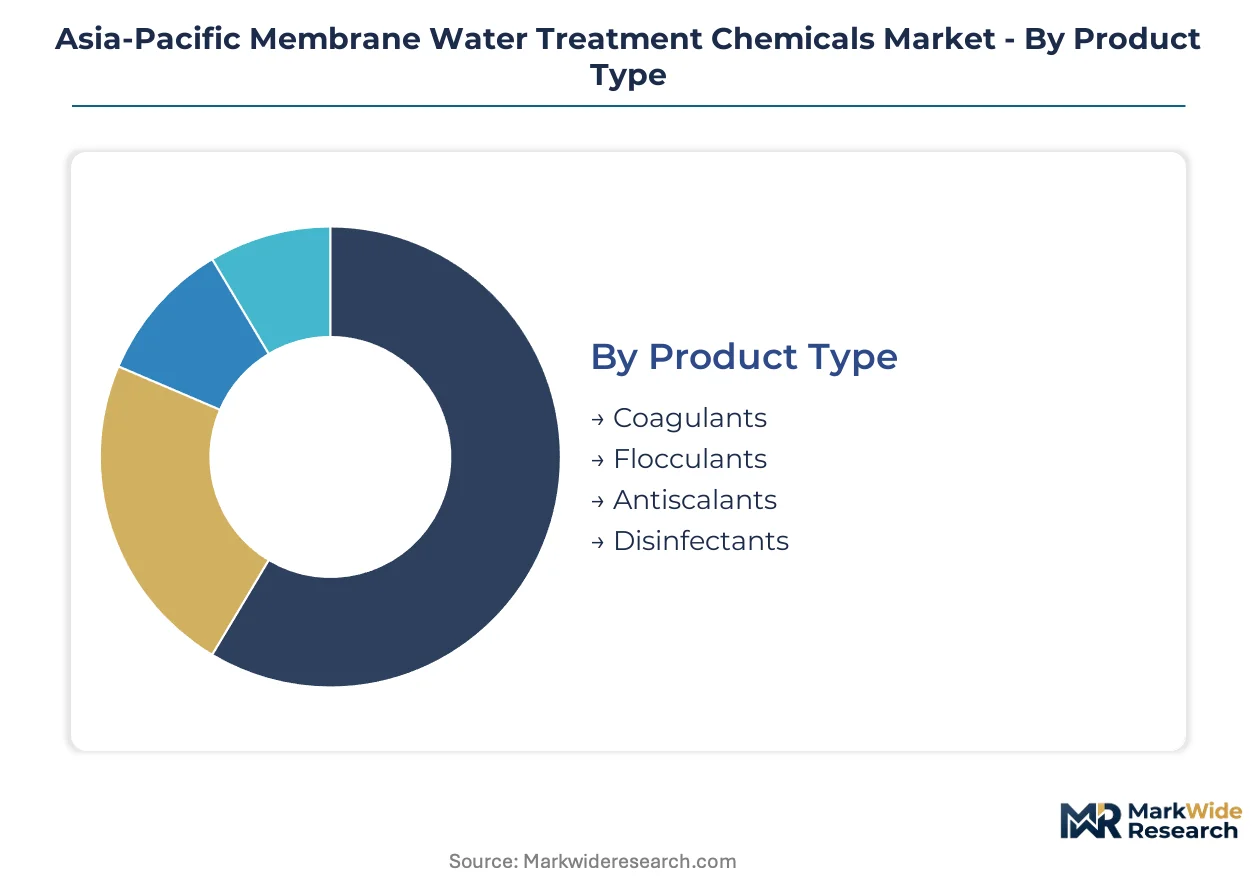
Membrane water treatment chemicals exhibit divergent margin structures and technical specifications across product chemistry, end-use intensity, and membrane pore classification. Procurement patterns in this market fragment sharply between bulk municipal tenders and precision-dosed industrial contracts.
Product Type:
Cost tier determines procurement sophistication, with premium formulations commanding extended technical service and calibration support.
- Antiscalants:Phosphonate and polyacrylate formulations inhibit silica, calcium sulfate, and barium strontium precipitation on polyamide membranes. Semiconductor fabs in Shanghai and Hefei drive concentrated demand for precision-calibrated inhibition indices under MEE discharge mandates.
- Coagulants:Aluminum and iron-based chemistries neutralize colloidal charge ahead of membrane trains. Coastal desalination plants in Vietnam and Indonesia prioritize rapid-settling variants to protect downstream reverse osmosis modules from organic fouling.
- Flocculants:High-molecular-weight polymers aggregate destabilized particles into settleable flocs. Municipal utilities deploy cationic and anionic grades based on raw water turbidity profiles.
- Disinfectants:Chlorine, chlorine dioxide, and non-oxidizing biocides control biofilm formation on membrane surfaces. Australia's TGA-aligned state authorities enforce registration requirements that filter uncertified imports from potable applications.
Antiscalants hold installed capacity. Disinfectants are rotating up the share rankings.
Application:
Application intensity correlates with membrane replacement economics and chemical dosing precision requirements.
- Industrial Processes:Boiler feed preparation and cooling tower blowdown recovery in power plants and semiconductor fabrication demand ultrapure water systems with sub-ppb contaminant specifications. Eastern Chinese provinces anchor this segment through advanced node chip manufacturing expansion.
- Desalination:Seawater reverse osmosis facilities dose antiscalants at 2–5 ppm to suppress gypsum and silica scaling on high-rejection membranes. Southeast Asian utilities in coastal manufacturing zones are expanding membrane-based capacity to address freshwater scarcity.
- Wastewater Treatment:Membrane bioreactors and tertiary filtration systems deploy coagulants and disinfectants to meet reuse standards. China's MEE effluent mandates are accelerating biodegradable formulation substitution.
- Drinking Water Treatment:Municipal ultrafiltration and nanofiltration plants prioritize certified biocides under BIS specifications in India and OECD-aligned protocols in Australia.
Industrial processes command the steepest expansion trajectory. Desalination maintains baseline volume.
End User:
Customer type shapes contract structure, with performance-based agreements displacing bulk procurement among sophisticated operators.
- Industrial:Semiconductor fabs, power plants, and pharmaceutical manufacturers specify chemical formulations tied to membrane OEM warranty lists. Singapore and Taiwan facilities lead adoption of sensor-driven dosing optimization.
- Municipal:Utilities in Australia, Japan, and South Korea consolidate vendor relationships toward single-source flux-guarantee contracts.
- Commercial:Hotels, hospitals, and data centers deploy packaged membrane systems with standardized chemical maintenance protocols.
- Residential:Point-of-use reverse osmosis units drive demand for pretreatment cartridges and membrane preservation chemistries in urban China and India.
Industrial end users anchor supplier margins. Municipal procurement is consolidating fastest.
Technology:
Membrane pore classification dictates chemical compatibility requirements and fouling mechanism profiles.
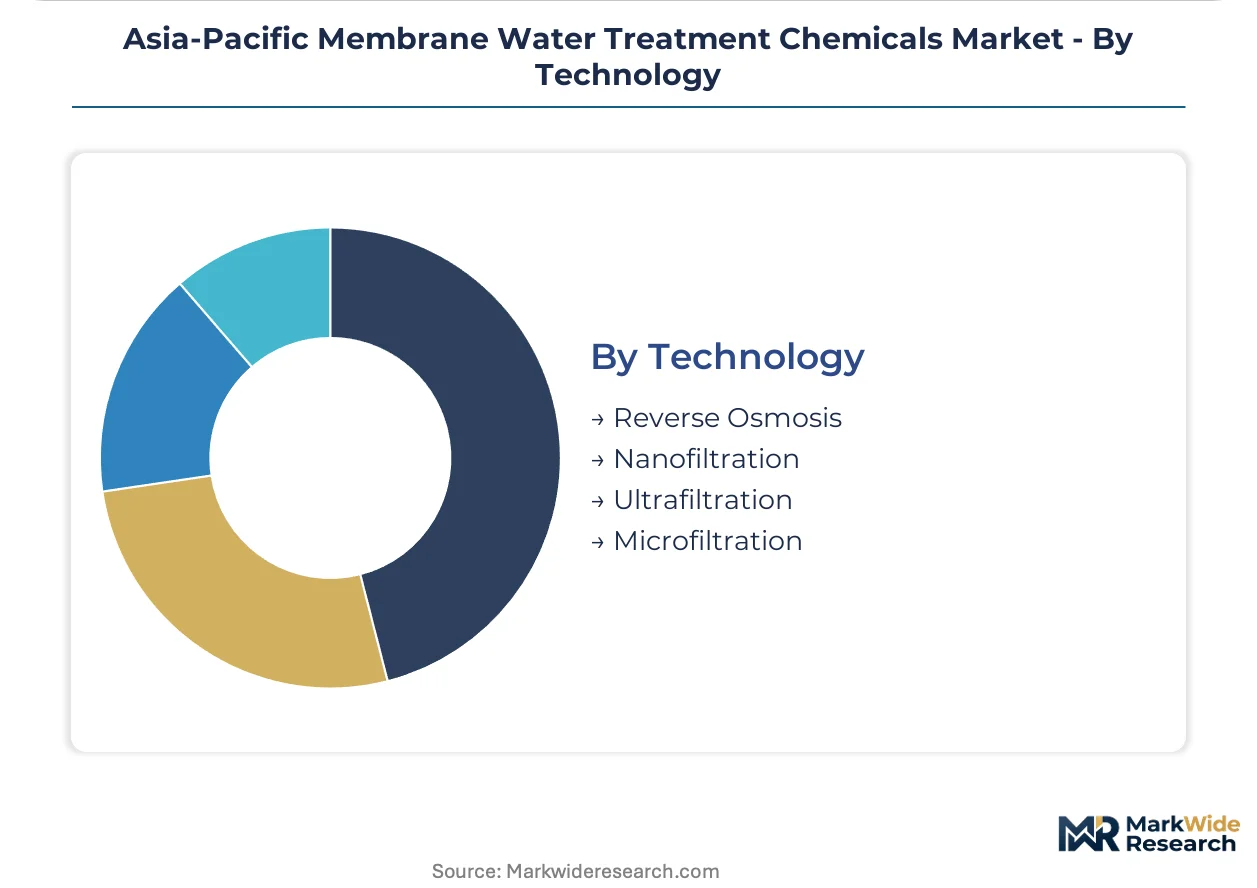
- Reverse Osmosis:Thin-film composite polyamide membranes dominate seawater desalination and ultrapure water production. Chemical demand concentrates here due to sensitivity to oxidants, scalants, and biofoulants.
- Ultrafiltration:Pretreatment chemicals for UF-RO hybrid trains reduce downstream fouling loads and extend antiscalant dosing intervals. Adoption is climbing fastest in Japanese and South Korean power plants facing thermal discharge limits.
- Nanofiltration:Selective divalent ion rejection drives demand for specialized antiscalants in water softening and selective contaminant removal applications.
- Microfiltration:Larger pore structures require less intensive chemical pretreatment, limiting additive intensity to coagulation and intermittent disinfection.
Reverse osmosis holds installed capacity. Ultrafiltration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply between industrial ultrapure water systems in eastern China and municipal desalination buildouts in Southeast Asia. Semiconductor fabs drive precision-dosed antiscalant demand, while coastal utilities prioritize bulk biocide procurement for seawater reverse osmosis trains.
China
Shanghai and Hefei semiconductor clusters anchor concentrated demand for membrane-intensive ultrapure water systems at advanced node fabrication facilities. MEE discharge standards under dual carbon mandates are accelerating phosphonate-to-polymer antiscalant substitution across Jiangsu and Zhejiang provinces. Municipal desalination plants in Tianjin and Qingdao are expanding chemical dosing capacity to address coastal freshwater stress.
Japan
Power plant operators in the Chubu and Kansai regions are adopting polymer-derived fouling-resistant pretreatment chemistries to meet strict thermal discharge limits. METI efficiency guidelines are pushing chemical suppliers toward integrated digital monitoring platforms that tie dosing to membrane flux recovery. Osaka-based formulators maintain captive laboratories for local feedwater calibration against silica saturation profiles.
South Korea
Semiconductor fabrication in the Seoul Capital Area and Busan-Ulsan corridor drives demand for sub-ppb contaminant specification chemicals in reverse osmosis trains. MFDS-aligned water quality standards are tightening biocide registration requirements for membrane contact applications. Daegu-Gyeongbuk power clusters are piloting ultrafiltration pretreatment chemicals to extend downstream antiscalant dosing intervals.
Australia
TGA-aligned state water authorities in New South Wales and Victoria enforce non-harmonized chemical registration requirements that multiply compliance costs for imported formulations. Municipal utilities in Queensland and Western Australia are consolidating vendor relationships toward single-source flux-guarantee contracts. Desalination plants in Perth and Adelaide dose antiscalants at calibrated inhibition indices against local barium and strontium saturation.
India
BIS drinking water specifications are tightening potable water standards, creating certification barriers for uncertified biocide imports in membrane-based municipal systems. Gujarat and Maharashtra industrial zones are expanding boiler feed preparation capacity with membrane-intensive chemical dosing. Tamil Nadu semiconductor assembly plants are driving initial demand for precision antiscalant formulations in southern clusters.
Asia-Pacific Membrane Water Treatment Chemicals Market Competitive Environment
Capability concentration sits with Japanese and European specialty chemical houses that control phosphonate precursor supply; scale advantage sits with diversified water treatment multinationals with captive formulation networks across Asia-Pacific. The vendor base structures into three tiers: integrated digital platform operators, regional formulation specialists with captive laboratories, and commodity blenders serving bulk municipal tenders. Dominant competitive moves include performance-based contract restructuring that ties supplier revenue to membrane recovery rates, and backward integration into polymer science expertise for fouling-resistant pretreatment chemistries.
Within the integrated platform tier, Ecolab, Inc. and Kurita Water Industries Ltd exemplify the shift toward sensor-driven dosing optimization and flux-guarantee agreements. Dow occupies a position among polymer science specialists extending material expertise into membrane-compatible pretreatment formulations. These three anchors represent divergent strategic postures: digital monitoring integration, regional laboratory customization, and materials science backward integration.
| Leading Market Players |
|---|
| Kurita Water Industries Ltd |
| Ecolab, Inc. |
| Dow |
| Toray Industries, Inc. |
| Kemira Oyj |
| Suez |
| Solenis |
| Nalco Water |
| Veolia Water Solutions & Technologies |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in phosphonate precursor production across Japan and Germany is compressing antiscalant margins while simultaneously incentivizing formulators to accelerate polymer substitution programs. This utilization imbalance feeds directly into procurement negotiations, with buyers in eastern Chinese semiconductor clusters extracting performance guarantees that shift supplier risk onto membrane recovery outcomes.
Pricing Analysis
Long-term offtake agreements dominate procurement between municipal utilities and incumbent suppliers, though spot purchasing persists for project-based desalination buildouts in Vietnam and Indonesia. Three-tier pricing structure across premium, standard, and economy levels separates certified biodegradable formulations under MEE protocols from phosphonate-heavy legacy grades and uncertified commodity blends. Cost compression in standard-tier antiscalants is intensifying because Japanese precursor suppliers face freight volatility from energy transition disruptions. Municipal utilities in Australia and Singapore exhibit the highest price sensitivity due to consolidated single-source contracting, while semiconductor fabs in Shanghai and Hefei prioritize performance premiums over unit economics.
Supply Chain Analysis
Export-control regimes limiting phosphonate specialty chemical flows from Germany and Japan are forcing Chinese formulators to diversify precursor sourcing toward domestic polymer R&D. Geographic supply concentration centers on Japan, Germany, and eastern China for phosphonate precursors, polyacrylate polymers, and biocide actives respectively. Raw material dependencies rest on ethylene oxide derivatives, phosphorous acid, and quaternary ammonium compounds. Single-source vulnerability from Japanese phosphonate suppliers exposes formulators to currency and shipping cost volatility. Distribution runs through regional blending facilities in Osaka, Shanghai, and Singapore that customize inhibition indices against local feedwater saturation profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting this market as sensor-driven dosing optimization collapses the traditional separation between chemical supply and membrane system operation, with Ecolab and Kurita's integrated monitoring ecosystems demonstrating how interoperability captures long-term contract value.
For Market Incumbents: Entrench position by acquiring captive formulation laboratories in Australia and India to preempt BIS and TGA registration barriers, while simultaneously backward integrating into polymer science expertise for biodegradable antiscalant R&D. Threat from membrane OEM warranty restrictions that lock in approved-chemical lists demands proactive engagement with Dow and Toray to secure formulation pre-qualification. Priority lever rests on converting bulk procurement relationships into flux-guarantee service contracts that tie revenue to measurable membrane performance outcomes. For New Entrants and Emerging Players: Pursue white-space opportunities in India's BIS-certified biocide segment where registration barriers have filtered out uncertified imports, and in ultrafiltration pretreatment chemicals for Japanese power plants facing METI thermal discharge limits. Tamil Nadu semiconductor assembly plants and Daegu-Gyeongbuk power clusters represent the most penetrable geographies given limited incumbent laboratory presence. Go-to-market angle should emphasize rapid OECD 301B biodegradability certification to unlock municipal tenders in Shanghai and Guangdong. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital platform operators as sensor hardware costs decline and software margins expand, favoring asset-light monitoring specialists over capital-heavy blending facilities. Long-term viability through the next decade hinges on acquiring formulators with established MEE registration dossiers and captive laboratory networks in China and Japan. Signal to watch is consolidation velocity among Australian municipal utilities toward single-source contracts, which will determine whether platform-enabled suppliers capture disproportionate share or regional blenders retain fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Science | Dow's materials expertise extension into fouling-resistant pretreatment chemistries aligns with RO module warranty bundling. |
| Performance-Based Service Contract Conversion | Kurita's flux-guarantee agreements in Singapore and Taiwan displace bulk procurement by tying revenue to membrane recovery rates. |
| Biodegradability Certification Investment | Ecolab's OECD 301B documentation enables MEE compliance in Jiangsu and Zhejiang provinces under dual carbon mandates. |
| Captive Laboratory Geographic Expansion | Regional formulation labs in Osaka and Shanghai calibrate antiscalant inhibition indices against local silica and barium saturation. |
| Digital Monitoring Platform Integration | Sensor-driven dosing optimization compresses chemical supply and system operation into unified performance contracts. |
Study Parameters
Initial hypotheses were tested against primary input from membrane plant operators, chemical procurement managers, and water utility engineers and refined through secondary validation against customs data, MEE discharge filings, and BIS certification registries. Bottom-up triangulation combined field perspectives from semiconductor fab water treatment directors, power plant maintenance chiefs, and municipal desalination procurement leads with top-down analysis of phosphonate trade flows and polymer capacity announcements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling membrane replacement intervals, chemical dosing precision requirements, and feedwater chemistry specialization by geography. Segmentation dimensions included product chemistry tier, end-use intensity, membrane pore classification, and regional regulatory cluster. CAGRs were derived from installed capacity buildouts and substitution elasticity parameters, with specific inputs from semiconductor cluster expansion timelines and MEE enforcement trajectories.
Sensitivities concentrate around MEE discharge standard revisions, BIS implementation timelines, and phosphonate precursor supply disruptions. Forecasts reflect documented assumptions regarding biodegradability certification adoption rates and membrane OEM warranty list expansion. Material shifts in dual carbon policy stringency or OECD protocol harmonization across Asia-Pacific would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market