
 South America Membrane Water and Wastewater (WWT) Treatment Market | 2026-2036
South America Membrane Water and Wastewater (WWT) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Membrane Water and Wastewater (WWT) Treatment Market Analytics
CONAMA Resolution 430 effluent quality standards is recalibrating procurement priorities across Brazilian municipal water authorities. Suez leverages its technology leadership in reverse osmosis systems to anchor large-scale desalination contracts along Chile's arid coastline. Veolia Water Technologies competes through integrated membrane bioreactor solutions that dominate Brazil's industrial wastewater retrofit segment. Evoqua Water Technologies LLC specializes in mobile filtration units that sustain emergency response capabilities for mining operators in Peru's Andean regions.
Membrane water and wastewater treatment employs semi-permeable polymeric or ceramic barriers with pore sizes ranging from 0.1 nanometers in reverse osmosis to 10 micrometers in microfiltration, operating under trans-membrane pressures of 1 to 80 bar to separate contaminants from aqueous streams. Reverse osmosis commands the largest installed base due to its dominance in desalination and high-purity industrial applications, while membrane bioreactor technology represents the fastest-expanding category as combined biological and membrane processes displace conventional activated sludge systems in space-constrained municipal plants. The industrial end-user segment concentrates margin pools where mining, pulp and paper, and food processing facilities require customized pretreatment trains and ongoing membrane replacement services.
ANVISA potable water quality protocols and Chile's Ministry of Environment mining effluent decrees shape product certification requirements and market access conditions across the region. Brazil's CONAMA framework and Peru's OEFA environmental audits create overlapping compliance obligations that favor suppliers with multi-country regulatory expertise. Stakeholders must monitor evolving lithium extraction wastewater rules in Argentina's Puna region as brine processing intensifies and membrane demand shifts toward specialized nanofiltration configurations.
Market Dynamics
Membrane bioreactor technology is compressing project footprints across Brazil's São Paulo industrial corridor, forcing incumbent suppliers to reconfigure their equipment architectures for space-constrained retrofit installations.
Growth Catalysts
- CONAMA Resolution 430:Brazil's effluent quality mandates are accelerating replacement cycles at municipal wastewater facilities. Membrane systems displace conventional activated sludge infrastructure unable to meet discharge thresholds.
- Chilean mining effluent decrees:The Ministry of Environment's brine processing rules are expanding nanofiltration demand in Antofagasta and Atacama regions. Operators require specialized pretreatment trains for lithium extraction wastewater.
- Reverse osmosis desalination:Coastal Chile and Peru's arid Pacific zones are deploying large-scale RO capacity. Trans-membrane pressure advances are reducing energy intensity per cubic meter treated.
Market Restraints
- Polymeric membrane import dependency:Ceramic and polymeric barrier materials concentrate in European and East Asian supply bases. South American fabricators face extended lead times and currency exposure.
- High-purity water specification gaps:ANVISA potable water protocols create certification friction for foreign equipment suppliers. Testing timelines extend commercialization cycles by 12-18 months.
- Conventional coagulation-flocculation:Legacy chemical treatment retains cost advantages in low-volume municipal applications. Price-sensitive Brazilian interior municipalities delay membrane adoption.
Strategic Opportunities
- Argentina's Puna lithium belt:Brine processing intensification in Catamarca and Jujuy provinces is creating specialized nanofiltration demand. Membrane configurations optimized for high-salinity extraction wastewater remain undersupplied.
- Mobile filtration units:Peruvian Andean mining operators require rapid-deployment emergency response capabilities. Containerized systems bypass fixed infrastructure constraints at remote extraction sites.
- Integrated MBR-RO trains:Convergence of biological treatment with reverse osmosis is enabling direct potable reuse. Chilean coastal utilities pilot closed-loop systems for municipal supply security.
Industry Challenges
- Membrane fouling expertise:Specialized chemical cleaning protocols and autopsy diagnostics require trained field technicians. Brazilian utilities report 23% higher OPEX from improper maintenance scheduling.
- Legacy activated sludge integration:Retrofit projects must sequence membrane installation around operational biological basins. Downtime minimization constraints compress installation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Membrane Water and Wastewater (WWT) Treatment Market |
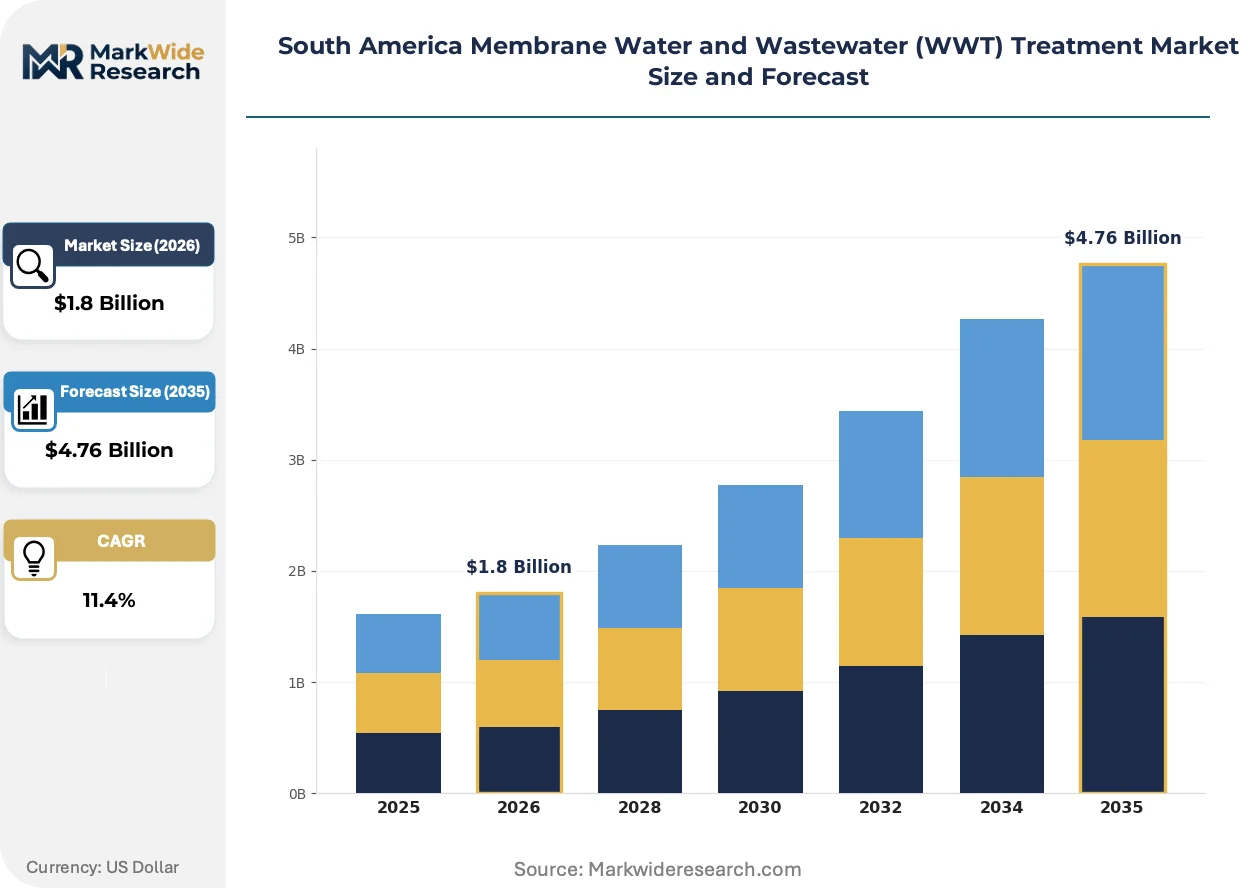
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultrafiltration, Microfiltration, Nanofiltration End User: Municipal, Industrial, Residential, Commercial Technology: Membrane Bioreactor, Pressure-Fed, Gravity-Fed, Integrated Membrane System Application: Desalination, Reuse & Recycling, Of Wastewater, Drinking Water Treatment |
| Companies Covered | Suez, Veolia Water Technologies, Kurita Water Industries Ltd., AECOM, Aquatech International LLC, Evoqua Water Technologies LLC, Black & Veatch Holding Company, IDE Technologies, Ovivo, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Membrane Water and Wastewater (WWT) Treatment Market Evolving Landscape
Equipment architectures are fragmenting into standardized skids and containerized subsystems, enabling faster deployment and localized assembly across South America's diverse topography and infrastructure gaps.
Membrane bioreactor systems are modularizing into pre-engineered package plants with integrated process control. Brazilian pulp and paper mills in Paraná state are adopting these configurations to bypass civil construction bottlenecks. The shift is compressing project delivery from 18 months to 8 months while reducing site labor requirements.
Chile's Ministry of Environment mining effluent decrees are mandating zero-liquid-discharge thresholds for copper and lithium operations. Antofagasta region processors must install advanced membrane trains to meet brine containment rules. Equipment suppliers are certifying ceramic ultrafiltration configurations specifically for high-TDS extraction wastewater.
Service unbundling is separating membrane replacement from original equipment supply. Peruvian mining operators now procure spiral-wound elements through independent distributors rather than turnkey contractors. The disintermediation is most visible in Arequipa and Cusco regions where mobile filtration fleets require rapid consumable turnaround.
South America Membrane Water and Wastewater (WWT) Treatment Market Segmentation
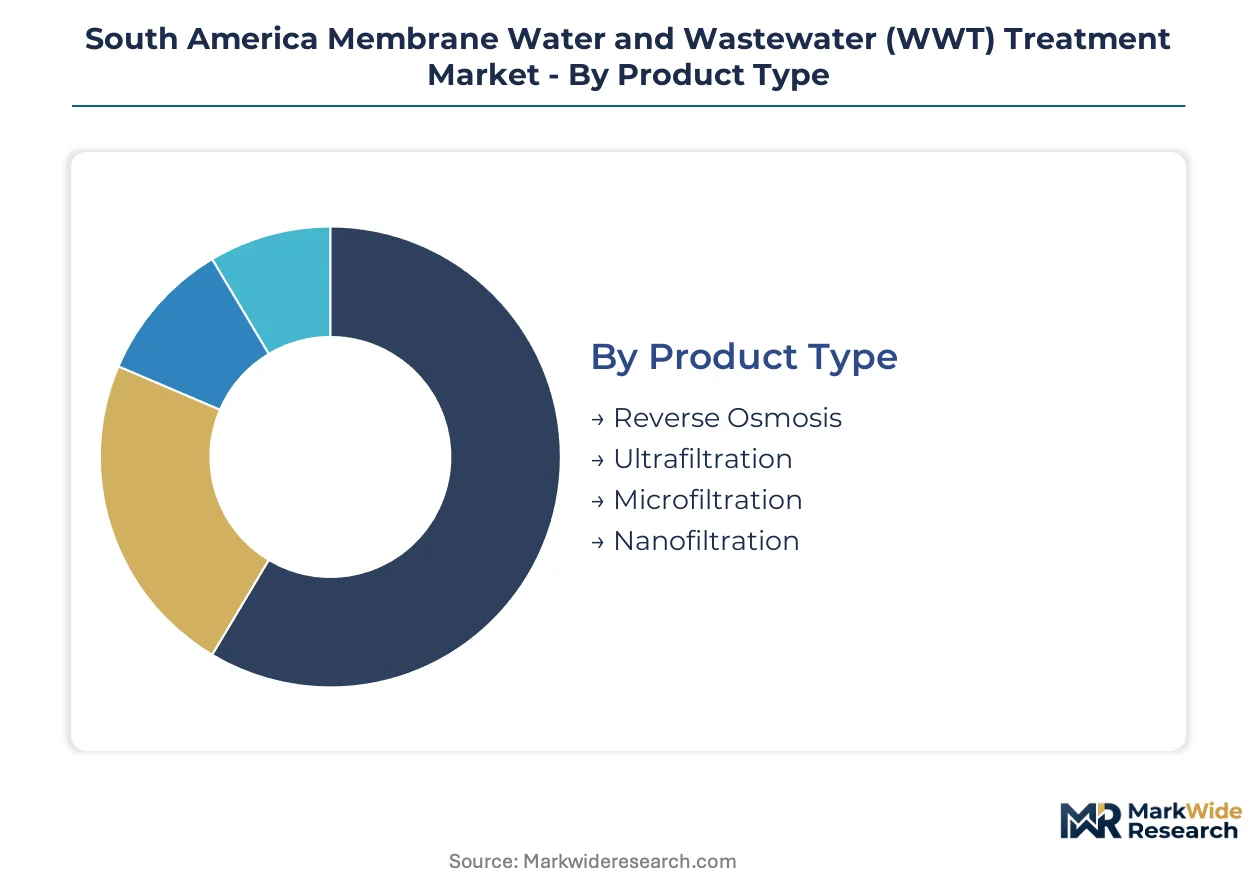
Membrane technology selection in South America tracks water stress gradients and regulatory stringency. Product specifications diverge sharply between Chile's mining-corridor desalination demands and Brazil's municipal retrofit constraints. Understanding segment boundaries clarifies where margin pools concentrate versus where price competition dominates.
Product Type:
Volume concentration sits with established pressure-driven systems, while premium capture shifts toward specialized barrier configurations for industrial process water.
- Reverse Osmosis:Dense polyamide thin-film composite membranes operate at 15-80 bar trans-membrane pressure, rejecting dissolved salts and organics below 0.1 nanometers. Chile's Antofagasta mining operators deploy seawater RO trains for copper processing, driven by freshwater scarcity in the Atacama Desert.
- Ultrafiltration:Porous polymeric or ceramic barriers with 0.01-0.1 micrometer pore sizes remove colloids, bacteria, and macromolecules under 1-10 bar pressure. Brazil's São Paulo state water utility Sabesp integrates UF pretreatment before RO in municipal reuse schemes, responding to CONAMA effluent mandates.
- Microfiltration:0.1-10 micrometer pore structures target suspended solids and protozoa in low-pressure applications. Brazilian food processors in Paraná deploy MF for dairy whey concentration.
- Nanofiltration:Divalent ion-selective membranes bridge RO and UF performance for softening and selective salt removal. Argentina's Puna lithium brine processors pilot NF for magnesium-lithium separation.
Today's leader: Reverse Osmosis. Tomorrow's challenger: Nanofiltration.
End User:
Procurement authority fragments between centralized municipal tenders and dispersed industrial specifications, with contract structures diverging accordingly.
- Industrial:Mining, pulp and paper, and food processing facilities specify customized pretreatment trains with performance guarantees tied to throughput metrics. Peru's Andean gold and copper operators drive mobile filtration demand for remote site water security.
- Municipal:State water companies in Brazil and Chile issue framework agreements for membrane bioreactor retrofits and desalination capacity. ANVISA potable water protocols shape equipment certification requirements.
- Commercial:Hotels, hospitals, and office complexes deploy point-of-entry ultrafiltration for localized treatment. São Paulo's commercial real estate sector adopts packaged MBR systems for sewage compliance.
- Residential:Point-of-use reverse osmosis units serve affluent households in water-stressed Chilean coastal zones. Penetration remains limited by import costs and maintenance infrastructure gaps.
Industrial buyers command specification authority. Municipal tenders determine volume scale.
Technology:
Biological-membrane integration is displacing conventional activated sludge, while pressure configuration choices reflect energy cost sensitivity across the region.
- Membrane Bioreactor:Immersed or external membrane modules combine biological treatment with solids separation, eliminating secondary clarifiers. Brazilian pulp mills in Santa Catarina adopt MBR to compress footprints and meet stringent COD discharge limits.
- Pressure-Fed:Pump-driven crossflow or dead-end filtration configurations dominate high-recovery industrial applications. Chilean mining operators prefer pressure-fed RO for brine concentration and zero-liquid-discharge compliance.
- Gravity-Fed:Low-energy membrane filtration operates without pumping for small-scale rural supply. Colombia's Andean communities pilot gravity UF for dispersed settlement water security.
- Integrated Membrane System:Multi-barrier trains combine MF/UF pretreatment with RO polishing for direct potable reuse. Chilean coastal utilities pilot closed-loop configurations for drought resilience.
Membrane Bioreactor claims the steepest expansion trajectory. Integrated systems await regulatory acceptance for potable reuse.
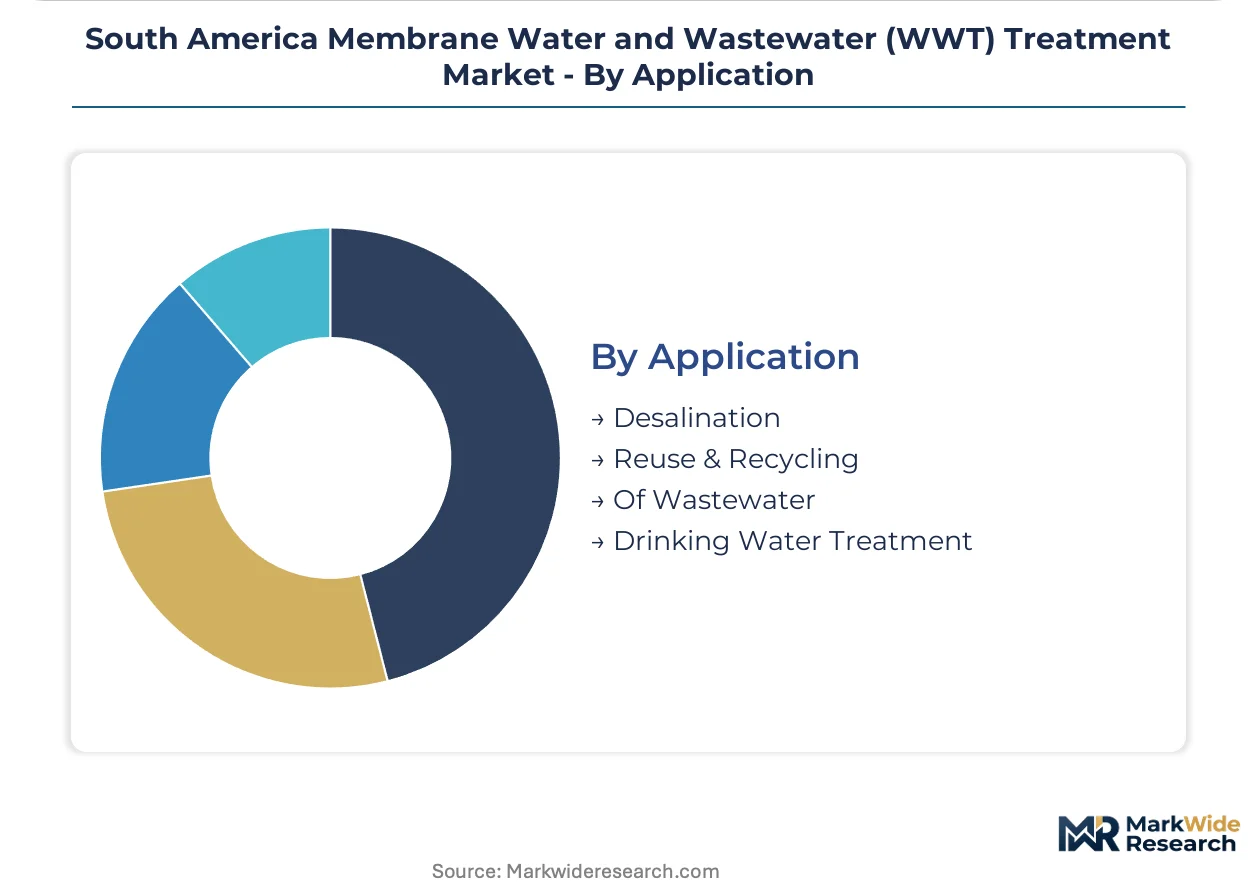
Application:
Freshwater scarcity and effluent compliance create divergent membrane demand profiles across coastal and inland geographies.
- Desalination:Seawater and brackish water reverse osmosis capacity expands along Chile's arid Pacific coastline and Peru's Sechura Desert. Energy recovery device advances reduce specific power consumption below 3 kWh per cubic meter.
- Reuse & Recycling:Treated municipal effluent undergoes membrane polishing for industrial process water or agricultural irrigation. São Paulo's ABC Paulista industrial corridor contracts for reclaimed water supply from municipal MBR plants.
- Wastewater Treatment:Membrane bioreactors and tertiary filtration upgrade biological plant effluent to meet discharge standards. Brazil's CONAMA Resolution 430 drives retrofit demand across state water utilities.
- Drinking Water Treatment:Surface water ultrafiltration removes pathogens and turbidity for municipal supply. Colombian utilities deploy membrane filtration for Andean reservoir protection against agricultural runoff.
Wastewater treatment anchors installed base growth. Reuse and recycling emerges as the strategic pivot point.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane water treatment infrastructure first scaled in Brazil's São Paulo industrial corridor during the 1990s municipal privatization wave. Chilean mining operators subsequently pioneered desalination integration for copper processing in the Atacama Desert. These two anchor markets now generate divergent technology demand profiles across the continent.
Brazil
CONAMA Resolution 430 effluent mandates are accelerating municipal retrofit cycles across state water utilities. ANVISA potable water protocols shape equipment certification timelines for foreign suppliers. São Paulo's ABC Paulista industrial corridor contracts for reclaimed water from membrane bioreactor plants serving pulp and paper processors.
Chile
The Ministry of Environment's mining effluent decrees are expanding nanofiltration demand in Antofagasta and Atacama regions. Zero-liquid-discharge thresholds for copper and lithium operations mandate advanced membrane trains. Coastal utilities pilot integrated MBR-RO configurations for direct potable reuse in drought-stressed Valparaíso.
Argentina
Brine processing intensification in Catamarca and Jujuy provinces is creating specialized nanofiltration demand for lithium extraction wastewater. The Puna region's high-salinity extraction requirements favor ceramic ultrafiltration configurations. Mendoza's wine processing sector deploys microfiltration for clarification and stabilization applications.
Peru
Andean mining operators in Arequipa and Cusco regions drive mobile filtration demand for remote site water security. OEFA environmental audits create compliance obligations favoring suppliers with multi-country regulatory expertise. Containerized systems bypass fixed infrastructure constraints at high-altitude extraction sites.
Colombia
Andean reservoir protection against agricultural runoff is driving surface water ultrafiltration deployment. The country's national environmental regulator shapes discharge standards for municipal utilities. Bogotá's water utility pilots gravity-fed membrane systems for dispersed rural settlement supply security.
South America Membrane Water and Wastewater (WWT) Treatment Market Competitive Landscape
Capital-heavy membrane fabricators compete with asset-light system integrators across South America's project landscape. The vendor base concentrates around three tiers: multinational technology licensors with regional service networks, mid-scale local assemblers of imported membrane elements, and specialized mobile filtration operators serving remote mining sites. Consolidation pressures favor players with multi-country regulatory expertise and established CONAMA or ANVISA certification pathways. Dominant competitive moves include strategic partnerships with state water utilities and geographic expansion through distributor networks in secondary markets.
Within the multinational technology tier, Suez and Veolia Water Technologies anchor large-scale desalination and industrial retrofit segments through integrated membrane bioreactor and reverse osmosis offerings. Evoqua Water Technologies LLC occupies a position among mobile filtration specialists, serving emergency response requirements for mining operators in Peru's Andean regions. These three exemplify divergent archetypes: technology licensors leveraging global R&D scale versus application-focused deployers of containerized systems.
| Leading Market Players |
|---|
| Suez |
| Veolia Water Technologies |
| Kurita Water Industries Ltd. |
| AECOM |
| Aquatech International LLC |
| Evoqua Water Technologies LLC |
| Black & Veatch Holding Company |
| IDE Technologies |
| Ovivo |
| Others |
Value Network & Pricing Analysis
Polyamide thin-film composite resin indices cascade through South American membrane procurement tiers, compressing margins on standard spiral-wound elements while ceramic ultrafiltration configurations retain pricing power through European supply scarcity.
Pricing Analysis
Project-based equipment supply with long-term consumables contracting anchors revenue architecture across Brazilian municipal tenders and Chilean mining frameworks. Price differentiation hinges on ANVISA certification tier and bundled membrane replacement service density. Cost compression in standard polymeric RO modules intensifies as Chinese fabricators expand distributor networks. Municipal utilities in Brazil's interior states exhibit acute price sensitivity, while Antofagasta lithium operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from East Asian ports to Pacific Coast terminals amplifies landed cost disparities between containerized membrane elements and bulk ceramic shipments. Polyamide barrier materials concentrate in Japan and South Korea; ceramic substrates anchor in Germany and France. Currency exposure and extended ocean freight cycles constitute the dominant supply chain risk. Distribution runs through São Paulo-based system integrators for Brazilian industrial clusters and direct OEM channels for Chilean mining operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
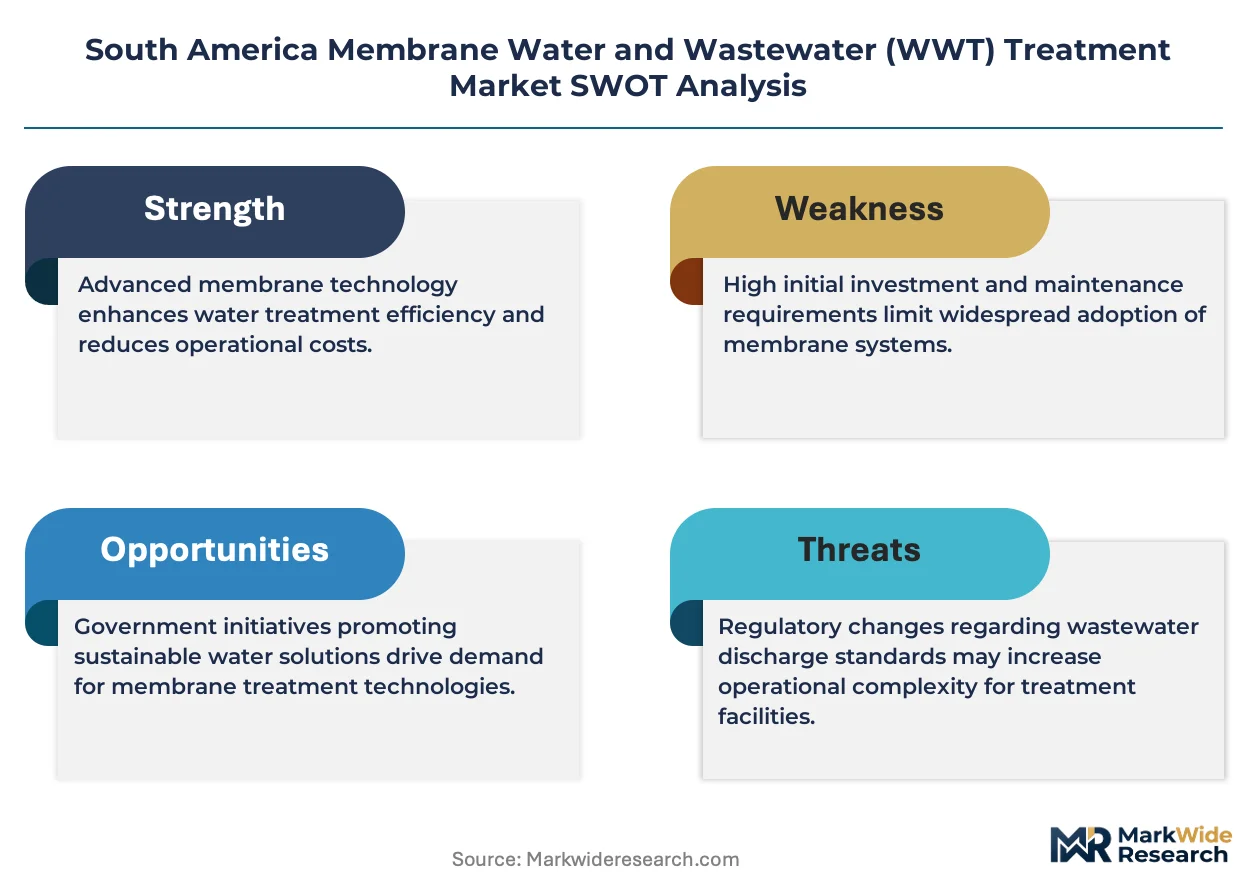
Margin expansion potential concentrates in specialized nanofiltration configurations for lithium brine processing, where ceramic membrane premiums offset polymeric commodity pressure through performance-linked pricing.
For Market Incumbents: Lock in CONAMA certification pathways to preempt municipal tender disqualification. Secure captive supply of ceramic substrates through backward integration into European membrane fabricators. Anchor service density in São Paulo's ABC Paulista corridor to block mobile filtration entrants from retrofit opportunities. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer white-space access in Peruvian Andean regions where OEFA compliance complexity deters established competitors. Target containerized emergency filtration for remote gold extraction sites in Cusco. Lead with rapid-deployment service models that bypass fixed infrastructure bidding cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-country regulatory expertise overlaps with CONAMA and ANVISA certification infrastructure. Mid-scale Brazilian system integrators with established state utility relationships represent priority acquisition profiles. Watch Argentine lithium extraction wastewater rule finalization as inflection signal for nanofiltration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Certification | ANVISA pathway clearance unlocks premium pricing in Brazilian municipal tenders. |
| Mobile Filtration Fleet Expansion | Containerized systems bypass fixed infrastructure constraints at Peruvian Andean sites. |
| Integrated MBR-RO Train Development | Closed-loop configurations target Chilean coastal direct potable reuse pilots. |
| Service Unbundling | Independent membrane replacement distribution captures Peruvian mining consumable turnover. |
| Argentina Market Entry | Puna lithium belt nanofiltration demand remains undersupplied by incumbent networks. |
Research Methodology
Coverage spans Brazil, Chile, Argentina, Peru, and Colombia, with primary inputs from each market cluster. The study combines interviews with state water utility procurement directors, mining operations environmental managers, membrane system integrators, and ceramic substrate suppliers with secondary validation through CONAMA regulatory filings, ANVISA certification databases, Chilean Ministry of Environment effluent decrees, and customs import records. Bottom-up project pipeline analysis triangulates against top-down equipment demand estimates.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include membrane product type, end-user industry, technology configuration, and application purpose. CAGRs derive from installed base expansion rates, replacement cycle acceleration, and technology substitution curves. Lithium extraction wastewater regulatory evolution and trans-membrane pressure efficiency gains constitute industry-specific forecast inputs.
Regulatory implementation delays, currency volatility against membrane import costs, and ceramic substrate supply disruptions are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market