
 Global Water Treatment Technology Market | 2026-2036
Global Water Treatment Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Treatment Technology Market Foresight
REACH is decoupling compliance costs from conventional treatment economics across European industrial zones. Ecolab Inc. leverages its integrated chemical-service model to sustain recurring revenue in food processing wastewater. Veolia Environnement anchors large-scale desalination contracts in water-stressed coastal zones. DuPont de Nemours differentiates through FilmTec membrane chemistry leadership in reverse osmosis applications.
Water treatment technology encompasses physical, chemical, and biological processes that remove contaminants from raw water to produce effluent safe for discharge or reuse, with membrane filtration systems typically operating at pore sizes ranging from 0.1 microns in microfiltration to 0.0001 microns in reverse osmosis for dissolved salt rejection. The primary purpose spans municipal potable supply, industrial process water conditioning, and environmental compliance for effluent discharge. Membrane filtration leads technology value capture due to energy intensity and replacement part cycles, while UV disinfection grows fastest in agricultural irrigation reuse where chemical residual limits constrain chlorine alternatives. Municipal supply dominates application revenue through tariff-backed infrastructure spending, yet desalination concentrates margin pools in Middle Eastern and Australian projects with high contract values and long operational tenors.
The EPA enforces Clean Water Act discharge limits that compel US power generation stations and chemical manufacturers to install advanced biological nutrient removal, while China's MEE implements dual carbon goals that restrict energy-intensive thermal desalination in favor of electrochemical and membrane-based alternatives. WHO drinking water quality guidelines shape product standards for UV dose validation and membrane integrity testing in export markets. Stakeholders must monitor how fragmented national standards for emerging contaminants such as PFAS create certification complexity that favors multi-technology platform providers over point-solution specialists.
Market Dynamics
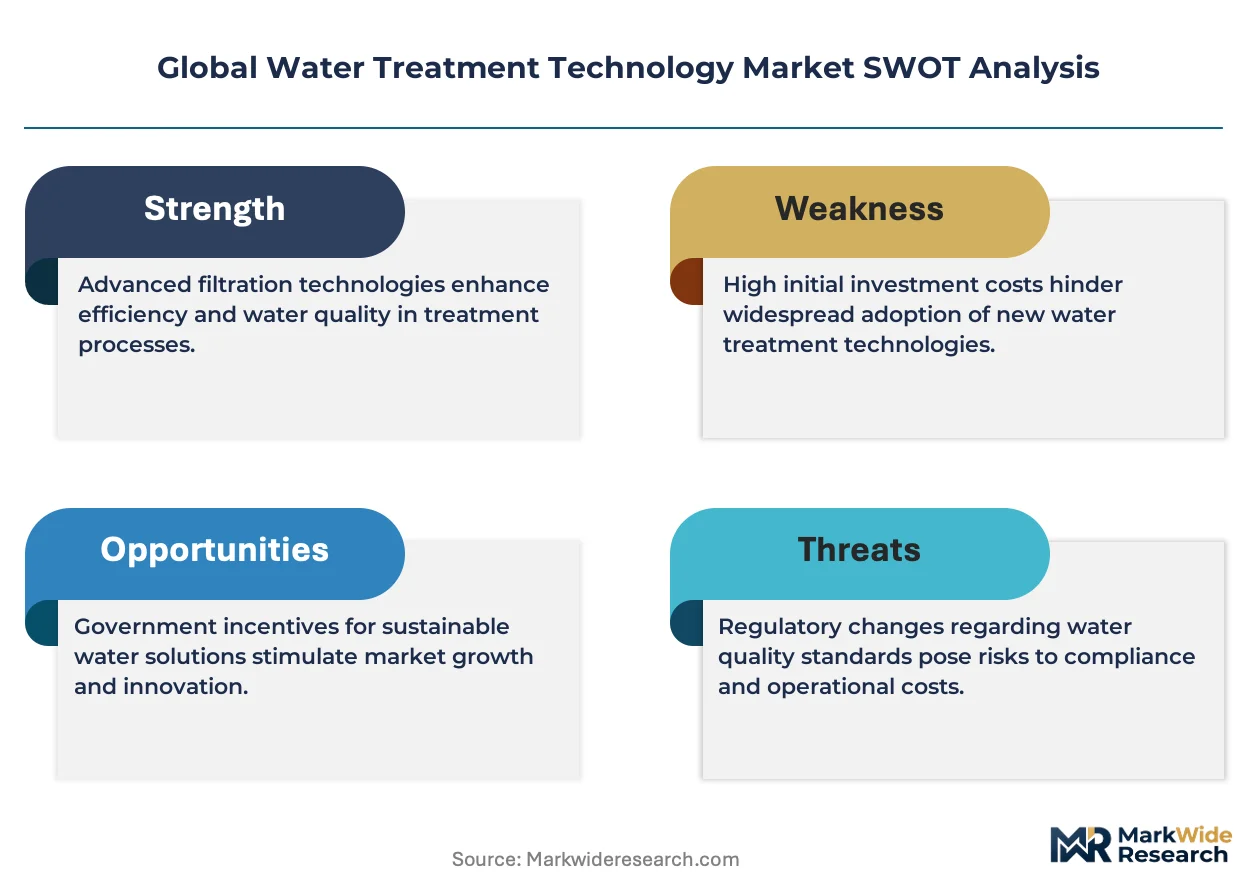
Membrane fouling chemistry and energy recovery system advances are compressing operational expenditure gaps between seawater desalination and conventional surface water treatment, forcing incumbent utilities to reassess asset replacement cycles.
Growth Catalysts
- REACH chemical restriction cascades:European industrial discharge permits now mandate tertiary treatment for legacy contaminants, compelling German chemical parks and Dutch refining clusters to retrofit biological nutrient removal with advanced oxidation stages.
- China's MEE dual carbon enforcement:Provincial emissions audits restrict thermal desalination expansion along the Bohai Rim, redirecting capital toward electrochemical desalination and membrane bioreactor installations in Shandong and Jiangsu provinces.
- Membrane replacement part cycles:The installed base of hollow-fiber ultrafiltration systems installed during the 2015-2020 municipal upgrade wave enters scheduled membrane replacement, generating recurring revenue for module suppliers serving utilities in São Paulo, Jeddah, and Singapore.
Market Restraints
- Specialty polymer supply concentration:Polyethersulfone and polyvinylidene fluoride membrane substrate production concentrates among Japanese and German chemical conglomerates, exposing module fabricators to feedstock allocation risk during petrochemical cycle tightness.
- High-purity chemical input cost volatility:Antiscalant chemistries and membrane cleaning formulations depend on phosphonate and acrylic acid derivatives whose pricing tracks energy-intensive acrylonitrile feedstock markets.
- Brine disposal regulatory friction:Coastal desalination projects in California and Mediterranean jurisdictions face extended permitting timelines due to evolving marine ecosystem impact assessments for concentrated brine outfalls.
Strategic Opportunities
- Industrial water reuse mandate expansion:India's Central Pollution Control Board zero-liquid-discharge directives for textile dyeing clusters in Tiruppur and Surat create captive treatment demand exceeding current installed electrodialysis reversal capacity.
- Digital twin convergence with membrane operations:Real-time fouling prediction algorithms fused with automated chemically-enhanced backwash systems enable remote operations staffing models for distributed rural treatment assets.
- EU Green Deal circular water economy incentives:Project finance structures for industrial symbiosis schemes—where treated effluent from semiconductor fabrication feeds adjacent cooling towers—qualify for green bond certification in Flanders and Catalonia industrial parks.
Industry Challenges
- Membrane integrity testing certification bottlenecks:Pressure decay test protocols and fluorescent dye validation procedures lack harmonization between EPA guidance documents and WHO drinking water quality guidelines, forcing multinational equipment suppliers to maintain parallel quality management systems.
- Legacy SCADA integration complexity:Municipal utilities operating distributed well-field networks confront protocol translation burdens when retrofitting 1990s-era programmable logic controllers with cloud-based operational analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Treatment Technology Market |
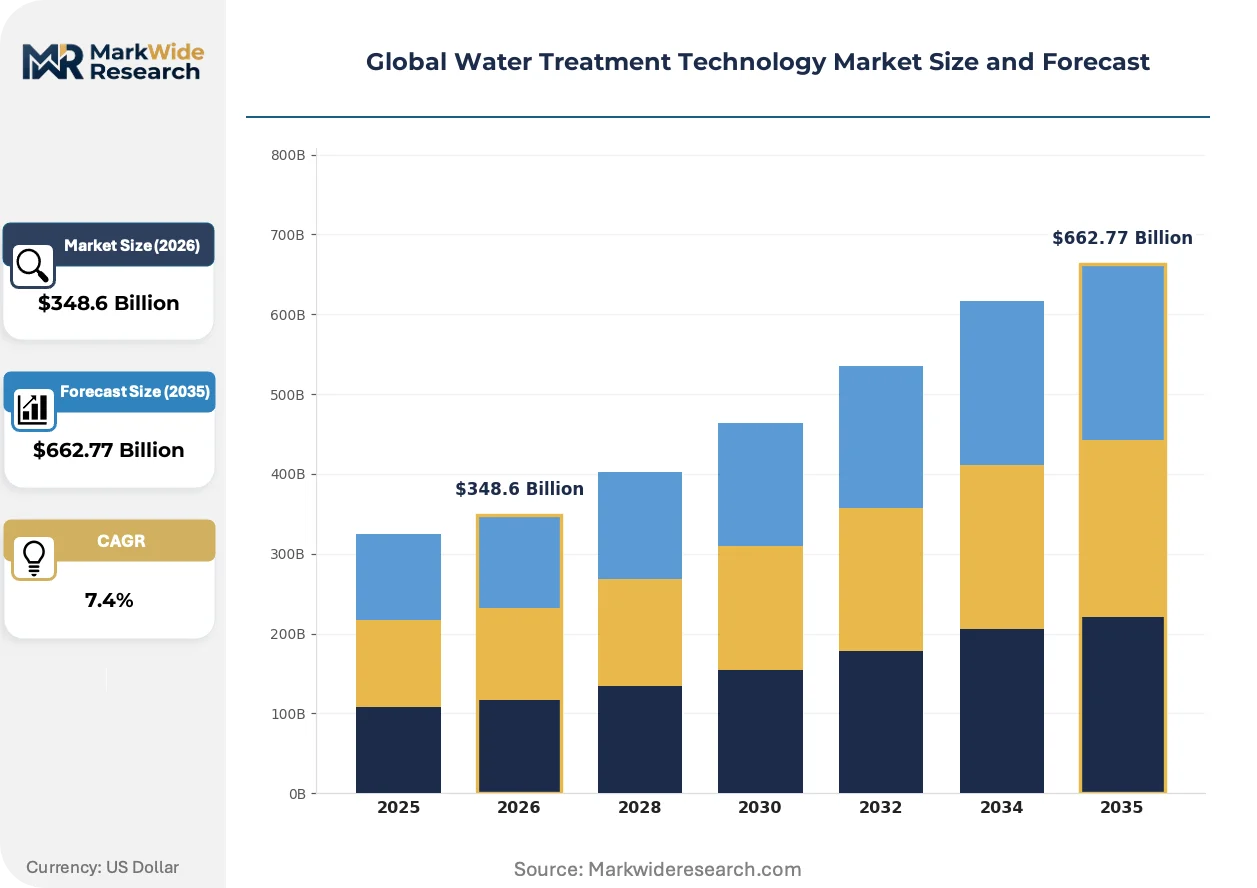
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $662.77 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, UV Disinfection, Ion Exchange, Activated Carbon, Electrochemical Treatment Application: Municipal Supply, Industrial Effluent, Agricultural Irrigation, Wastewater Recycling, Desalination End User: Water Utilities, Food & Beverage Plants, Chemical Manufacturers, Mining Firms, Power Generation Stations Deployment Type: On-Premise, Mobile Units, Plug & Play Systems, Remote Monitoring, Modular Plants |
| Companies Covered | Ecolab Inc., Pentair plc, Veolia Environnement, DuPont de Nemours, Kurita Water Industries, SUEZ Water Technologies, Evoqua Water Technologies, BASF SE, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Treatment Technology Market Shifts & Advancements
Electrochemical process intensification and artificial intelligence-driven predictive maintenance are compressing the traditional engineering-procurement-construction model for water treatment infrastructure deployment.
Containerized reverse osmosis skids are modularizing project delivery for mining camp water supply and disaster relief applications. Engineering firms in Chile's Atacama lithium triangle and Australia's Pilbara iron ore region now specify plug-and-play desalination units with 90-day commissioning windows versus 18-month conventional builds. This compression is displacing permanent civil works contracts with rental-lease-operate structures that transfer residual technology risk to equipment vendors.
EPA's forthcoming PFAS maximum contaminant level rule is forcing granular activated carbon and anion exchange resin specification upgrades across US municipal utilities. The regulatory consequence extends beyond treatment technology to residual management, as spent carbon regeneration facilities face air emissions permitting complexity that favors centralized regional hubs over on-site reactivation. Small and medium utilities in the Ohio River Valley and Southeast aquifer regions are consolidating procurement through inter-municipal purchasing cooperatives to achieve volume pricing on compliant resin systems.
Power purchase agreement structures for renewable energy are reshaping operational economics for energy-intensive membrane plants. Saudi desalination developers and Australian water utilities now contract directly with solar and wind farm operators for behind-the-meter supply, bypassing traditional utility tariff structures. This direct contracting model is most advanced in regions with nodal electricity market pricing, where treatment plant load flexibility enables demand response revenue stacking that offsets 15-25% of baseline energy costs.
Global Water Treatment Technology Market Segmentation
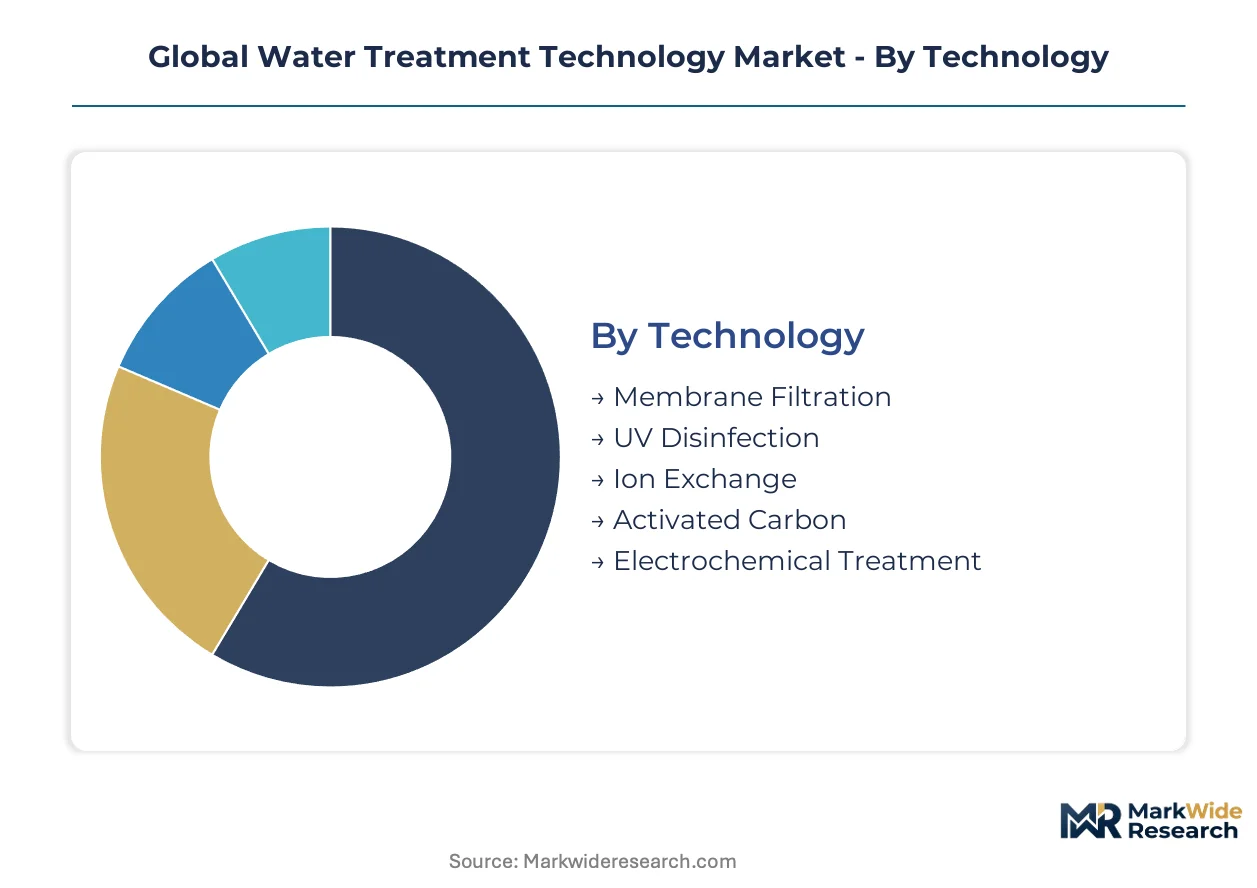
Technology selection in water treatment hinges on contaminant profiles, energy economics, and regulatory discharge limits. Each segmentation axis reveals distinct procurement patterns and margin structures across municipal and industrial buyer groups.
Technology:
Membrane chemistry and energy intensity separate premium systems from commodity alternatives.
- Membrane Filtration:Polyethersulfone and polyvinylidene fluoride substrates operate at pore sizes from 0.1 microns down to 0.0001 microns for dissolved salt rejection. Demand concentrates in China's Yangtze River Delta industrial corridor, where tightening MEE discharge rules force textile and electronics manufacturers toward zero-liquid-discharge configurations.
- UV Disinfection:Medium-pressure mercury and UV-LED systems deliver validated dose delivery for pathogen inactivation without chemical residuals. Agricultural irrigation reuse in California's Central Valley and Australia's Murray-Darling Basin drives specification, where chlorine residual limits constrain chemical alternatives.
- Ion Exchange:Selective resin beds remove dissolved inorganics through reversible chemical binding.
- Activated Carbon:Granular and powdered forms adsorb organic compounds and chlorine precursors.
- Electrochemical Treatment:Electrocoagulation and electrooxidation units treat recalcitrant industrial streams.
Mature deployment sits with activated carbon. Newer deployment is concentrated in electrochemical treatment.
Application:
Revenue concentration follows infrastructure spending cycles and regulatory enforcement intensity.
- Municipal Supply:Conventional coagulation-filtration-disinfection trains and advanced membrane-based potable systems serve tariff-backed utility procurement. German municipalities under the revised EU Drinking Water Directive upgrade legacy infrastructure, while São Paulo and Jeddah utilities replace hollow-fiber ultrafiltration membranes from the 2015-2020 installation wave.
- Desalination:Seawater reverse osmosis and thermal distillation plants address water stress in coastal zones. Saudi Arabia's Red Sea and Persian Gulf projects and Australian utilities deploy solar-PPA-backed membrane plants, bypassing traditional utility tariffs through direct renewable contracting.
- Industrial Effluent:Biological nutrient removal and advanced oxidation stages treat process streams.
- Agricultural Irrigation:Reclaimed wastewater and brackish groundwater treatment supports crop production.
- Wastewater Recycling:Tertiary polishing enables industrial symbiosis and direct potable reuse.
Contract value pools concentrate in desalination. Steepest expansion trajectory appears in wastewater recycling.
End User:
Procurement sophistication varies from tariff-regulated utilities to risk-managed industrial operators.
- Water Utilities:Municipal and regional authorities deploy capital-intensive infrastructure with decades-long operational tenors. Inter-municipal purchasing cooperatives in the US Ohio River Valley consolidate granular activated carbon procurement to achieve volume pricing on EPA PFAS-compliant resin systems.
- Chemical Manufacturers:German chemical parks and Dutch refining clusters under REACH mandates retrofit biological nutrient removal with advanced oxidation stages for legacy contaminant destruction.
- Food & Beverage Plants:Process water conditioning and wastewater treatment for discharge compliance.
- Mining Firms:Remote camp water supply and process water treatment in water-scarce regions.
- Power Generation Stations:Cooling tower makeup and flue gas desulfurization wastewater treatment.
Recurring service revenue anchors with water utilities. Technology risk transfer concentrates in mining firms.
Deployment Type:
Project delivery compression is displacing permanent civil works with flexible commercial structures.
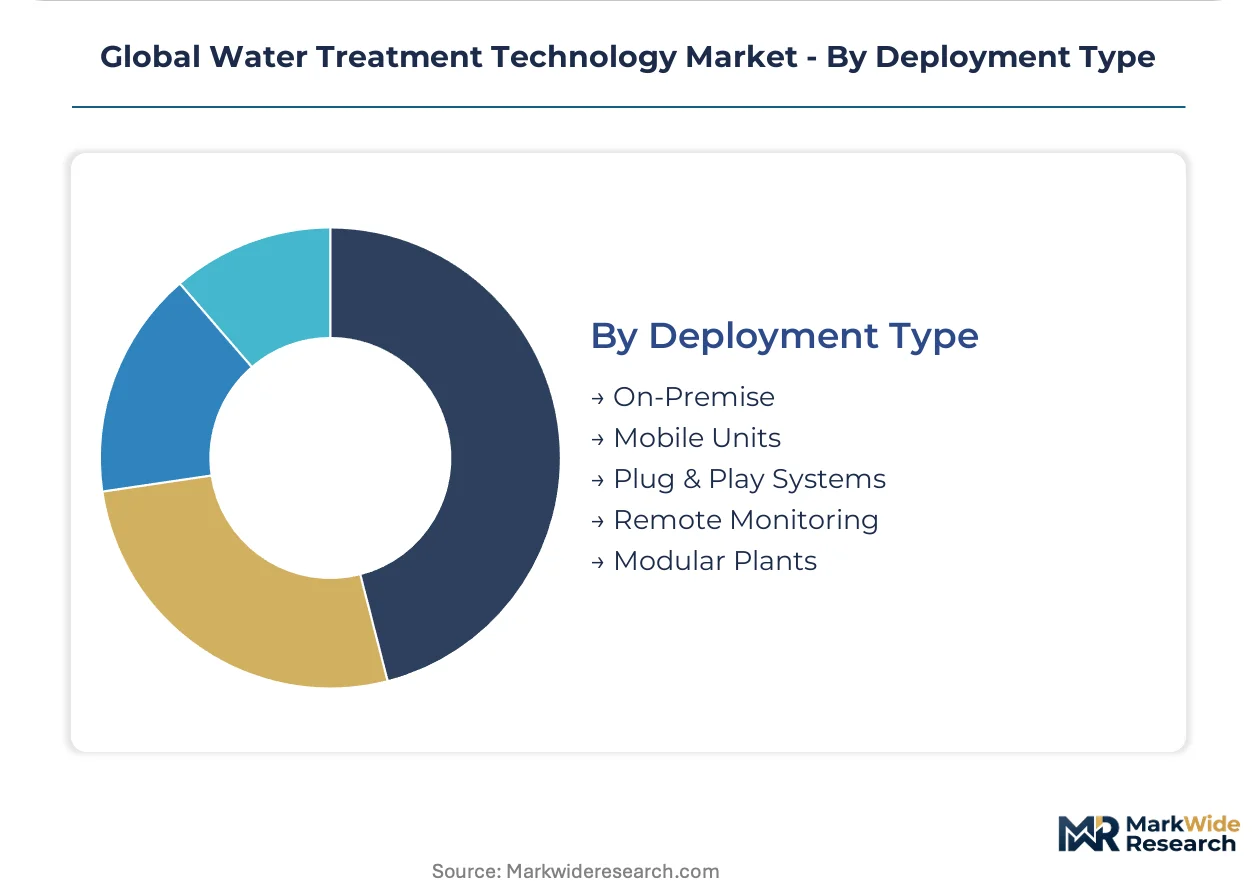
- Plug & Play Systems:Containerized reverse osmosis skids with 90-day commissioning windows replace 18-month conventional builds. Chile's Atacama lithium triangle and Australia's Pilbara iron ore region specify rental-lease-operate structures that transfer residual technology risk to equipment vendors.
- Remote Monitoring:Cloud-based operational analytics platforms fuse real-time fouling prediction with automated chemically-enhanced backwash systems. Distributed rural assets in India's textile clusters and Southeast Asian municipal networks enable remote operations staffing models.
- On-Premise:Permanent civil works with integrated SCADA and legacy PLC infrastructure.
- Mobile Units:Trailer-mounted emergency response and temporary industrial supply systems.
- Modular Plants:Standardized process trains for capacity expansion and phased investment.
Established installed base remains on-premise. Greenfield specification is concentrating in plug & play systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta industrial corridor concentrates membrane filtration demand as textile and electronics manufacturers face tightening discharge rules. German municipalities drive European upgrade cycles under revised EU Drinking Water Directive mandates. Saudi Arabia's coastal desalination projects anchor Middle Eastern contract values.
China
Shandong and Jiangsu provinces redirect capital toward electrochemical desalination as MEE dual carbon enforcement restricts thermal expansion along the Bohai Rim. Provincial emissions audits force industrial clusters toward membrane bioreactor installations. The Yangtze River Delta textile corridor scales zero-liquid-discharge configurations to meet tightening discharge standards.
Germany
Rhineland chemical parks retrofit biological nutrient removal with advanced oxidation stages under REACH chemical restriction cascades. Municipal utilities upgrade legacy coagulation-filtration trains to comply with revised EU Drinking Water Directive standards. The Ruhr industrial basin sees concentrated tertiary treatment investment for legacy contaminant destruction.
Saudi Arabia
Red Sea and Persian Gulf desalination projects deploy solar power purchase agreement structures to bypass traditional utility tariffs. Developers contract directly with renewable farm operators for behind-the-meter supply. Coastal membrane plants concentrate margin pools through long operational tenors and high contract values.
United States
Ohio River Valley utilities consolidate granular activated carbon procurement through inter-municipal purchasing cooperatives ahead of EPA PFAS maximum contaminant level rules. Southeast aquifer regions face residual management complexity as spent carbon regeneration facilities confront air emissions permitting. California coastal projects encounter extended timelines due to evolving marine ecosystem impact assessments for brine outfalls.
Australia
Murray-Darling Basin agricultural irrigation drives UV disinfection specification where chlorine residual limits constrain chemical alternatives. Pilbara iron ore region mining camps specify containerized reverse osmosis skids with 90-day commissioning windows. Nodal electricity market pricing enables demand response revenue stacking that offsets baseline membrane plant energy costs.
Global Water Treatment Technology Market Competitive Landscape
European producers anchor one tier; Japanese specialists hold membrane substrate supply concentration. The vendor base separates into integrated chemical-service operators, membrane chemistry leaders, and regional equipment fabricators. Three archetypes dominate: recurring revenue platforms, technology risk transfer specialists, and feedstock-integrated substrate suppliers. Consolidation concentrates around membrane replacement part cycles and desalination contract bundling.
Within the integrated service tier, Ecolab Inc. and Veolia Environnement exemplify recurring revenue models that bundle chemical supply with operational contracts. DuPont de Nemours occupies a position representing membrane chemistry leadership in reverse osmosis applications. These three anchors demonstrate how platform breadth creates certification complexity advantages over point-solution specialists when fragmented national standards for emerging contaminants proliferate.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Pentair plc |
| Veolia Environnement |
| DuPont de Nemours |
| Kurita Water Industries |
| SUEZ Water Technologies |
| Evoqua Water Technologies |
| BASF SE |
| Xylem Inc. |
| Others |
Supply & Pricing Matrix
Membrane chemistry tier divergence between polyethersulfone substrates and commodity polyvinylidene fluoride alternatives shapes both procurement premiums and raw material sourcing strategies across module fabricators. This bifurcation concentrates margin capture with Japanese and German chemical conglomerates while compressing pricing power for downstream system integrators facing feedstock allocation risk during petrochemical cycle tightness.
Pricing Analysis
Volume-heavy municipal utility contracts trade margin for installed base expansion, while desalination project bundling commands premium pricing through long operational tenors and technology risk transfer clauses. Price differentiation rests on membrane replacement part cycles and EPA PFAS-compliant certification tiers, with small and medium utilities in the Ohio River Valley consolidating procurement through inter-municipal cooperatives to offset cost compression. Pricing pressure intensifies in hollow-fiber ultrafiltration modules as the 2015-2020 installation wave enters scheduled replacement, forcing module suppliers toward rental-lease-operate structures. Industrial end-users in China's Yangtze River Delta exhibit highest price sensitivity due to zero-liquid-discharge mandate compliance costs, whereas Saudi coastal developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale membrane replacement demand, while equipment vendors in Chile's Atacama and Australia's Pilbara specify containerized skids through rental-lease-operate structures. Geographic supply concentration centers on Japan and Germany for polyethersulfone and polyvinylidene fluoride substrates, with Chinese electrochemical desalination component fabrication expanding under MEE dual carbon enforcement. Raw material dependencies draw from phosphonate antiscalant chemistries, acrylic acid derivatives, and high-purity membrane cleaning formulations tracking energy-intensive acrylonitrile feedstock markets. Single-source vulnerability in specialty polymer production exposes module fabricators to allocation risk during petrochemical cycle tightness. Distribution runs through regional equipment fabricators serving municipal utilities, industrial clusters, and desalination developers with integrated chemical-service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restriction cascades and EPA PFAS maximum contaminant level rules erect compliance moats that favor multi-technology platform providers with parallel quality management systems over point-solution specialists lacking certification breadth.
For Market Incumbents: Deepen backward integration into membrane substrate production to offset Japanese and German chemical conglomerate feedstock allocation risk, while expanding remote monitoring platform deployment to capture recurring service revenue from distributed rural assets. Consolidate position in hollow-fiber ultrafiltration replacement cycles through long-term operational contracts with São Paulo, Jeddah, and Singapore utilities. Prioritize certification investment spanning EPA guidance documents and WHO drinking water quality guidelines to defend against emerging entrant price competition in fragmented national standards environments. For New Entrants and Emerging Players: Small and medium utilities in the US Southeast aquifer regions represent an underserved buyer archetype lacking volume pricing power for EPA PFAS-compliant granular activated carbon systems. India's textile dyeing clusters in Tiruppur and Surat offer penetrable zero-liquid-discharge demand exceeding current electrodialysis reversal capacity. Target containerized reverse osmosis rental-lease-operate structures for mining camp applications in water-scarce regions, leveraging 90-day commissioning windows against 18-month conventional build timelines. For Investors and Strategic Acquirers: Re-rating potential sits with integrated chemical-service operators given recurring revenue visibility from membrane replacement part cycles and desalination contract bundling. Long-term viability favors platform providers with certification complexity advantages across fragmented national standards for emerging contaminants. Monitor EPA PFAS rule implementation timelines and EU Green Deal circular water economy incentive uptake as inflection indicators for industrial symbiosis project finance structures qualifying for green bond certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrates | Captive supply of polyethersulfone reduces exposure to Japanese and German chemical conglomerate allocation decisions. |
| Remote Monitoring Platform Deployment | Cloud-based fouling prediction enables distributed rural asset staffing models across India's textile clusters. |
| Long-term Desalination Contract Bundling | Saudi Red Sea and Persian Gulf projects concentrate margin pools through solar PPA-backed operational tenors. |
| Zero-Liquid-Discharge Capacity Expansion | Tiruppur and Surat textile clusters face Central Pollution Control Board mandates exceeding installed electrodialysis reversal capacity. |
| Green Bond Certification Qualification | EU Green Deal circular water economy incentives reward industrial symbiosis schemes in Flanders and Catalonia parks. |
Research Methodology
Trade databases, SEC filings, and MEE provincial emissions audit records formed the secondary backbone, supplemented by customs data tracking membrane module imports and WHO drinking water quality guideline documentation. Primary interviews with municipal utility procurement directors, membrane module fabrication plant managers, EPC contractors specializing in desalination, and chemical-service operational contract managers validated demand assumptions. Bottom-up and top-down triangulation cross-checked installed base replacement cycle timing against capital expenditure disclosures from water utilities across São Paulo, Jeddah, and Singapore.
Bottom-up modeling aggregated technology-specific procurement patterns across membrane filtration, UV disinfection, ion exchange, and electrochemical treatment segments, while top-down analysis calibrated aggregate market expansion against regulatory enforcement intensity in REACH jurisdictions and MEE dual carbon audit provinces. Segmentation dimensions spanned technology chemistry tiers, application end-uses from municipal supply through wastewater recycling, deployment type from on-premise through plug-and-play systems, and regional regulatory clusters. CAGRs derived from regression analysis of historical capital expenditure cycles projected across the analysis window, incorporating membrane replacement part cycle timing and brine disposal permitting timeline assumptions.
Revisions become necessary when EPA PFAS maximum contaminant level rule implementation delays, REACH chemical restriction cascade enforcement variations, or MEE dual carbon audit intensity shifts materialize. Forecasts reflect assumptions regarding specialty polymer supply concentration persistence, renewable energy PPA pricing trajectory, and inter-municipal purchasing cooperative consolidation momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Liquid Waste Container Market