
 EV Powertrain Market | 2026-2036
EV Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
EV Powertrain Market Intelligence
Multi-source supplier arrangements for electric motors and inverters are repositioning how OEMs manage cost and IP control. Tesla, Inc. sustains captive production of its integrated motor-inverter systems across Gigafactory sites. Bosch Mobility leverages its tier-one scale to supply modular e-axle platforms to multiple European and Asian automakers. BYD Co. Ltd. anchors its competitive stance through backward integration into battery cells and permanent-magnet motor manufacturing.
An EV powertrain comprises the integrated assembly of electric motor, power electronics inverter, reduction transmission, and thermal management hardware that converts stored electrical energy into mechanical propulsion, typically operating at DC bus voltages between 400V and 800V with peak system efficiencies exceeding 90 percent. The battery pack segment commands the largest value share within component breakdowns due to raw material intensity and cell-level engineering complexity. Passenger cars dominate vehicle type demand, though commercial vehicles represent the fastest-expanding application as logistics operators electrify last-mile and regional-haul duty cycles. Power output stratification above 300 kW is gaining traction in premium performance and heavy-duty platforms where torque density requirements intensify.
The EPA tailpipe standards and EU Green Deal carbon benchmarks are forcing OEM product planners to accelerate powertrain electrification timelines and retool assembly capacity. China's MIIT new-energy vehicle mandates and dual carbon goals reinforce domestic demand for locally manufactured motor and inverter supply chains. NHTSA fuel economy rules and the IRA domestic content provisions in the United States are reshaping where suppliers locate motor winding and power module packaging operations. Stakeholders must monitor how regional content thresholds and carbon border adjustments alter sourcing economics for rare-earth magnet materials and silicon carbide semiconductors.
Market Dynamics
Silicon carbide power modules are compressing inverter footprints while elevating thermal ceilings, forcing incumbent suppliers to retool semiconductor packaging lines or cede share to vertically integrated OEMs. This single technology vector is redrawing competitive boundaries across motor-inverter integration tiers.
Growth Catalysts
- EPA tailpipe standards:The agency's fleet-average emissions benchmarks compel Detroit and European transplant OEMs to accelerate battery-electric powertrain rollouts across light-truck and SUV nameplates.
- Last-mile logistics electrification:Parcel and grocery delivery fleets in Germany, the Netherlands, and California are procuring integrated e-axle platforms to compress total cost of ownership against diesel equivalents.
- 800V DC architectures:Higher-voltage bus designs reduce copper mass in traction motors and enable faster DC fast-charging, reshaping thermal management hardware specifications.
Market Restraints
- Rare-earth magnet concentration:Neodymium-dysprosium supply chains concentrate in Chinese refining and magnet sintering operations, exposing motor manufacturers to export quota volatility.
- Silicon carbide wafer scarcity:Substrate ingot capacity for power modules remains bottlenecked at two merchant suppliers, inflating inverter bill-of-materials.
- IRA domestic content thresholds:The act's assembly and mineral sourcing rules disqualify powertrains with non-compliant battery cells from consumer tax credits, constraining sourcing flexibility.
Strategic Opportunities
- India's PLI scheme for auto:The production-linked incentive program for advanced chemistry cell and component manufacturing is attracting motor winding and power module packaging investments.
- Construction equipment electrification:Excavator and wheel-loader OEMs are specifying 300+ kW integrated drivetrains for urban job sites with noise and emissions restrictions.
- Wireless power transfer convergence:Inductive charging pad infrastructure paired with onboard receiver coils is enabling opportunity-charging for transit and depot-based fleets.
Industry Challenges
- Power electronics talent scarcity:Motor control firmware and wide-bandgap semiconductor packaging expertise pools remain shallow relative to hiring demand across OEM and tier-one engineering centers.
- Functional safety certification timelines:ISO 26262 ASIL-D validation for inverter control loops extends development schedules by 12-18 months versus prior-generation hardware.
- Legacy vehicle platform integration:Retrofitting skateboard battery architectures and central-drive motors into internal-combustion vehicle structures demands structural redesign rather than component substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Powertrain Market |
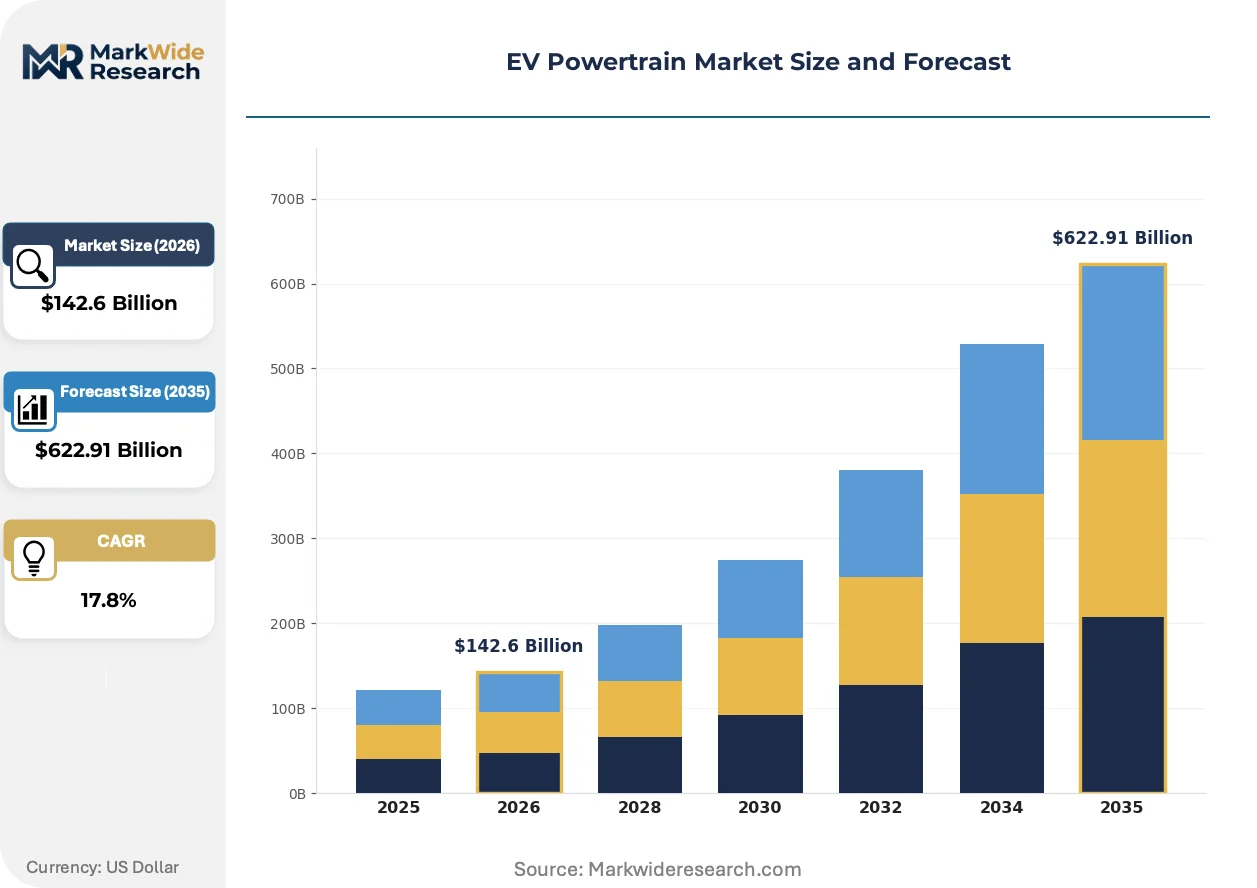
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $622.91 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Electric Motor, Inverter, Transmission, Battery Pack, DC-DC Converter, Onboard Charger Power Output: Below 100 kW, 100-200 kW, 201-300 kW, Above 300 kW Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Three-Wheelers, Off-Road Vehicles End User: OEM Manufacturers, Aftermarket Suppliers, Fleet Operators, Mobility Service Providers |
| Companies Covered | Tesla, Inc., BYD Co. Ltd., Bosch Mobility, Magna International Inc., BorgWarner Inc., ZF Friedrichshafen AG, Dana Incorporated, Continental AG, Vitesco Technologies Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Powertrain Market Strategic Shifts & Innovations
Electrification is fragmenting the traditional tier-one supply hierarchy as OEMs internalize motor and inverter competencies. Three concurrent developments are compressing development cycles and reshaping procurement patterns.
Hairpin winding technology for stator construction is decentralizing manufacturing footprints relative to conventional round-wire methods. Tier-one motor suppliers in Germany and Japan are licensing continuous-hairpin forming equipment to regional plants in Mexico and Hungary. This process shift enables localized production without shipping wound stator cores across oceans, compressing logistics costs and customs exposure.
The EU Green Deal's carbon border adjustment mechanism is tightening embodied-carbon accounting for imported steel and aluminum used in motor housings and transmission casings. European OEMs are now requiring mill certificates documenting blast-furnace versus electric-arc production routes. Suppliers with scrap-based aluminum casting operations in Spain and Italy are gaining preferential qualification status.
Fleet operators are unbundling powertrain procurement from vehicle acquisition, signing separate service contracts for battery state-of-health management and motor-inverter refurbishment. This financing innovation is most visible in California and Germany, where logistics companies lease drivetrain hardware while owning cab-and-chassis assets, shifting residual risk to component suppliers.
EV Powertrain Market Segmentation
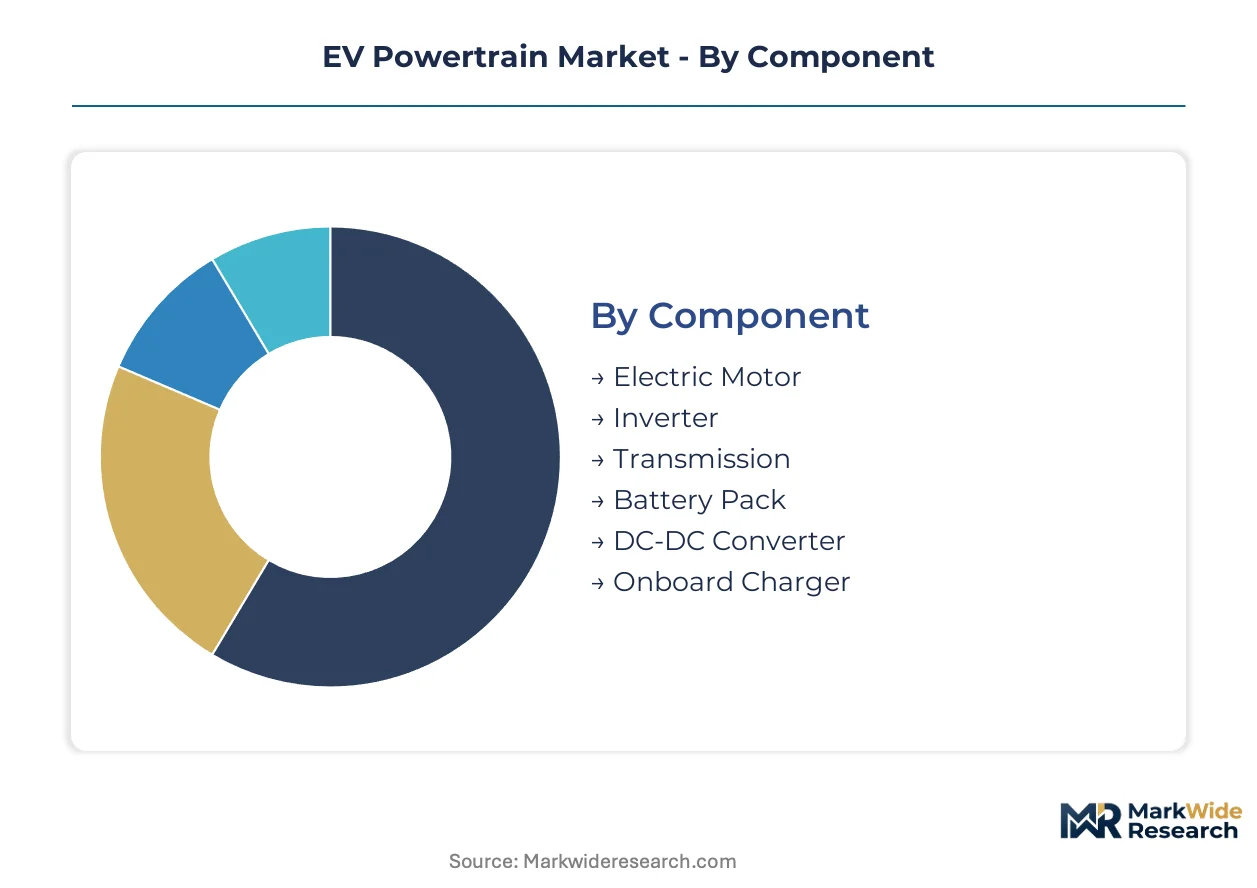
Powertrain component sourcing and integration strategies diverge sharply across vehicle architectures and duty cycles. Certification requirements from NHTSA, EU Green Deal carbon benchmarks, and China's MIIT new-energy vehicle mandates create tiered compliance burdens that reshape supplier qualification timelines and regional manufacturing footprints.
Component:
ISO 26262 ASIL-D functional safety certification applies differentially across powertrain subsystems, with inverter control loops and battery management systems facing the longest validation cycles while transmission and thermal hardware navigate shorter homologation paths.
- Battery Pack:The cell-to-pack architecture integrates thermal management and structural enclosure, commanding the highest bill-of-materials intensity across the powertrain. Demand concentrates in China, Germany, and the United States where IRA domestic content provisions and EU Green Deal carbon border adjustments are forcing cell-level localization investments.
- Electric Motor:Permanent-magnet synchronous designs utilizing neodymium-iron-boron rotors deliver torque density above 15 Nm/kg, though rare-earth supply concentration in Chinese refining operations exposes OEMs to export quota volatility. Motor winding operations are relocating to Mexico and Hungary to satisfy regional content thresholds.
- Inverter:Silicon carbide power modules enable 800V DC bus operation with switching frequencies exceeding 20 kHz.
- Transmission:Single-speed reduction gearsets with helical or planetary configurations dominate passenger applications.
- DC-DC Converter:Bidirectional architectures support vehicle-to-load functionality for construction and emergency service vehicles.
- Onboard Charger:11-22 kW AC charging units face EMC certification variance between FCC Part 15 and CISPR 25 jurisdictions.
Leading the category by volume: Battery Pack. Expanding most quickly: Silicon carbide-based Inverter platforms.
Power Output:
Cost tiers stratify sharply across output bands, with below-100 kW systems competing on manufacturing scale while above-300 kW platforms command engineering premiums for torque density and thermal endurance.
- Below 100 kW:Compact permanent-magnet motors with air-cooled inverters serve urban two-wheelers and entry-level passenger cars. Procurement concentrates in India and Southeast Asia where PLI scheme incentives attract motor winding investments for domestic two-wheeler OEMs.
- Above 300 kW:Liquid-cooled hairpin stator designs with direct oil-spray rotor cooling enable continuous operation above 500 Nm for heavy-duty trucks and performance SUVs. Demand clusters in Germany's autobahn-capable premium segment and North American full-size pickup electrification programs.
- 100-200 kW:The volume heartland of C-segment passenger cars and mid-size commercial vans.
- 201-300 kW:Premium sedans and regional-haul delivery trucks specify this band for 0-100 km/h acceleration targets.
Highest shipment volumes: Below 100 kW. Steepest expansion trajectory: Above 300 kW for commercial and performance applications.
Vehicle Type:
Application-specific duty cycles dictate thermal management architecture and power electronics durability requirements, with commercial platforms facing 3-5x higher annual mileage stress than passenger equivalents.
- Passenger Cars:Integrated e-axle modules combining motor, inverter, and reduction gear into a single housing dominate platform engineering. Battery-electric architectures from Tesla, Volkswagen Group, and BYD anchor volume demand across China, Germany, and California regulatory jurisdictions.
- Commercial Vehicles:Last-mile delivery vans and regional-haul trucks specify 150-250 kW e-axle platforms with regenerative braking energy recovery above 70%. Fleet operators in the Netherlands, California, and the United Kingdom are procuring integrated drivetrains under separate service contracts to compress total cost of ownership.
- Two-Wheelers:Hub-mounted direct-drive motors eliminate transmission complexity for Southeast Asian and Indian urban mobility.
- Three-Wheelers:Cargo and passenger auto-rickshaw electrification accelerates in India under FAME subsidy extensions.
- Off-Road Vehicles:Mining haul trucks and agricultural tractors demand 400+ kW continuous ratings with IP6K9K environmental sealing.
Dominant by unit volume: Passenger Cars. Gaining share fastest: Commercial Vehicles under fleet electrification mandates.
End User:
Customer type determines procurement modality, with OEM captive production competing against tier-one supply contracts and emerging powertrain-as-a-service financing structures.
- OEM Manufacturers:Vertically integrated powertrain design preserves IP control over motor-inverter calibration and thermal management software. Tesla sustains captive production across Gigafactory sites while legacy OEMs hybridize between in-house motor winding and outsourced power module packaging.
- Fleet Operators:Logistics companies in Germany and California are unbundling drivetrain procurement from vehicle acquisition, leasing battery and motor-inverter hardware while owning cab-and-chassis assets. This shifts residual value risk to component suppliers and enables battery state-of-health service contracts.
- Aftermarket Suppliers:Remanufactured inverter control boards and refurbished battery modules serve vehicle life extension markets.
- Mobility Service Providers:Ride-hail and car-share fleets prioritize swappable battery architectures with standardized powertrain interfaces.
Largest procurement volume: OEM Manufacturers. Fastest-growing engagement model: Fleet Operators adopting powertrain-as-a-service structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet refining capacity in Inner Mongolia anchors China's grip on permanent-motor supply chains. This geological concentration forces OEMs across three continents to secure alternative magnet formulations or accept sourcing exposure.
China
Domestic demand for integrated e-axle platforms absorbs over half of global battery cell output through 2035. MIIT new-energy vehicle mandates and dual carbon goals reinforce captive supply chain requirements for locally manufactured motors and inverters. The Yangtze River Delta cluster around Shanghai hosts Gigafactory-scale motor winding operations serving BYD and Tesla captive production.
Germany
Premium OEMs specify 300+ kW powertrains for autobahn-capable performance SUVs and heavy-duty commercial platforms. EU Green Deal carbon border adjustments tighten embodied-carbon accounting for imported steel and aluminum in motor housings. The Stuttgart-Munich corridor concentrates hairpin winding equipment licensing from Bosch Mobility to tier-one motor suppliers.
United States
Full-size pickup electrification programs and last-mile logistics fleets drive procurement of 150-250 kW integrated drivetrains. IRA domestic content provisions disqualify powertrains with non-compliant battery cells from consumer tax credits, forcing cell-level localization. Michigan and Tennessee assembly plants retool for motor-inverter integration under NHTSA fuel economy compliance timelines.
India
Two-wheeler and three-wheeler electrification accelerates under FAME subsidy extensions and PLI scheme incentives for advanced chemistry cell manufacturing. The country's national automotive regulator mandates localized component sourcing for subsidy eligibility. Gujarat and Tamil Nadu industrial corridors attract motor winding and power module packaging investments from tier-one suppliers.
Japan
Automotive OEMs hybridize between in-house motor design and outsourced silicon carbide power module packaging. METI industrial policy supports rare-earth magnet recycling and alternative ferrite motor research to reduce Chinese supply dependence. The Nagoya-Toyota industrial zone maintains concentrated expertise in motor control firmware and ASIL-D functional safety validation.
EV Powertrain Market Key Industry Players
Capacity expansion dominates the current landscape as suppliers retool semiconductor packaging lines for silicon carbide power modules. The vendor base stratifies across three tiers: vertically integrated OEMs preserving IP control, tier-one scale suppliers offering modular e-axle platforms, and specialized component manufacturers focusing on narrow technology vectors. Two competitive moves define positioning: backward integration into battery cell and magnet supply chains, and geographic relocation of motor winding operations to satisfy regional content thresholds.
Within the vertically integrated tier, Tesla, Inc. and BYD Co. Ltd. exemplify the archetype of captive production across Gigafactory-scale sites, controlling motor-inverter calibration and thermal management software in-house. Among tier-one scale suppliers, Bosch Mobility occupies a position representing modular platform supply to multiple automakers, leveraging established tier-one relationships and continuous-hairpin forming equipment licensing to regional plants.
| Leading Market Players |
|---|
| Tesla, Inc. |
| BYD Co. Ltd. |
| Bosch Mobility |
| Magna International Inc. |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Dana Incorporated |
| Continental AG |
| Vitesco Technologies Group AG |
| Others |
Cost & Logistics Intelligence
Fleet operators procuring integrated e-axle platforms under powertrain-as-a-service contracts are compressing upfront capital outlays while shifting residual value risk to component suppliers, embedding lifecycle service pricing into hardware procurement decisions.
Pricing Analysis
Warranty and service bundling separates captive OEM supply arrangements from tier-one modular platform sales, with the former including predictive maintenance software and battery state-of-health guarantees while the latter unbundles refurbishment obligations. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 ASIL-D certification grade and volume scale commitments. Cost compression in below-100 kW systems is intensifying because of manufacturing scale competition in India and Southeast Asia. Fleet operators represent the most price-sensitive buyer segment, while premium OEMs purchasing 300+ kW platforms exhibit lowest sensitivity due to torque density requirements.
Supply Chain Analysis
ISO 26262 ASIL-D functional safety certification gates supplier qualification timelines, extending motor-inverter integration development cycles by 12-18 months versus uncertified hardware. Manufacturing concentrates in China, Germany, and the United States where IRA domestic content provisions and EU Green Deal carbon border adjustments force cell-level localization. The supply chain draws from rare-earth magnet refining in Inner Mongolia, silicon carbide wafer production in Japan and Germany, and copper winding operations relocating to Mexico and Hungary. Single-source vulnerability in silicon carbide substrate ingot capacity exposes inverter manufacturers to supply rationing. Distribution runs through tier-one platform suppliers to OEM assembly plants and direct captive production at Gigafactory-scale sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV powertrain market is a vertical-integration race where control over silicon carbide semiconductor packaging and rare-earth magnet supply chains determines margin capture and sourcing security.
For Market Incumbents: Acquire silicon carbide wafer processing capabilities to secure power module supply against merchant substrate bottlenecks. Incumbents must also lock in long-term offtake agreements for neodymium-dysprosium magnet materials before export quota volatility disrupts motor production. Emerging OEM captive production threatens tier-one market share in integrated e-axle platforms. For New Entrants and Emerging Players: Regional commercial fleet operators in India and Southeast Asia present the most penetrable buyer archetype for sub-100 kW motor-inverter systems. New entrants should target construction equipment electrification specifying 300+ kW drivetrains for urban noise-restricted job sites. A licensing-based go-to-market angle for continuous-hairpin winding equipment reduces capital intensity versus manufacturing scale plays. For Investors and Strategic Acquirers: The window for entry favors specialized component manufacturers with silicon carbide packaging expertise or alternative ferrite motor research programs. Long-term viability hinges on securing positions ahead of carbon border adjustment mechanism enforcement tightening embodied-carbon accounting. The signal to watch is IRA domestic content threshold recalibration affecting subsidy eligibility for imported battery cells.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Enables 800V architectures that reduce copper mass and accelerate DC fast-charging speeds. |
| Rare-Earth Magnet Recycling Investment | Reduces Chinese supply dependence through METI-supported alternative ferrite motor research programs. |
| Hairpin Winding Equipment Licensing | Decentralizes manufacturing footprints to Mexico and Hungary, compressing logistics costs and customs exposure. |
| Battery State-of-Health Service Contracts | Shifts residual value risk from fleet operators to component suppliers under powertrain-as-a-service structures. |
| Regional Content Threshold Compliance | Qualifies powertrains for IRA consumer tax credits and EU Green Deal carbon border adjustment preferences. |
Research Approach
Independent corroboration across OEM platform engineering directors, tier-one supplier procurement leads, fleet operator logistics managers, and silicon carbide semiconductor packaging specialists underwrites the qualitative findings. Primary interviews with motor control firmware engineers and thermal management hardware designers combined with secondary validation from NHTSA fuel economy rulemakings, EPA tailpipe standard filings, EU Green Deal carbon benchmark disclosures, and MIIT new-energy vehicle mandate documentation established demand-side parameters. Bottom-up bill-of-materials analysis across battery pack, electric motor, and inverter subsystems triangulated against top-down OEM production planning data.
Comparable-period anchoring to historical vehicle electrification program timelines informed the projection horizon across passenger car, commercial vehicle, and off-road equipment segments. The analytical framework modeled power output stratification, component integration tiers, and regional regulatory cluster effects throughout the forecast period. CAGRs derived from shipment volume trajectories weighted by battery cell capacity expansion announcements and motor winding facility investments. Forecast inputs included silicon carbide power module adoption curves and rare-earth magnet price volatility indices.
Revisions become necessary when IRA domestic content threshold recalibrations, EU carbon border adjustment mechanism enforcement dates, or Chinese rare-earth export quota policy shifts materialize. Forecasts reflect assumptions regarding continued MIIT mandate enforcement and NHTSA fuel economy compliance timeline adherence. A model refresh is warranted upon material change in silicon carbide substrate ingot capacity expansion timelines or alternative ferrite motor technology readiness levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Crankshaft Oil Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
LNG Engine Market
Powertrain
Yaw Damper Market
Powertrain
Clutch Friction Plate Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Engine Tuner Market
Powertrain
Natural Gas Engines Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Gas Engine Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Internal Combustion Engine Market