
 Clutch Market | 2026-2036
Clutch Market Size, Share, and Industry Trends Forecast 2026-2036
Clutch Market Analysis
Aftermarket service revenue is fragmenting across regional distributor networks as clutch replacement intervals lengthen with improved friction materials. ZF Friedrichshafen AG leverages its integrated transmission-clutch systems to capture platform-level contracts with European commercial vehicle builders. BorgWarner Inc. competes through advanced thermal management in high-torque applications, while Schaeffler AG anchors its position via precision bearing-clutch module combinations that reduce assembly complexity for OEM customers.
A clutch is a mechanical coupling device that transmits torque from a driving shaft to a driven shaft through frictional engagement, typically incorporating friction plates, pressure assemblies, and release mechanisms engineered to withstand surface temperatures exceeding 300°C during engagement cycles. Friction clutches occupy the largest volume share due to their cost efficiency in internal combustion powertrains, while electronic clutches represent the fastest-expanding segment as electrified architectures demand precise torque modulation without mechanical linkages. The automotive application segment sustains dominant demand, though industrial machinery procurement generates higher per-unit margins through custom-engineered pneumatic and hydraulic configurations.
The EPA enforces particulate and greenhouse gas standards that compel clutch-integrated powertrain efficiency gains, while NHTSA safety regulations mandate reliability testing for friction material degradation under thermal stress. EMA and REACH frameworks in Europe restrict hazardous substance content in friction linings, redirecting formulation investments toward ceramic and carbon-based composites. Stakeholders must monitor powertrain electrification timelines and corresponding clutch content reduction in battery-electric platforms while positioning for hybrid residual demand and industrial aftermarket longevity.
Market Dynamics
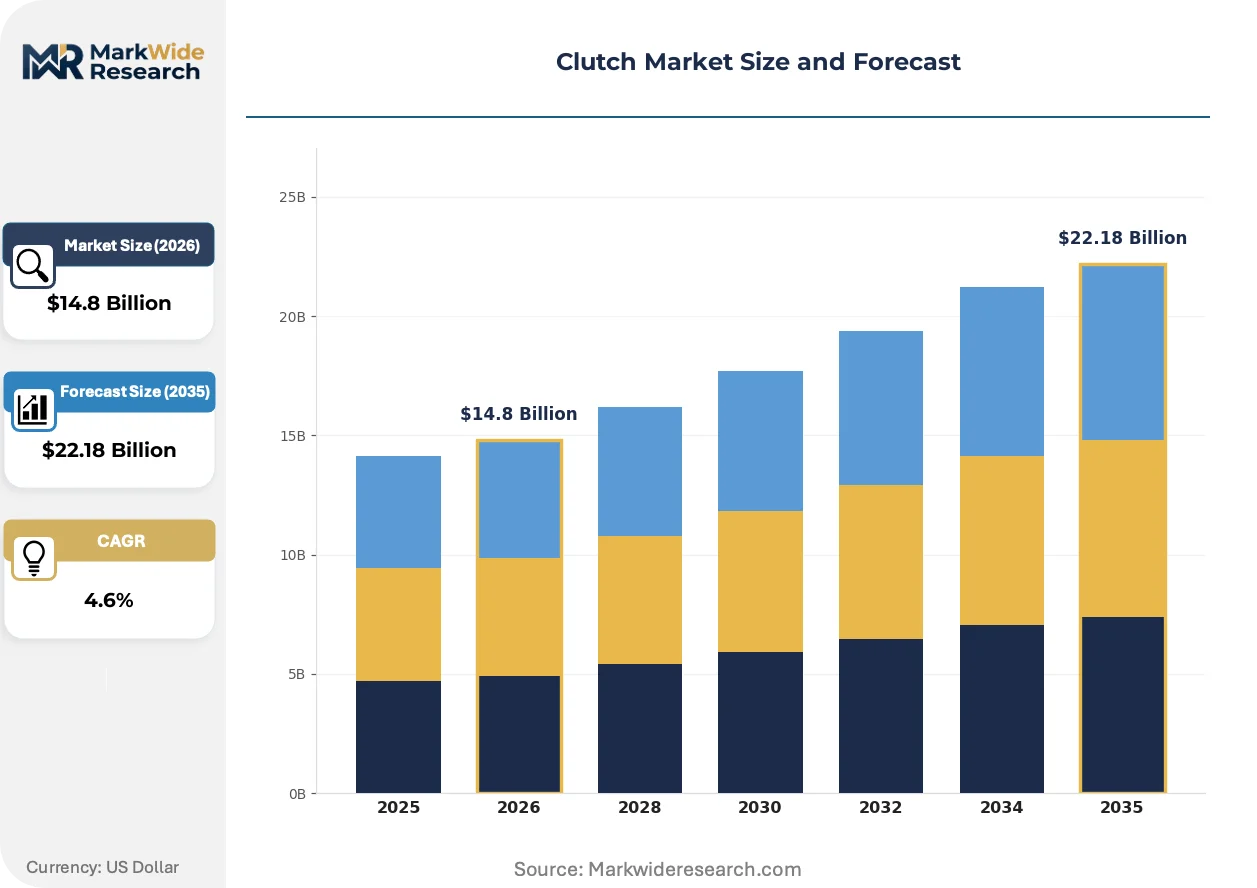
Powertrain electrification timelines are compressing clutch content per vehicle while simultaneously extending replacement cycles through advanced friction formulations, forcing suppliers to pivot toward hybrid residual demand and industrial aftermarket longevity.
Growth Catalysts
- EPA emissions benchmarks:These standards accelerate dual-clutch transmission redesigns that integrate higher-efficiency clutch modules for commercial vehicle compliance.
- Ceramic friction composites:REACH and EMA restrictions on hazardous substances redirect formulation investments toward carbon-based alternatives with superior thermal durability.
- Asia-Pacific logistics corridors:Fleet operators across eastern China manufacturing belts are expanding replacement cycles, anchoring regional procurement concentration.
Market Restraints
- Copper and rare earth input volatility:Friction lining formulations depend on concentrated mineral supply chains subject to export restriction regimes.
- Single-source bearing supply:Precision clutch module assembly relies on concentrated German and Japanese bearing manufacturers.
- Battery-electric powertrain substitution:Pure electric architectures eliminate mechanical torque coupling entirely, removing clutch content from vehicle platforms.
Strategic Opportunities
- India commercial vehicle retrofit:BIS certification pathways and PLI scheme incentives create accessible aftermarket expansion for friction material suppliers.
- Pneumatic-hydraulic industrial configurations:Custom-engineered clutch systems for mining and construction machinery generate higher per-unit margins than automotive volumes.
- Dual-clutch thermal management convergence:Integration of advanced cooling architectures with electronic control modules opens platform-level contract positioning.
Industry Challenges
- Tribology specialist scarcity:Friction material formulation requires expertise in surface engineering and thermal degradation modeling that outpaces technical education pipelines.
- Euro 7 certification timelines:Powertrain redesign validation cycles compress development windows for integrated transmission-clutch systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clutch Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Friction Clutches, Hydraulic Clutches, Pneumatic Clutches, Electronic Clutches Material: Fabric, Steel, Carbon, Aluminum Application: Automotive, Aerospace, Marine, Industrial End User: OEMs, Aftermarket Providers, Fleet Operators, Manufacturers |
| Companies Covered | Exedy Corporation, Aisin Seiki Co., Ltd., ZF Friedrichshafen AG, FCC Co., Ltd., Eaton Corporation plc, BorgWarner Inc., Valeo S.A., Advanced Clutch Technology (ACT), Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clutch Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are actively reconfiguring competitive advantage in torque transmission, with thermal performance and electronic modulation emerging as the primary axes of differentiation.
Carbon-ceramic matrix friction materials are collapsing the traditional trade-off between engagement smoothness and heat dissipation capacity. High-torque commercial vehicle builders in Germany and Japan are adopting these composites for severe-duty applications. The technology is collapsing service interval expectations and forcing incumbent suppliers to reformulate product roadmaps.
REACH framework amendments restricting copper and asbestos alternatives in friction linings are mandating chemistry transitions across European supply chains. Formulation houses must validate new ceramic and aramid-based composites through ECHA notification procedures. Commercial vehicle friction suppliers face the steepest compliance burden given their higher thermal load profiles.
Fleet procurement departments are unbundling clutch replacement from full transmission service contracts. Large logistics operators in China's eastern manufacturing belt now source friction modules directly from tier-two suppliers, bypassing traditional OEM service networks. This pattern concentrates purchasing power among fleet managers and compresses distributor margins across aftermarket channels.
Clutch Market Segmentation
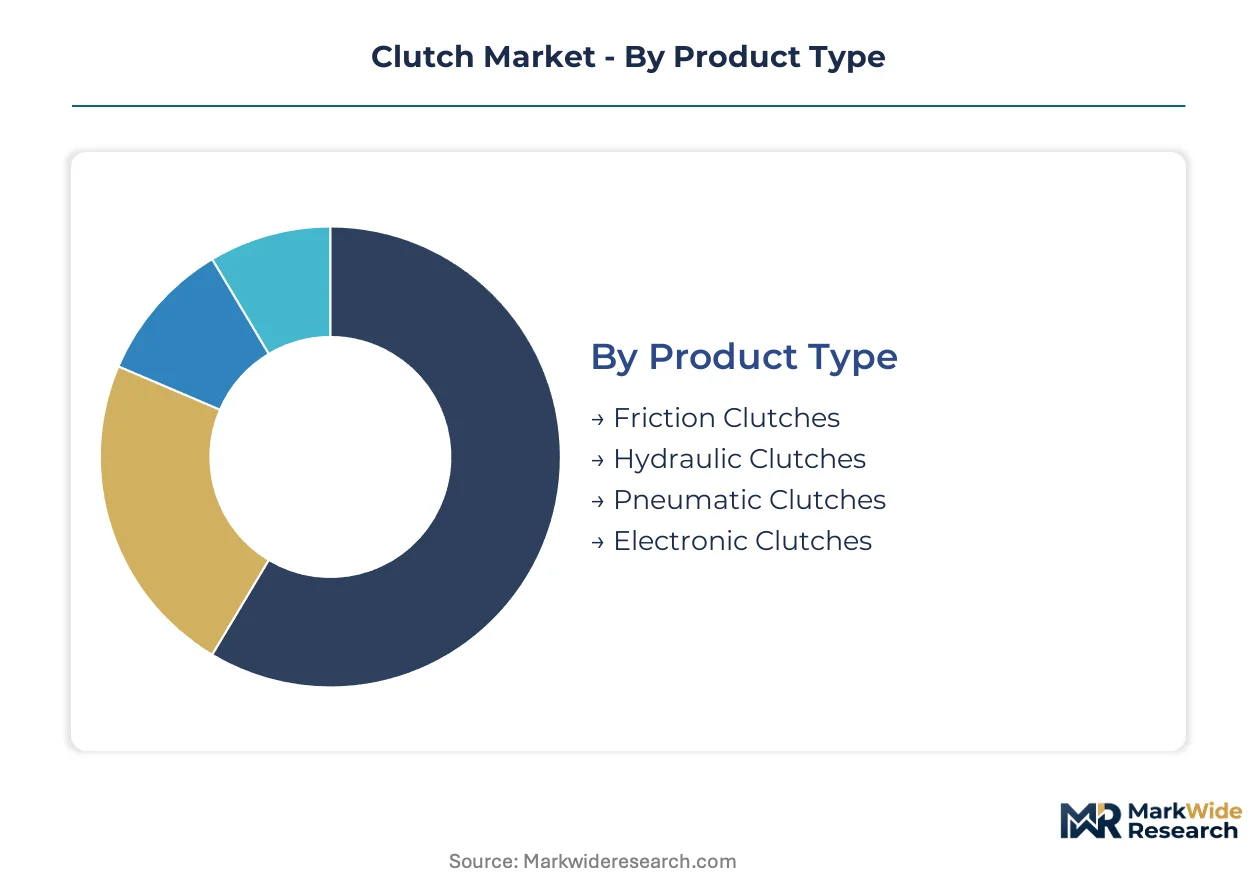
Clutch procurement patterns diverge sharply across product architectures and end-use contexts, with replacement cycles stretching to 500,000 kilometers for commercial friction units while electronic variants face obsolescence risk from powertrain electrification. Material composition and thermal load profiles dictate margin structures, separating commodity automotive volumes from precision-engineered industrial configurations.
Product Type:
Friction clutches turn over fastest in heavy-duty fleets, while electronic variants face the longest development cycles but shortest platform lifespans as electrification advances.
- Friction Clutches:Mechanical torque transmission through woven friction plates and pressure assemblies withstands surface temperatures exceeding 300°C during engagement. Demand concentrates in China's eastern manufacturing belt, where transmission assembly capacity anchors regional procurement for commercial vehicle builders facing Euro 7 compliance deadlines.
- Electronic Clutches:Electromagnetic actuation enables precise torque modulation without mechanical linkages, critical for hybrid powertrain architectures. German and Japanese OEMs dominate development, though battery-electric substitution threatens long-term installed base expansion.
- Hydraulic Clutches:Fluid-pressure engagement systems deliver smooth torque transfer for mining and construction machinery. Custom-engineered configurations generate higher per-unit margins than automotive volumes.
- Pneumatic Clutches:Compressed air actuation serves heavy industrial presses and marine propulsion systems. Fleet operators across Asia-Pacific logistics corridors specify these units for severe-duty replacement cycles.
Friction clutches dominate installed base. Electronic clutches are where expansion concentrates.
Material:
Cost tier stratification separates commodity steel formulations from premium carbon-ceramic composites commanding three-to-five-fold price multiples.
- Carbon:Carbon-ceramic matrix composites collapse the trade-off between engagement smoothness and heat dissipation capacity, withstanding thermal loads that degrade conventional materials. German commercial vehicle builders specify these for severe-duty applications, forcing incumbent suppliers to reformulate product roadmaps.
- Fabric:Woven aramid and glass fiber composites serve cost-sensitive automotive volumes, though REACH restrictions on copper and asbestos alternatives redirect European formulation investments.
- Steel:Laminated steel plates provide structural rigidity for multi-plate clutch assemblies in high-torque transmissions. Chinese foundries anchor global supply concentration.
- Aluminum:Lightweight housing and pressure plate materials reduce rotational inertia in passenger vehicle applications. Japanese precision metalworking clusters specialize in thin-wall casting techniques.
Fabric materials dominate installed base. Carbon composites are where expansion concentrates.
Application:
Volume-maturity mismatch positions automotive as the largest revenue pool while industrial machinery generates superior per-unit economics through custom engineering requirements.
- Automotive:Internal combustion and hybrid powertrains sustain dominant demand volume, though battery-electric substitution eliminates clutch content entirely from pure electric platforms. EPA emissions benchmarks accelerate dual-clutch transmission redesigns.
- Industrial:Mining, construction, and manufacturing machinery procurement generates higher per-unit margins through pneumatic and hydraulic configurations engineered to application-specific torque profiles.
- Aerospace:Aircraft auxiliary power units and rotorcraft transmissions demand certified friction materials with documented thermal degradation characteristics under FAA and EASA airworthiness protocols.
- Marine:Commercial vessel propulsion systems specify corrosion-resistant clutch modules for saltwater environments, with classification society approvals from Lloyd's Register and DNV governing procurement specifications.
Automotive applications dominate installed base. Industrial configurations are where expansion concentrates.
End User:
Procurement authority is shifting from OEM captive supply toward fleet direct sourcing, compressing traditional distributor margins.
- OEMs:Integrated transmission-clutch system contracts anchor platform-level supplier relationships, with ZF Friedrichshafen AG and BorgWarner Inc. competing through thermal management and electronic control convergence.
- Fleet Operators:Large logistics operators in China's eastern manufacturing belt now source friction modules directly from tier-two suppliers, bypassing traditional OEM service networks and concentrating purchasing power.
- Aftermarket Providers:Regional distributor networks fragment as replacement intervals lengthen with improved friction materials, forcing inventory rationalization across Asia-Pacific corridors.
- Manufacturers:Industrial machinery builders specify custom-engineered clutch systems with application-unique torque curves and engagement protocols.
OEM supply relationships dominate installed base. Fleet direct procurement is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Fleet operators in China negotiate aggressively on friction module unit costs. German commercial vehicle builders absorb premium pricing for carbon-ceramic thermal performance.
China
Logistics fleet operators across the eastern manufacturing belt extend replacement cycles to 500,000 kilometers, compressing aftermarket distributor margins. MIIT dual carbon goals accelerate hybrid powertrain adoption that sustains electronic clutch demand. Transmission assembly clusters in Shanghai and Jiangsu province anchor regional procurement concentration for domestic commercial vehicle builders.
Germany
Commercial vehicle builders specify carbon-ceramic composites for severe-duty thermal loads exceeding 300°C. KBA enforces Euro 7 powertrain validation timelines that compress integrated transmission-clutch development windows. Stuttgart and Munich engineering corridors concentrate precision bearing-clutch module assembly for European OEM platform contracts.
United States
Heavy-duty fleet procurement prioritizes EPA-compliant dual-clutch efficiency gains over unit cost minimization. NHTSA mandates reliability testing for friction material degradation under thermal stress. Detroit automotive clusters and Indiana transmission corridors sustain integrated system sourcing relationships with tier-one suppliers.
Japan
Premium passenger vehicle builders demand electronic clutch precision for hybrid torque modulation. METI industrial standards govern precision metalworking for thin-wall aluminum pressure plate casting. Nagoya and Tokyo-Yokohama manufacturing belts specialize in multi-plate clutch assemblies for high-torque applications.
India
Commercial vehicle retrofit demand accelerates as BIS certification pathways lower aftermarket entry barriers. PLI scheme incentives attract friction material suppliers to domestic production. Maharashtra and Gujarat industrial corridors concentrate foundry capacity for laminated steel plate fabrication serving regional transmission builders.
Clutch Market Vendor Landscape
Capability concentration sits with precision engineering specialists; scale advantage sits with integrated powertrain suppliers. The vendor base organizes into three tiers: transmission-system integrators capturing platform-level contracts, friction material formulators competing on thermal durability, and regional fabricators serving aftermarket price sensitivity. Consolidation pressure intensifies as electrification eliminates pure-play clutch content from battery-electric architectures. Dominant competitive moves include backward integration into bearing supply and geographic expansion through India PLI scheme localization.
Among integrated transmission-clutch system suppliers, ZF Friedrichshafen AG and BorgWarner Inc. occupy positions defined by thermal management convergence with electronic control modules. Schaeffler AG anchors the precision bearing-clutch module tier, exemplifying formulation-to-assembly integration that reduces OEM customer complexity. These three entities represent distinct competitive archetypes: platform-level system integration, advanced materials engineering, and precision component modularization.
| Leading Market Players |
|---|
| Exedy Corporation |
| Aisin Seiki Co., Ltd. |
| ZF Friedrichshafen AG |
| FCC Co., Ltd. |
| Eaton Corporation plc |
| BorgWarner Inc. |
| Valeo S.A. |
| Advanced Clutch Technology (ACT) |
| Schaeffler AG |
| Others |
Supply Flow & Price Mechanics
Copper and rare earth export restriction regimes in concentrated mineral supply chains determine both pricing tier spreads and supply chain shape across friction material formulations. Input volatility compresses margins at the commodity end while carbon-ceramic thermal performance commands premium multiples in severe-duty applications.
Pricing Analysis
Aftermarket service revenue from extended replacement cycles now drives lifetime value more than initial hardware sales. Three-tier pricing structure across premium carbon-ceramic, standard ceramic-composite, and economy fabric-based formulations separates German commercial vehicle builders from Chinese fleet operators. Pricing pressure stems from direct procurement by logistics operators bypassing traditional OEM service networks. Chinese fleet managers exhibit highest price sensitivity; German severe-duty builders absorb premium thermal performance costs.
Supply Chain Analysis
Precision bearing manufacturing concentrates at German and Japanese foundries serving clutch module assembly. Laminated steel plate fabrication draws from Chinese eastern manufacturing belt capacity; carbon-ceramic matrix composites rest on Japanese and German specialty materials houses. Single-source bearing dependency creates structural vulnerability for integrated transmission-clutch system suppliers. Distribution runs through tier-one automotive suppliers and direct fleet procurement channels fragmenting traditional aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Friction module replacement services and thermal management retrofit contracts expand faster than new vehicle hardware sales, positioning the market as a service-attach opportunity with recurring revenue layers anchored in fleet direct sourcing.
For Market Incumbents: Entrench platform-level supplier relationships through backward integration into precision bearing supply and carbon-ceramic formulation capacity. Battery-electric powertrain substitution threatens pure-play clutch content elimination; hybrid thermal management convergence offers defensive positioning. Prioritize certification investment for Euro 7 integrated transmission-clutch validation timelines. For New Entrants and Emerging Players: India's western industrial corridors present geographic underpenetration with BIS certification pathways and PLI scheme incentives lowering aftermarket entry barriers. Target commercial vehicle retrofit demand in Maharashtra and Gujarat foundry clusters. Pursue direct fleet procurement relationships bypassing established OEM service networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision component modularization specialists with formulation-to-assembly integration capabilities. Long-term viability hinges on hybrid residual demand and industrial aftermarket longevity rather than pure automotive volume exposure. Watch electronic clutch obsolescence risk from battery-electric platform acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Supply | Reduces single-source dependency for German and Japanese precision clutch module assembly. |
| Carbon-Ceramic Formulation Capacity Buildout | Captures premium thermal performance contracts with severe-duty commercial vehicle builders. |
| India PLI Scheme Localization | Positions friction material production for BIS-certified commercial vehicle retrofit expansion. |
| Direct Fleet Procurement Channel Development | Bypasses OEM service networks to capture logistics operator friction module sourcing. |
| Hybrid Thermal Management Convergence | Integrates electronic control modules with advanced cooling for platform-level contracts. |
Methodological Framework
Operator-level perspectives from fleet procurement managers, aftermarket service directors, OEM platform engineers, and friction material R&D leads anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, EPA emissions filings, KBA type-approval records, and MIIT dual carbon policy documents. Bottom-up clutch content per vehicle estimates triangulated against top-down transmission production forecasts.
Scenario-bracketing framed powertrain electrification timelines and hybrid residual demand curves across the projection horizon. Segmentation dimensions modeled include product architecture, material composition tier, application context, and end-user procurement authority. CAGRs derived from installed base turnover rates and replacement cycle extensions. Forecast inputs incorporated REACH chemical restriction timelines and Euro 7 certification windows.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric pure-play powertrain specialists or carbon-ceramic formulation entrants would shift outcomes. Quarterly review of fleet direct procurement penetration rates and friction material chemistry transition progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Japan Electrically Powered Hydraulic Steering Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Automotive TCU Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Global Powertrain Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Automotive Counter Shaft Market
Powertrain
Iridium Spark Plug Market
Powertrain
India Automotive Engine Oils Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Clutch Actuator Market