
 Engine Cylinder Liners Market | 2026-2036
Engine Cylinder Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Cylinder Liners Market Foresight
Asset-light leasing models for engine remanufacturing equipment is tilting competitive dynamics toward mid-tier suppliers that avoid heavy foundry capital. Mahle GmbH leverages captive casting networks across Germany and Mexico to sustain cost discipline in high-volume diesel liner production. Tenneco Inc. anchors its aftermarket position through direct distribution to independent repair chains in North America. Federal-Mogul Corporation differentiates via specialized coatings that extend liner life in severe-service mining applications.
Engine cylinder liners are cylindrical sleeves inserted into engine blocks to provide a wear-resistant running surface for pistons, typically manufactured from centrifugally cast grey iron with pearlitic microstructures and hardness ratings of 190-240 HB. Their primary purpose is to enable block repairability, reduce friction losses, and maintain compression integrity across millions of combustion cycles. Cast iron formulations continue to dominate material selection for heavy-duty diesel applications where thermal fatigue resistance commands premium positioning. Hybrid engine types represent the fastest-growing segment as automakers bridge thermal management demands between combustion and electrified powertrains. Machining-intensive finishing processes concentrate margin pools in precision honing and surface treatment subsystems rather than raw casting operations.
EPA emission mandates and NHTSA fuel economy standards in the United States compel liner manufacturers to reduce wall thickness while preserving structural durability under higher peak cylinder pressures. The EU Green Deal and REACH chemical restrictions in Europe are phasing out certain coating chemistries, redirecting R&D toward boron-nitride and diamond-like carbon alternatives. Stakeholders must monitor how ISO 9001 and IATF 16949 certification requirements evolve for composite liner entrants challenging incumbent metallurgy.
Market Dynamics
Commercial vehicle fleet operators are compressing cylinder liner replacement cycles as EPA and NHTSA emissions standards tighten across North America, forcing suppliers to engineer thinner-walled designs that withstand higher peak combustion pressures without sacrificing durability.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Heavy-duty truck OEMs in the United States are sourcing upgraded liner specifications to meet stricter NOx and particulate limits, expanding replacement part volumes through 2035.
- India's aging diesel fleet:BIS-certified cast iron liners dominate aftermarket demand as commercial vehicle parc expansion outpaces new engine sales in the heavy-duty segment.
- Hybrid thermal management requirements:Automakers bridging combustion and electrified powertrains are specifying liners with enhanced heat dissipation properties for stop-start engine cycles.
Market Restraints
- Scrap cast iron price volatility:Foundry input costs fluctuate with Chinese pig iron export tariffs, compressing margin predictability for centrifugal casting operations.
- EU REACH chemical restrictions:Phased elimination of chrome-based plating chemistries forces coating reformulation investments before boron-nitride alternatives achieve cost parity.
- Electrification substitution threat:Battery-electric powertrain adoption in urban delivery segments eliminates liner demand entirely for affected vehicle populations.
Strategic Opportunities
- Remanufacturing equipment leasing:Asset-light models allow mid-tier suppliers to access precision honing capacity without foundry capital deployment.
- Diamond-like carbon coating penetration:Mining and severe-service applications offer premium positioning for extended-life surface treatments that command price premiums over standard grey iron.
- Mexico nearshoring corridor:Captive casting networks serving North American OEMs benefit from USMCA rules of origin and reduced logistics exposure versus Asian supply routes.
Industry Challenges
- IATF 16949 certification timelines:Composite liner entrants face 18-24 month qualification periods to challenge incumbent metallurgy in OEM supply agreements.
- Precision honing skill scarcity:Machining-intensive finishing processes concentrate in aging workforce regions, constraining output scaling for surface treatment subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Cylinder Liners Market |
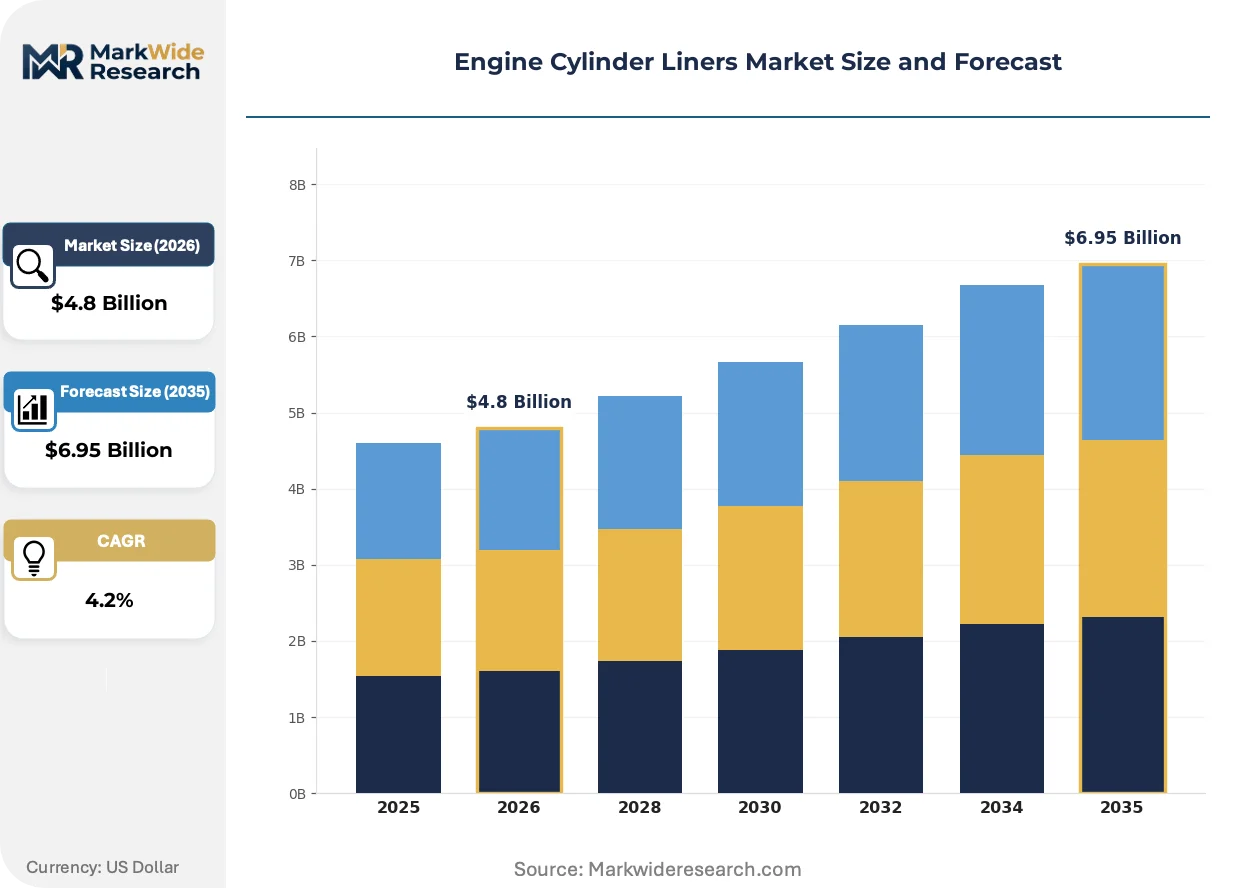
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cast Iron, Aluminum Alloy, Steel, Composite Engine Type: Petrol, Diesel, Hybrid, Electric Manufacturing Process: Sand Casting, Die Casting, Forging, Machining Application: Automotive, Aerospace, Marine, Industrial |
| Companies Covered | Mahle GmbH, Tenneco Inc., Federal-Mogul Corporation, Nippon Piston Ring Co., Ltd., TPR Co. Ltd., Westwood Cylinder Liners Ltd., Darton International, ZYNP, Melling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Cylinder Liners Market Shifts & Advancements
Surface engineering and thermal management innovations are redefining competitive advantage as liner wall thickness shrinks and combustion pressures escalate across heavy-duty diesel and hybrid applications.
Boron-nitride coatings are rendering obsolete traditional chrome plating in European heavy-duty applications. ECHA REACH restrictions on hexavalent chromium compounds have accelerated German and Italian foundry conversions since 2023. Fleet operators now specify 40,000-hour liner life guarantees that only ceramic-metallic composites can satisfy, compressing demand for conventional surface treatments.
EPA Phase 3 greenhouse gas standards are mandating 2% annual fuel economy improvements for US heavy-duty trucks through 2032. Liner manufacturers must reduce wall thickness by 15-20% while maintaining structural integrity under 220 bar peak cylinder pressures. Independent repair chains in the Midwest and Southeast are stockpiling thicker legacy inventory ahead of specification transitions.
Direct distribution contracts are displacing traditional warehouse distributor networks for high-volume aftermarket accounts. Tenneco and comparable suppliers now bypass regional jobbers to serve national repair chains with consolidated pricing and technical support. This channel consolidation concentrates most visible in North American Class 8 truck service operations where fleet purchasing centralization accelerates.
Engine Cylinder Liners Market Segmentation
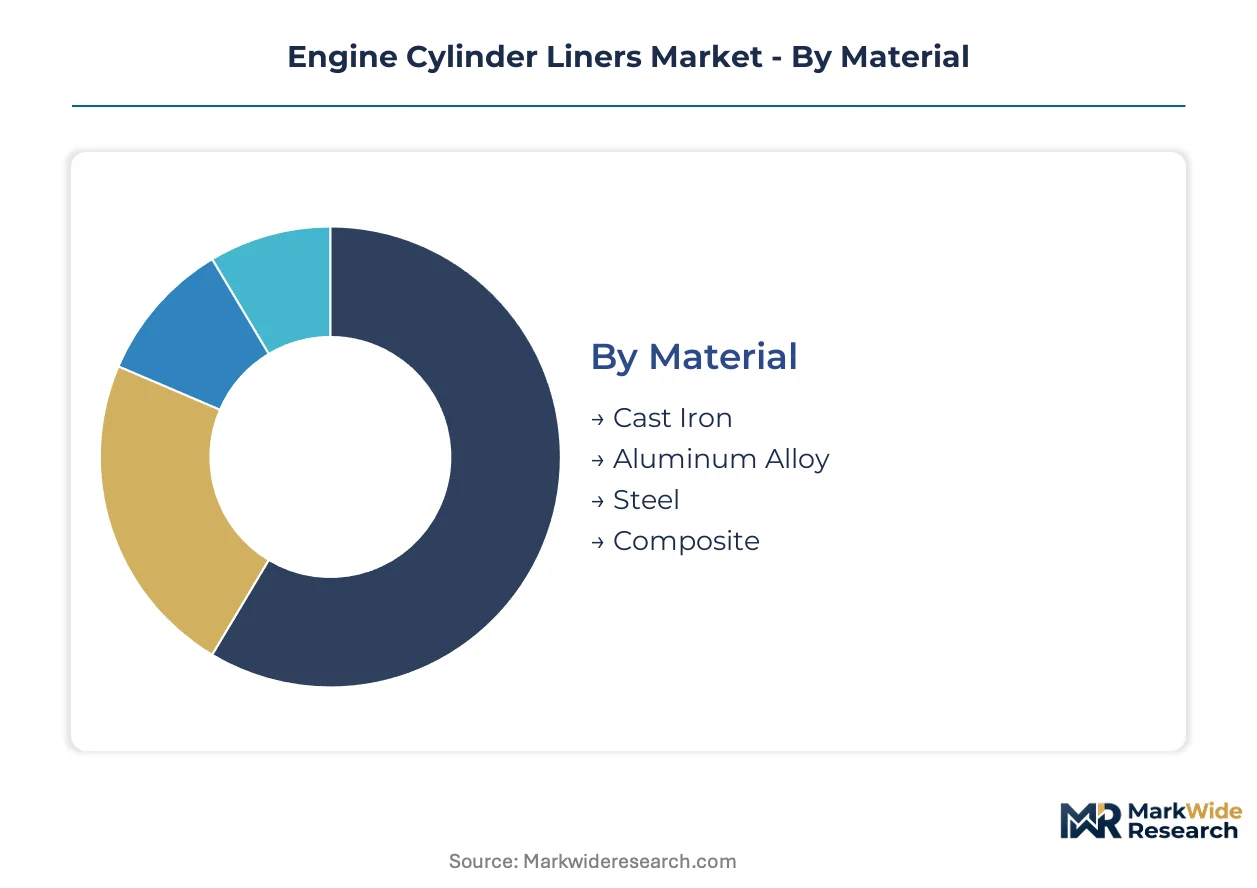
Engine cylinder liner segmentation reflects divergent thermal and mechanical demands across powertrain architectures. Material selection and manufacturing process choices directly determine cost structures, replacement intervals, and supplier qualification pathways in OEM and aftermarket channels.
Material:
Cost tier differentiation separates commodity metallurgy from premium surface-engineered alternatives in heavy-duty and high-performance applications.
- Cast Iron:Centrifugally cast grey iron with pearlitic microstructures and 190-240 HB hardness ratings dominates heavy-duty diesel specifications. India's BIS-certified foundries supply replacement cycles for aging commercial vehicle fleets where thermal fatigue resistance commands premium positioning.
- Aluminum Alloy:Hypereutectic aluminum-silicon formulations reduce reciprocating mass in petrol engines. European OEMs specify these for hybrid thermal management where stop-start cycles demand rapid heat dissipation.
- Steel:Chrome-molybdenum alloy liners serve severe-service mining equipment with extended-life surface treatments.
- Composite:Ceramic-metallic hybrids incorporating boron-nitride coatings satisfy REACH-compliant alternatives to chrome plating.
Cast iron commands the established base. The steepest expansion runs through composite formulations.
Engine Type:
Application maturity across combustion and electrified architectures shapes volume concentration and technology investment priorities.
- Diesel:Heavy-duty commercial vehicle specifications drive aftermarket replacement volumes through EPA Phase 3 compliance pressures. Peak cylinder pressures reaching 220 bar mandate structural durability in thinner-walled designs.
- Hybrid:Stop-start engine cycles and thermal bridging between combustion and electric powertrains create demand for enhanced heat dissipation properties. Automakers bridging powertrain architectures specify these liners most intensively.
- Petrol:Light-duty automotive applications favor aluminum alloy liners for weight reduction.
- Electric:Battery-electric powertrains eliminate liner demand entirely in affected vehicle populations.
Diesel anchors current replacement part volumes. Hybrid specifications are climbing the fastest as OEMs navigate emissions transition timelines.
Manufacturing Process:
Margin distribution concentrates in precision finishing rather than raw casting operations, reshaping capital deployment strategies.
- Centrifugal Casting:Grey iron liner production relies on rotating mold technology for directional solidification and porosity control. Mexican captive foundries serving North American OEMs leverage USMCA rules of origin.
- Machining:Precision honing and surface treatment subsystems capture disproportionate margin pools. Skill scarcity in these finishing processes constrains output scaling for premium coating applications.
- Sand Casting:Lower-volume production for legacy engine specifications and aftermarket replacement.
- Die Casting:Aluminum alloy liner production for petrol and hybrid applications.
Centrifugal casting holds the volume base. Machining-intensive finishing is gaining share fastest as surface engineering requirements escalate.
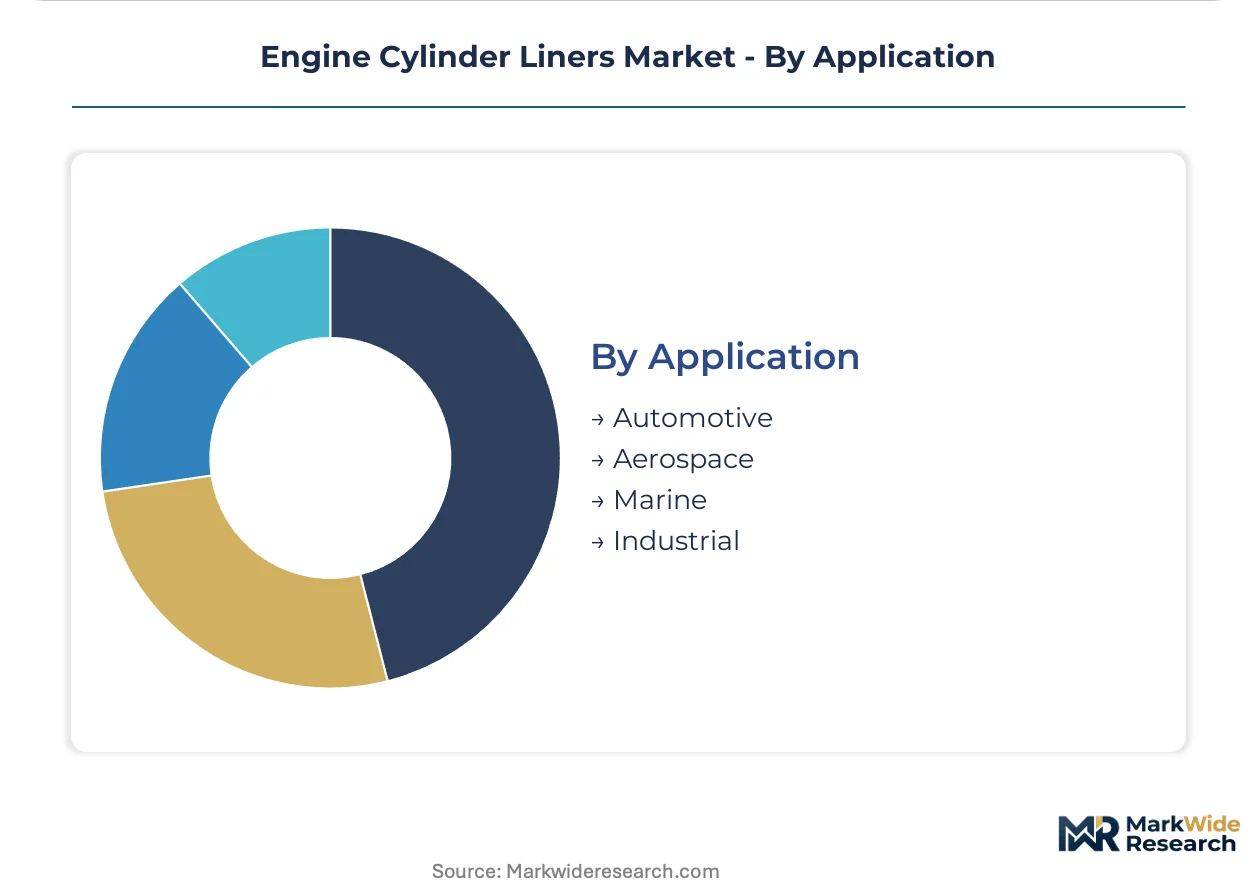
Application:
End-use concentration determines regulatory exposure and replacement cycle compression across geographic markets.
- Automotive:Class 8 truck service operations concentrate demand in North American aftermarket channels. Fleet purchasing centralization accelerates direct distribution contracts bypassing traditional warehouse networks.
- Industrial:Mining and severe-service applications specify extended-life surface treatments that command price premiums over standard specifications.
- Marine:Diesel propulsion systems in commercial shipping face IMO emissions compliance pressures.
- Aerospace:Specialized high-performance engine requirements with limited volume but exacting certification standards.
Automotive claims the dominant share. Industrial applications are expanding most quickly as resource extraction intensifies in frontier geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 greenhouse gas standards and India's BIS certification mandates are compressing replacement cycles and reshaping sourcing patterns across key manufacturing hubs. Foundry investments concentrate near OEM assembly plants to reduce logistics exposure.
United States
Class 8 truck fleet operators stockpile legacy liner inventory ahead of thinner-walled specification transitions. NHTSA fuel economy standards mandate 2% annual improvements through 2032. Midwest independent repair chains in Ohio and Illinois dominate aftermarket distribution consolidation.
Germany
ECHA REACH restrictions on hexavalent chromium accelerate boron-nitride coating conversions in heavy-duty foundries. The EU Green Deal redirects R&D investment toward ceramic-metallic composites. Stuttgart and Munich industrial clusters host precision honing capacity for premium surface treatments.
India
BIS-certified cast iron suppliers capture replacement demand from aging commercial vehicle parc expansion. Central Electricity Authority regulations indirectly pressure thermal efficiency in auxiliary power units. Gujarat and Maharashtra foundry belts concentrate centrifugal casting operations for diesel engine rebuilds.
Mexico
USMCA rules of origin attract captive casting networks serving North American OEMs. EPA emissions compliance pressures transmit directly across integrated supply chains. Nuevo León and Bajío Region industrial corridors expand precision machining capacity for thinner-walled liner production.
China
Scrap cast iron price volatility from export tariff adjustments compresses margin predictability for grey iron foundries. Ministry of Industry and Information Technology standards enforce dual carbon goals in metallurgical processes. Yangtze River Delta clusters balance domestic aftermarket demand with export logistics optimization.
Engine Cylinder Liners Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. Consolidation concentrates among German and Japanese automotive suppliers with captive foundry networks, while mid-tier independents leverage asset-light remanufacturing equipment leasing. Three archetypes dominate: integrated metallurgy specialists with backward casting control, precision surface engineering boutiques, and scale-driven aftermarket distributors. M&A activity targets honing capacity acquisitions, and geographic expansion follows OEM nearshoring corridors.
Within the integrated metallurgy tier, Mahle GmbH and Federal-Mogul Corporation exemplify foundry-captive strategies, while Tenneco Inc. occupies a position emphasizing direct distribution channels. Zhengzhou-based ZYNP represents Chinese scale fabrication, and TPR Co. Ltd. anchors Japanese precision engineering heritage. Westwood Cylinder Liners Ltd. and Darton International sit within specialist boutiques focused on severe-service applications, with Melling exemplifying North American aftermarket distribution concentration.
| Leading Market Players |
|---|
| Mahle GmbH |
| Tenneco Inc. |
| Federal-Mogul Corporation |
| Nippon Piston Ring Co., Ltd. |
| TPR Co. Ltd. |
| Westwood Cylinder Liners Ltd. |
| Darton International |
| ZYNP |
| Melling |
| Others |
Supply & Pricing Matrix
Chinese pig iron export tariffs and Yangtze River Delta foundry concentration transmit directly into margin compression for centrifugal casting operations serving North American and European OEMs. This upstream metallurgy concentration forces downstream margin pools into precision honing and boron-nitride coating subsystems where skill scarcity sustains pricing power.
Pricing Analysis
Certification level creates the primary spread between BIS-certified Indian foundry output and premium ceramic-metallic composite liners from German precision engineering clusters. Three-tier pricing structure across premium, standard, and economy levels reflects IATF 16949 qualification timelines, with OEM supply agreements commanding 40% premiums over independent repair chain volumes. Price erosion runs through legacy grey iron specifications as EPA Phase 3 compliance forces thinner-walled design transitions. Fleet operators in North American Class 8 truck service operations exhibit lowest price sensitivity due to consolidated national purchasing contracts, while Midwest independent repair chains stockpile inventory opportunistically during specification transitions.
Supply Chain Analysis
Export-control scrutiny on advanced coating technologies limits boron-nitride and diamond-like carbon process equipment flows into Chinese foundries, constraining capacity expansion for REACH-compliant alternatives. Supply concentrates in Germany, Mexico, and India, with captive casting networks in Nuevo León and Stuttgart serving integrated OEM supply chains. Raw material dependencies center on scrap cast iron, chrome-molybdenum alloys, and ceramic-metallic composite substrates. Single-source vulnerability in precision honing equipment from aging workforce regions in Ohio and Illinois threatens output scaling. Distribution runs through direct contracts to national repair chains, displacing traditional warehouse distributor networks in North American aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engine cylinder liner demand follows heavy-duty truck replacement cycles, with EPA Phase 3 compliance pressures creating a cyclical upswing in aftermarket volumes through the projection horizon.
For Market Incumbents: Pre-empt composite liner entrants by accelerating IATF 16949 certification investments for ceramic-metallic hybrid formulations before 18-24 month qualification windows close. Backward integration into captive boron-nitride coating capacity in Stuttgart or Munich industrial clusters defends margin position against asset-light mid-tier suppliers leasing remanufacturing equipment. Channel control through direct distribution contracts to national fleet operators reinforces aftermarket pricing power versus regional jobber networks. For New Entrants and Emerging Players: India's BIS-certified cast iron aftermarket offers the most penetrable white-space, with aging commercial vehicle parc expansion outpacing new engine sales in Gujarat and Maharashtra foundry belts. Asset-light precision honing equipment leasing models bypass heavy foundry capital requirements while accessing margin-rich surface treatment subsystems. Technical partnerships with German coating technology licensors provide fastest route to REACH-compliant chrome plating alternatives for European heavy-duty specifications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive supplier portfolios seeking exit liquidity from non-core casting operations. Five-to-ten year viability hinges on hybrid thermal management specification capture as automakers bridge combustion and electrified powertrains. Acquisition targets should prioritize honing capacity in Mexico's USMCA corridor or boron-nitride coating boutiques in German industrial clusters. The signal to watch is battery-electric powertrain penetration rates in urban delivery segments, which eliminate liner demand entirely for affected vehicle populations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron-Nitride Coating Capacity | Captive supply of REACH-compliant surface treatments commands 25-30% premiums over outsourced chrome plating in German heavy-duty applications. |
| Asset-Light Precision Honing Equipment Leasing | Mid-tier suppliers access margin-rich finishing subsystems without foundry capital deployment in Mexico's Nuevo León corridor. |
| Direct Distribution Contract Consolidation | National fleet purchasing centralization in North American Class 8 truck service operations displaces regional warehouse distributor networks. |
| IATF 16949 Certification Acceleration | Composite liner entrants face compressed qualification windows to challenge incumbent metallurgy in OEM supply agreements. |
| Nearshoring Captive Casting Networks | USMCA rules of origin and reduced logistics exposure favor Mexican foundry investments serving EPA Phase 3 compliance pressures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foundry operations managers, OEM procurement leads at Tier 1 engine suppliers, aftermarket distributors in North American Class 8 truck service channels, and precision honing equipment specialists in German industrial clusters. Secondary validation drew from EPA Phase 3 regulatory filings, ECHA REACH restriction updates, BIS certification registries, USMCA trade documentation, and IHS Markit commercial vehicle production databases. Bottom-up unit demand estimates triangulated against top-down market sizing from foundry capacity utilization and replacement cycle modeling.
Calibration anchored volume projections to historical replacement patterns under prior emissions standard transitions, with segmentation across material grade, engine architecture, manufacturing process intensity, and end-use application. Modeled dimensions included diesel-hybrid-petrol-electric propulsion splits, centrifugal casting versus machining-intensive finishing value capture, and automotive-industrial-marine-aerospace demand concentration. CAGRs derived from regression analysis of fleet age demographics, regulatory compliance cost pass-through elasticities, and coating technology substitution curves.
Practitioners should monitor battery-electric powertrain adoption rates in urban delivery segments and scrap cast iron export tariff adjustments for early signals of demand destruction or input cost volatility. Forecasts embed assumptions around EPA Phase 3 implementation timelines, ECHA REACH enforcement consistency, and IATF 16949 certification pathway stability. Material shifts in electrification penetration or foundry input cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Brazil Automotive Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Car Oil Filter Market
Powertrain
Global Automotive Dyno Market
Powertrain
Gasoline Turbochargers Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Clutch Hub Puller Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Clutch Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market