
 Automotive Coil Spring Market | 2026-2036
Automotive Coil Spring Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coil Spring Market Analysis
The capital-intensity gap between integrated steel processors and standalone spring fabricators is collapsing as OEMs consolidate supplier bases and demand in-house heat-treatment capabilities. NHK Spring Co. Ltd. leverages its captive steel rolling and wire-drawing operations to control alloy grades from melt to finished coil. Mubea sustains dominant share in chassis modules through backward integration into high-strength wire production and just-in-sequence delivery to German vehicle assemblers.
An automotive coil spring is a helical mechanical spring manufactured from high-carbon steel, chrome-silicon, or chrome-vanadium alloy wire, cold-coiled or hot-wound to specified pitch and free length, then stress-relieved and shot-peened to resist fatigue under cyclic compression loads; its primary function is to store and release kinetic energy while maintaining ride height, wheel alignment, and suspension geometry across vehicle operating conditions. Compression springs occupy the largest volume share within product type segmentation due to their ubiquity in MacPherson strut and multi-link front suspensions across passenger cars and light trucks. Carbon fiber and titanium material categories represent the fastest-expanding segment pools, driven by EV platform weight-reduction targets that reward density savings despite premium unit economics.
The EPA enforces fuel economy standards that directly incentivize unsprung mass reduction, while NHTSA crashworthiness rules govern spring retention and structural integrity under impact loading. Europe's REACH regulation restricts hexavalent chromium in surface coatings, compelling suppliers to migrate toward zinc-flake or organic corrosion-protection systems. Stakeholders must monitor how evolving EV platform architectures with fixed battery packs redistribute suspension load paths and redefine spring rate specifications across vehicle classes.
Market Dynamics
The automotive coil spring market is experiencing a fundamental reconfiguration as electric vehicle platforms impose new load-path geometries and mass-reduction imperatives that invalidate legacy steel-intensive spring specifications developed for internal combustion chassis architectures.
Growth Catalysts
- EV Platform Weight Targets:Battery-electric vehicle architectures demand unsprung mass reduction to offset fixed battery pack weight, accelerating specification of titanium and carbon fiber composite spring materials in premium segment applications.
- REACH Surface Treatment Mandates:ECHA restrictions on hexavalent chromium coatings compel migration toward zinc-flake and organic corrosion-protection systems, creating upgrade cycles across European aftermarket and OE supply chains.
- German Manufacturing Corridor Concentration:OEM-Tier-1 co-location of engineering and production functions in Baden-Württemberg and Bavaria compresses development timelines and stabilizes demand visibility for precision spring fabricators.
Market Restraints
- Alloy Wire Price Volatility:Chrome-silicon and chrome-vanadium wire rod costs fluctuate with ferrochrome and vanadium spot markets, squeezing margin predictability for standalone spring manufacturers lacking captive melt-to-wire operations.
- Heat Treatment Capacity Bottleneck:In-house induction hardening and tempering capabilities require capital outlays exceeding $15 million per production line, concentrating viable supply among integrated steel processors and excluding mid-scale fabricators.
- MacPherson Strut Design Saturation:Compression spring ubiquity in front suspension architectures limits product diversification opportunities as multi-link and air-spring configurations penetrate upper vehicle segments.
Strategic Opportunities
- India Passenger Vehicle Localization:PLI scheme incentives for advanced automotive components create opening for high-strength spring suppliers to establish domestic wire-drawing and coiling operations serving Maruti Suzuki and Hyundai Motor India assembly plants.
- Fixed Battery Pack Load Path Redesign:EV skateboard platforms redistribute suspension attachment points and spring rate requirements, enabling spring designers to specify variable-pitch architectures previously incompatible with fuel tank and exhaust system packaging constraints.
- China Dual Carbon Policy:MIIT energy-efficiency mandates for automotive manufacturing processes favor lightweight spring materials that reduce vehicle curb weight and improve fleet-average fuel consumption metrics.
Industry Challenges
- Shot Peening Parameter Certification:OEM qualification protocols for residual stress profiles and coverage uniformity extend validation timelines to 18-24 months, delaying revenue recognition for new alloy formulations.
- Legacy Suspension System Integration:Spring rate specifications must maintain backward compatibility with existing damper valving and bush compliance in vehicle refresh programs, constraining radical geometry innovation.
- Alloy Metallurgy Talent Scarcity:Specialized expertise in high-carbon steel patenting and wire rod microstructure control concentrates among retiring European and Japanese engineering cohorts, creating knowledge transfer gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coil Spring Market |
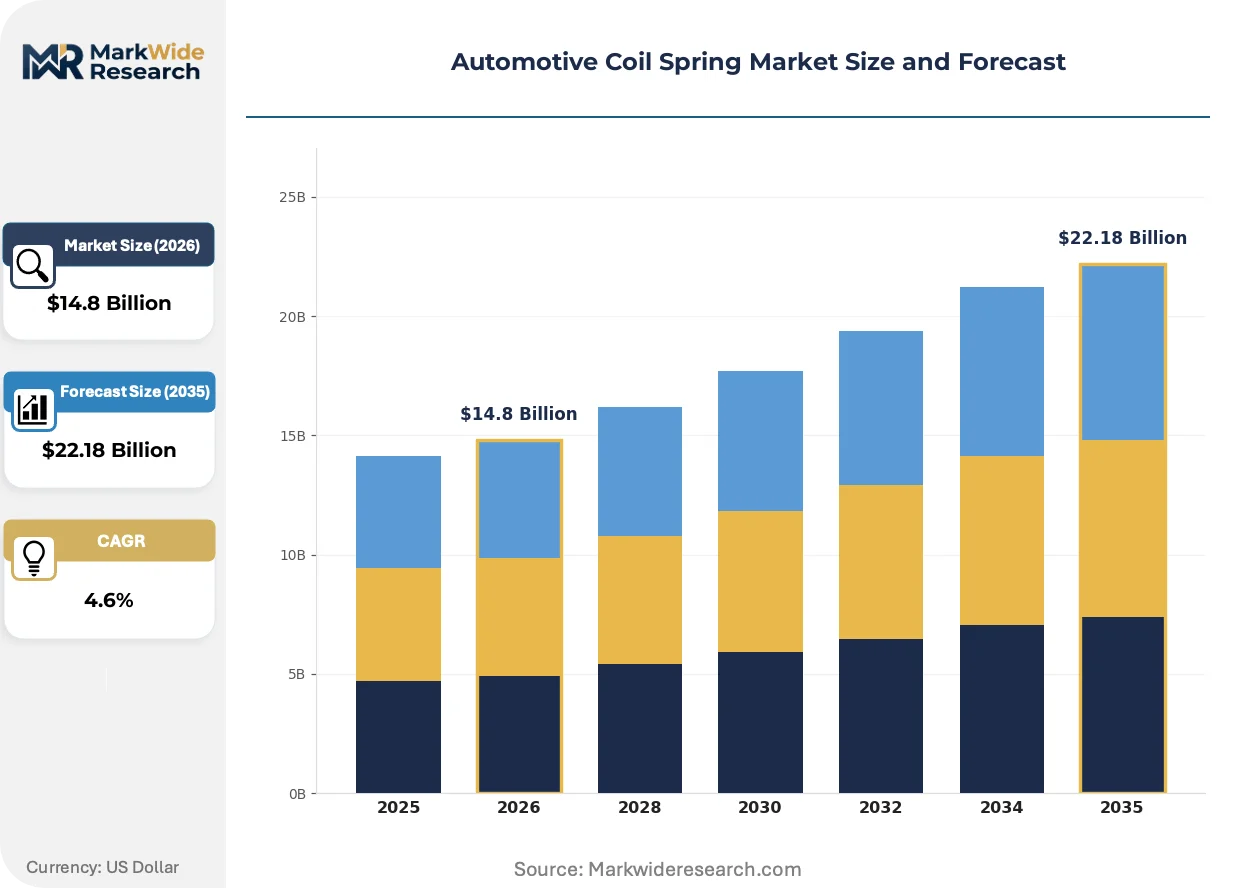
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Spring, Extension Spring, Torsion Spring, Flat Spring Material: Steel, Titanium, Aluminum, Carbon Fiber End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Cars, Light Trucks, Heavy Vehicles, Motorcycles |
| Companies Covered | NHK Spring Co. Ltd., Mubea, Sogefi Group, Thyssenkrupp, GKN, Betts Spring, Rassini, Lesjöfors Automotive, Z F Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coil Spring Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are simultaneously compressing traditional supply structures while opening specification pathways for novel alloy and composite architectures in suspension systems.
Titanium coil springs are supplanting chrome-silicon steel in upper-segment battery-electric vehicles where density reduction justifies premium unit economics. Porsche and Lucid Motors have adopted titanium front springs to offset battery pack mass while maintaining target ride frequencies. This substitution is supplanting conventional high-strength steel specifications in applications where mass savings translate directly to range extension.
Europe's F-Gas Regulation and REACH compliance frameworks are prohibiting hexavalent chromium conversion coatings and fluorinated greenhouse gas processes in surface treatment operations. Suppliers are migrating toward zinc-flake systems and organic polymer barriers that meet salt-spray requirements without regulated substances. German and Czech surface engineering facilities are retooling anodizing and phosphating lines to accommodate these chemistry transitions.
Buyer consolidation among vehicle assemblers is compressing supplier qualification cycles and demanding just-in-sequence delivery capabilities. Tier-1 chassis module integrators now specify spring rate tolerances of ±3% versus historical ±5% bands, requiring statistical process control investments at fabricator level. This specification tightening is most visible in German and Japanese OE supply agreements where module suppliers assume full suspension assembly responsibility.
Automotive Coil Spring Market Segmentation
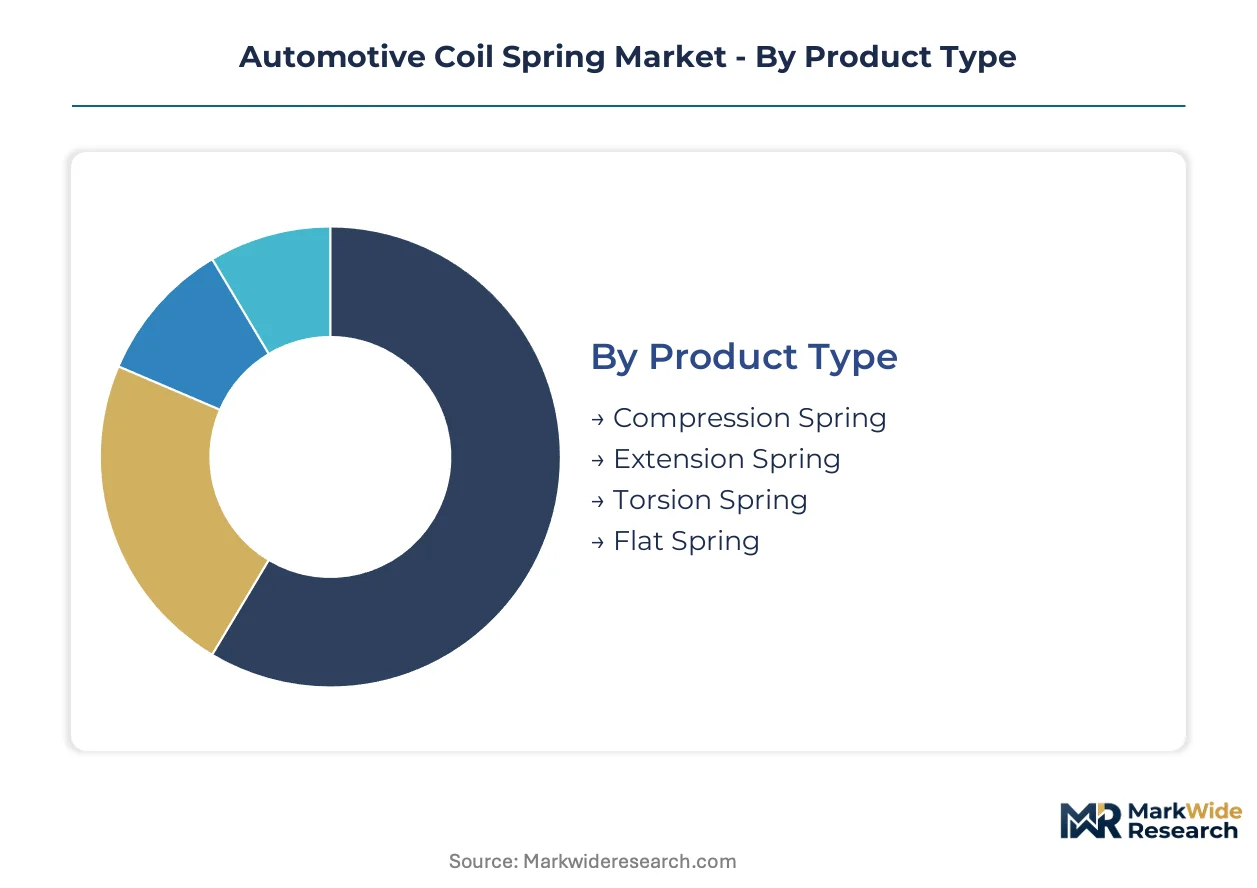
Coil spring specification varies sharply across vehicle architectures and procurement channels. Segmentation reveals where material substitution pressures concentrate and which customer tiers command pricing power.
Product Type:
Compression springs face the strongest substitution threat from air-spring modules in premium segments, while torsion and extension architectures retain defensible positions in specialized load-bearing applications.
- Compression Spring:Helical springs wound from high-carbon or chrome-silicon wire, cold-formed to precise pitch dimensions for MacPherson strut assemblies. Demand concentrates in German and Japanese passenger car platforms where OEMs specify ±3% rate tolerances for chassis module integration.
- Torsion Spring:Bars or coils that store rotational energy through angular deflection, common in rear suspension twist-beam axles and hood hinge mechanisms. Indian and Chinese light truck manufacturers specify these for cost-optimized leaf-spring replacement programs.
- Extension Spring:Helical designs with hooks or loops at each end, absorbing tensile loads in brake return mechanisms and clutch pedal linkages. These occupy stable aftermarket demand from North American and European service channels.
- Flat Spring:Stamped or rolled strip steel configurations, including leaf-spring derivatives and Belleville washers for limited-travel applications. Heavy vehicle seat suspension and motorcycle rear linkages specify these where space constraints prohibit coil geometries.
Compression springs anchor the volume base while carbon fiber-reinforced alternatives in upper vehicle segments gain share at the steepest rate.
Material:
Cost tiers separate commodity steel specifications from performance alloys, with density-driven materials commanding 8-15x unit premiums that only EV mass budgets currently justify.
- Steel:High-carbon grades and chrome-silicon alloys dominate through captive melt-to-wire integration at NHK Spring and Mubea. European REACH compliance is forcing migration from hexavalent chromium coatings toward zinc-flake surface protection systems.
- Carbon Fiber:Thermoset composite springs filament-wound or pultruded to anisotropic stiffness specifications. Porsche and Lucid Motors specify these for front axle applications where unsprung mass reduction extends battery range.
- Titanium:Ti-6Al-4V alloy wire cold-coiled and solution-treated for density-critical applications. Premium EV platforms in Germany and California adopt these despite raw material costs exceeding steel by an order of magnitude.
- Aluminum:7075-T6 and similar alloys coiled and precipitation-hardened for motorcycle and light vehicle applications where moderate weight savings suffice. Chinese manufacturers experiment with these for domestic EV platforms under MIIT efficiency mandates.
Steel retains absolute volume leadership while carbon fiber composite formulations climb fastest among materials qualifying for EV platform specifications.
End User:
Procurement concentration among German vehicle assemblers compresses supplier margins for Tier-1 integrators while aftermarket channels sustain fragmented, higher-margin demand.
- OEMs:Vehicle manufacturers specifying spring rates and fatigue life directly for captive chassis engineering teams. Baden-Württemberg and Bavaria co-location patterns give these buyers 18-24 month qualification leverage over fabricators.
- Tier-1 Suppliers:Module integrators like Mubea assembling complete suspension corners with just-in-sequence delivery obligations. These intermediaries assume spring rate tolerance risk and shot-peening certification costs.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations sourcing through approved supplier lists. India's Maruti Suzuki and Hyundai Motor India assembly plants drive localization requirements under PLI scheme incentives.
- Aftermarket Providers:Independent distributors and service chains supplying replacement springs for wear-item replacement. European REACH surface-treatment mandates are retooling these channels toward zinc-flake and organic coating systems.
Tier-1 suppliers intermediate the largest contract values while aftermarket channels deliver superior margin stability through fragmented demand.
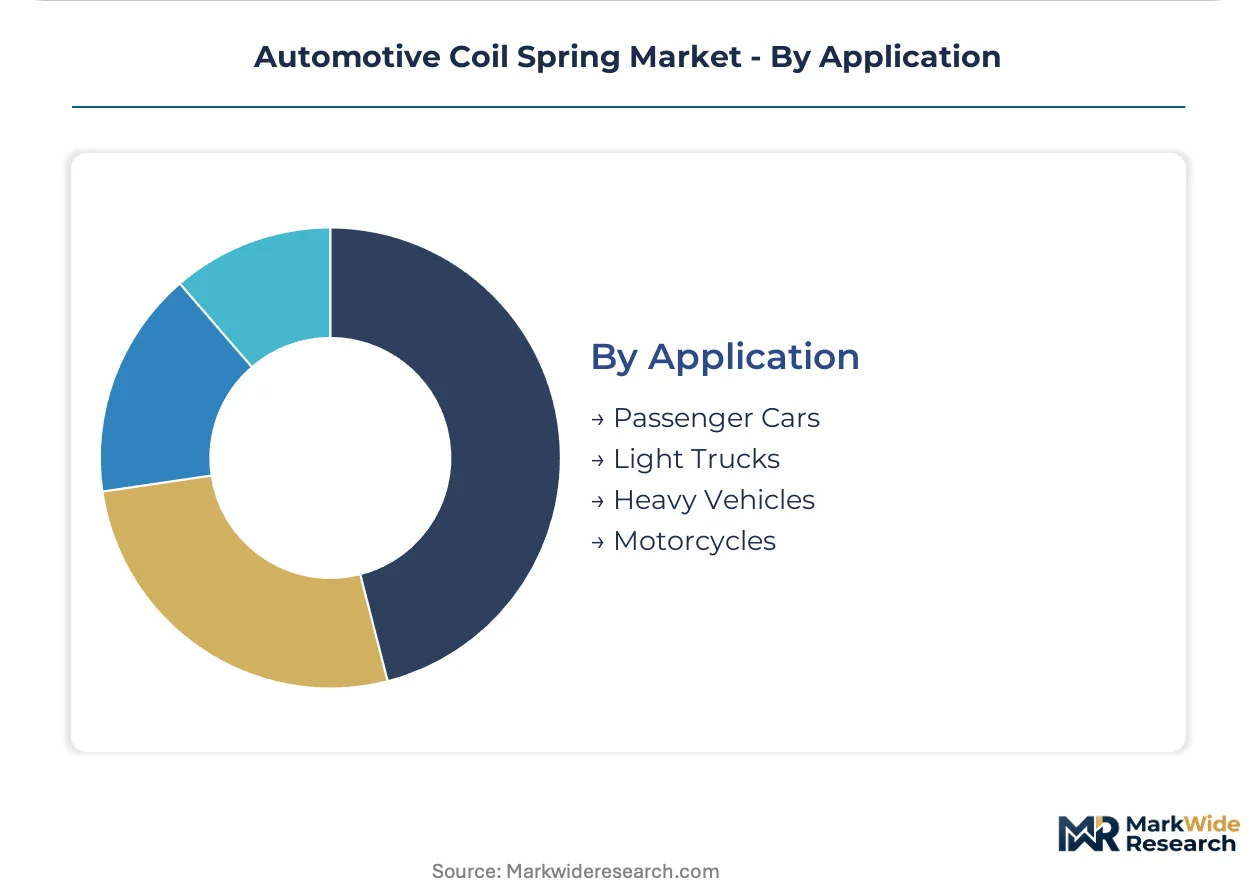
Application:
Vehicle class determines load-path geometry and spring rate specifications, with electrification redistributing demand toward passenger car platforms optimized for battery pack mass distribution.
- Passenger Cars:MacPherson strut and multi-link front suspensions specifying variable-pitch compression springs. EV skateboard platforms enable geometries previously incompatible with exhaust and fuel tank packaging.
- Light Trucks:Pickup and van architectures combining coil springs with auxiliary air springs for load-leveling. North American and Thai manufacturing corridors concentrate demand for these dual-rate configurations.
- Heavy Vehicles:Commercial trucks and buses specifying parabolic leaf springs or air-ride systems, with coil springs limited to cab suspension and seat isolators. Indian and Brazilian truck assemblers drive steel-intensive specifications.
- Motorcycles:Telescopic fork and rear mono-shock applications demanding high-stress, low-mass springs. Japanese and Italian sportbike manufacturers specify titanium and surface-treated steel for this weight-sensitive segment.
Passenger car applications generate the dominant specification volume while motorcycle and premium EV platforms adopt alternative materials most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive coil springs track the geographic dispersion of vehicle assembly capacity and captive steel processing infrastructure. Major producing jurisdictions maintain trade surpluses in precision-wound components while importing specialty alloy wire for performance specifications.
Germany
OEM-Tier-1 co-location in Baden-Württemberg and Bavaria compresses development cycles for chassis module integrators. REACH restrictions on hexavalent chromium coatings mandate zinc-flake surface protection migrations across supplier facilities. Stuttgart's engineering corridor concentrates heat-treatment and shot-peening capabilities serving Mercedes-Benz and BMW assembly networks.
United States
EPA fuel economy standards and NHTSA crashworthiness rules govern spring retention specifications for domestic light truck platforms. The EPA enforces unsprung mass reduction targets that indirectly incentivize lightweight material adoption. Michigan's automotive manufacturing belt anchors coil spring demand from Detroit Three assemblers and their Tier-1 module suppliers.
China
MIIT energy-efficiency mandates under the dual carbon policy favor lightweight suspension components that reduce fleet-average fuel consumption. GB standards govern fatigue life testing protocols for domestic passenger vehicle platforms. The Yangtze River Delta manufacturing cluster concentrates wire-drawing and cold-coiling capacity serving SAIC Motor and Geely assembly operations.
India
PLI scheme incentives for advanced automotive components create openings for high-strength spring localization serving Maruti Suzuki and Hyundai Motor India. BIS certification requirements govern material specifications for domestic vehicle production. Tamil Nadu's Sriperumbudur-Oragadam corridor concentrates foreign OEM assembly plants driving suspension component demand.
Japan
METI industrial policy supports domestic production of precision automotive components including fatigue-resistant suspension springs. JIS standards govern wire rod metallurgy and spring rate tolerance specifications. The Aichi Prefecture manufacturing cluster around Toyota City maintains integrated steel-to-spring supply chains for just-in-time delivery.
Automotive Coil Spring Market Vendor Landscape
Concentration sits with integrated steel processors possessing captive melt-to-wire capabilities that standalone fabricators cannot replicate. The supplier base compresses around three strategic archetypes: steel-integrated specialists controlling alloy grades from raw material through finished spring; module integrators assembling complete suspension corners with just-in-sequence delivery obligations; and regional fabricators serving aftermarket channels with standardized specifications. Dominant competitive moves include backward integration into high-strength wire production and geographic expansion into emerging vehicle assembly corridors.
Among steel-integrated specialists, NHK Spring Co. Ltd. and Mubea occupy positions exemplifying captive metallurgy control, while Thyssenkrupp sits within the diversified industrial conglomerate tier. These archetypes represent how alloy grade mastery and heat-treatment certification capabilities separate viable suppliers from excluded mid-scale competitors. Module integrators assume spring rate tolerance risk and shot-peening validation costs that OEMs increasingly refuse to bear directly.
| Leading Market Players |
|---|
| NHK Spring Co. Ltd. |
| Mubea |
| Sogefi Group |
| Thyssenkrupp |
| GKN |
| Betts Spring |
| Rassini |
| Lesjöfors Automotive |
| Z F Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Heat-treatment line utilization rates exceeding 85% at German and Japanese integrated processors create scale thresholds that standalone fabricators cannot match, compressing mid-tier competitors into commodity steel specifications while concentrating premium alloy pricing power among NHK Spring and Mubea. This capacity concentration reinforces price floors for chrome-silicon and titanium grades while forcing smaller players toward standard carbon steel aftermarket segments.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with just-in-sequence delivery obligations. Three-tier pricing structure across premium, standard, and economy levels separates titanium EV specifications from chrome-silicon OE grades and carbon steel aftermarket volumes. Cost compression in standard steel grades is intensifying because OEMs are consolidating supplier bases and demanding captive heat-treatment capabilities. Aftermarket distributors exhibit highest price sensitivity due to fragmented demand and import competition, while German OEM chassis module integrators accept premium positioning for qualified suppliers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for chrome-vanadium wire rod shipments from Japanese melt shops to European coiling facilities. Supply concentrates in Germany, Japan, and China, with the Yangtze River Delta and Aichi Prefecture anchoring wire-drawing capacity and Baden-Württemberg controlling precision coiling and heat treatment. Raw material flows draw from ferrochrome spot markets in South Africa and vanadium processing in Russia and China. Single-source vulnerability concentrates in high-strength wire rod supply from Nippon Steel and Posco. Distribution runs through Tier-1 chassis module integrators with direct OEM assembly plant feed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV platform weight-reduction mandates and REACH surface-treatment compliance are disrupting legacy steel-intensive supply structures, creating openings for titanium and carbon fiber specialists while threatening commodity fabricators dependent on hexavalent chromium processes.
For Market Incumbents: Consolidate heat-treatment and shot-peening certification capabilities to defend against integrated steel processors expanding downstream. Secure captive wire-drawing capacity or long-term offtake agreements with Japanese and Korean melt shops to offset ferrochrome price volatility. Lock in multi-year chassis module contracts with German OEMs before qualification cycles reset for EV skateboard architectures. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridor around Tamil Nadu, where Maruti Suzuki and Hyundai Motor India localization requirements outstrip domestic high-strength spring capacity. Target carbon fiber composite spring qualification for premium EV platforms in California and Germany, where density savings justify 8-15x unit premiums over steel. Pursue direct OEM engineering relationships rather than Tier-1 module integration to bypass incumbent supply chain control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors steel-integrated specialists with captive metallurgy control over standalone fabricators facing alloy wire cost volatility. Five-to-ten year viability hinges on EV platform penetration rates and material substitution curves. Watch titanium spring adoption in Porsche and Lucid Motors production ramps as the signal for premium segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Production | NHK Spring's captive melt-to-wire control insulates margin from ferrochrome spot volatility. |
| EV Platform Qualification Investment | Titanium spring certification with German OEMs opens premium segment access at 8-15x steel pricing. |
| REACH Surface Treatment Retooling | Zinc-flake system migration at Czech and German facilities preserves European OE market access. |
| India PLI Localization Buildout | Domestic wire-drawing capacity serving Maruti Suzuki captures PLI scheme incentives and import substitution demand. |
| Just-in-Sequence Delivery Infrastructure | Baden-Württemberg co-location with BMW and Mercedes-Benz compresses development cycles and stabilizes contract visibility. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 chassis module procurement leads, aftermarket distributor operations heads, and heat-treatment facility technical directors and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and customs trade records for wire rod and finished spring movements. Bottom-up spring volume estimates by vehicle class and propulsion architecture were triangulated against top-down OEM procurement spend patterns.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation dimensions modeled include vehicle class, propulsion architecture, spring material grade, OEM tier positioning, and regional production cluster. CAGRs were derived from fitted growth curves applied to segment-level baselines, with EV platform penetration rates and alloy substitution elasticities serving as key automotive-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued EV platform expansion and REACH compliance enforcement; material deviation in battery-electric vehicle adoption curves or suspension architecture standardization would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Tachometer Market
Powertrain
Global Automotive Tappet Market
Powertrain
Timing Belt Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Automotive Carburetor Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market