
 Hydraulic Cylinder Rod Market | 2026-2036
Hydraulic Cylinder Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Cylinder Rod Market Insights
Chinese steel mill capacity for precision-ground bar stock is decoupling from European forging output, creating divergent supply timelines for rod converters. Bosch Rexroth leverages captive metallurgy partnerships to secure alloy steel consistency across its cylinder lines. Parker Hannifin Corporation anchors North American availability through vertically controlled chrome plating networks. Eaton competes on induction hardening depth specifications that exceed OEM warranty thresholds for construction hydraulics.
A hydraulic cylinder rod is a precision-machined, surface-hardened steel shaft that transmits linear force within a sealed fluid chamber, typically finished to sub-micron roughness tolerances and chrome-plated or coated for corrosion resistance and seal longevity. Carbon steel and alloy steel formulations dominate volume, though stainless steel variants command margin pools in marine and offshore applications where salt exposure degrades standard platings. Chrome plated rod still leads unit shipments across agriculture and construction end users, while induction hardened rod is gaining fastest in automotive press lines where cycle frequency accelerates wear. The manufacturing process split reveals forging and machining as mature, high-throughput stages, with extrusion occupying niche positions in small-bore specialty cylinders.
FDA surface finish guidelines for food-processing hydraulics, EPA chromium discharge limits, and REACH restrictions on hexavalent chrome plating collectively redirect coating investments toward tungsten carbide and HVOF alternatives. ISO 9001 and sector-specific OEM audit protocols further gate market access for second-tier rod suppliers. Stakeholders must monitor which coating technology achieves cost parity with legacy chrome before the next round of environmental rule tightening closes process windows.
Market Dynamics
Chrome plating phase-out timelines are compressing converter investment cycles as mills race to certify HVOF and tungsten carbide alternatives before REACH enforcement windows close.
Growth Catalysts
- Induction hardening depth specifications:Construction equipment OEMs in China are mandating deeper case depths for high-cycle hydraulic systems, pulling demand toward premium alloy formulations.
- REACH Article 57 restrictions:ECHA's hexavalent chromium sunset dates are accelerating mill capex into laser cladding and thermal spray coating lines.
- Shanghai-Busan port cluster concentration:East Asian manufacturing hubs are consolidating precision-ground bar stock procurement, reducing logistics friction for rod converters.
Market Restraints
- Alloy steel input volatility:Nickel and molybdenum price swings distort converter margin planning for induction-hardened rod batches.
- Chrome plating capacity lock-in:North American mills with legacy tank infrastructure face stranded asset risk as EPA chromium discharge limits tighten.
- Surface finish specification ceilings:Sub-micron Ra tolerances for high-pressure food-processing hydraulics remain technically constrained without ceramic coating breakthroughs.
Strategic Opportunities
- Marine stainless steel variants:Salt-exposure applications in offshore wind installations offer margin expansion beyond standard carbon steel commoditization.
- Automotive press line retrofit cycles:Cycle-frequency acceleration in stamping operations creates replacement demand for induction-hardened rods with enhanced fatigue resistance.
- India PLI scheme for capital goods:Domestic content incentives are opening local assembly opportunities for precision-ground bar stock converters.
Industry Challenges
- Metallurgical technician scarcity:Deep case-hardening process control requires specialized heat-treatment expertise that outpaces vocational training output.
- Multi-certification audit fatigue:ISO 9001 layering with OEM-specific protocols extends qualification timelines for second-tier rod suppliers.
- Coating-line reconfiguration capex:Transitioning from hexavalent chrome to HVOF demands furnace and robotic spray investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Cylinder Rod Market |
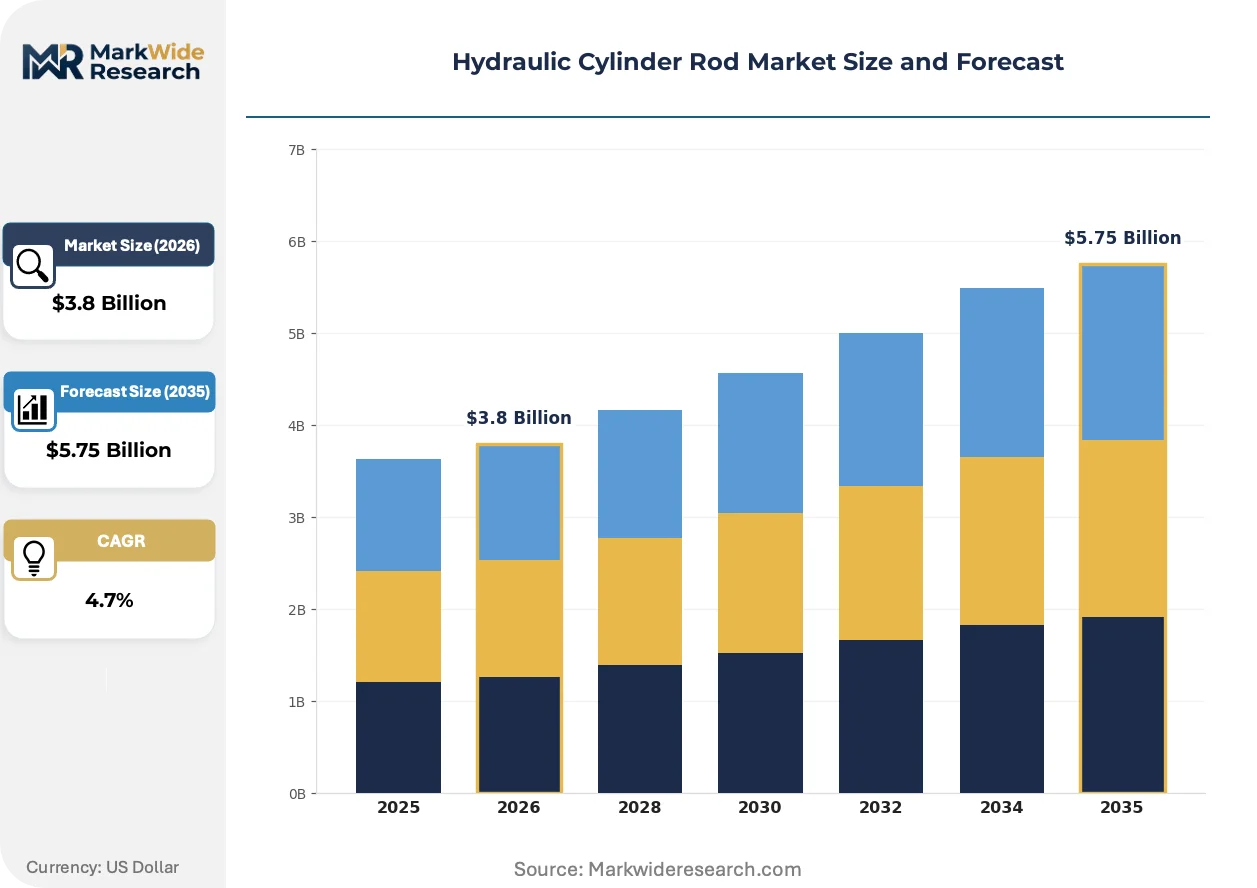
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chrome Plated Rod, Hardened Rod, Induction Hardened Rod, Others Material: Carbon Steel, Stainless Steel, Alloy Steel, Brass Manufacturing Process: Forging, Machining, Welding, Extrusion End User: Agriculture, Construction, Automotive, Marine |
| Companies Covered | Parker Hannifin Corporation, Bosch Rexroth, Eaton, KYB Corporation, Caterpillar, Enerpac Tool Group, SMC Corporation, HYDAC, Wipro Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Cylinder Rod Market Trends and Innovations
Coating chemistry transitions and precision machining automation are redrawing competitive boundaries between integrated mills and specialized converters.
HVOF-sprayed tungsten carbide coatings are rewriting durability benchmarks for hydraulic rods exposed to abrasive media in mining and construction fluids. OEMs in Germany and Australia are specifying these surfaces for warranty-critical cylinder lines. The technology is compressing chrome plating's residual market share by delivering equivalent seal longevity without hexavalent chromium exposure liabilities.
EPA's chromium discharge limits under the Clean Water Act are forcing North American plating shops into closed-loop wastewater systems or process abandonment. Mills without captive chemical recovery infrastructure are exiting the market. Food-processing equipment manufacturers are accelerating FDA-compliant surface finish sourcing to preempt liability exposure.
Buyer consolidation around cylinder assemblers with captive metallurgy partnerships is squeezing independent rod distributors. Direct mill-to-OEM contracts now dominate agriculture and construction volume in the US Midwest and northern China. This channel compression is most visible in Illinois and Shandong Province, where regional distributors have ceded 30-40% of historical volume to integrated supply arrangements.
Hydraulic Cylinder Rod Market Segmentation
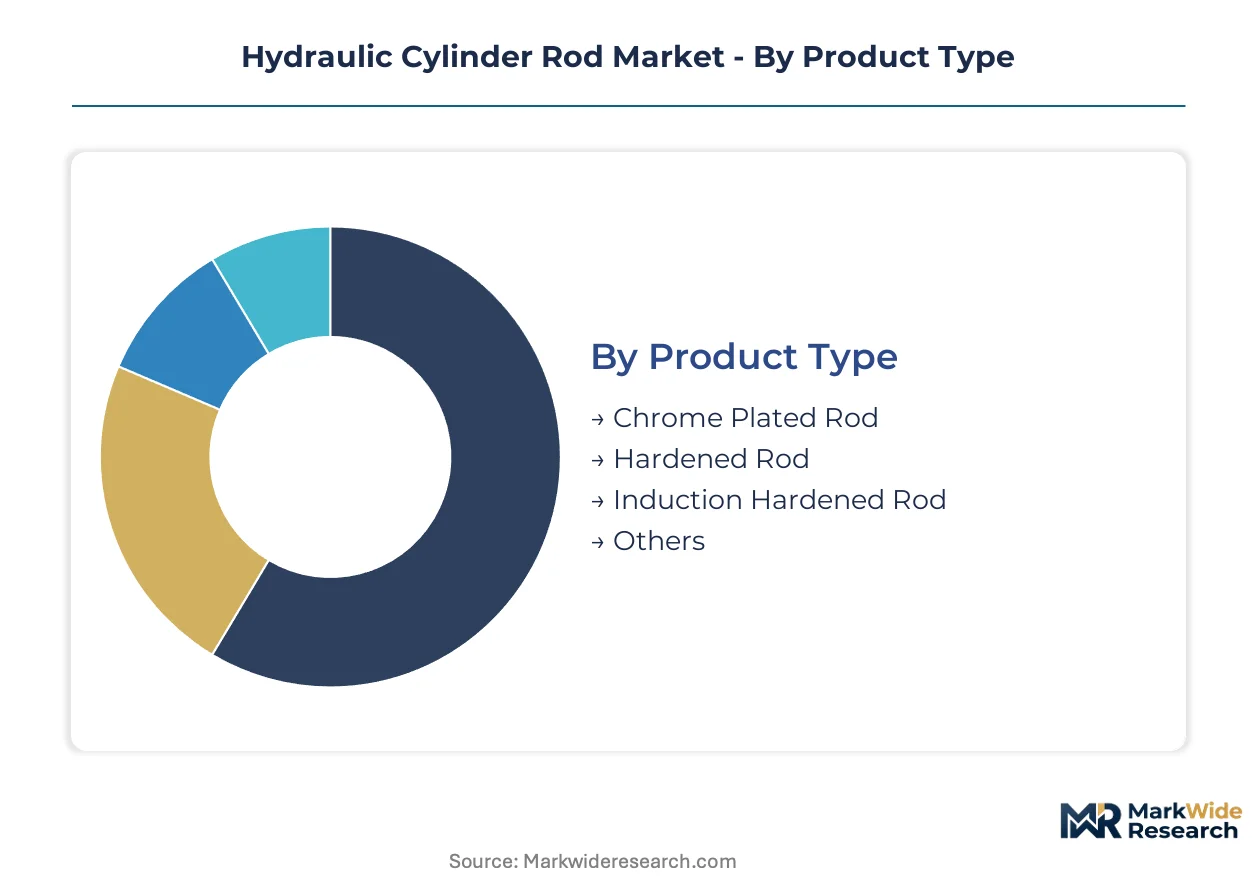
Segmentation in hydraulic cylinder rods maps directly to performance thresholds and regulatory compliance pathways. Specification choices determine coating chemistry investments, alloy procurement strategies, and end-use qualification timelines.
Product Type:
Surface treatment technology defines the competitive axis across rod specifications, with coating durability and environmental liability shaping converter capex decisions.
- Chrome Plated Rod:Electrodeposited chromium layer delivers sub-micron surface finish and corrosion resistance for seal longevity. Demand concentrates in North American agriculture equipment where EPA discharge limits are forcing plating shop consolidation, not product abandonment.
- Induction Hardened Rod:Case-hardened surface through electromagnetic heating achieves depth-controlled hardness gradients without coating chemistry. Automotive press lines in Germany and China specify these rods for high-cycle fatigue resistance as stamping speeds accelerate.
- Hardened Rod:Through-hardened alloy formulations serve medium-duty construction hydraulics with simpler heat-treatment protocols.
- Others:Laser-clad and thermal spray variants occupy emerging niches in abrasive mining applications.
Mature deployment sits with Chrome Plated Rod. Newer deployment is concentrated in Induction Hardened Rod.
Material:
Alloy composition governs strength-to-weight ratios and corrosion performance, with raw material volatility distorting batch economics for converters.
- Alloy Steel:Nickel-molybdenum formulations deliver tensile strength exceeding 1000 MPa for high-pressure construction cylinders. Procurement clusters around Shanghai and Busan port hubs where integrated mills control ingot supply.
- Carbon Steel:Standard-grade formulations dominate unit volume in cost-sensitive agriculture hydraulics across the US Midwest and northern China.
- Stainless Steel:Marine-grade variants command margin premiums in offshore wind installations where salt exposure degrades standard platings.
- Brass:Non-sparking properties serve specialized mining and chemical processing equipment with limited volume scale.
Volume leadership rests with Carbon Steel. Margin expansion concentrates in Stainless Steel.
Manufacturing Process:
Process selection reflects bore diameter, lot size, and dimensional tolerance requirements, with automation investments favoring high-throughput forging and machining lines.
- Forging:Closed-die hammer and press forging align grain structure for heavy-bore construction rods. Chinese mills lead capacity deployment for 100mm+ diameter bars.
- Machining:Precision grinding and polishing achieve Ra 0.2 micron finishes for seal compatibility. German equipment suppliers dominate high-accuracy grinding machine supply.
- Extrusion:Continuous profile forming serves small-bore specialty cylinders with limited diameter range.
- Welding:Rod end attachment processes for customized actuator assemblies, not primary rod blank production.
Throughput dominance sits with Forging. Precision-critical applications concentrate in Machining.
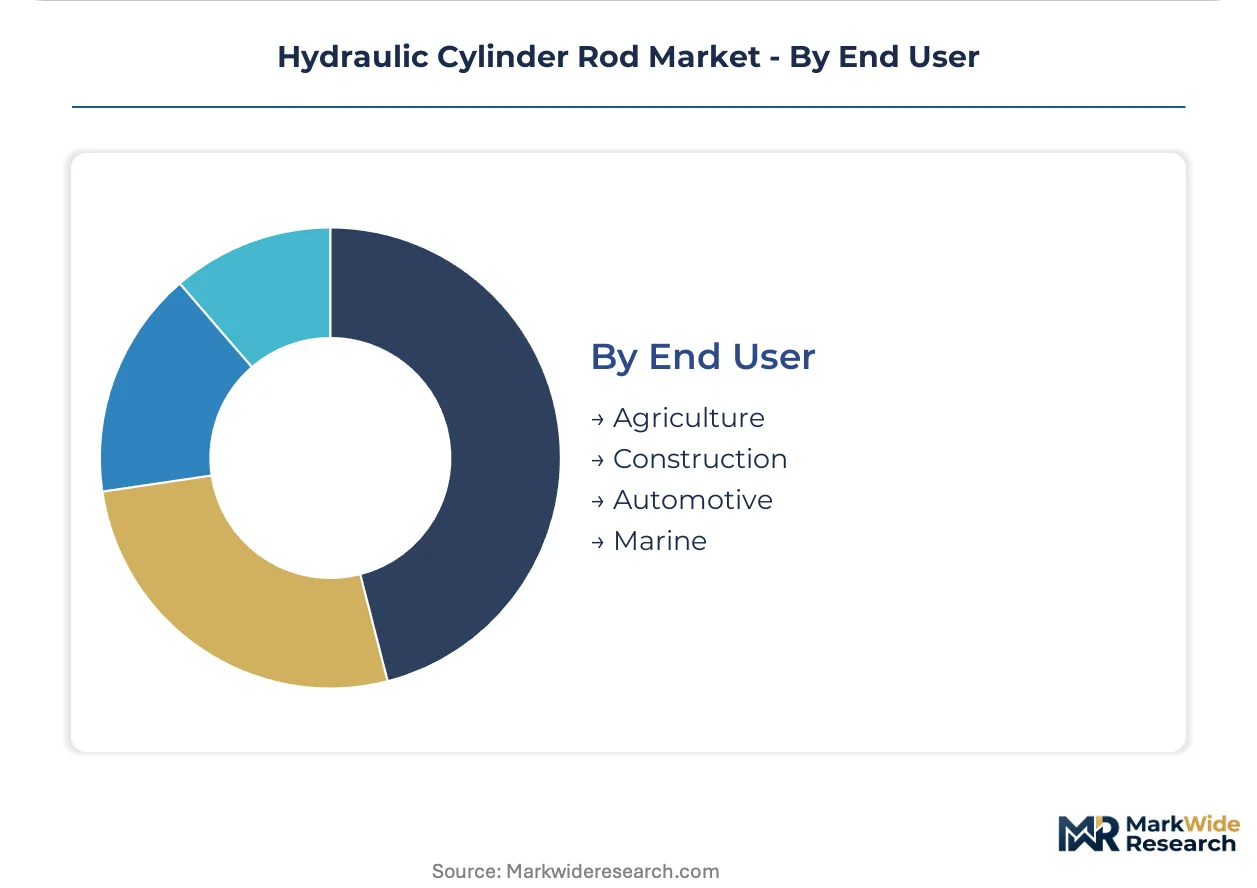
End User:
Application severity and duty cycle frequency determine specification tiering, with warranty terms and regulatory exposure varying sharply across sectors.
- Construction:Earthmoving and lifting equipment demand induction-hardened rods with deep case depths for impact loading. Chinese OEMs are expanding procurement of premium alloy formulations as infrastructure budgets scale.
- Automotive:Press line retrofits drive replacement demand for fatigue-resistant rods in stamping operations with accelerated cycle frequencies.
- Agriculture:Tractor and implement hydraulics sustain chrome-plated rod volume despite coating transition pressures, particularly in North American mid-market equipment.
- Marine:Offshore wind and vessel systems specify stainless steel variants with specialized surface finishes for salt exposure compliance.
Specification intensity peaks in Construction. Coating transition exposure concentrates in Agriculture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-ground bar stock procurement clusters around Shanghai and Busan port hubs, with alloy steel supply chains decoupling from European forging output. Converter investments concentrate where infrastructure budgets and environmental enforcement timelines create simultaneous demand pull and compliance pressure.
China
Construction equipment OEMs in Shandong Province mandate deeper induction hardening case depths for high-cycle hydraulic systems. MEE discharge standards under dual carbon goals accelerate mill capex into laser cladding lines. Shanghai port clusters consolidate precision-ground bar stock procurement, reducing logistics friction for rod converters serving Yangtze River Delta manufacturing.
Germany
Automotive press line retrofits drive specification intensity for fatigue-resistant rods as stamping speeds accelerate. ECHA REACH Article 57 sunset dates force plating shops toward HVOF certification before enforcement windows close. Bavarian forging mills anchor European alloy steel consistency for cylinder OEMs requiring sub-micron surface finishes.
United States
Agriculture equipment sustains chrome-plated rod volume across Illinois and Iowa implement manufacturers despite coating transition pressures. EPA chromium discharge limits under the Clean Water Act strand legacy tank infrastructure without captive chemical recovery. Midwest regional distributors cede volume to direct mill-to-OEM contracts as channel compression intensifies.
India
Domestic content incentives under the PLI scheme for capital goods open local assembly opportunities for precision-ground bar stock converters. BIS certification requirements extend qualification timelines for second-tier rod suppliers entering food-processing hydraulics. Maharashtra and Gujarat industrial corridors attract forging capacity expansion targeting construction equipment demand.
South Korea
Busan port hubs serve as East Asian distribution nodes for alloy steel formulations bound for Japanese and Southeast Asian cylinder assemblers. MFDS surface finish guidelines for pharmaceutical processing equipment redirect coating investments toward ceramic alternatives. Daegu-Gyeongbuk manufacturing clusters specialize in small-bore specialty cylinder extrusion for precision automation.
Hydraulic Cylinder Rod Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chrome-free coating certification ahead of regulatory enforcement windows. The vendor base separates into integrated mills with captive metallurgy, specialized converters with process depth, and regional distributors facing channel compression. Three archetypes dominate: alloy-secured cylinder OEMs, coating-transition specialists, and precision-machining job shops. Competitive moves center on backward integration into bar stock supply and furnace line reconfiguration for thermal spray alternatives.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton occupy positions representing North American availability and specification leadership respectively. Bosch Rexroth exemplifies the European integrated model with captive metallurgy partnerships. KYB Corporation anchors Japanese precision grinding expertise for automotive press line applications. These three names from the raw data represent distinct geographic and capability archetypes without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Bosch Rexroth |
| Eaton |
| KYB Corporation |
| Caterpillar |
| Enerpac Tool Group |
| SMC Corporation |
| HYDAC |
| Wipro Enterprises |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap forging specialists in Shandong Province and Bavaria anchor supply discipline through generational capital patience, enabling long-term alloy procurement contracts that insulate converter pricing from nickel-molybdenum volatility while squeezing distributor margins in spot-dependent North American agriculture channels.
Pricing Analysis
Warranty bundling separates OEM direct contracts from distributor spot sales, with cylinder assemblers absorbing surface finish liability and extended fatigue guarantees into premium tier pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: REACH-compliant HVOF coatings command margin pools above legacy chrome-plated agricultural volume. Pricing pressure stems from EPA chromium discharge limits forcing plating shop consolidation, stranding mid-market converters without captive chemical recovery. Agriculture OEMs in the US Midwest exhibit highest price sensitivity, while offshore wind contractors in the North Sea accept stainless steel premiums for salt-exposure compliance.
Supply Chain Analysis
Regional distribution centers in Shanghai and Busan port clusters consolidate precision-ground bar stock procurement for East Asian cylinder assemblers. Raw material supply draws from Chinese nickel-molybdenum alloy mills, German forging ingot producers, and South Korean stainless steel specialists. Single-source vulnerability concentrates in Shanghai port logistics nodes where Yangtze River Delta manufacturing clusters depend on integrated mill output. Distribution runs through direct mill-to-OEM contracts that have displaced 30-40% of historical regional distributor volume in Illinois and Shandong Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH Article 57 sunset dates on hexavalent chromium erect barrier-to-entry moats for plating shops with certified HVOF and laser cladding infrastructure, freezing out second-tier converters unable to fund furnace reconfiguration capex.
For Market Incumbents: Hedge coating-transition risk by accelerating captive metallurgy partnerships ahead of enforcement windows, locking alloy steel consistency for induction-hardened rod lines while emerging Chinese converters without REACH certification face export market closure. Prioritize backward integration into precision-ground bar stock supply to defend margin position against channel compression from direct mill-to-OEM contracts.
For New Entrants and Emerging Players: The premium-economy price gap in North American agriculture equipment offers white-space entry below Parker Hannifin Corporation's vertically controlled chrome plating networks, targeting mid-market implement manufacturers in Iowa and Illinois with unbundled warranty terms. Penetrate India's PLI scheme corridors in Maharashtra and Gujarat with BIS-certified induction-hardened rods for domestic construction equipment assembly, bypassing established East Asian supply clusters.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating-transition specialists in Germany with ECHA-certified HVOF lines but stranded without automotive OEM scale, available at compressed multiples as REACH enforcement accelerates. Long-term viability centers on ceramic coating cost parity achievement before the next regulatory tightening closes process windows. Watch for laser cladding throughput breakthroughs signaling inflection in chrome displacement economics.
| Strategic Initiative | Industry Significance |
|---|---|
| HVOF Coating Line Certification | ECHA REACH compliance secures European market access before sunset dates strand hexavalent chrome capacity. |
| Captive Alloy Steel Partnership | Bosch Rexroth's metallurgy integration ensures consistency across high-cycle construction cylinder specifications. |
| Regional Distribution Center Consolidation | Shanghai-Busan hub concentration reduces logistics friction for Yangtze River Delta converter procurement. |
| Automotive Press Line Retrofit Targeting | German OEM cycle-frequency acceleration creates replacement demand for fatigue-resistant induction-hardened rods. |
| Marine Stainless Steel Variant Expansion | Offshore wind salt-exposure specifications command margin premiums beyond carbon steel commoditization. |
Research Methodology
Document review covered ECHA regulatory filings, EPA Clean Water Act discharge enforcement records, and MEE dual carbon policy documents, complemented by interviews with cylinder OEM procurement directors, metallurgical heat-treatment technicians, precision grinding equipment suppliers, and aftermarket service heads at construction equipment fleets. Secondary validation drew from customs trade data on alloy steel bar stock movements, SEC 10-K disclosures from diversified industrial conglomerates, and ISO 9001 certification registries. Bottom-up unit shipment estimates from converter capacity utilization were cross-referenced against top-down infrastructure budget allocations to triangulate demand figures.
Historical shipment patterns were cross-referenced against expert panel inputs from plant engineers at Chinese construction equipment manufacturers and automotive press line operators in Germany. Segmentation modeling tracked surface treatment technology, alloy composition tier, manufacturing process type, and end-use application severity across the projection horizon. CAGRs were derived from regression analysis of procurement cycle frequencies and replacement demand elasticity, incorporating nickel-molybdenum price volatility bands and coating chemistry transition capex schedules as sensitivity inputs.
Inputs from ECHA pre-registration databases and MEE discharge permit registries were available through the study window; gaps in real-time HVOF coating cost parity data introduce uncertainty bands around chrome displacement timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and alloy price mean reversion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Europe Conveyor Belt Market