
 Precision Bearing Market | 2026-2036
Precision Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Bearing Market Analytics
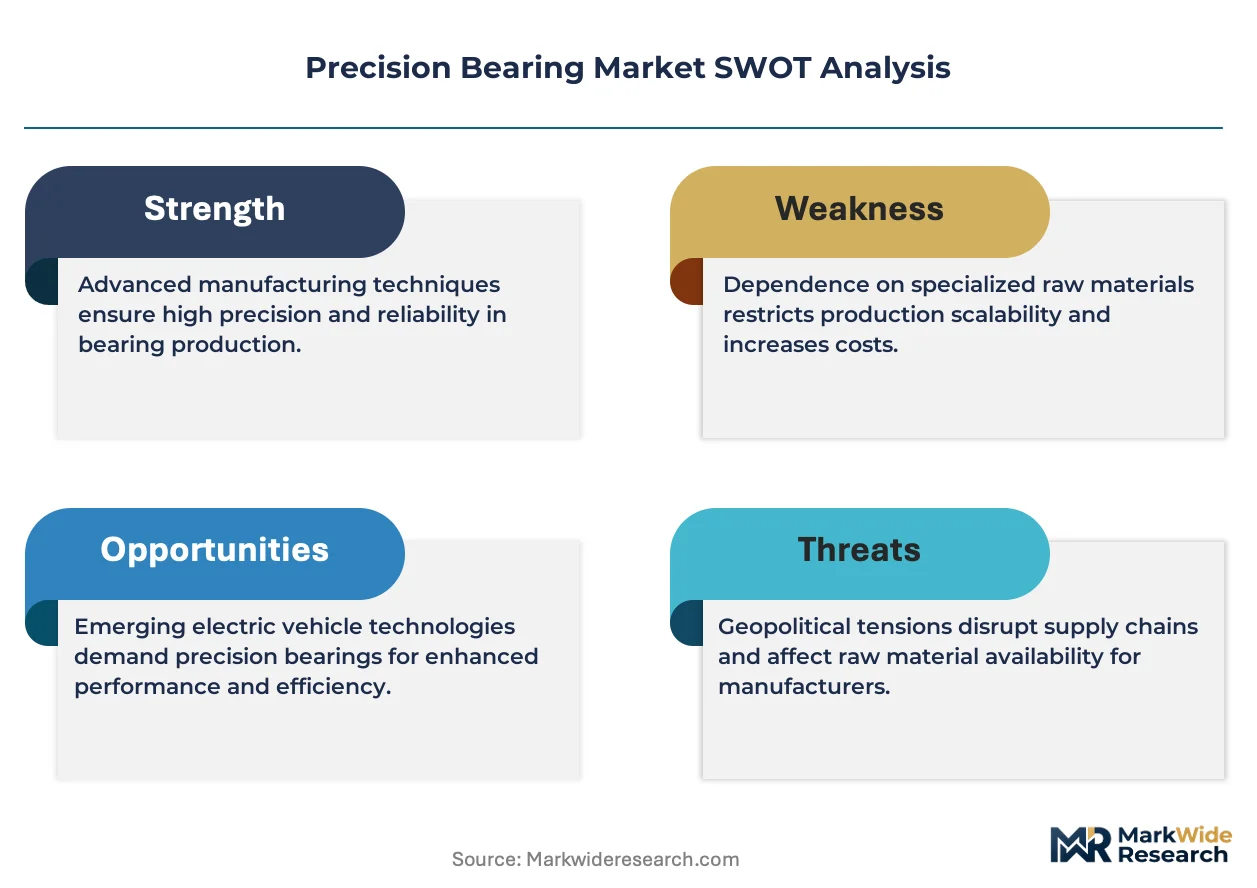
Aerospace and robotics end-use verticals is realigning demand toward ceramic-hybrid and magnetic bearing architectures. SKF AB leverages its integrated condition-monitoring platforms to anchor long-term service contracts with wind turbine OEMs. NSK Ltd. specializes in ultra-high-speed ball bearing designs for electric vehicle powertrains, while Schaeffler Technologies AG & Co. KG sustains manufacturing scale across its European and Asian production networks.
Precision bearings are mechanical components engineered to constrain relative motion to desired degrees of freedom with rotational accuracy typically within micrometers, manufactured through controlled grinding, honing, and superfinishing of raceways with surface roughness below 0.1 micrometers Ra. They serve critical functions in reducing friction, maintaining shaft alignment, and enabling repeatable positioning in high-speed rotating machinery. Ball bearings occupy the largest volume share across industrial machinery installations, whereas magnetic bearings represent the fastest-expanding margin pool due to their elimination of contact wear in semiconductor vacuum processing and flywheel energy storage. Ceramic material formulations, particularly silicon nitride, are displacing conventional stainless steel in high-temperature turbine applications where thermal expansion coefficients govern design constraints.
The EU F-Gas Regulation and REACH framework restrict perfluorinated lubricant chemistries used in precision bearing assemblies, compelling reformulation of sealing and grease systems. The EPA enforces comparable emissions and material safety standards for U.S.-based bearing manufacturers supplying federal aviation programs. Japan's METI coordinates domestic JIS certification requirements that govern dimensional tolerances for bearings exported to precision automation markets. Stakeholders must monitor evolving substance restriction schedules and pre-qualify alternative lubricant platforms before existing formulations lose regulatory authorization.
Market Dynamics
Ceramic-hybrid bearing architectures are displacing conventional steel assemblies in high-temperature turbine applications, driven by thermal expansion coefficient requirements and REACH-mandated lubricant reformulations that favor non-contact sealing systems.
Growth Catalysts
- EU F-Gas Regulation:Perfluorinated lubricant restrictions are accelerating adoption of ceramic-hybrid bearings with dry-running capabilities in semiconductor vacuum processing equipment.
- Electric vehicle powertrains:Ultra-high-speed ball bearing designs for 20,000+ RPM motor speeds are creating dedicated demand from tier-one automotive suppliers.
- Silicon nitride formulations:Advanced ceramic materials with thermal stability above 1,000°C are penetrating aerospace turbofan platforms requiring reduced weight and corrosion resistance.
Market Restraints
- Raw material concentration:High-purity silicon nitride powder production concentrates in Japan and Germany, creating supply vulnerability for ceramic bearing manufacturers outside these clusters.
- REACH compliance costs:ECHA substance restriction schedules force premature obsolescence of qualified lubricant platforms, compressing product development cycles.
- Magnetic bearing substitution:Contactless magnetic bearing systems eliminate wear entirely in flywheel energy storage, threatening margin pools in conventional precision bearing segments.
Strategic Opportunities
- Wind turbine aftermarket:Condition-monitoring-anchored service contracts for offshore installations in the North Sea and Baltic regions offer recurring revenue streams.
- Japan METI certification alignment:JIS dimensional tolerance pre-qualification opens precision automation markets in East Asian manufacturing clusters.
- Semiconductor equipment:Vacuum-compatible ceramic-hybrid architectures for EUV lithography systems represent unpenetrated specification tiers.
Industry Challenges
- Superfinishing skill scarcity:Raceway surface roughness below 0.1 micrometers Ra requires specialized grinding technicians, with training pipelines failing to match replacement demand.
- Dual certification timelines:Simultaneous FAA airworthiness and EPA material safety approvals for aerospace bearings extend qualification periods by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Bearing Market |
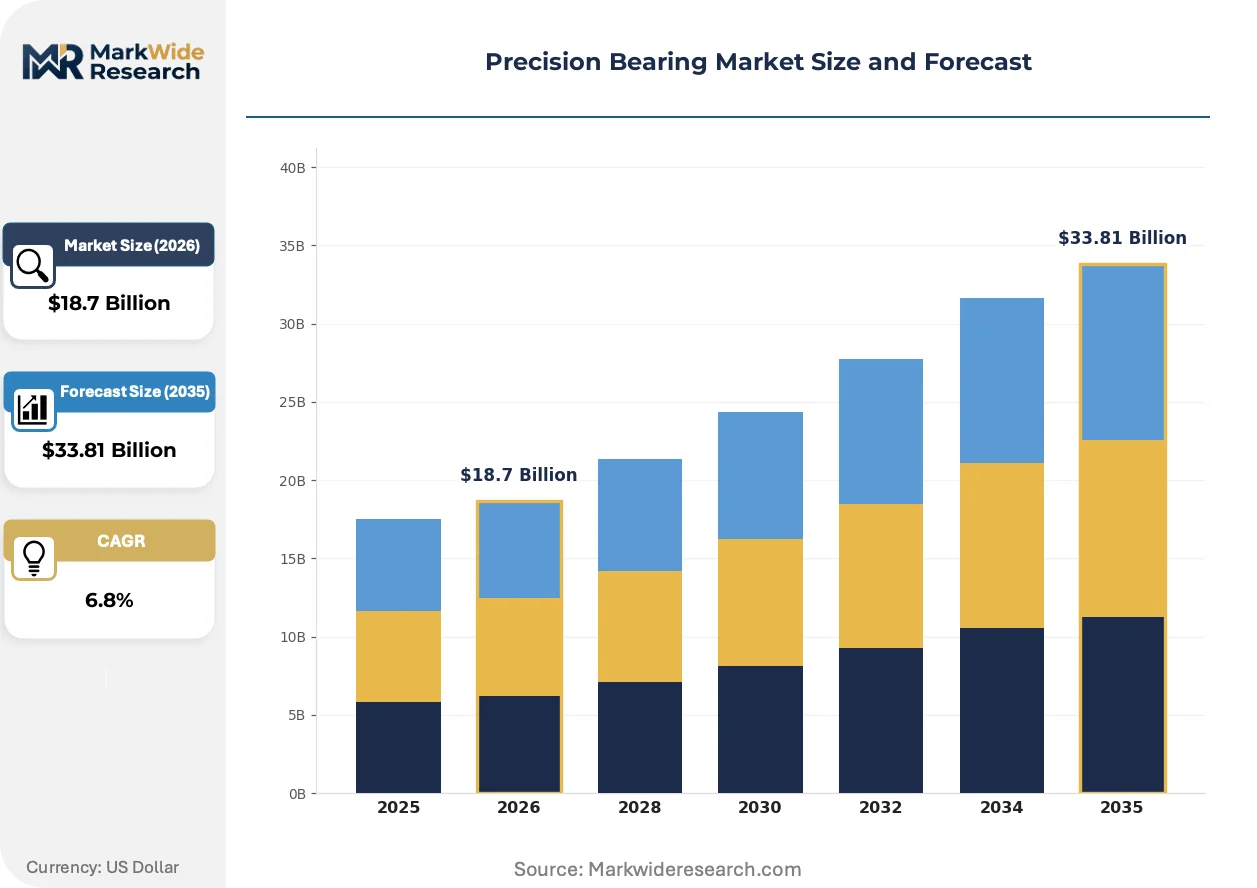
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Thrust Bearings, Magnetic Bearings Material: Stainless Steel, Ceramic, Polymer, Bronze End User: Aerospace, Automotive, Industrial Machinery, Robotics Operation Type: High-Speed, Low-Speed, High-Load, Standard |
| Companies Covered | SKF AB, NSK Ltd., Schaeffler Technologies AG & Co. KG, NTN Corporation, JTEKT Corporation, Timken Company, Minebea Mitsumi Inc., THK Co. Ltd., RBC Bearings Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Bearing Market Evolving Landscape
Active magnetic bearing systems and ceramic-hybrid architectures are converging to eliminate contact wear in critical rotating machinery, while regulatory pressure on fluorinated chemistries forces parallel innovation in sealing and lubrication platforms.
Silicon nitride ceramic ball technology is integrating into hybrid bearing designs that combine ceramic rolling elements with steel raceways, delivering weight reduction and thermal stability for gas turbine shafts. Aerospace OEMs are qualifying these architectures for next-generation turbofan platforms at accelerated schedules. The technology is integrating condition-monitoring capabilities directly into bearing housings, compressing maintenance intervals and enabling predictive replacement models.
REACH substance restriction schedules and the EU F-Gas Regulation are prohibiting perfluoropolyether lubricants historically used in vacuum and high-temperature bearing applications. Manufacturers are reformulating grease systems around perfluorinated alkyl substance-free chemistries while maintaining viscosity and oxidation stability. Semiconductor equipment builders in Germany and the Netherlands are pre-qualifying alternative platforms before existing formulations lose authorization.
Aftermarket service contracts are unbundling from original equipment sales as wind turbine operators seek performance-guaranteed bearing replacement programs. Independent service providers are capturing maintenance volumes previously held by OEM captive networks. This shift concentrates in offshore wind clusters where access costs favor predictive maintenance over reactive replacement.
Precision Bearing Market Segmentation
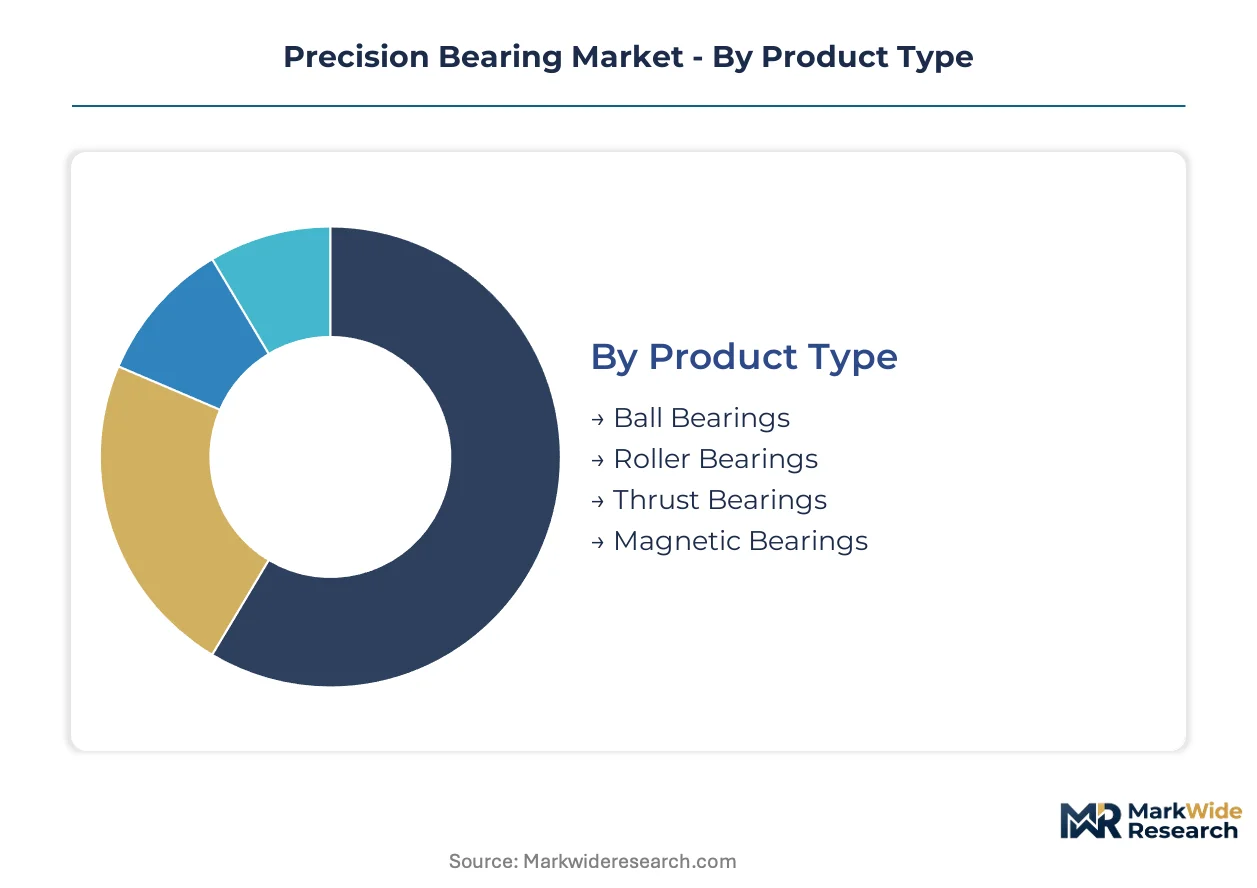
Precision bearing buyers select architectures based on rotational speed requirements, thermal constraints, and regulatory compliance obligations. Segmentation reveals how material choices and operational specifications create divergent margin structures across end-use verticals.
Product Type:
Buyers differentiate primarily by contact mechanics and speed tolerance thresholds.
- Ball Bearings:Deep-groove and angular-contact designs dominate industrial machinery installations with rotational accuracy within micrometers. Demand concentrates in Germany and Japan where precision manufacturing clusters require surface roughness below 0.1 micrometers Ra for repeatable positioning.
- Roller Bearings:Cylindrical and tapered configurations distribute radial loads across line contact geometries for heavy-duty applications. Automotive powertrain suppliers in the United States specify these for transmission systems where shaft alignment maintenance is critical.
- Thrust Bearings:Axial load management for vertical shaft arrangements in turbine assemblies.
- Magnetic Bearings:Contactless suspension eliminates wear in semiconductor vacuum processing and flywheel energy storage systems.
Ball bearings lead volumes today; magnetic bearings are gaining share fastest.
Material:
Cost tiers separate specification-driven buyers from price-sensitive procurement.
- Stainless Steel:AISI 440C and equivalent alloys provide corrosion resistance and dimensional stability for standard industrial applications. Wind turbine OEMs specify these for offshore installations where salt exposure accelerates degradation of conventional carbon steels.
- Ceramic:Silicon nitride formulations deliver thermal stability above 1,000°C with 60% lower density than steel equivalents. Aerospace turbofan platforms in the United States and EU are qualifying ceramic-hybrid architectures for next-generation engines where reduced weight improves fuel efficiency.
- Polymer:PTFE and PEEK composites serve food processing and medical equipment with FDA-compliant dry-running capabilities.
- Bronze:Sintered and cast bronze alloys provide conformability and embeddability for marginal lubrication conditions in legacy industrial equipment.
Stainless steel retains the largest installed base; ceramic formulations show the steepest expansion trajectory.
End User:
Application maturity determines whether buyers prioritize performance optimization or total cost reduction.
- Aerospace:FAA airworthiness certification and EPA material safety approvals govern bearing selection for turbofan engines and flight control systems. OEMs in the United States and France are expanding procurement of ceramic-hybrid spindle bearings for platforms requiring reduced thermal expansion coefficients.
- Automotive:Electric vehicle powertrain specifications demand ultra-high-speed ball bearings rated for 20,000+ RPM motor speeds. Tier-one suppliers in Japan and Germany are qualifying dedicated designs for battery electric vehicle production ramps.
- Industrial Machinery:Machine tool and automation equipment builders specify precision bearings for positioning repeatability in manufacturing cells.
- Robotics:Collaborative and industrial robot joints require compact bearing arrangements with integrated condition monitoring for predictive maintenance.
Industrial machinery anchors current procurement volumes; robotics applications are climbing the fastest.
Operation Type:
Volume concentration versus margin concentration splits along speed and load specifications.
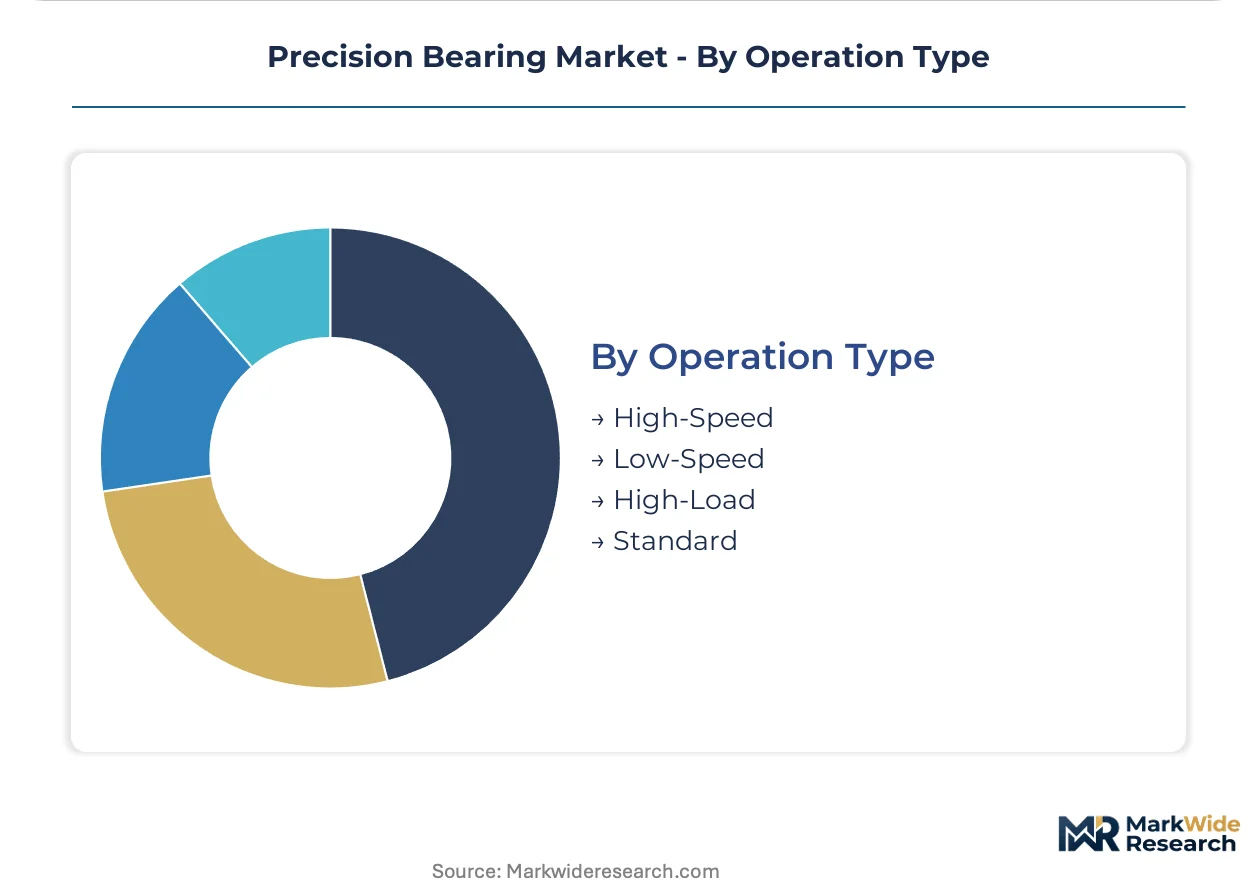
- High-Speed:DN values exceeding 500,000 require precision cage designs and ceramic rolling elements to manage centrifugal forces. Semiconductor equipment builders in the Netherlands specify these for EUV lithography systems where vacuum compatibility eliminates conventional lubrication options.
- High-Load:Static and dynamic load ratings prioritize raceway fatigue life over rotational velocity for mining and construction equipment.
- Low-Speed:Oscillating and intermittent motion applications in medical imaging equipment emphasize friction torque consistency.
- Standard:General-purpose industrial bearings serve replacement markets with established supply chains and catalog pricing.
Standard operation types dominate unit shipments; high-speed specifications command premium pricing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate to jurisdictions with streamlined REACH compliance pathways and consolidated supplier ecosystems. Cost-of-compliance gaps between the EU and Asia-Pacific are accelerating qualification of alternative ceramic powder sourcing outside traditional German and Japanese clusters.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria anchor European ceramic-hybrid bearing qualification for aerospace OEMs. ECHA substance restriction schedules under REACH compel reformulation of perfluorinated lubricant platforms before 2027 authorization deadlines. Stuttgart-based supplier networks are pre-qualifying silicon nitride architectures for next-generation turbofan platforms.
Japan
Ultra-high-speed ball bearing demand from electric vehicle powertrain suppliers concentrates in Aichi and Kanagawa prefectures. METI coordinates JIS certification requirements that govern dimensional tolerances for bearings exported to precision automation markets. Nagoya-area manufacturing cells are qualifying dedicated designs for 20,000+ RPM motor specifications.
United States
FAA airworthiness certification requirements and EPA material safety standards govern bearing selection for federal aviation programs. The Timken Company and RBC Bearings anchor domestic production networks serving defense and commercial aerospace procurement. Ohio and Connecticut manufacturing bases are expanding ceramic-hybrid spindle bearing output for next-generation engine platforms.
China
Industrial machinery installations in Jiangsu and Zhejiang provinces drive volume demand for deep-groove ball bearings with micrometer-level rotational accuracy. MIIT national standards for precision components are converging with ISO specifications to reduce technical barriers for export-oriented manufacturers. Suzhou and Hangzhou precision manufacturing clusters are qualifying local ceramic powder suppliers to reduce import dependency.
Netherlands
Semiconductor equipment builders in Eindhoven specify vacuum-compatible ceramic-hybrid architectures for EUV lithography systems. EU F-Gas Regulation restrictions on perfluorinated chemistries are accelerating adoption of dry-running bearing designs in cleanroom environments. ASML supplier ecosystems are pre-qualifying alternative lubricant platforms before existing formulations lose regulatory authorization.
Precision Bearing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated technology providers capturing premium pricing in condition-monitored installations while component fabricators serve replacement markets. The vendor base organizes around three strategic archetypes: full-service platform providers with predictive maintenance capabilities, ceramic material specialists with captive powder supply, and precision grinding houses with superfinishing expertise. M&A activity concentrates on sensor technology integration and geographic expansion into Southeast Asian manufacturing clusters.
Among European integrated providers, SKF AB and Schaeffler Technologies AG & Co. KG exemplify the platform-provider archetype through condition-monitoring-anchored service models. NSK Ltd. occupies a position within the ceramic-specialist tier, leveraging Japanese silicon nitride supply chain proximity. These three entities represent divergent strategic postures: SKF emphasizes aftermarket recurring revenue, Schaeffler sustains manufacturing scale across dual-continent production networks, and NSK concentrates on ultra-high-speed design qualification for electrified powertrains.
| Leading Market Players |
|---|
| SKF AB |
| NSK Ltd. |
| Schaeffler Technologies AG & Co. KG |
| NTN Corporation |
| JTEKT Corporation |
| Timken Company |
| Minebea Mitsumi Inc. |
| THK Co. Ltd. |
| RBC Bearings Incorporated |
| Others |
Value Network & Pricing Analysis
Ceramic-hybrid certification tiers bifurcate procurement economics between aerospace-qualified suppliers and industrial-grade commodity producers, with REACH-mandated lubricant reformulations compressing margins in the latter while concentrating pricing power among German and Japanese powder-integrated specialists.
Pricing Analysis
Distributor margin layers absorb 15-25 points between OEM direct contracts and aftermarket replacement channels, with three-tier pricing separating FAA-certified aerospace assemblies from JIS-tolerance industrial units and uncataloged spot-market generics. Price differentiation hinges on silicon nitride purity grades and METI certification status. Cost compression in commodity ball bearings intensifies as Chinese manufacturers qualify local ceramic powder sources. Tier-one automotive suppliers exhibit lowest price sensitivity; maintenance-replacement buyers in legacy industrial equipment show highest.
Supply Chain Analysis
Refurbishment flows from offshore wind turbine installations in the North Sea are creating secondary supply streams for reconditioned bearing assemblies, with independent service providers capturing volumes previously held by OEM captive networks. Raw material sourcing draws from high-purity silicon nitride production clusters in Japan and Germany, with secondary ceramic powder qualification emerging in China. Single-source vulnerability concentrates in Japanese silicon nitride feedstock for aerospace-grade formulations. Distribution runs through authorized distributor networks for certified tiers and direct procurement for high-volume OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EU F-Gas authorization deadlines accelerating pre-qualification spending ahead of 2027 reformulation cutoffs.
For Market Incumbents: Anticipate magnetic bearing substitution in flywheel energy storage by anchoring long-term service contracts with condition-monitoring platforms. Defend against emerging ceramic-specialist entrants through backward integration into silicon nitride powder supply or captive superfinishing capacity expansion in Baden-Württemberg. Prioritize dual FAA-EPA certification pipelines to compress 18-24 month approval timelines.
For New Entrants and Emerging Players: REACH in Europe opens a window for perfluorinated alkyl substance-free lubricant platforms pre-qualified to semiconductor equipment builders in the Netherlands. Target vacuum-compatible ceramic-hybrid architectures for EUV lithography systems where incumbent qualification gaps persist. Pursue JIS dimensional tolerance certification as the go-to-market angle for East Asian precision automation penetration.
For Investors and Strategic Acquirers: Consolidation pressure builds where superfinishing skill scarcity intersects with dual-certification timeline compression. Five-to-ten year viability favors platform providers with predictive maintenance recurring revenue over component fabricators exposed to spot-market pricing. Target acquisition archetypes include sensor-technology integrators and Southeast Asian grinding houses with METI-aligned certification pipelines. Monitor ECHA substance restriction schedule announcements as inflection indicators for lubricant platform obsolescence cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Supply | Captive silicon nitride sourcing in Japan and Germany insulates against raw material concentration risks. |
| Condition-Monitoring Platform Integration | SKF's predictive maintenance contracts with wind turbine OEMs demonstrate recurring revenue anchoring. |
| Dual Certification Pipeline Investment | Simultaneous FAA airworthiness and EPA material safety approvals compress aerospace bearing qualification periods. |
| Alternative Lubricant Pre-Qualification | ASML supplier ecosystems in the Netherlands are accelerating dry-running bearing adoption ahead of F-Gas deadlines. |
| Southeast Asian Grinding Capacity Expansion | Suzhou and Hangzhou clusters qualify local ceramic powder suppliers to reduce import dependency from Japanese sources. |
Research Methodology
Direct dialogue with bearing design engineers, OEM procurement directors, aftermarket service managers, and ECHA regulatory compliance officers grounded qualitative insights, cross-referenced with SEC 10-K filings from listed manufacturers, JIS certification registries, ECHA substance restriction schedules, and customs trade data for silicon nitride powder flows. Bottom-up unit economics triangulated against top-down aerospace and automotive production forecasts.
Segment-level projections across product type, material formulation, end-use vertical, and operational speed specification fed into a unified analytical framework spanning the projection horizon. CAGRs derived from regression analysis against turbofan platform ramp schedules, electric vehicle motor speed requirements, and semiconductor capital expenditure cycles. Industry-specific inputs included DN value thresholds for high-speed classifications and REACH authorization sunset timelines.
Revisions become necessary when ECHA accelerates substance restriction schedules, Japanese silicon nitride export controls materialize, or magnetic bearing cost curves intersect conventional hybrid architectures. Practitioners should monitor ECHA authorization deadline announcements, METI certification requirement updates, and FAA airworthiness directive issuances for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Front Forks Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Global Bearings Market
Vehicle Components
RV Battery Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
5th Wheel Hitches Market