
 Surround View System Market | 2026-2036
Surround View System Market Size, Share, and Industry Trends Forecast 2026-2036
Surround View System Market Analysis
Silicon-based image processors is rebalancing cost-performance economics for surround view modules. Continental AG leverages captive semiconductor partnerships to secure supply continuity for multi-camera controllers. Robert Bosch GmbH sustains R&D intensity in AI-driven stitching algorithms that reduce hardware complexity. NXP Semiconductors anchors its position through automotive-grade system-on-chip platforms purpose-built for real-time video fusion.
A surround view system comprises multiple ultra-wide-angle cameras mounted around a vehicle perimeter, whose feeds undergo real-time geometric correction and seamless blending into a single top-down or three-dimensional representation displayed to the driver; systems typically operate at 30 frames per second with latency below 50 milliseconds to prevent motion sickness and ensure parking maneuver safety. Factory fit installations dominate volume as OEMs pre-integrate camera modules during vehicle assembly, while AI Integration represents the fastest-expanding technology segment as neural networks replace rule-based image stitching. Aftermarket Installers occupy a narrower but margin-rich niche serving vehicle fleet retrofits and specialty commercial applications.
NHTSA mandates rear-visibility standards for light vehicles sold in the United States, while Euro NCAP scoring protocols incentivize surround view inclusion for top-tier safety ratings, and Japan's METI promotes camera-based advanced driver assistance as part of its automated driving roadmap. These frameworks compel Tier-1 Suppliers to certify systems against divergent regional test protocols, fragmenting validation budgets. Stakeholders must monitor how software-defined vehicle architectures shift camera processing from distributed electronic control units to centralized compute platforms, altering supplier value capture.
Market Dynamics
Software-defined vehicle architectures are redistributing processing load from distributed camera modules to centralized compute platforms, compressing supplier value capture and forcing Tier-1s to recalibrate hardware-software bundling strategies.
Growth Catalysts
- NHTSA rear-visibility mandates:Federal requirements for backup camera coverage in light vehicles sold in the United States create baseline demand for multi-camera visibility infrastructure.
- Silicon image processors:Advanced semiconductor nodes are collapsing per-module cost curves while sustaining 30 frames-per-second performance thresholds.
- Premium passenger vehicle standardization:German and Japanese OEMs now specify surround view as factory-fit equipment across electric vehicle platforms.
Market Restraints
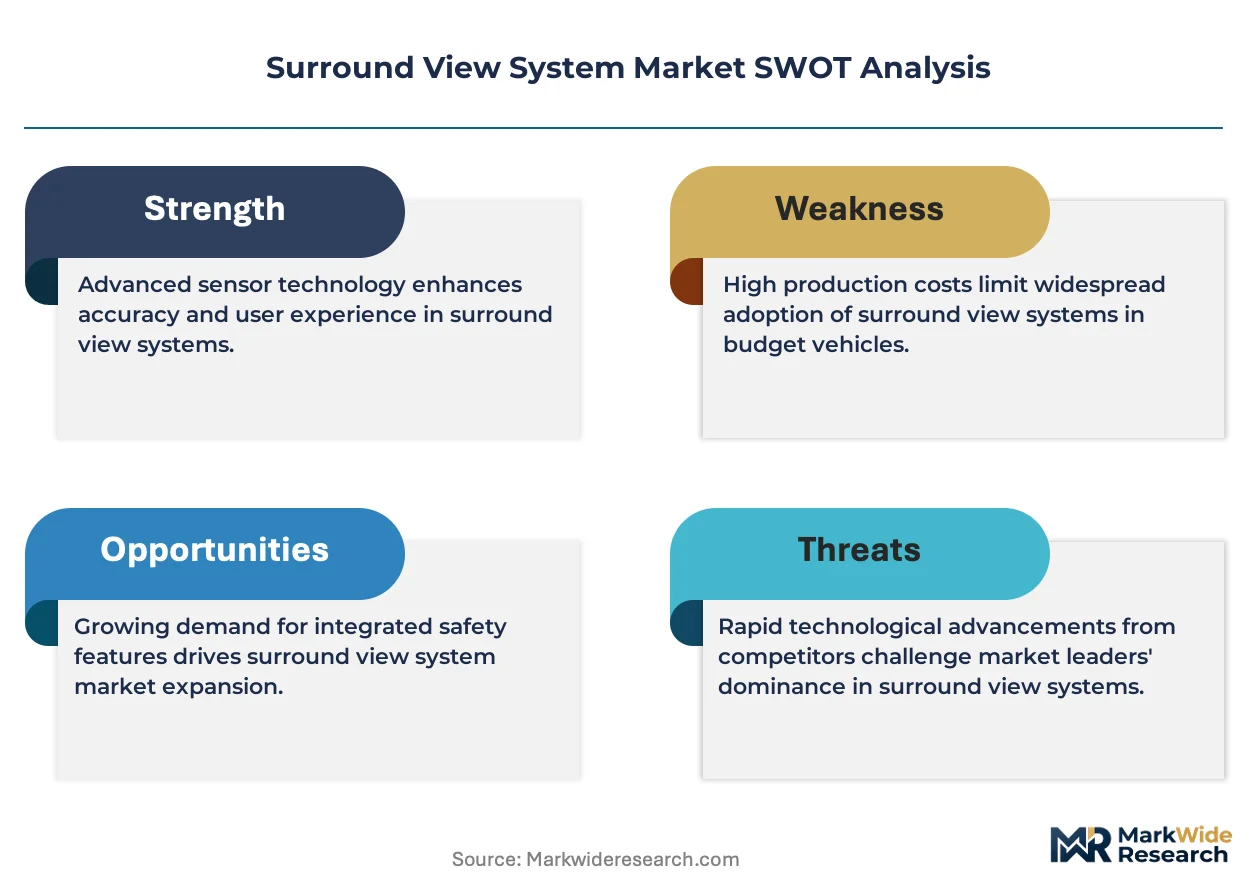
- Automotive-grade semiconductor supply concentration:Foundry capacity for image signal processors clusters in Taiwan and South Korea, exposing Tier-1s to single-source fragility.
- Multi-protocol certification burden:Divergent NHTSA, Euro NCAP, and METI test requirements fragment validation budgets across regional variants.
- Ultrasonic sensor substitution:Parking assistance systems in economy vehicle segments retain acoustic ranging for cost-sensitive applications.
Strategic Opportunities
- Commercial fleet aftermarket retrofit:Logistics operators in Germany seek camera-based blind-spot elimination for existing heavy-duty vehicle pools.
- AI-driven neural stitching:Machine learning algorithms are displacing rule-based image fusion, reducing hardware complexity and enabling software upgrades.
- Euro NCAP safety scoring incentives:Top-tier rating protocols reward surround view inclusion, pulling adoption into mid-market vehicle segments.
Industry Challenges
- Embedded vision software talent scarcity:Real-time geometric correction and latency optimization require specialized firmware engineering capabilities concentrated at semiconductor vendors.
- Legacy electronic control unit integration:Centralized compute migration demands reconciliation with existing distributed architectures during platform transition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surround View System Market |
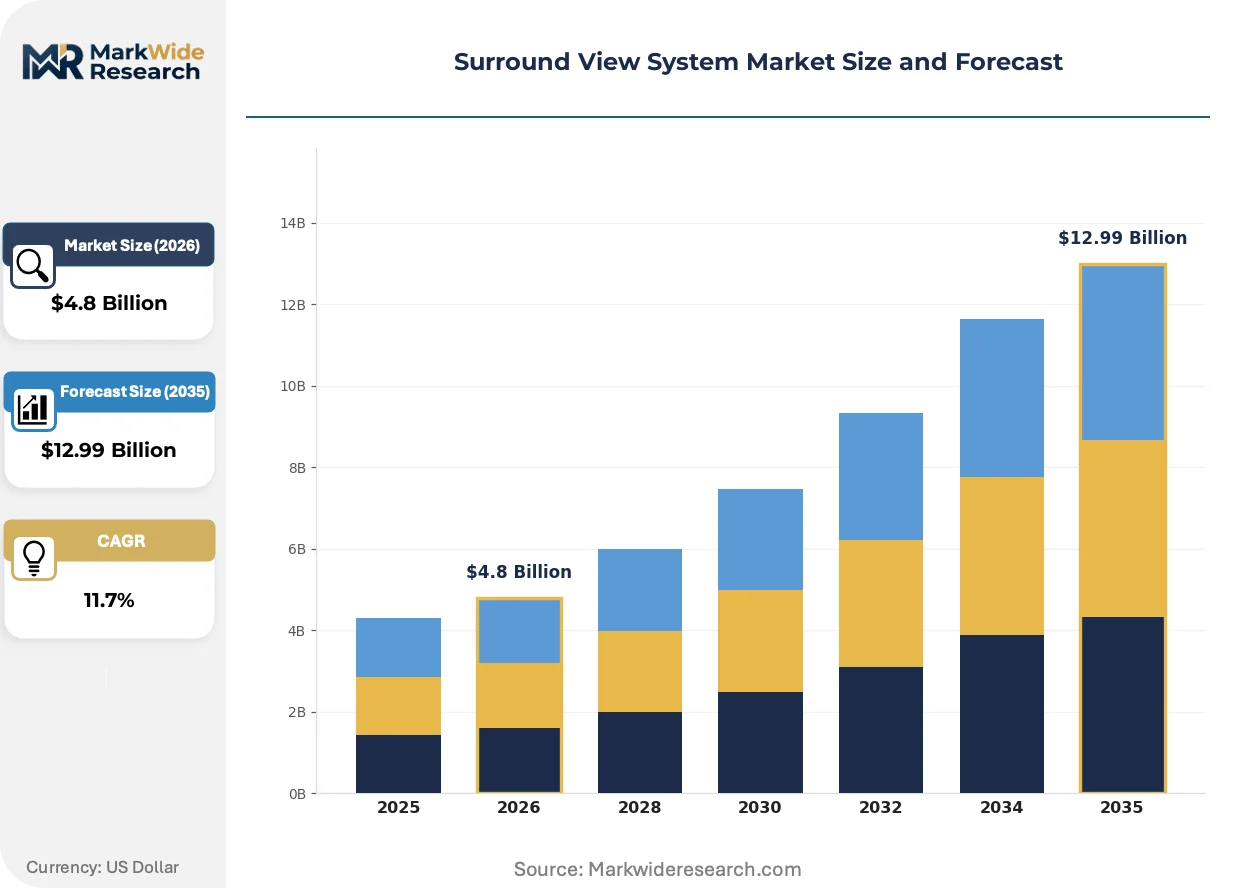
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-camera System, 360-degree View, Rear-View Camera, Front-View Camera Technology: Image Processing, AI Integration, Sensor Fusion, Ultra HD End User: OEMs, Tier-1 Suppliers, Aftermarket Installers, Vehicle Assemblers Installation Type: Factory Fit, Aftermarket Fit, Retrofit, Modular Installation |
| Companies Covered | Continental AG, Magna International, Robert Bosch GmbH, Denso Corporation, Valeo SA, Texas Instruments, NXP Semiconductors, Aptiv, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surround View System Market Emerging Trajectories
Neural network architectures are displacing deterministic algorithms across the imaging pipeline, compressing development cycles while elevating software monetization potential for component suppliers.
Deep learning-based image stitching is automating the geometric correction and seamless blending previously executed through fixed-parameter pipelines. Tier-1 suppliers deploy these models across next-generation electric vehicle platforms launching from 2026. This compression of hardware dependency is enabling over-the-air feature upgrades and recurring software revenue streams.
Euro NCAP's evolving safety assessment protocols now weight camera-based visibility systems in overall vehicle scoring calculations. European OEMs respond by pre-integrating surround view modules into base trim configurations rather than reserving them for premium variants. This regulatory pull is standardizing multi-camera architectures across vehicle classes previously served by simpler sensor arrays.
Fleet procurement officers now specify camera-based advanced driver assistance as a contractual requirement for commercial vehicle acquisitions. Leasing companies and logistics operators in Japan and Germany embed these specifications into multi-year vehicle supply agreements. This specification migration transfers technology selection authority from individual drivers to centralized fleet management functions with standardized safety mandates.
Surround View System Market Segmentation
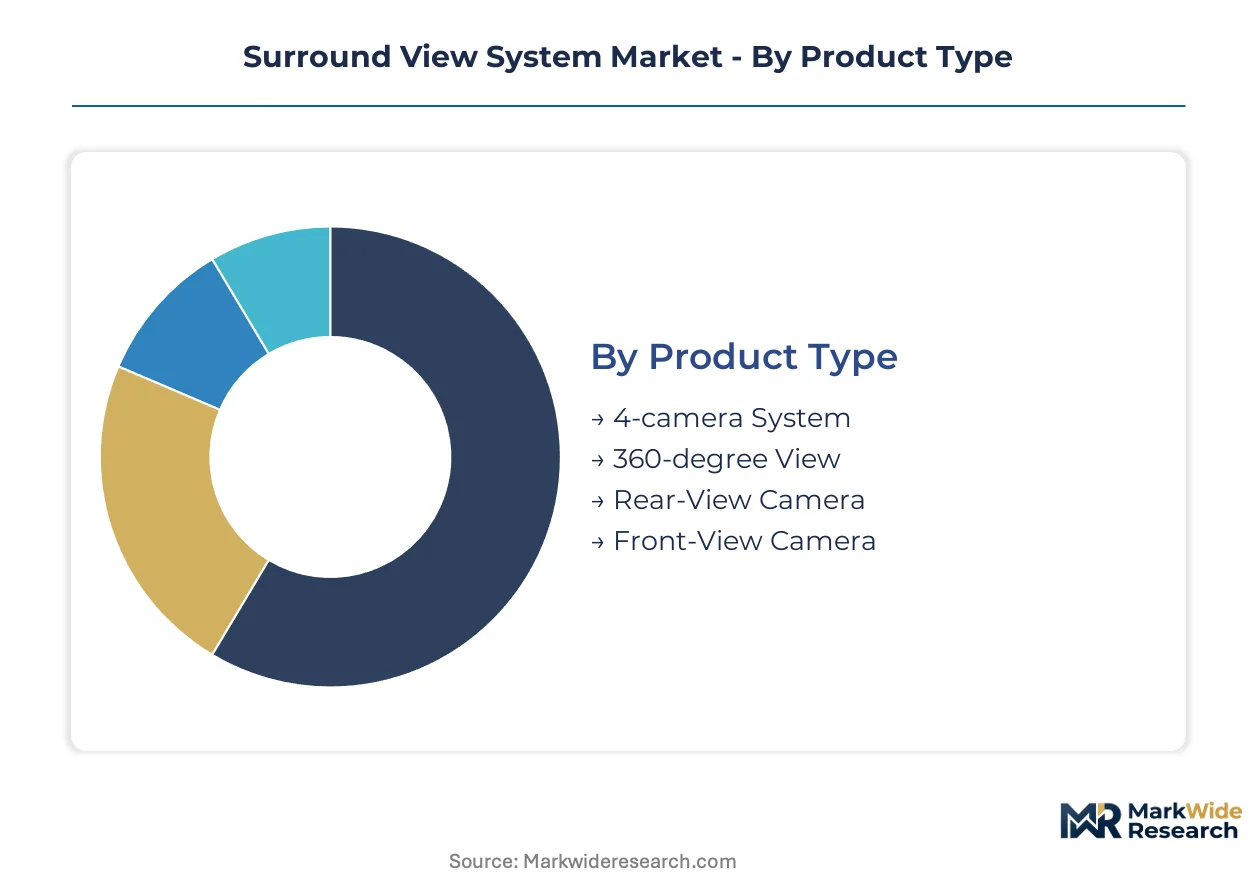
Surround view system architectures fragment across hardware complexity, software sophistication, and integration depth. Each segmentation axis reveals distinct margin profiles and supplier competitive moats. OEM procurement strategies target specific combinations of these dimensions based on platform positioning and regulatory exposure.
Product Type:
Capital intensity escalates with camera count and field-of-view coverage, with multi-camera arrays demanding substantial upfront validation and calibration infrastructure.
- 4-camera System:Four ultra-wide-angle modules positioned at vehicle corners feed synchronized streams into centralized processors. German premium OEMs specify these configurations for electric vehicle platforms requiring comprehensive parking assistance and low-speed maneuvering visibility.
- 360-degree View:Seamless spherical projection synthesizes overlapping camera feeds into a continuous overhead representation. Japanese automakers integrate this capability into base trim levels to satisfy METI automated driving roadmap milestones and differentiate against acoustic-only parking systems.
- Rear-View Camera:Single-module solution addressing NHTSA rear-visibility mandates with minimal hardware overhead.
- Front-View Camera:Forward-facing unit supporting intersection navigation and narrow-path positioning in urban environments.
Most installed capacity flows through 4-camera System configurations. Expansion is steepest in 360-degree View as Euro NCAP scoring protocols pull adoption into mid-market segments.
Technology:
Software-defined architectures are redistributing value capture toward algorithmic sophistication and away from dedicated hardware modules.
- AI Integration:Neural networks replace geometric correction pipelines with learned stitching models that adapt to lens distortion and lighting variation. Tier-1 suppliers monetize these capabilities through over-the-air feature activation and recurring software licenses.
- Sensor Fusion:Camera-radar-ultrasonic integration delivers redundancy for automated parking and low-speed autonomous operation. US-based electric vehicle manufacturers specify fused architectures to satisfy NHTSA testing protocols for advanced driver assistance systems.
- Image Processing:Dedicated signal processors execute real-time dewarping and color matching at 30 frames per second.
- Ultra HD:High-resolution sensors enable zoom functionality and distant object recognition for highway merge assistance.
Revenue concentration sits with Image Processing hardware. AI Integration is gaining share fastest as semiconductor vendors release automotive-grade inference accelerators.
End User:
Supply chain position determines specification authority and volume commitment horizons across the value chain.
- OEMs:Vehicle manufacturers dictate system architecture, camera placement, and software feature sets through platform-level sourcing decisions. German and Japanese OEMs now mandate surround view as standard equipment across electric vehicle lineups.
- Tier-1 Suppliers:Integrated module providers bundle camera hardware, processing electronics, and calibration services for direct OEM delivery. Continental AG and Robert Bosch GmbH dominate this tier through captive semiconductor partnerships and algorithm IP.
- Aftermarket Installers:Independent service providers retrofit camera systems to existing vehicle fleets.
- Vehicle Assemblers:Contract manufacturers execute factory-fit installation per OEM specification.
Procurement volume concentrates at OEMs. Aftermarket Installers deliver the steepest margin expansion as commercial fleet operators seek blind-spot elimination for legacy heavy-duty vehicles.
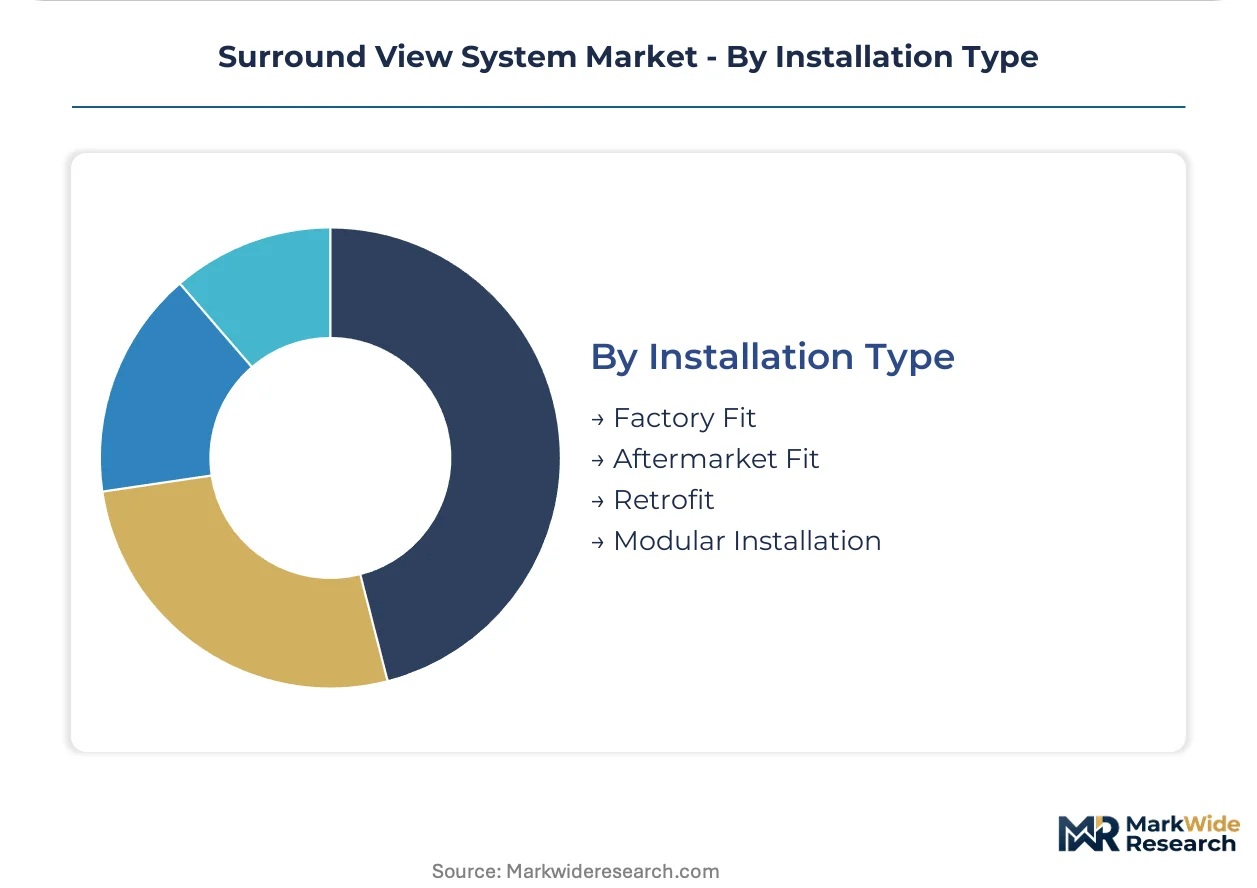
Installation Type:
Integration depth shapes warranty liability, calibration precision, and subsequent upgrade pathways.
- Factory Fit:Camera modules pre-integrated during vehicle assembly with millimeter-level alignment and sealed environmental protection. OEMs favor this pathway for quality consistency and streamlined regulatory certification.
- Retrofit:Post-production installation for existing vehicle pools requiring visibility upgrades without platform replacement. German logistics operators contract retrofit services for heavy-duty fleet compliance with emerging safety mandates.
- Aftermarket Fit:Dealer-installed options for vehicle buyers selecting visibility packages after initial purchase.
- Modular Installation:Swappable camera and processing units enabling field replacement and technology refresh.
Factory Fit commands the dominant share of unit volume. Retrofit installation is expanding most quickly as fleet procurement officers embed camera-based advanced driver assistance into multi-year supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor concentrates surround view system demand as premium OEMs mandate multi-camera visibility across electric vehicle platforms. NHTSA rear-visibility regulations in the United States and Euro NCAP scoring protocols in Europe are accelerating factory-fit installations. Japan's METI automated driving roadmap pulls technology adoption into mid-market segments through regulatory incentives.
United States
Detroit-area automakers integrate surround view modules into electric truck and SUV lineups launching through 2026. NHTSA mandates backup camera coverage for all light vehicles, establishing baseline multi-camera infrastructure requirements. Michigan's automotive engineering clusters host validation facilities for real-time geometric correction algorithms.
Germany
Bavarian premium manufacturers specify 4-camera systems as standard equipment across battery-electric platforms. KBA certification protocols require demonstration of sub-50-millisecond latency for parking maneuver safety. Stuttgart's Tier-1 supplier ecosystem anchors algorithm development for AI-driven neural stitching.
Japan
Nagoya-based vehicle assemblers deploy 360-degree view configurations to satisfy METI automated driving milestones. JIS standards govern environmental sealing and vibration resistance for camera modules. Kanto region electronics manufacturers supply automotive-grade image signal processors to domestic OEMs.
South Korea
Seoul Capital Area battery-electric vehicle producers adopt surround view technology for export compliance with Euro NCAP protocols. Foundry capacity for semiconductors clusters in Gyeonggi Province, supplying image processors to Tier-1 module integrators. Busan-Ulsan logistics operators contract aftermarket retrofits for heavy-duty fleet visibility upgrades.
China
Yangtze River Delta new energy vehicle manufacturers source multi-camera controllers from domestic semiconductor vendors. GB standards specify performance thresholds for real-time video fusion in low-speed autonomous operation. Shenzhen's electronics manufacturing base produces ultra-wide-angle camera modules for regional OEM integration.
Surround View System Market Vendor Landscape
Global majors compete with regional champions across algorithm IP and semiconductor supply partnerships, creating a tiered structure where captive silicon relationships determine value capture. The vendor base separates into integrated module providers, semiconductor specialists, and software-centric challengers. Three archetypes dominate: Tier-1 systems integrators bundling hardware-software stacks, semiconductor vendors supplying automotive-grade inference accelerators, and AI-focused challengers monetizing neural stitching through licensing. Consolidation pressure intensifies as software-defined vehicle architectures compress hardware margins and elevate recurring software revenue streams.
Within the Tier-1 systems integrator tier, Continental AG and Robert Bosch GmbH exemplify the integrated module provider archetype through their positioning across European and Asian OEM supply chains. NXP Semiconductors anchors the semiconductor specialist segment with automotive-grade system-on-chip platforms. These three entities represent distinct competitive vectors: hardware-software bundling, silicon supply security, and centralized compute migration readiness.
| Leading Market Players |
|---|
| Continental AG |
| Magna International |
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo SA |
| Texas Instruments |
| NXP Semiconductors |
| Aptiv |
| ZF Friedrichshafen |
| Others |
Supply Flow & Price Mechanics
Neural stitching algorithm migration from hardware-bound pipelines to software-defined architectures is collapsing per-module silicon requirements while redistributing value capture toward semiconductor vendors with automotive-grade inference accelerators. This technology shift concentrates pricing power among foundry operators in Taiwan and South Korea, forcing Tier-1 integrators to absorb margin compression or accelerate captive silicon partnerships.
Pricing Analysis
Input-cost pass-through from automotive-grade image signal processors dominates module economics, with foundry wafer pricing feeding directly into Tier-1 contract negotiations. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled neural stitching packages from basic geometric correction hardware, with certification grade against NHTSA and Euro NCAP protocols commanding substantial premiums. Pricing pressure stems from ultrasonic sensor substitution in economy vehicle segments where acoustic ranging satisfies baseline parking assistance. Fleet procurement officers exhibit lowest price sensitivity due to contractual safety mandates, while independent aftermarket installers face acute margin compression from semiconductor spot market volatility.
Supply Chain Analysis
Warehouse-distribution layer consolidation around Stuttgart, Nagoya, and Detroit automotive corridors concentrates finished module inventory within 48-hour delivery radius of major OEM assembly plants. Geographic supply concentration clusters in Taiwan for foundry capacity, South Korea for memory and logic components, and Germany for precision camera module assembly. Raw material dependencies span silicon wafers, automotive-grade lens glass, and high-temperature resistant housing polymers. Single-source vulnerability from Taiwan Semiconductor Manufacturing Company concentration for advanced nodes exposes Tier-1s to allocation rationing during capacity constraints. Distribution runs through hub-and-spoke patterns anchored by Continental AG and Robert Bosch GmbH regional fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surround view system market functions as a stable compounder anchored by regulatory mandates that institutionalize multi-camera visibility infrastructure across vehicle segments regardless of cyclical demand fluctuations.
For Market Incumbents: Cement algorithm IP ownership through accelerated R&D in neural stitching architectures that reduce hardware dependency and enable recurring software revenue streams. Deepen captive semiconductor partnerships with foundry operators in Taiwan and South Korea to defend against allocation rationing during capacity constraints. Prioritize certification investment against evolving Euro NCAP scoring protocols that pull surround view adoption into mid-market vehicle segments previously served by simpler sensor arrays. For New Entrants and Emerging Players: Enter via commercial fleet aftermarket retrofit services targeting German and Japanese logistics operators with contractual blind-spot elimination mandates for legacy heavy-duty vehicle pools. White-space concentration sits with AI-driven stitching software licensing to Tier-1 module integrators seeking to reduce hardware complexity without sacrificing performance thresholds. Go-to-market execution should anchor on software monetization through over-the-air feature activation rather than capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among semiconductor specialists with automotive-grade inference accelerator portfolios tethered to software-defined vehicle architecture transitions. Long-term viability framing centers on 5-10 year regulatory mandate persistence across NHTSA, Euro NCAP, and METI jurisdictions that institutionalize camera-based visibility requirements. Acquisition target archetype: Tier-1 suppliers with bundled hardware-software stacks and established OEM platform integration relationships. Signal to watch: centralized compute migration velocity as indicator of value capture redistribution from distributed camera modules to domain controllers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized compute migration compresses hardware margins and elevates algorithm licensing revenue for NXP Semiconductors. |
| Automotive-Grade Semiconductor Partnership | Captive foundry relationships secure allocation priority for Continental AG during Taiwan capacity constraints. |
| AI-Driven Neural Stitching Development | Machine learning displacement of geometric correction pipelines enables over-the-air feature upgrades for Robert Bosch GmbH. |
| Multi-Protocol Certification Investment | Simultaneous NHTSA, Euro NCAP, and METI validation streamlines OEM platform sourcing decisions for Denso Corporation. |
| Commercial Fleet Aftermarket Expansion | German logistics operator contracts for heavy-duty retrofit installations deliver margin-rich volume outside OEM pricing pressure. |
Methodological Framework
Bottom-up vehicle platform modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet procurement managers combined with secondary validation against NHTSA regulatory filings, Euro NCAP test protocol documentation, METI automated driving roadmap publications, and vehicle production registration databases. Triangulation across these sources ensures segmentation outputs reflect actual procurement patterns rather than aspirational technology adoption curves.
Historical trendline analysis of surround view system penetration rates across electric and internal combustion vehicle platforms established baseline growth trajectories. The analytical framework models segmentation dimensions spanning camera count architecture, software sophistication tier, integration depth, vehicle class, propulsion architecture, and regional regulatory cluster across the projection horizon. CAGRs derive from regression analysis of technology adoption curves calibrated against regulatory mandate implementation schedules and OEM platform launch cadences. Forecast inputs incorporate foundry capacity expansion announcements, Euro NCAP protocol evolution timelines, and fleet procurement contract specifications.
The model holds under stable regulatory mandate enforcement and continued foundry capacity expansion; deviation in semiconductor supply disruption severity or regulatory delay would shift volume and value outputs. Forecasts reflect documented assumptions regarding technology migration velocity and pricing elasticity across vehicle segments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market