
 High Voltage PTC Heaters for Electric Vehicles Market | 2026-2036
High Voltage PTC Heaters for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage PTC Heaters for Electric Vehicles Market Insights
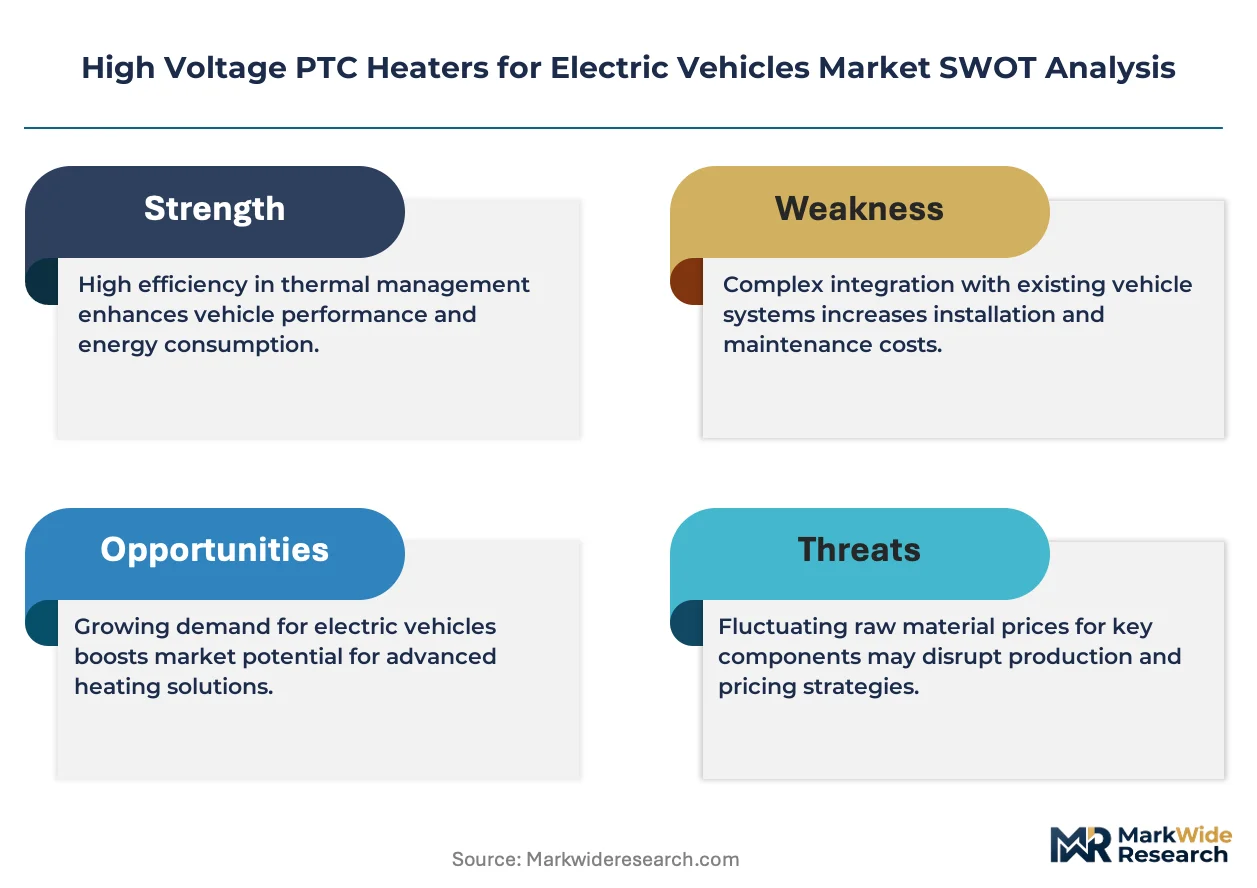
Software-defined thermal management is hardening into a recurring revenue layer as automakers sell cabin pre-conditioning subscriptions separate from hardware. Eberspächer leverages its European OEM relationships to anchor long-term service contracts. BorgWarner Inc. competes through integrated thermal system architectures that bundle PTC modules with heat pumps.
High Voltage PTC Heaters for Electric Vehicles are self-regulating ceramic or composite resistive heating elements operating at 400V–800V that convert electrical energy to heat without external control circuitry, primarily deployed to maintain cabin comfort and battery thermal equilibrium in electrified powertrains. Liquid-type PTC heaters dominate OEM installations where battery warming demands precise coolant temperature control, while ceramic variants occupy the fastest-growing tier in premium passenger cars seeking faster response times. The aftermarket installation segment remains structurally thin on margin as workshop retrofitting requires proprietary diagnostic interfaces that OEMs control.
EPA tailpipe standards, China's MIIT dual carbon goals, and South Korea's KBA energy efficiency mandates collectively force automakers to document thermal system watt-per-kilometer performance in type-approval filings. Product access now hinges on GB standards compliance in China and CE marking under EU F-Gas Regulation for systems integrating refrigerant loops. Stakeholders must monitor whether solid-state battery thermal profiles reduce peak heating loads or simply shift demand timing across drive cycles.
Market Dynamics
EPA tailpipe standards and China's MIIT dual carbon goals are compressing thermal efficiency timelines, forcing OEMs to document watt-per-kilometer performance in type-approval filings and accelerating hardware-software integration investments.
Growth Catalysts
- Cold-climate range preservation:Battery heating applications in the US, China, and South Korea have become purchase-decision factors for EV buyers facing winter range loss.
- F-Gas Regulation:EU mandates under the F-Gas Regulation are pushing automakers toward refrigerant-integrated thermal systems that bundle PTC modules with heat pump architectures.
- MIIT dual carbon goals:China's GB standards compliance requirements are expanding the addressable market for certified high-voltage heating components in domestic EV production.
Market Restraints
- Silicon carbide supply concentration:Power electronics substrate sourcing from limited Asian foundries creates input cost volatility for 800V-rated PTC controller circuits.
- Proprietary diagnostic lockout:OEM-controlled software interfaces block independent workshops from aftermarket retrofitting, structurally thinning margin pools outside factory channels.
- Heat pump substitution:Integrated heat pump systems in mild-climate European vehicles are displacing standalone PTC cabin heaters in efficiency-optimized powertrains.
Strategic Opportunities
- Software-defined thermal services:Cabin pre-conditioning subscriptions sold separate from hardware are creating recurring revenue layers anchored by European OEM service contracts.
- Solid-state battery thermal profiles:Next-generation cell chemistries with modified peak heating loads are shifting demand timing across drive cycles for adaptive PTC control systems.
- CE marking expansion:Systems integrating refrigerant loops under EU F-Gas Regulation are opening certified product access across 27 member state markets.
Industry Challenges
- GB standards certification timelines:Chinese type-approval documentation requirements for thermal system efficiency are extending product launch cycles by 8-14 months.
- 800V-400V legacy integration:Dual-voltage platform engineering requires redundant heating architectures that complicate BOM management and thermal control software validation.
- Embedded systems firmware talent:Scarce automotive thermal control algorithm developers are concentrating in German and South Korean engineering clusters, raising compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage PTC Heaters for Electric Vehicles Market |
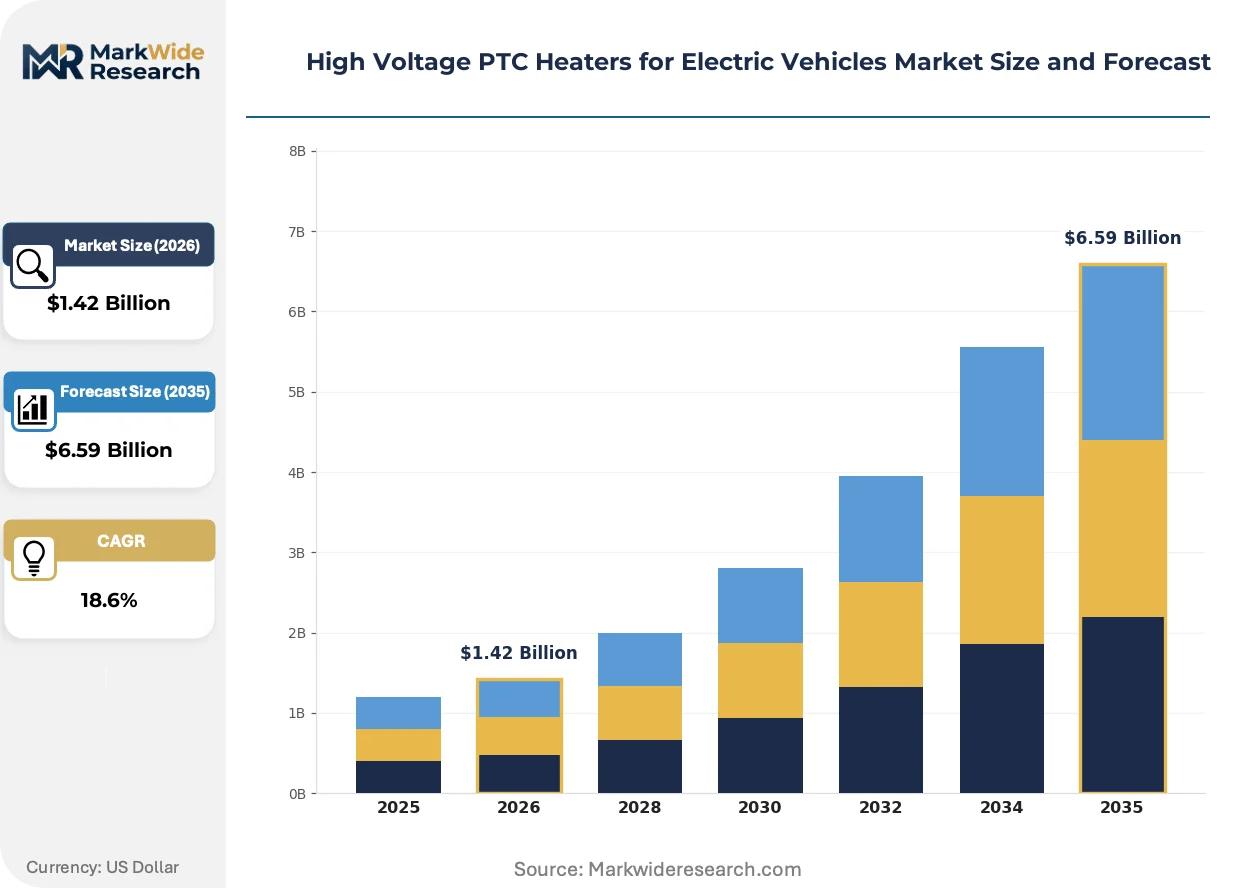
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.59 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Air, Ceramic, Composite End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Aftermarket Application: Cabin Heating, Battery Heating, Engine Preheating, Fluid Heating Installation: OEM, Retrofitting, Workshop Installation, Home Garage |
| Companies Covered | Eberspächer, BorgWarner Inc., DBK Group, Huagong Tech Company, Mitsubishi Heavy Industries, Zhenjiang Dongfang Electric Heating, Woory Corporation, Suzhou Xinye Electronics, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage PTC Heaters for Electric Vehicles Market Trends and Innovations
Intelligent thermal management architectures are displacing fixed-output heating elements, with ceramic PTC variants and adaptive control algorithms compressing response times while enabling subscription-based feature monetization.
Self-regulating ceramic composite elements are automating temperature control without external circuitry, reducing wiring complexity in 800V architectures. Premium passenger car OEMs in Germany and South Korea are adopting these variants for faster cabin warm-up. The technology is automating the shift from coolant-based battery heating toward direct air heating in compact urban EVs.
China's MIIT dual carbon goals and GB standards compliance requirements are mandating documented thermal efficiency in type-approval filings. Automakers must now submit watt-per-kilometer performance data alongside traditional safety documentation. Battery heating applications face the strictest scrutiny, with MIIT auditors rejecting systems exceeding baseline consumption thresholds.
Fleet operators and lease providers are unbundling after-sales thermal management from hardware purchases, favoring pay-per-use cabin pre-conditioning over capitalized heating systems. This procurement evolution is concentrating demand among software-capable tier-1 suppliers who can deliver over-the-air control updates. The US and Nordic markets show the fastest uptake of subscription thermal services among commercial EV fleets.
High Voltage PTC Heaters for Electric Vehicles Market Segmentation
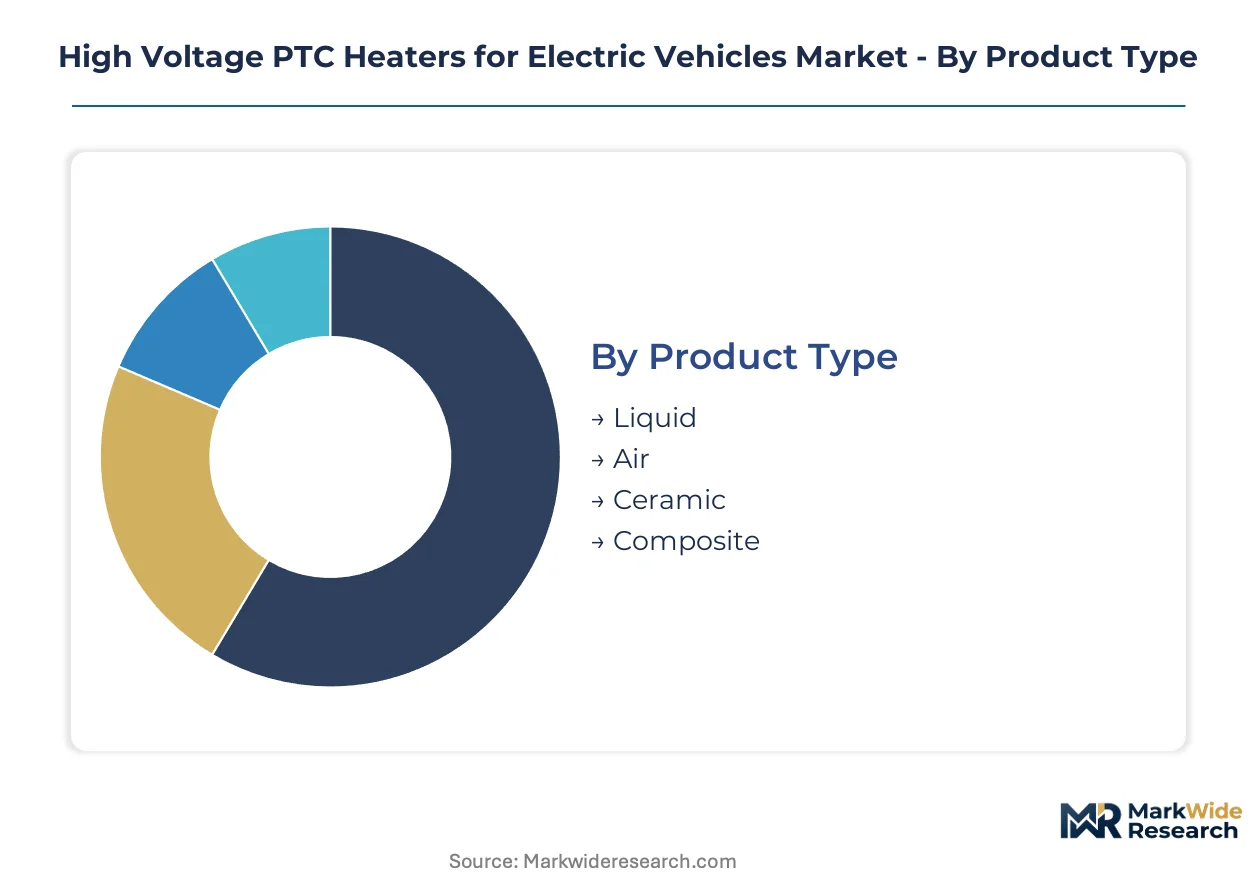
High voltage PTC heater procurement varies sharply across buyer types, with OEMs prioritizing integration complexity while fleet operators weigh total cost of ownership against subscription flexibility. Segmentation reveals how thermal system architecture, vehicle electrification level, and regulatory compliance requirements fragment addressable demand into distinct commercial pockets.
Product Type:
Buyers differentiate primarily by thermal response speed versus coolant compatibility requirements in their platform architectures.
- Liquid:These heaters integrate directly into battery coolant loops, enabling precise temperature management for lithium-ion packs in cold climates. OEM installations across Germany and South Korea favor this variant where MIIT and KBA efficiency mandates require documented watt-per-kilometer performance in type-approval filings.
- Ceramic:Self-regulating composite elements eliminate external control circuitry and compress warm-up latency. Premium passenger car platforms seeking faster cabin response times are driving adoption, particularly where 800V architectures reduce wiring complexity.
- Air:Direct cabin heating elements bypass coolant infrastructure in compact urban EVs with limited packaging space.
- Composite:Hybrid material constructions balance thermal mass and electrical efficiency for mid-range battery electric vehicles.
Liquid heaters lead volumes today; ceramic variants are gaining share fastest in premium segments.
End User:
Procurement scale and software integration capability separate fleet buyers from individual consumers.
- Passenger Cars:German and South Korean OEMs specify integrated thermal system architectures bundling PTC modules with heat pumps. EPA tailpipe standards and F-Gas Regulation compliance documentation now accompanies every platform approval.
- Commercial Vehicles:Fleet operators in the US and Nordic markets unbundle hardware purchases from cabin pre-conditioning subscriptions. Pay-per-use thermal services concentrate demand among tier-1 suppliers delivering over-the-air control updates.
- Two-Wheelers:Compact form factors and cost constraints favor simplified air-type heating in urban mobility platforms.
- Aftermarket:Proprietary diagnostic interfaces controlled by OEMs structurally limit workshop retrofitting opportunities.
Passenger cars dominate current revenue; commercial vehicles show the steepest expansion trajectory as fleet electrification accelerates.
Application:
Thermal priority hierarchy shifts with climate exposure and battery chemistry sensitivity.
- Battery Heating:Cold-climate range preservation has become a purchase-decision factor across the US, China, and South Korea. Systems face strictest MIIT scrutiny with auditors rejecting designs exceeding baseline consumption thresholds.
- Cabin Heating:Occupant comfort demands compete with efficiency optimization, driving heat pump integration in mild-climate European vehicles.
- Engine Preheating:Range-extended electric platforms require thermal management for auxiliary power units.
- Fluid Heating:Windshield washer and brake fluid temperature maintenance addresses secondary thermal loads.
Battery heating commands premium positioning today; cabin heating subscriptions are climbing fastest as software-defined services proliferate.
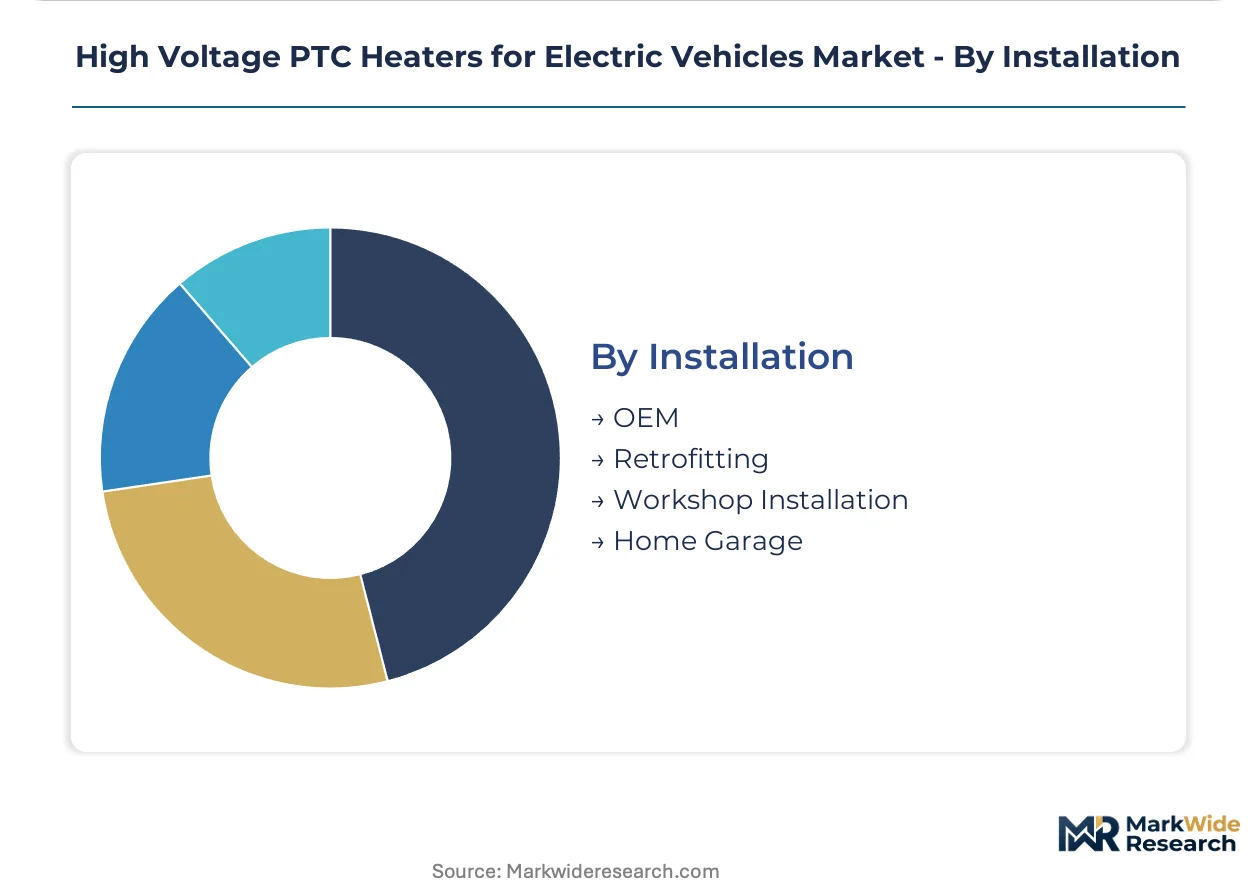
Installation:
Channel control over diagnostic access determines margin capture and customer relationship ownership.
- OEM:Factory integration ensures firmware validation and thermal control algorithm optimization. Eberspächer leverages European OEM relationships to anchor long-term service contracts spanning vehicle lifecycles.
- Retrofitting:Legacy vehicle electrification projects face 800V-400V dual-voltage engineering complexity and redundant architecture costs.
- Workshop Installation:Proprietary software lockout blocks independent service providers from margin participation.
- Home Garage:Consumer self-installation remains negligible given high-voltage safety certification requirements.
OEM channels capture dominant value today; retrofitting is expanding most quickly in commercial fleet conversion projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as automakers relocate thermal system assembly to jurisdictions with streamlined GB standards and CE marking pathways. Cost-of-compliance gaps between China, Germany, and South Korea are concentrating high-voltage PTC controller circuit manufacturing in clustered engineering zones.
China
Domestic EV production volumes and MIIT dual carbon enforcement are driving battery heating procurement at scale. GB standards compliance requirements extend product launch cycles by 8-14 months, filtering out uncertified suppliers. The Yangtze River Delta manufacturing corridor hosts concentrated PTC module assembly for export-qualified platforms.
Germany
Premium passenger car OEMs specify integrated thermal architectures bundling PTC modules with heat pumps. KBA energy efficiency mandates and EU F-Gas Regulation documentation accompany every platform approval. Bavaria's automotive engineering clusters anchor Eberspächer's long-term European service contract relationships.
South Korea
KBA-aligned efficiency mandates and cold-climate range preservation priorities position battery heating as a purchase-decision factor. Domestic OEMs source ceramic PTC variants for 800V architectures to compress cabin warm-up latency. The Seoul Capital Area concentrates firmware talent for thermal control algorithm development.
United States
EPA tailpipe standards and cold-climate range anxiety are accelerating hardware-software integration investments for battery thermal management. Fleet operators in commercial EV segments unbundle hardware purchases from cabin pre-conditioning subscriptions. Midwest automotive corridors and California clean-tech clusters split demand between legacy OEM integration and startup platform development.
Japan
METI efficiency guidelines and heat pump substitution trends in mild-climate applications are displacing standalone PTC cabin heaters. Engineering focus concentrates on adaptive control systems for solid-state battery thermal profiles. The Kanto region maintains specialized ceramic composite element research for next-generation cell chemistries.
High Voltage PTC Heaters for Electric Vehicles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated thermal system architects capturing OEM factory channels while component fabricators serve tier-2 retrofitting demand. The vendor base organizes around three strategic archetypes: European full-system integrators with service contract anchoring, Asian electronics conglomerates with captive semiconductor supply, and Chinese domestic market specialists with GB certification speed. Dominant competitive moves include capacity expansion in 800V-rated production lines and strategic partnerships for over-the-air thermal control software licensing.
Within the European full-system integrator tier, Eberspächer GmbH and BorgWarner Inc. exemplify archetypes leveraging long-term OEM relationships to anchor recurring revenue streams. Among Asian electronics conglomerates, LG Electronics occupies a position representing captive vertical integration into power electronics substrates. Chinese specialists including Zhenjiang Dongfang Electric Heating and Huagong Tech Company sit within the domestic certification-speed tier, where GB standards compliance capabilities determine market access velocity.
| Leading Market Players |
|---|
| Eberspächer |
| BorgWarner Inc. |
| DBK Group |
| Huagong Tech Company |
| Mitsubishi Heavy Industries |
| Zhenjiang Dongfang Electric Heating |
| Woory Corporation |
| Suzhou Xinye Electronics |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer pricing volatility cascades through 800V PTC controller manufacturing, compressing margins for tier-2 suppliers while OEM direct-contracting captures cost stability. This input-cost pressure stratifies the market into certified premium tiers serving German and South Korean automakers versus uncertified economy channels facing GB standards rejection risk.
Pricing Analysis
Distributor markups on ceramic PTC elements vary by certification tier, with CE-marked and GB-compliant products commanding premium positioning against uncertified alternatives. Price differentiation hinges on MIIT audit documentation and KBA efficiency validation, with volume-scale discounts concentrating among fleet operators unbundling hardware from subscription services. Cost compression in standard-grade liquid heaters is intensifying due to silicon carbide supply bottlenecks, while aftermarket retrofitting remains the most price-sensitive channel blocked by proprietary diagnostic lockout.
Supply Chain Analysis
Returns and refurbishment flows for failed PTC modules remain underdeveloped, with most defective units scrapped rather than remanufactured due to ceramic element degradation. Manufacturing concentrates in China, Germany, and South Korea, drawing from silicon carbide substrates sourced primarily from Asian foundries, copper winding materials, and ceramic composite feedstocks. Single-source vulnerability in 800V-rated power electronics creates exposure to export control disruptions. Distribution runs through tier-1 system integrators holding OEM service contracts rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as electrification mandates harden into enforceable compliance deadlines across major automotive production jurisdictions. Regulatory tailwinds provide durable demand visibility independent of near-term vehicle sales cyclicality.
For Market Incumbents: Anticipate heat pump substitution pressure in mild-climate European segments by anchoring long-term service contracts for battery thermal management software. Prioritize backward integration into silicon carbide controller production to defend margin position against substrate cost volatility. Expand 800V-rated capacity in South Korean engineering clusters where firmware talent scarcity raises competitor compensation costs. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass OEM procurement gatekeeping for commercial vehicle operators seeking pay-per-use thermal services. Target Nordic and US commercial EV retrofitting where workshop installation barriers are lower and subscription bundling creates recurring revenue footholds. Lead with over-the-air control capability as the primary go-to-market wedge against legacy hardware-only suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-1 thermal system architects possessing GB certification speed and European service contract anchoring. The five-to-ten year viability window favors acquirers of software-defined thermal management platforms over pure component fabricators. Monitor solid-state battery thermal profile disclosures from Japanese and South Korean cell manufacturers as the critical inflection signal for adaptive PTC control demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces redundant 800V-400V dual-voltage engineering costs for OEM thermal architectures. |
| Battery Supply Agreement | Secures lithium-ion pack thermal management partnerships with cold-climate range-focused OEMs. |
| Software-Defined Vehicle Investment | Enables cabin pre-conditioning subscription monetization through over-the-air control updates. |
| Geographic Manufacturing Footprint | Positions GB-compliant production in Yangtze River Delta for MIIT audit documentation speed. |
| Charging Infrastructure Partnership | Integrates battery heating preconditioning with DC fast-charging network operator platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, thermal control firmware developers, and fleet operator electrification managers with secondary validation. Sources included MIIT type-approval filings, KBA energy efficiency documentation, vehicle production databases, and SEC disclosures from listed automotive suppliers. Bottom-up segment sizing and top-down macro constraint checks triangulated volume and value estimates.
Segment-weighting approaches modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the projection horizon. CAGRs derived from fitted growth curves applied to baseline penetration rates, with cross-checks against OEM platform rollout schedules and regulatory mandate enforcement timelines. Forecast inputs incorporated silicon carbide supply elasticity assumptions and solid-state battery commercialization trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook for peak heating load requirements. Forecasts reflect documented assumptions regarding MIIT enforcement intensity and F-Gas Regulation implementation pace. Practitioners should monitor KBA efficiency mandate revisions and EPA tailpipe standard litigation outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
US Electric Vehicle Market