
 Can Racks Market | 2026-2036
Can Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Can Racks Market Analytics
Aluminum is broadening its share in can rack construction as producers seek corrosion-resistant alternatives to traditional painted steel. InterMetro Industries Corporation leverages its medical and foodservice heritage to dominate specification-driven commercial channels. ClosetMaid Corporation anchors the residential segment through mass retail partnerships and modular system design. Daifuku competes in automated storage integration, extending its material handling expertise into high-throughput beverage distribution centers.
A can rack is a purpose-built storage frame engineered to hold cylindrical containers in stable, accessible arrays, typically fabricated from 14- to 18-gauge steel or extruded aluminum with weight capacities ranging from 200 to 2,000 pounds per shelf tier. Floor racks occupy the largest installed base across industrial food processing and warehouse environments where pallet-scale throughput governs layout decisions. Wall-mounted racks sustain faster growth in compact urban retail and residential kitchens where floor space commands premium value. Custom racks capture concentrated margin pools in pharmaceutical and cold-chain applications requiring temperature-rated finishes and exact dimensional compliance.
FDA food-contact surface regulations and NSF International sanitation standards shape material selection and finish specifications for can racks serving food preparation and pharmaceutical storage environments. OSHA walking-working surface rules mandate load labeling and anchoring protocols that elevate engineering documentation requirements for industrial installations. Stakeholders must monitor evolving EPA guidelines on powder coating emissions and state-level extended producer responsibility frameworks as these will increasingly determine supplier qualification and total cost of ownership calculations.
Market Dynamics
Foodservice procurement standardization is compressing vendor margins while elevating specification requirements across commercial kitchen installations. EPA powder coating emission limits and OSHA load-rating mandates are forcing engineering documentation upgrades that smaller fabricators cannot sustain.
Growth Catalysts
- Aluminum alloy substitution:Corrosion-resistant extrusions are displacing painted steel in coastal food processing facilities where salt exposure accelerates degradation.
- FDA food-contact surface mandates:Sanitation-grade finishes are becoming non-negotiable in pharmaceutical cold-chain storage, expanding the addressable market for temperature-rated rack systems.
- Southeastern US warehouse construction:Accelerated beverage distribution center buildouts in Georgia and Florida are concentrating demand for high-density floor rack configurations.
Market Restraints
- Steel price volatility:Cold-rolled coil input costs fluctuate with energy markets, compressing margin predictability for 14- to 18-gauge rack fabricators.
- Supply concentration in aluminum extrusion:Domestic billet supply tightness limits rapid scaling for producers pivoting from steel construction.
- NSF certification timelines:Extended third-party validation cycles delay product launches for sanitation-critical foodservice applications.
Strategic Opportunities
- Modular wall-mounted systems:Urban retail kitchens in Manhattan and San Francisco are prioritizing vertical storage to reclaim floor space.
- Automated storage integration:Convergence of rack engineering with warehouse robotics is opening specification channels in high-throughput beverage distribution.
- Extended producer responsibility frameworks:State-level recycling mandates in California and Washington are creating first-mover advantage for take-back program operators.
Industry Challenges
- Welding technician scarcity:Qualified aluminum TIG welders command premium wages, constraining production scaling for corrosion-resistant product lines.
- Legacy system integration:Retrofitting automated retrieval systems into existing floor rack arrays requires custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Can Racks Market |
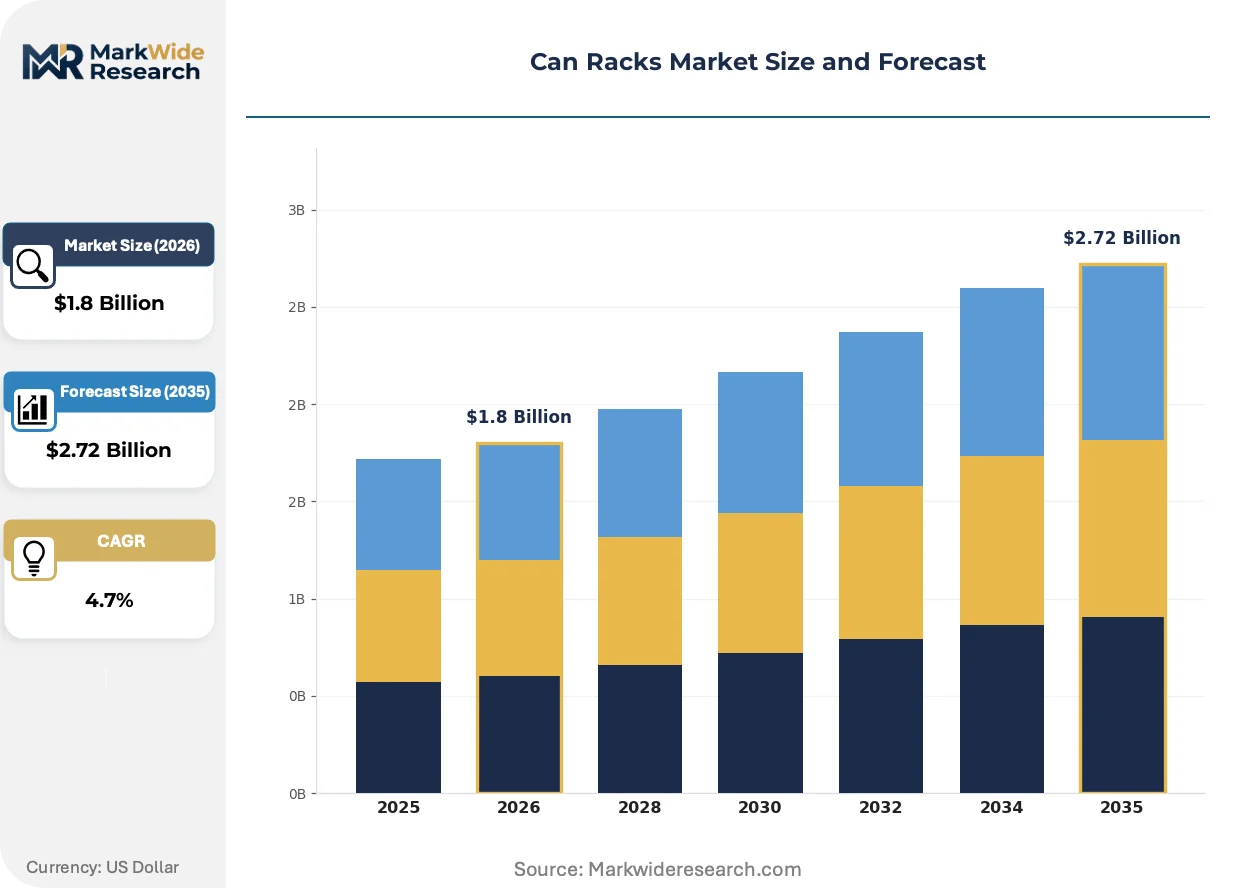
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Racks, Wall-Mounted Racks, Custom Racks, Portable Racks Material: Metal, Plastic, Wood, Composite End User: Commercial, Residential, Industrial, Retail Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | InterMetro Industries Corporation, ClosetMaid Corporation, Honey-Can-Do, AR Racking, Mecalux, Kardex Group, Daifuku, AK Material Handling Systems, Ridg-U-Rak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Can Racks Market Evolving Landscape
Material science advances and regulatory precision are elevating rack engineering from commodity metalwork to specification-driven systems integration. Three developments are compressing traditional competitive advantages while opening specialized margin pools.
Extruded aluminum channel construction is converging with antimicrobial surface treatments to create corrosion-resistant, FDA-compliant storage arrays. Pharmaceutical manufacturers and coastal food processors are specifying these hybrid systems at accelerating rates. This convergence is compressing the market share of traditional painted steel fabricators who lack metallurgical finishing capabilities.
OSHA walking-working surface rules are mandating load labeling and anchoring documentation for all industrial installations above six feet. Fabricators must now maintain engineering stamp capabilities and third-party testing relationships that smaller competitors cannot afford. Food processing facilities in the Midwest and Texas are responding by consolidating vendor lists toward specification-certified suppliers.
Specification-driven procurement is displacing price-first buying in commercial kitchen channels. Chain restaurant operators are centralizing rack selection through corporate engineering teams rather than franchisee discretion. This behavioral shift is most visible in quick-service restaurant buildouts across the southeastern United States, where standardized layouts now dominate new construction.
Can Racks Market Segmentation
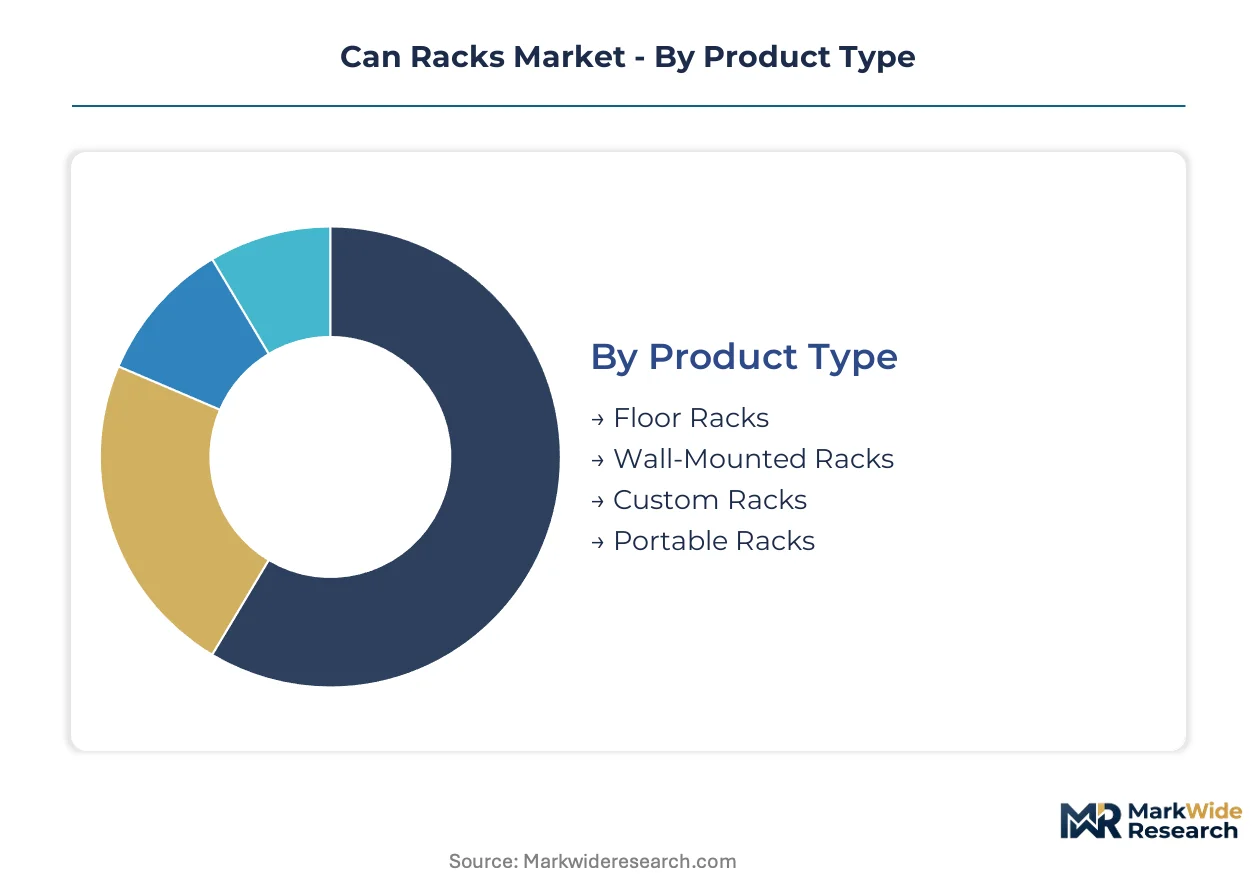
Can rack segmentation reflects divergent engineering priorities across foodservice, pharmaceutical, and residential channels. Specification requirements from FDA and OSHA fragment demand into distinct performance tiers that reward specialized fabrication capabilities.
Product Type:
Structural configuration determines load-bearing architecture and installation protocols.
- Floor Racks:Pallet-scale steel or aluminum frames engineered for 200-2,000 pound shelf capacities dominate beverage distribution centers in Georgia and Florida. Warehouse construction acceleration in the southeastern United States concentrates procurement of standardized high-density configurations.
- Wall-Mounted Racks:Vertical extrusion systems reclaim floor space in Manhattan and San Francisco retail kitchens where square footage commands premium economics. Urban foodservice operators specify these for compact back-of-house layouts.
- Portable Racks:Castor-mounted units serve catering and temporary foodservice operations requiring rapid reconfiguration.
- Custom Racks:Temperature-rated pharmaceutical cold-chain arrays command specialized margin pools through exact dimensional compliance.
Floor racks lead on scale; wall-mounted racks lead on momentum.
Material:
Corrosion resistance and sanitation compliance drive substitution patterns across coastal and pharmaceutical applications.
- Metal:Extruded aluminum displaces painted steel in salt-exposed food processing facilities. FDA food-contact surface mandates elevate specification requirements for 14- to 18-gauge steel and aluminum alloys in commercial kitchen installations.
- Plastic:Polymer composites serve light-duty residential and retail display applications where load requirements remain modest.
- Wood:Aesthetic-focused residential pantries and specialty retail environments specify hardwood frames for visual warmth.
- Composite:Hybrid material systems bridge weight and corrosion performance in niche pharmaceutical applications.
Metal dominates installed value; aluminum within metal is climbing fastest.
End User:
Procurement centralization and compliance intensity vary sharply across customer categories.
- Commercial:Chain restaurant engineering teams now standardize rack selection across southeastern US buildouts. Quick-service operators consolidate vendor lists toward specification-certified suppliers.
- Industrial:Food processing and beverage distribution centers drive volume through pallet-scale floor rack procurement.
- Residential:Modular system design through mass retail channels anchors consumer demand for pantry organization.
- Retail:Urban grocery and convenience store operators prioritize vertical storage for backroom efficiency.
Commercial leads on specification value; industrial leads on unit volume.
Distribution Channel:
Channel selection reflects order scale, customization requirements, and specification support needs.
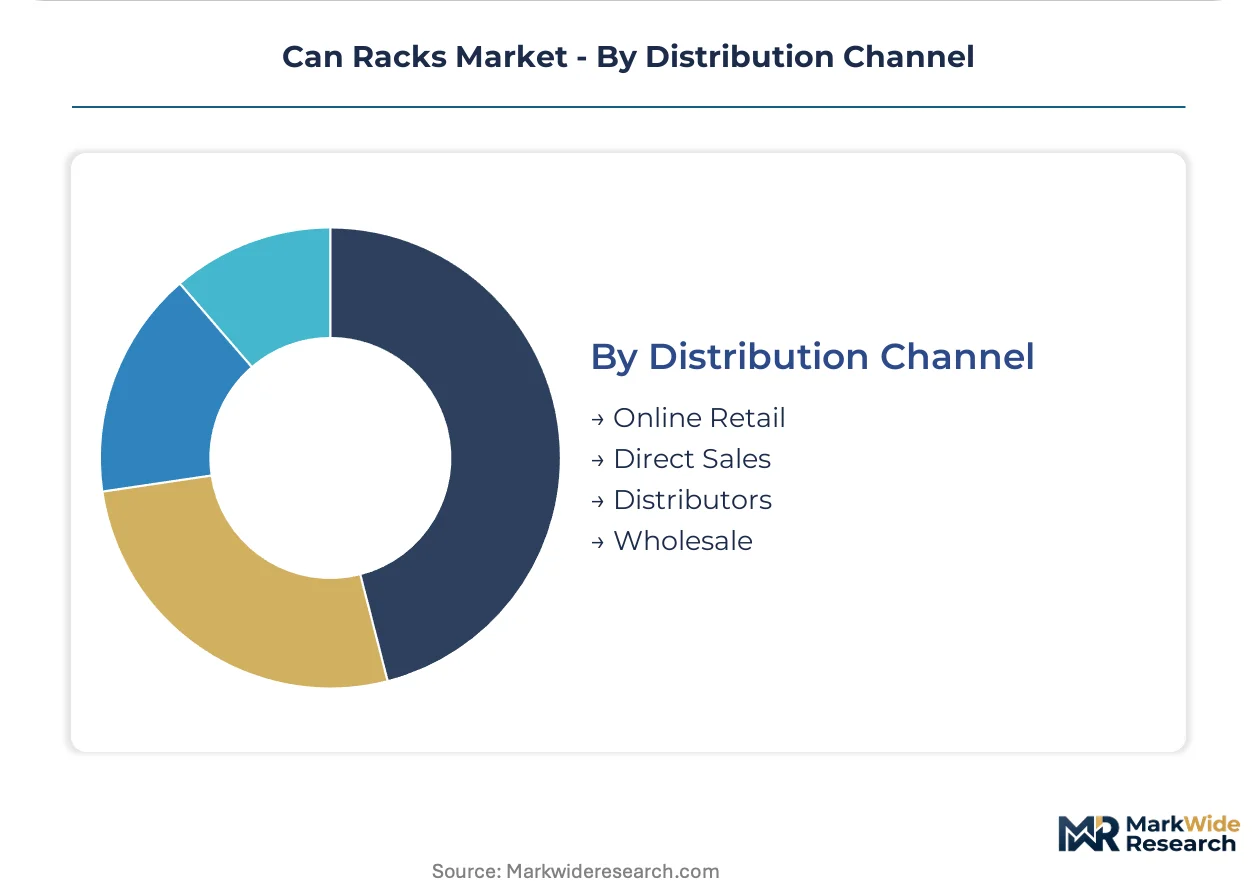
- Direct Sales:Corporate engineering teams at chain restaurant operators engage fabricators for standardized layout programs. Specification-driven procurement bypasses intermediaries for complex compliance documentation.
- Distributors:Foodservice equipment dealers aggregate demand from independent restaurants and institutional kitchens.
- Online Retail:Modular residential systems and light-duty commercial units flow through e-commerce platforms.
- Wholesale:Volume beverage distributors procure standardized floor rack configurations through buying cooperatives.
Direct sales captures the steepest expansion trajectory; distributors retain the broadest reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage distribution centers in the southeastern United States concentrate the largest procurement volumes for high-capacity floor rack systems. Commercial kitchen standardization and warehouse automation investments are fragmenting demand patterns across distinct regulatory environments.
United States
Georgia and Florida anchor beverage distribution center construction, with Atlanta and Miami metropolitan areas driving pallet-scale floor rack procurement. OSHA walking-working surface rules mandate load labeling and anchoring documentation above six feet. FDA food-contact surface regulations shape material selection for pharmaceutical cold-chain storage arrays in New Jersey and Pennsylvania industrial corridors.
Germany
Industrial food processing facilities in Bavaria and North Rhine-Westphalia specify corrosion-resistant aluminum extrusions for sanitation-critical applications. REACH compliance and CE marking requirements elevate engineering documentation standards for rack fabricators serving EU markets. Stuttgart's automotive supplier ecosystem is cross-applying precision manufacturing capabilities to modular storage system production.
China
Guangdong and Jiangsu provinces concentrate light-duty rack fabrication for export-oriented consumer goods channels. GB standards and SAMR quality supervision frameworks govern domestic market entry for industrial shelving systems. Shanghai's logistics real estate boom is accelerating demand for automated storage integration in e-commerce fulfillment centers.
Japan
Tokyo-Osaka corridor retail operators prioritize vertical wall-mounted configurations to maximize limited back-of-house space. METI industrial standards and JIS certification requirements fragment vendor qualification across prefectural procurement systems. Nagoya's automotive parts distribution heritage is extending into precision-engineered modular storage for pharmaceutical applications.
Brazil
São Paulo state foodservice chains are consolidating vendor lists toward specification-certified suppliers for standardized kitchen layouts. ANVISA sanitary surveillance requirements govern material selection for pharmaceutical and food-contact storage applications. Campinas industrial district is emerging as a fabrication hub for aluminum extrusion-based rack systems serving Mercosur markets.
Can Racks Market Competitive Landscape
Specification-driven procurement dominates the current landscape, compressing price-first buying patterns in commercial channels. The vendor base stratifies across three tiers: multinational material handling conglomerates with automated integration capabilities, regional metal fabricators serving standardized foodservice programs, and mass-market consumer brands competing on modular design. Strategic archetypes include corrosion-resistant specialists pivoting from steel to aluminum construction, automation integrators converging rack engineering with warehouse robotics, and private-label suppliers anchoring retail distribution. M&A activity and NSF certification investments constitute the primary competitive moves.
Among specification-certified fabricators, InterMetro Industries Corporation occupies a position within the foodservice heritage tier, while ClosetMaid Corporation anchors mass-market residential channels through retail partnerships. Daifuku sits within the automation integration archetype, extending material handling expertise into high-throughput distribution environments.
| Leading Market Players |
|---|
| InterMetro Industries Corporation |
| ClosetMaid Corporation |
| Honey-Can-Do |
| AR Racking |
| Mecalux |
| Kardex Group |
| Daifuku |
| AK Material Handling Systems |
| Ridg-U-Rak |
| Others |
Value Network & Pricing Analysis
Specification-certification divergence between NSF-validated fabricators and uncertified commodity producers manifests in pricing spreads exceeding 40 percent and supply chain fragmentation across tiered supplier bases. FDA food-contact surface mandates and OSHA load-rating documentation requirements concentrate premium procurement through engineering-stamp-capable vendors while price-sensitive foodservice operators default to undifferentiated steel fabricators.
Pricing Analysis
Input-cost pass-through from cold-rolled steel coil and aluminum billet markets governs rack pricing dynamics, with fabricators adjusting contract terms quarterly to protect margins. Three-tier pricing structure across premium NSF-certified, standard commercial-grade, and economy residential tiers separates buyers by compliance intensity and volume scale. Pricing pressure stems from steel price volatility and procurement centralization at chain restaurant engineering teams. Independent restaurants and residential consumers exhibit highest price sensitivity, while pharmaceutical cold-chain operators prioritize temperature-rated finishes over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with domestic aluminum extrusion capacity, where billet supply tightness constrains rapid scaling for corrosion-resistant product lines. Manufacturing concentrates in China for light-duty consumer racks, the United States for specification-certified commercial systems, and Germany for precision-engineered pharmaceutical arrays. Raw material dependencies encompass cold-rolled steel coil, aluminum 6061-T6 extrusions, and antimicrobial powder coatings. Tariff exposure on Chinese steel and aluminum inputs elevates landed cost unpredictability. Distribution runs through foodservice equipment dealers, direct corporate sales teams, and mass retail channels serving distinct buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in can racks rests on aluminum alloy substitution cost curves flattening and specification-certified suppliers capturing premium-tier procurement centralization. Cost-down drivers in extrusion efficiency and antimicrobial finish scale economies support this trajectory.
For Market Incumbents: Deploy NSF certification investment as a competitive moat against commodity steel fabricators losing share to aluminum specialists. Consolidate vendor relationships with southeastern US beverage distribution center developers before automation integrators capture specification channels. Anchor position through backward integration into aluminum extrusion capacity to secure billet supply and compress input cost volatility.
For New Entrants and Emerging Players: Premium-economy price-point gaps in wall-mounted urban retail systems present white-space entry vectors. Target Manhattan and San Francisco compact kitchen operators prioritizing vertical space reclamation over floor-scale capacity. Penetrate through modular system design partnerships with architectural specification firms serving quick-service restaurant buildouts.
For Investors and Strategic Acquirers: Asymmetric upside sits with aluminum-specialist fabricators possessing metallurgical finishing capabilities and existing NSF validation. Long-term viability favors vendors converging rack engineering with warehouse robotics integration. Monitor beverage distribution center automation investment announcements as inflection indicators for specification-channel demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Investment | FDA food-contact surface mandates elevate validation requirements for foodservice channel access. |
| Aluminum Extrusion Backward Integration | Domestic billet supply tightness rewards captive sourcing for corrosion-resistant product lines. |
| Automated Storage Integration Partnership | Daifuku and Kardex convergence models demonstrate specification-channel capture in beverage distribution. |
| Modular Wall-Mounted System Development | Urban retail kitchen density in Manhattan and San Francisco commands premium vertical storage economics. |
| Extended Producer Responsibility Program Launch | California and Washington state recycling mandates create first-mover qualification advantages. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and Brazil, with primary inputs from each market cluster. The analysis combines structured interviews with foodservice equipment procurement directors, commercial kitchen engineering teams, aluminum extrusion plant managers, and pharmaceutical cold-chain facility operators with secondary validation. Secondary sources include FDA food-contact surface regulation filings, OSHA walking-working surface rule documentation, NSF International certification databases, and customs trade data on steel and aluminum inputs. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchor volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, material substitution patterns, end-user procurement centralization intensity, and distribution channel structure. CAGRs derive from segment-level growth rate synthesis and cross-validation against input cost trajectory assumptions. Industry-specific forecast inputs encompass southeastern US warehouse construction permits, aluminum alloy price curves, and NSF certification pipeline data.
The model assumes a particular technology adoption path; alternative pathways for automated storage integration would alter the outlook for floor rack demand composition. Forecasts reflect assumptions on regulatory enforcement continuity, billet supply normalization, and foodservice procurement standardization velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Bale Clamp Intensive Market