
 Electric Tugger Market | 2026-2036
Electric Tugger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Tugger Market Insights
Lithium-ion powertrains are reconfiguring electric tugger design priorities, replacing lead-acid batteries with energy-dense alternatives that cut charging downtime and extend operational cycles. Crown Equipment Corporation leverages vertical integration in battery systems to control component quality across its manufacturing footprint. Daifuku anchors its position through sustained R&D intensity in automated guided vehicle interoperability. Seegrid differentiates by specializing in vision-guided navigation technology that eliminates infrastructure modifications for warehouse deployment.
An electric tugger is a battery-powered industrial vehicle designed to pull wheeled loads, typically operating at speeds up to 5 mph with drawbar pull ratings from 1,000 to 50,000 pounds depending on model class. Its primary commercial purpose centers on horizontal material movement within confined facility environments where forklift maneuverability proves impractical or hazardous. Compact tuggers dominate unit volume in retail backroom and light manufacturing settings where aisle width constraints limit equipment dimensions. Heavy-duty tuggers command premium positioning in automotive assembly applications where multi-ton load requirements justify higher capital outlay. Automated tuggers represent the fastest-expanding technology category as warehousing operators pursue labor reduction in repetitive transport loops.
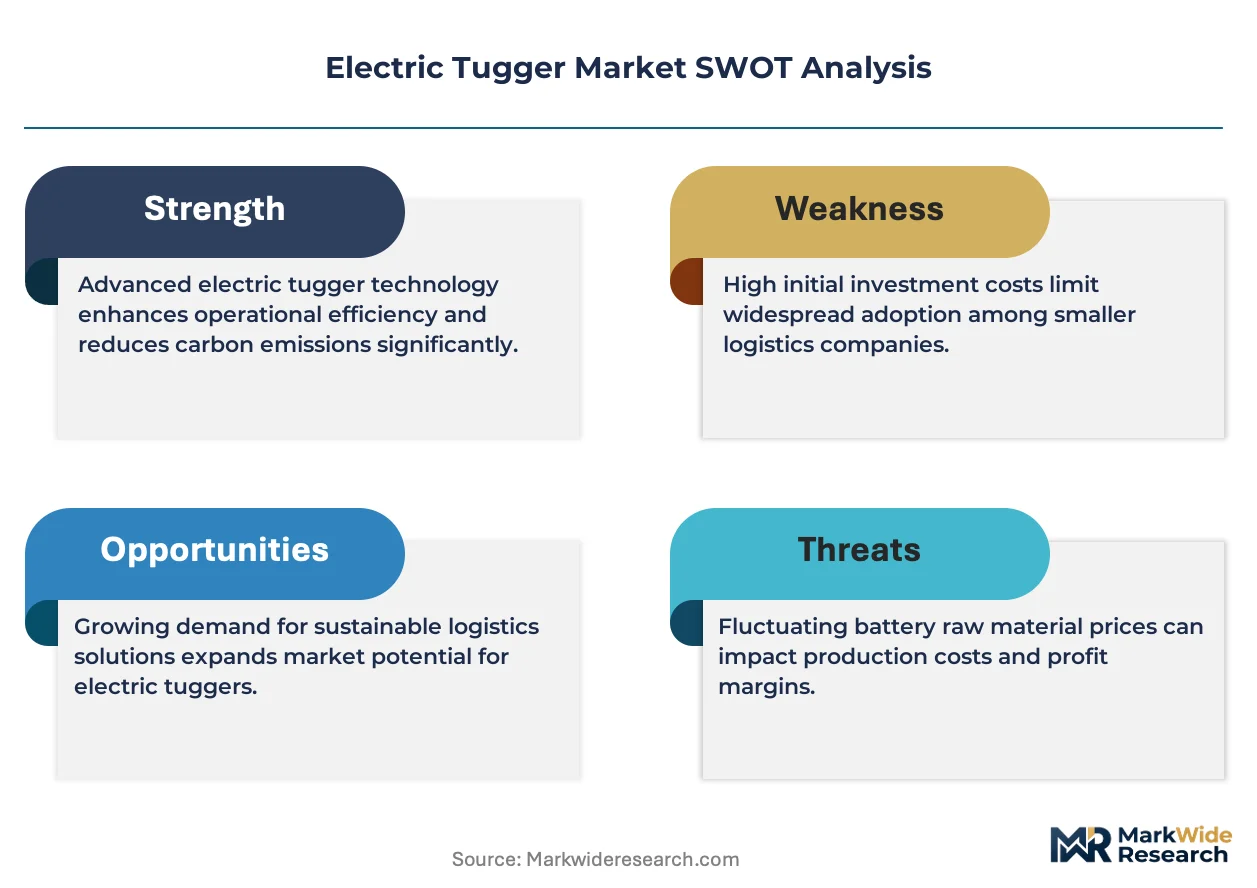
FCC equipment authorization requirements govern radio-frequency controls in North American electric tugger deployments, while OSHA powered industrial truck standards mandate operator training and equipment inspection protocols that shape fleet replacement cycles. The EU Machinery Directive and CE marking requirements constrain market access for non-compliant manufacturers, creating certification barriers that favor established European suppliers. Stakeholders must monitor evolving EPA indoor emissions guidelines and state-level warehouse decarbonization mandates that will progressively disqualify internal combustion alternatives from new facility specifications.
Market Dynamics
Lithium-ion chemistry is virtualizing the electric tugger powertrain architecture, collapsing charging infrastructure requirements while extending duty cycles beyond what lead-acid systems permitted. This electrochemical transition is compressing fleet replacement timelines as operators recalculate total cost of ownership around energy density gains rather than upfront capital outlay.
Growth Catalysts
- OSHA Indoor Air Quality Mandates:Warehouse operators in the United States face compliance deadlines that disqualify propane-powered industrial trucks from enclosed facility specifications, accelerating electric tugger procurement.
- E-commerce Fulfillment Density:Third-party logistics providers operating multi-tenant distribution centers require zero-emission material handling equipment to satisfy tenant sustainability scorecards and lease requirements.
- Automotive Assembly Reshoring:Electric vehicle manufacturers expanding North American production footprints are specifying automated guided tuggers for just-in-time component delivery to assembly lines.
Market Restraints
- Lithium Carbonate Price Volatility:Battery pack cost fluctuations tied to South American brine extraction capacity constraints compress manufacturer margins and create quoting uncertainty for fleet contracts.
- Charging Infrastructure Capital Requirements:Facility electrical upgrades to support high-voltage fast-charging stations demand substantial upfront investment that delays electrification decisions for smaller warehousing operations.
- Interoperability Fragmentation:Proprietary fleet management protocols from dominant equipment manufacturers lock buyers into single-vendor ecosystems that limit competitive sourcing flexibility.
Strategic Opportunities
- India Warehouse Formalization:Organized retail and cold chain expansion in Indian metropolitan corridors creates first-mover positioning for electric tugger suppliers as the country's logistics infrastructure modernizes.
- Vision-Guided Navigation Convergence:Integration of camera-based autonomous navigation with existing warehouse management systems eliminates infrastructure retrofit costs that previously stalled automation adoption.
- California Warehouse Decarbonization Mandates:State-level regulations requiring zero-emission equipment in new and expanded distribution facilities create guaranteed demand pull through the mid-2030s.
Industry Challenges
- Industrial Electrician Scarcity:Facility maintenance departments lack personnel certified for high-voltage battery system diagnostics and repair, extending equipment downtime during fault conditions.
- AGV-Tugger Integration Complexity:Retrofitting automated navigation onto existing manual tugger fleets requires mechanical and software engineering coordination that strains integrator capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Tugger Market |
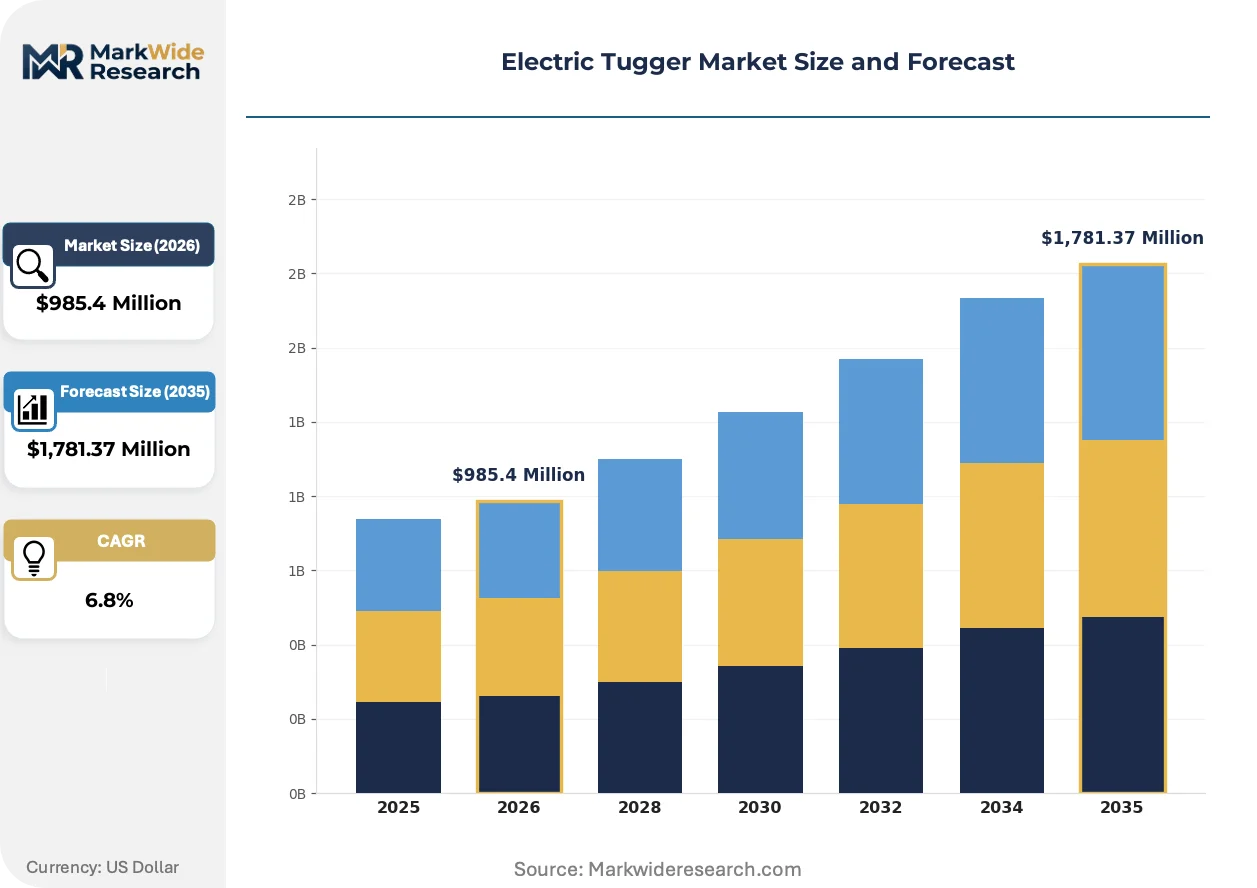
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tugger, Heavy-Duty Tugger, Integrated Tugger, Automated Tugger Technology: Electric Drive, Hydraulic, Pneumatic, Hybrid End User: Manufacturing, Logistics, Retail, Warehousing Application: Material Handling, Assembly Line, Order Picking, Transport Systems |
| Companies Covered | Crown Equipment Corporation, Daifuku, Linde Material Handling, Seegrid, Motrec International, Komatsu Ltd., Hyster-Yale, MasterMover Inc., Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Tugger Market Trends and Innovations
Electrification is compressing the traditional powertrain supply chain while autonomous navigation systems eliminate fixed infrastructure dependencies. Equipment manufacturers are repositioning around software and energy services rather than mechanical hardware differentiation.
Digital twin simulation is virtualizing electric tugger deployment planning, allowing logistics engineers to model fleet sizing and charging schedules against actual operational data before capital commitment. Regional grocery distribution networks are adopting these tools to validate automation business cases. The technology is compressing pilot program timelines from months to weeks while reducing implementation risk for first-time automation adopters.
The EPA's evolving indoor emissions guidelines are tightening permissible particulate thresholds for material handling equipment operating in enclosed warehousing environments. Equipment lessors are restructuring fleet offerings to emphasize electric alternatives ahead of anticipated compliance phase-outs. Automotive component suppliers with multi-site North American footprints are most exposed, accelerating consolidated procurement of standardized electric tugger platforms.
Leasing structures are displacing outright purchase as the dominant acquisition model for mid-capacity warehousing operations. Third-party fleet management providers are capturing maintenance and energy optimization functions that equipment OEMs previously controlled. This shift is most visible in United States e-commerce fulfillment networks where capital efficiency metrics dominate procurement committee evaluations.
Electric Tugger Market Segmentation
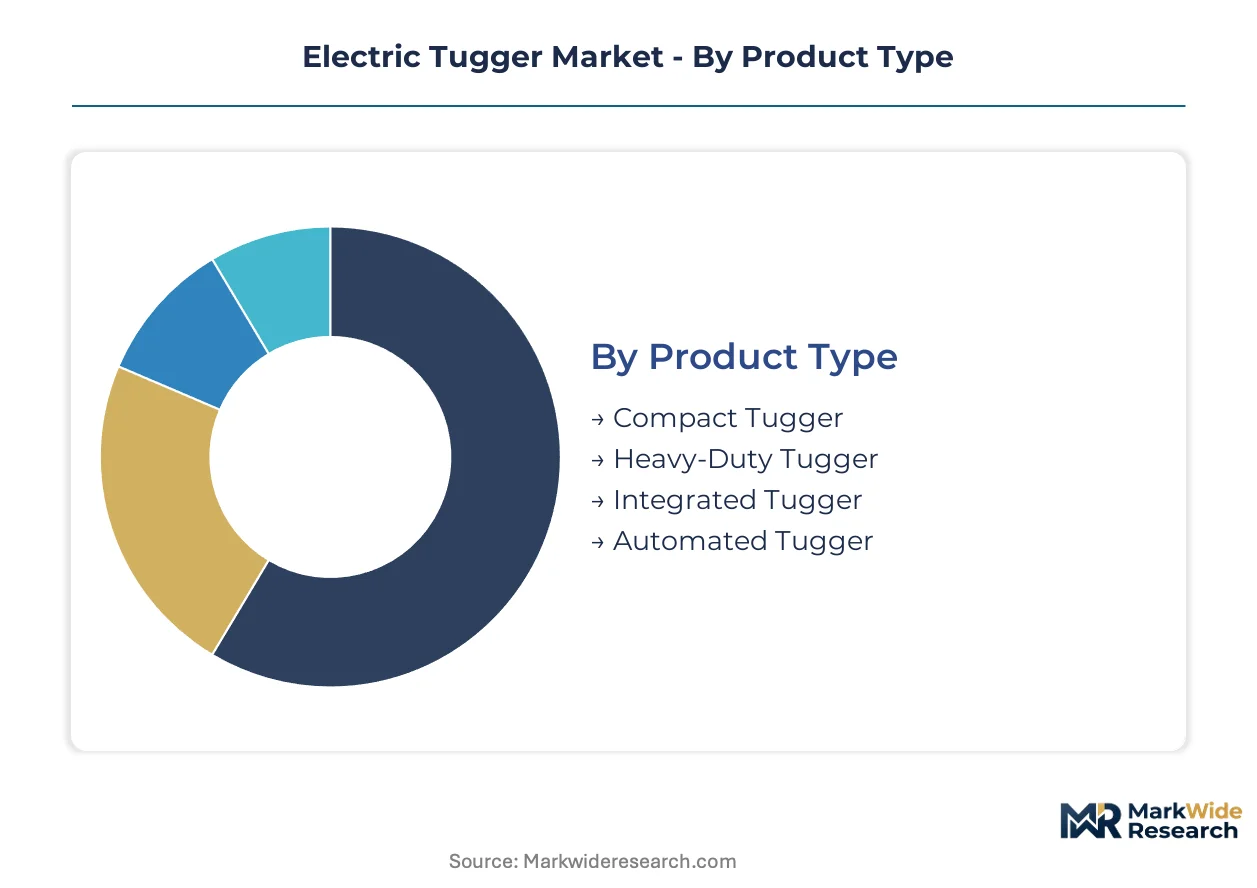
Electric tugger procurement patterns diverge sharply across facility scale, automation readiness, and load requirements. Segmentation reveals how lithium-ion powertrains and vision-guided navigation are reshaping category boundaries that once separated manual from automated equipment.
Product Type:
Cost tier differentiation separates entry-level units from capital-intensive automated platforms, with battery chemistry acting as the pivot point for total cost of ownership calculations.
- Compact Tugger:Drawbar pull ratings from 1,000 to 5,000 pounds suit narrow-aisle retail backrooms and light manufacturing cells. Grocery distribution networks in the United States deploy these units for store delivery consolidation, with OSHA indoor air quality mandates accelerating propane-to-electric conversions.
- Heavy-Duty Tugger:Multi-ton load capacity serves automotive assembly lines where just-in-time component delivery demands reliability. Reshoring electric vehicle production to Michigan and Tennessee facilities is expanding specification volumes for 30,000+ pound drawbar models.
- Integrated Tugger:Pre-wired fleet management compatibility reduces deployment friction for multi-site operators. Third-party logistics providers favor these configurations for standardized maintenance protocols across tenant facilities.
- Automated Tugger:Vision-guided navigation eliminates magnetic tape or reflector infrastructure. E-commerce fulfillment centers in California are adopting these units to satisfy warehouse decarbonization mandates while reducing labor exposure to repetitive transport loops.
Heavy-duty tuggers hold installed capacity. Automated tuggers are rotating up the share rankings.
Technology:
Application environment dictates powertrain selection, with electrification penetrating indoor operations while hybrid systems retain relevance for mixed indoor-outdoor duty cycles.
- Electric Drive:Lithium-ion battery packs deliver energy density above 200 Wh/kg, collapsing charging downtime versus lead-acid predecessors. Logistics operators in the United States are recalibrating fleet replacement timelines around these electrochemical gains.
- Hydraulic:Piston-based force multiplication persists in legacy manufacturing installations where retrofit capital is constrained. Automotive stamping plants retain these systems for die-handling applications exceeding electric motor torque curves.
- Pneumatic:Compressed air powertrains operate in explosive atmosphere zones where electrical spark risk is prohibitive. Chemical processing facilities specify these units for solvent-handling areas under EPA emissions guidelines.
- Hybrid:Dual-mode systems bridge indoor electric operation with outdoor diesel range extension. Airport ground support equipment fleets utilize these configurations for tarmac-to-terminal cargo movements.
Electric drive systems command the technology mix. Hybrid configurations are climbing the fastest as transitional infrastructure.
End User:
Customer type determines specification complexity, with integrated automation requirements concentrating among multi-site manufacturing operators.
- Manufacturing:Assembly line synchronization demands precise speed control and programmable acceleration curves. Electric vehicle battery plants specify automated tuggers for cell module transport between production stations.
- Logistics:Third-party providers face tenant sustainability scorecards mandating zero-emission equipment. Cold chain expansion in Indian metropolitan corridors is opening first-mover positioning for electric tugger suppliers.
- Retail:Backroom space constraints favor compact dimensions with tight turning radii. Regional grocery chains are piloting vision-guided units to validate automation business cases before capital commitment.
- Warehousing:High-velocity fulfillment operations prioritize uptime metrics over upfront capital outlay. Leasing structures are displacing outright purchase as the dominant acquisition model for mid-capacity operators.
Manufacturing holds installed capacity. Warehousing is rotating up the share rankings.
Application:
Volume throughput separates intermittent material movement from continuous transport systems, with automation ROI hinging on loop frequency and labor substitution potential.
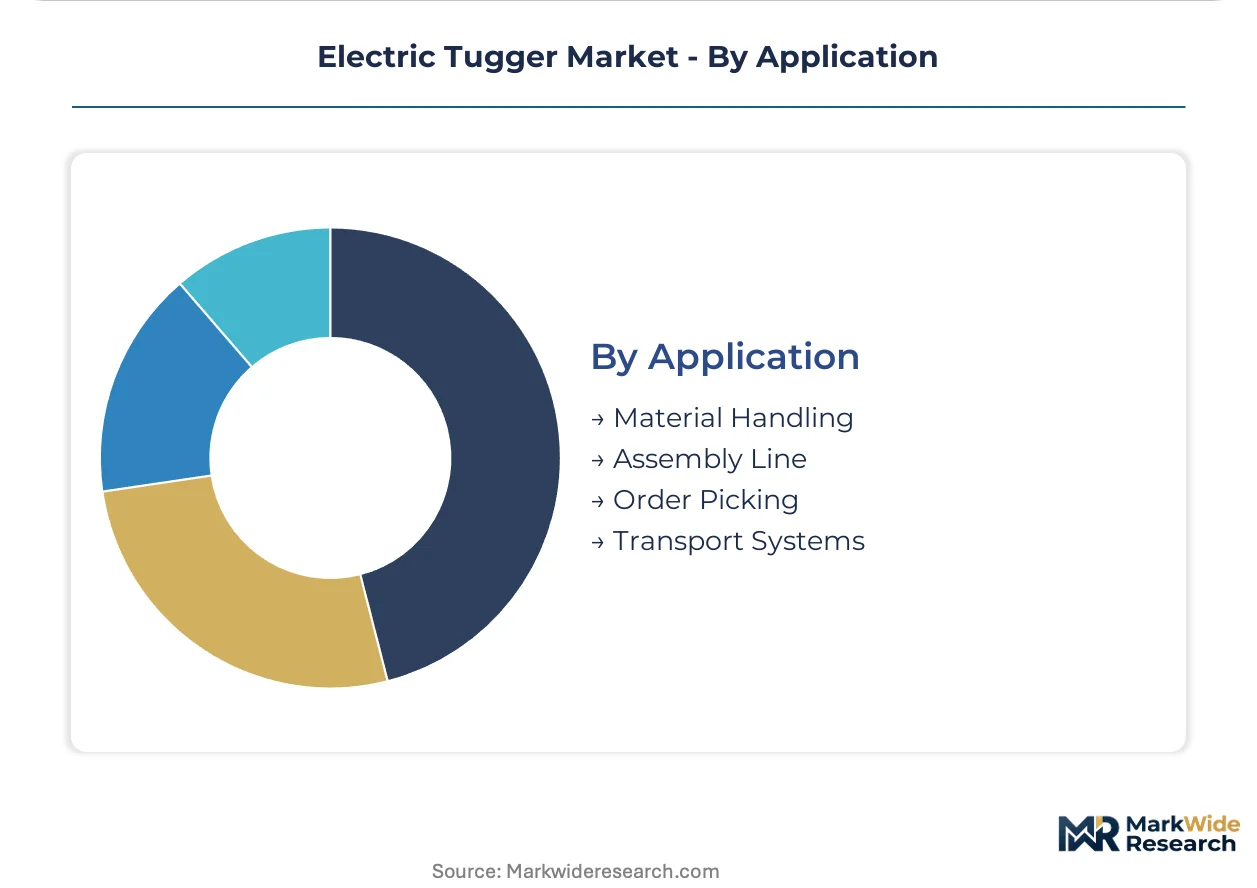
- Material Handling:Horizontal load movement within confined facility environments where forklift maneuverability proves impractical. Compact tuggers dominate this application in retail and light manufacturing settings.
- Assembly Line:Synchronized component delivery to workstation sequences requires programmable routing. Automotive reshoring is expanding specification volumes for automated guided tuggers in just-in-time configurations.
- Order Picking:Cart-based fulfillment support in e-commerce operations demands ergonomic operator interfaces. Vision-guided navigation is eliminating infrastructure retrofit costs that previously stalled adoption.
- Transport Systems:Inter-facility load movement across expansive distribution campuses. Heavy-duty tuggers with extended-range battery configurations serve these routes in California warehouse decarbonization compliance scenarios.
Material handling holds installed capacity. Transport systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export automated tugger systems to United States distribution networks, while Japanese suppliers serve Southeast Asian automotive assembly corridors. Trade flows concentrate battery technology from East Asian cell producers toward North American and European integration facilities.
United States
E-commerce fulfillment networks in California and Texas drive specification volumes for vision-guided automated tuggers. OSHA powered industrial truck standards mandate operator training protocols that shape fleet replacement cycles across multi-site logistics operators. The Inland Empire warehouse cluster east of Los Angeles is deploying heavy-duty electric tuggers to satisfy state-level warehouse decarbonization mandates.
Germany
Automotive OEM reshoring and battery plant construction in Bavaria and Lower Saxony expand demand for synchronized assembly line delivery systems. The EU Machinery Directive and CE marking requirements constrain market access for non-compliant manufacturers, favoring established European suppliers. Stuttgart's automotive supplier ecosystem is specifying automated guided tuggers for just-in-time component transport between production stations.
China
Domestic logistics modernization and cold chain expansion in Yangtze River Delta metropolitan corridors create procurement volumes for compact electric tuggers. MIIT industrial equipment standards and GB certification protocols govern radio-frequency controls and battery safety in warehouse deployments. Shanghai's Pudong airport cargo zone is adopting hybrid tugger configurations for inter-facility load movement across expansive distribution campuses.
India
Organized retail formalization and third-party logistics growth in Maharashtra and Karnataka generate first-mover positioning for electric material handling equipment. BIS certification requirements and state-level warehouse infrastructure incentives shape equipment procurement decisions for cold chain operators. Mumbai's Nhava Sheva port logistics corridor is piloting lithium-ion powered tuggers to replace diesel alternatives in container handling operations.
Japan
Precision manufacturing automation and semiconductor facility expansion in Kanto and Chubu regions sustain demand for programmable transport systems. METI energy efficiency guidelines and JIS industrial equipment standards influence fleet electrification timelines for electronics manufacturers. Nagoya's automotive component supplier cluster is integrating automated tuggers with existing warehouse management systems to reduce labor exposure in repetitive transport loops.
Electric Tugger Market Competitive Landscape
On the supply side, the industry is consolidating around integrated powertrain and automation technology stacks. Equipment manufacturers compete through battery chemistry control and navigation software differentiation rather than mechanical hardware alone. Three archetypes dominate: diversified industrial truck conglomerates with captive battery supply, specialized autonomous navigation developers, and regional fabrication specialists serving price-sensitive procurement segments. Dominant competitive moves include backward integration into lithium-ion cell sourcing and strategic partnerships with warehouse management software providers.
Among diversified industrial truck manufacturers, Crown Equipment Corporation, Daifuku, and Seegrid occupy distinct positioning vectors. Crown Equipment Corporation exemplifies the vertically integrated archetype through captive battery system production. Daifuku represents the automation-forward tier with sustained positioning in automated guided vehicle interoperability. Seegrid anchors the vision-guided navigation specialization, eliminating infrastructure retrofit requirements for warehouse deployment. These three entities collectively illustrate how competitive advantage is migrating from mechanical engineering toward electrochemical and software-defined differentiation.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Daifuku |
| Linde Material Handling |
| Seegrid |
| Motrec International |
| Komatsu Ltd. |
| Hyster-Yale |
| MasterMover Inc. |
| Jungheinrich AG |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's lithium-ion battery logistics costs cascade through electric tugger pricing architecture, concentrating margin pressure on manufacturers without captive cell sourcing while amplifying price differentiation between energy-dense and legacy lead-acid configurations.
Pricing Analysis
Lead-acid-to-lithium-ion generational pricing gaps stratify the electric tugger market into three performance tiers. Contract-based long-term fleet agreements dominate mid-capacity warehousing procurement, with price differentiation anchored in battery chemistry grade and OSHA certification tier. Cost compression in economy-class lead-acid configurations is intensifying because South American brine extraction constraints feed lithium carbonate volatility. Third-party logistics providers show highest price sensitivity due to tenant sustainability scorecard pressures, while automotive OEMs prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Tariff exposure between China and the United States dominates electric tugger supply chain risk calculations. Battery cell production concentrates in China, South Korea, and Japan, with final assembly drawing from Mexican and German fabrication hubs. Raw material dependencies rest on lithium carbonate from Chilean brine operations, nickel from Indonesian laterite mines, and copper from Peruvian extraction. Single-source vulnerability in vision-guided navigation sensor modules threatens automated tugger lead times. Distribution runs through OEM-direct channels for large fleet operators and specialized industrial equipment distributors for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric tugger markets are restructuring around service-attach revenue, with battery health monitoring and predictive maintenance subscriptions expanding faster than hardware unit sales as fleet operators prioritize uptime over ownership.
For Market Incumbents: Harden defensive positioning through backward integration into lithium-ion cell sourcing and captive production of battery management systems. Emerging autonomous navigation developers threaten equipment commoditization by decoupling software from hardware. Certification investment in FCC equipment authorization and EU Machinery Directive compliance creates switching costs that lock multi-site operators into established supplier ecosystems.
For New Entrants and Emerging Players: Indian organized retail corridors offer first-mover positioning as cold chain infrastructure formalizes and BIS certification requirements mature. Vision-guided navigation retrofit kits for existing manual tugger fleets represent the most penetrable entry vector, bypassing proprietary fleet management protocol lock-in. Channel partnership with third-party logistics providers operating multi-tenant distribution centers accelerates reference customer acquisition without direct OEM sales force investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized material handling divisions lacking automation software capabilities. Long-term viability favors suppliers with energy service revenue streams and warehouse management system integration depth. The signal to watch is California warehouse decarbonization mandate compliance acceleration, which would compress replacement timelines and consolidate procurement around standardized electric platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium-ion sourcing insulates margins from South American brine extraction constraints. |
| Vision-Guided Navigation Acquisition | Camera-based autonomy eliminates magnetic tape infrastructure retrofit costs for warehouse deployment. |
| Aftermarket Service Platform Launch | Predictive maintenance subscriptions capture recurring revenue from fleet uptime guarantees. |
| Geographic Manufacturing Footprint | Mexican assembly proximity reduces tariff exposure for United States distribution network supply. |
| Warehouse Management System Partnership | Direct WMS integration accelerates automated tugger deployment in e-commerce fulfillment centers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warehouse operations directors, fleet maintenance managers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from OSHA enforcement databases, EPA indoor emissions guidelines, FCC equipment authorization filings, and customs trade records. Bottom-up unit deployment estimates triangulated against top-down logistics sector capital expenditure patterns.
Calibration against historical lithium-ion battery cost curves and warehouse automation adoption rates anchored projections across the analysis window. Segmentation dimensions modeled include tugger product class, battery chemistry tier, navigation technology, end-use industry vertical, and facility automation readiness. CAGRs derived from logistic function fitting to S-curve penetration patterns, with electric vehicle manufacturing reshoring and e-commerce fulfillment density as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese battery producers or accelerated California regulatory phase-outs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Tube Rotator Market